
 Logic Semiconductor Market | 2026-2036
Logic Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Logic Semiconductor Market Analysis
The foundry-to-IDM capability gap is rotating competitive capital allocation toward extreme ultraviolet lithography and advanced packaging. TSMC sustains process leadership through aggressive node migration and captive customer co-development programs. Intel Corporation navigates a multi-year manufacturing turnaround while competing for external foundry contracts. Samsung Electronics anchors memory-centric synergies while extending logic ambitions through gate-all-around transistor introduction.
Logic semiconductors are integrated circuits that execute binary computational operations through transistor arrays fabricated at nanometer-scale geometries, typically employing CMOS technology with FinFET or gate-all-around architectures for power efficiency. These devices form the processing core of electronic systems, converting electrical signals into arithmetic, logical, and control functions across computing platforms. Microprocessors dominate value capture in data processing applications, while application-specific integrated circuits concentrate margin pools in automotive and telecommunications end uses where customization commands premium positioning. Field programmable gate arrays represent the fastest-growing product category as hardware reconfigurability gains traction in AI inference and adaptive robotics deployments.
FDA oversight of medical devices incorporating logic semiconductors shapes reliability standards for healthcare-adjacent chip demand, while FCC equipment authorization requirements influence electromagnetic compatibility design rules for telecommunications applications. The EPA's emerging focus on perfluorinated compound emissions from semiconductor fabrication is pressuring wet chemistry process redesign and abatement capital expenditure. Stakeholders must monitor how the EU AI Act's risk classification tiers will cascade into logic semiconductor performance verification and traceability mandates for embedded AI accelerators.
Market Dynamics
The EU Chips Act is concentrating advanced-node fabrication investment decisions toward European subsidy zones while TSMC's Taiwan ecosystem captures data center AI training procurement.
Growth Catalysts
- EU Chips Act capital subsidies:The framework is redirecting foundry location decisions toward Dresden, Leuven, and Grenoble clusters. Equipment qualification timelines are compressing for beneficiaries.
- Gate-all-around transistor architecture:Samsung Electronics and Intel Corporation are migrating 3nm-class production to this geometry. Power efficiency gains are unlocking mobile and automotive design wins.
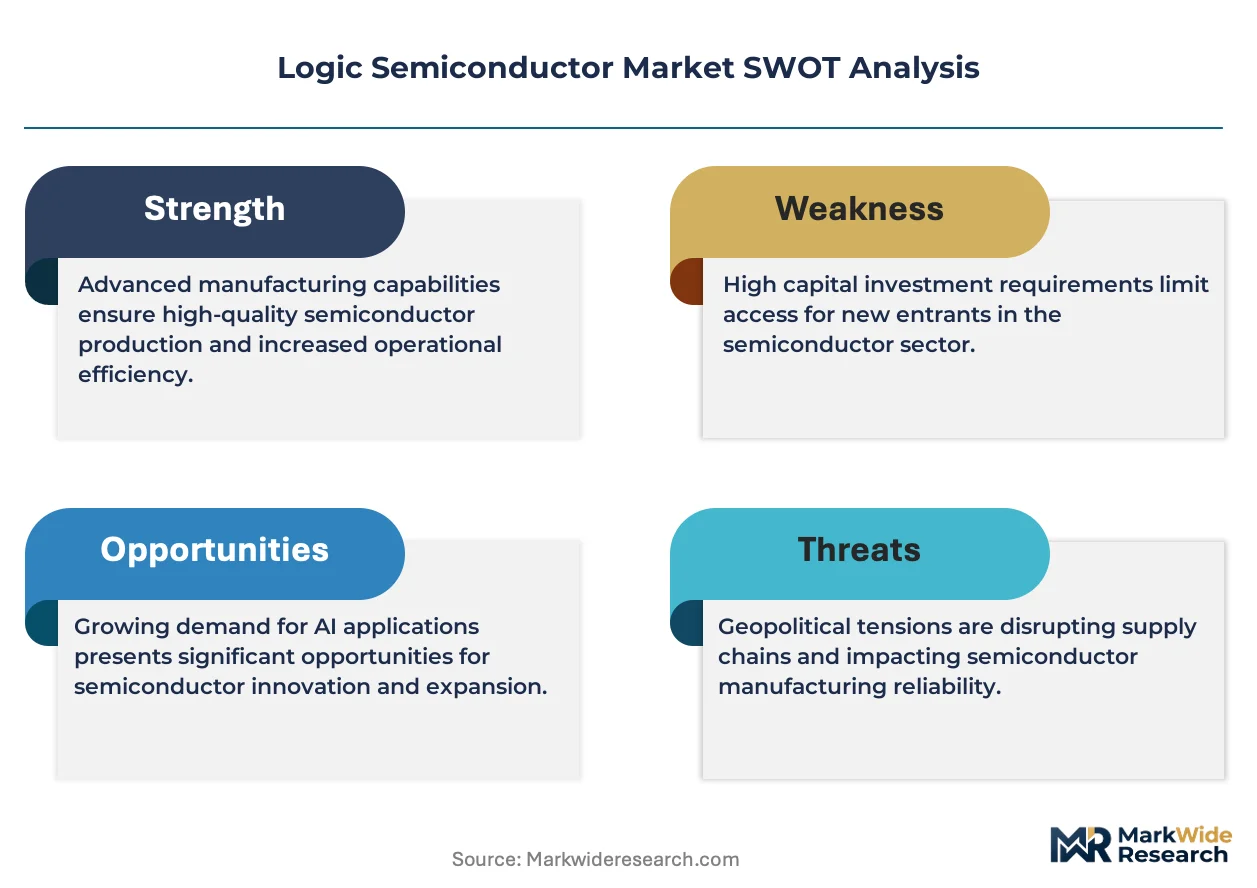
- Data center AI training workloads:Hyperscaler procurement of high-performance logic chips is concentrating in Taiwan's advanced-node ecosystem. Co-development programs between foundries and cloud operators are accelerating tape-out schedules.
Market Restraints
- Extreme ultraviolet lithography equipment scarcity:ASML Holding NV's annual system output caps foundry expansion velocity. Deposition and etch tool lead times now extend past eighteen months.
- Perfluorinated compound emissions constraints:The EPA's emerging abatement mandates are forcing wet chemistry process redesign. Capital expenditure for scrubber retrofits is diverting funds from node migration.
- Advanced packaging substrate shortage:Ajinomoto Build-up Film and glass core substrate capacity is bottlenecking chiplet integration. Outsourced assembly and test providers are throttling high-bandwidth memory logic stack output.
Strategic Opportunities
- Automotive functional safety certification:ISO 26262 ASIL-D compliance is creating premium positioning for fault-tolerant microcontrollers. German and Japanese tier-one suppliers are qualifying domestic foundry alternatives.
- India's semiconductor PLI scheme:The production-linked incentive framework is attracting assembly and test investment. Gujarat and Tamil Nadu are emerging as packaging hubs for logic devices.
- FPGA-ASIC convergence:Adaptive compute platforms are bridging reconfigurability and power efficiency. Robotics and edge AI deployments are absorbing these hybrid architectures.
Industry Challenges
- Process engineer talent scarcity:Atomic layer deposition and EUV resist chemistry expertise is concentrating at TSMC and Samsung. Intel's Arizona and Oregon fabs are competing for the same limited pool.
- IP licensing complexity:ARM architecture negotiations and RISC-V ecosystem fragmentation are extending system-on-chip design cycles. Fabless customers are facing royalty stacking in AI accelerator blocks.
- Legacy node equipment obsolescence:200mm wafer tool refurbishment is lagging automotive microcontroller demand. Secondhand market prices for mature lithography systems are escalating.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logic Semiconductor Market |
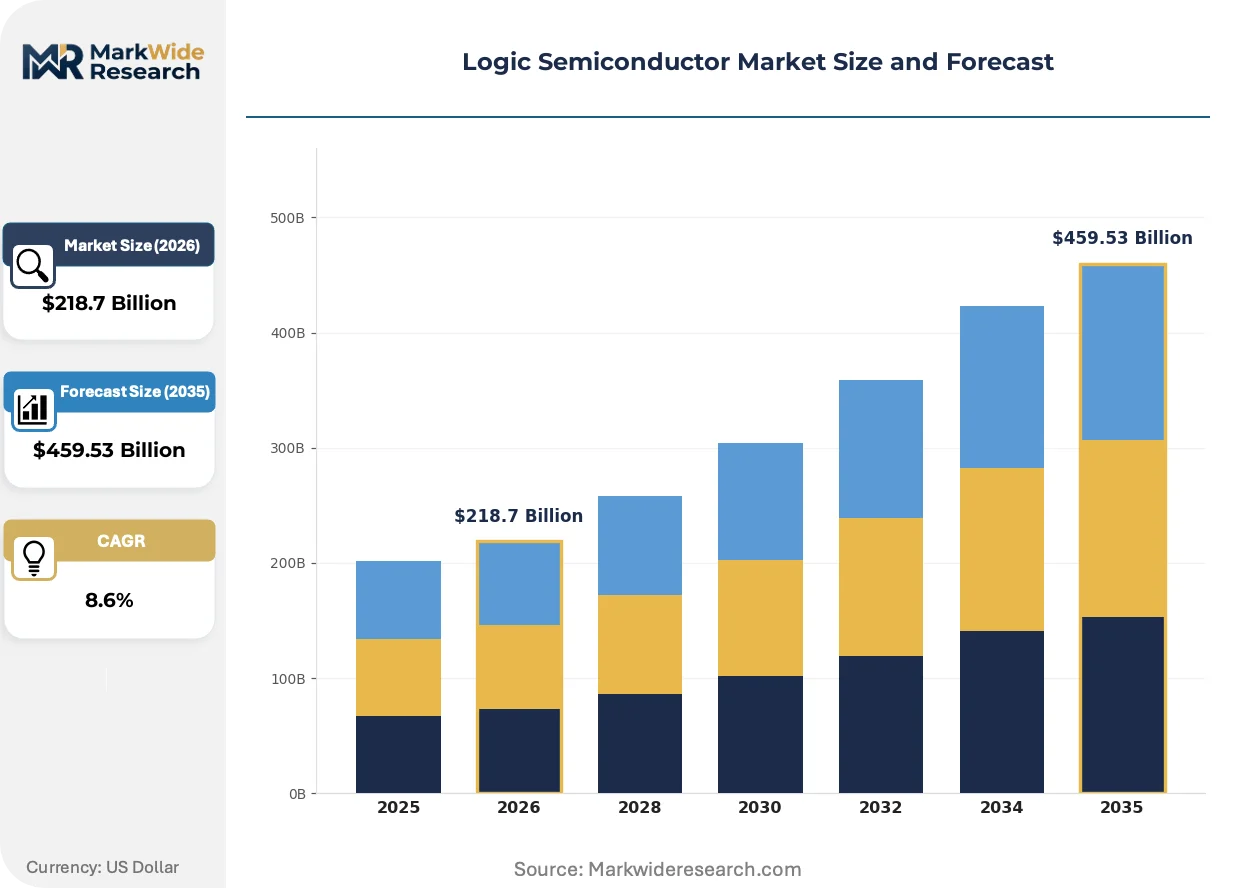
| Market Size in 2026 | $218.7 Billion |
| Market Size in 2035 | $459.53 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, Digital Signal Processors, Field Programmable Gate Arrays, Application-Specific Integrated Circuits Technology: CMOS, GaN, SiGe, BiCMOS End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Application: Data Processing, Communication, Control Systems, Robotics |
| Companies Covered | Intel Corporation, Qualcomm Incorporated, NVIDIA Corporation, ASML Holding, Applied Materials, Taiwan Semiconductor Manufacturing Company (TSMC), Broadcom Inc., Samsung Electronics, Advanced Micro Devices (AMD), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logic Semiconductor Market Emerging Trajectories
Chiplet-based disaggregation is fragmenting monolithic die economics while EUV lithography and advanced packaging are converging into unified process flows.
Gate-all-around transistor structures are displacing FinFET geometries at the 3nm node and below. Data center GPU and AI accelerator designers are adopting these architectures for power-performance density gains. The transition is compressing design rule learning curves and concentrating R&D expenditure among foundries with live production.
The EU AI Act's risk classification tiers are mandating traceability and performance verification for embedded AI accelerators. Medical device and automotive system suppliers must document logic semiconductor provenance through supply chain tiers. High-risk application categories are driving demand for certified manufacturing flows in European Economic Area jurisdictions.
Hyperscalers are consolidating logic semiconductor procurement through direct foundry partnerships rather than merchant distributor channels. Cloud operators in the United States and Taiwan are negotiating multi-year wafer supply agreements with volume commitments. This disintermediation is compressing component distributor margins and redirecting technical support responsibilities toward foundry customer engineering teams.
Logic Semiconductor Market Segmentation
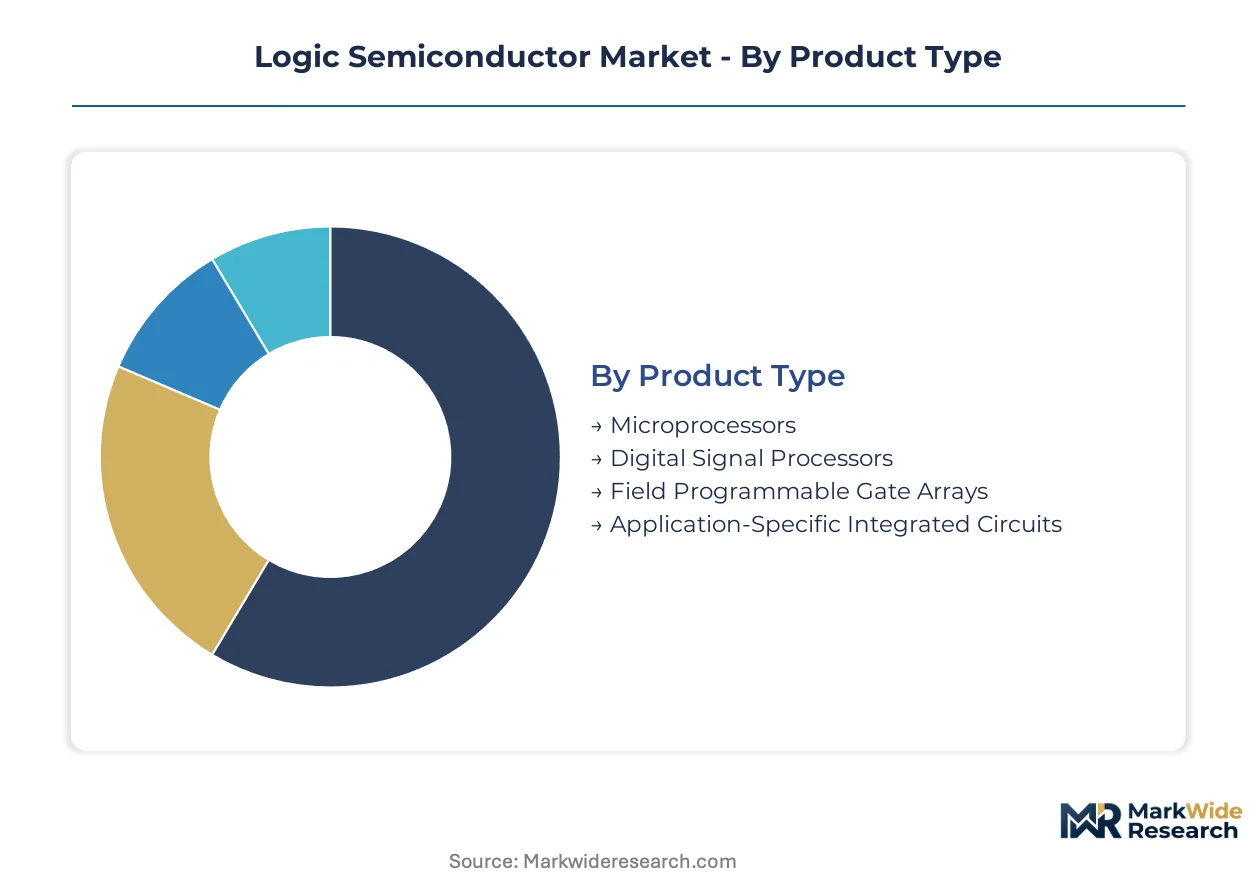
Logic semiconductor procurement channels diverge sharply by segment complexity. Microprocessors and ASICs flow through direct foundry partnerships, while FPGAs and DSPs retain distributor networks for mid-volume customers.
Product Type:
Channel mix separates high-volume custom silicon from configurable standard products. Direct wafer supply agreements dominate the largest categories.
- Microprocessors:Central processing units fabricated at advanced nodes execute general-purpose instruction sets through superscalar architectures. Hyperscaler data centers in the United States and Taiwan are consolidating procurement through TSMC direct partnerships, bypassing traditional component distribution. By volume, microprocessors lead. By growth pace, field programmable gate arrays are ahead.
- Application-Specific Integrated Circuits:Custom-fabricated logic devices optimize die area and power for single-application workloads. Automotive suppliers in Germany and Japan are qualifying domestic foundry alternatives for ASIC supply security under ISO 26262 ASIL-D mandates.
- Field Programmable Gate Arrays:Reconfigurable logic arrays enable post-manufacturing function modification through hardware description language programming. Robotics and edge AI deployments are absorbing adaptive compute platforms.
- Digital Signal Processors:Specialized arithmetic units optimized for multiply-accumulate operations handle real-time audio, video, and sensor data streams. Telecommunications infrastructure OEMs remain the primary demand source.
ASICs command premium positioning through customization. FPGAs are expanding most quickly on hardware reconfigurability demand.
Technology:
Cost tier stratification separates mature-node commodity production from leading-edge premium positioning. Depreciation schedules and yield learning curves determine competitive economics.
- CMOS:Complementary metal-oxide-semiconductor technology pairs n-type and p-type transistors for static power minimization. Foundries in Taiwan and South Korea are migrating CMOS production to gate-all-around architectures at 3nm-class nodes.
- GaN:Gallium nitride wide-bandgap semiconductors enable higher switching frequencies and breakdown voltages than silicon equivalents. Power supply and RF amplifier applications in telecommunications infrastructure are concentrating demand.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with low-power CMOS logic on unified die. Automotive radar and precision analog-to-digital converters represent primary end uses.
- SiGe:Silicon-germanium heterojunction bipolar transistors extend RF performance into millimeter-wave frequencies without compound semiconductor costs. 5G base station transceivers and satellite communication terminals are absorbing output.
CMOS dominates wafer starts by volume. GaN is climbing the fastest on power electronics substitution.
End User:
Application maturity determines margin structure and contract duration. Long-automotive qualification cycles contrast with consumer electronics velocity.
- Automotive:Functional safety requirements under ISO 26262 ASIL-D mandate fault-tolerant microcontroller architectures. German and Japanese tier-one suppliers are diversifying foundry sourcing beyond Taiwan.
- Consumer Electronics:Smartphone and personal computing OEMs drive annual volume peaks tied to product launch cycles. Mobile system-on-chip designs are concentrating at Samsung and TSMC.
- Telecommunications:Base station and optical transport equipment demand high-reliability logic devices with extended temperature specifications. FCC equipment authorization requirements shape electromagnetic compatibility design rules.
- Industrial Automation:Programmable logic controllers and motor drives require deterministic real-time processing with extended operational lifespans. Factory automation OEMs in Germany and Japan are qualifying domestic foundry alternatives.
Consumer electronics leads by volume. Automotive is gaining share fastest on electrification and autonomy.
Application:
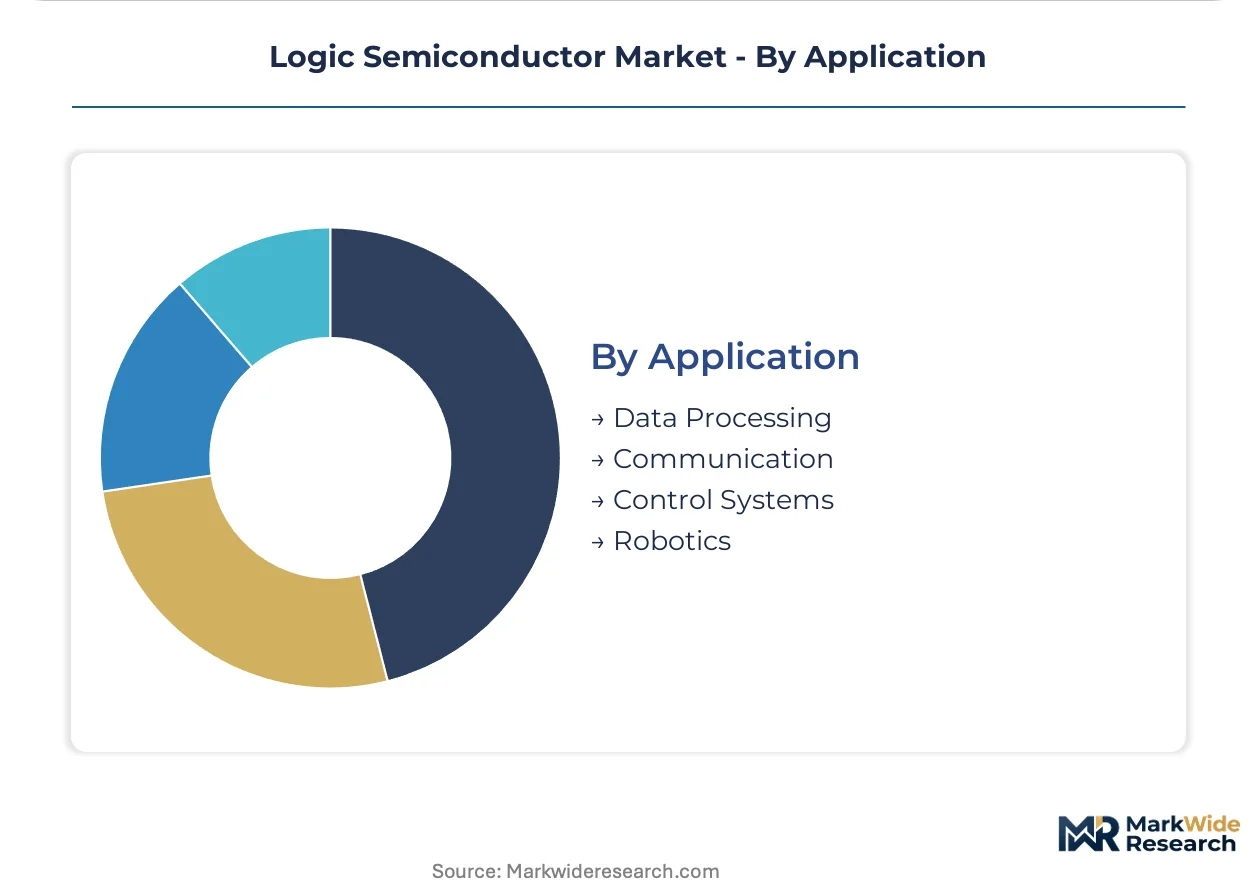
Supply concentration varies by computational intensity. Data processing workloads cluster at advanced-node foundries while control systems distribute across mature nodes.
- Data Processing:Arithmetic and logical operations on structured and unstructured information streams. AI training workloads are concentrating procurement in Taiwan's advanced-node ecosystem.
- Communication:Protocol processing and signal modulation for wired and wireless transmission systems. 5G and optical transport infrastructure are driving DSP and FPGA absorption.
- Control Systems:Real-time feedback loops for industrial process and motion control. Automotive and factory automation are concentrating demand for deterministic microcontrollers.
- Robotics:Sensor fusion and motion planning for autonomous manipulation and navigation. Edge AI inference is driving FPGA-ASIC hybrid architecture adoption.
Data processing leads by volume. Robotics is expanding most quickly on adaptive compute platform deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logic semiconductor trade flows reveal stark asymmetries. Taiwan and South Korea generate substantial export surpluses in advanced-node devices, while the United States and European Union remain net importers despite significant design capabilities. China is accelerating domestic substitution investments to narrow its import dependency.
United States
Hyperscaler data centers in Virginia and Oregon are consolidating procurement through direct foundry partnerships. The CHIPS and Science Act is channeling subsidy eligibility toward Arizona and Texas fab clusters. Intel's manufacturing turnaround is concentrating process engineering recruitment in the Phoenix and Hillsboro metro areas.
Taiwan
TSMC's Hsinchu Science Park ecosystem captures the majority of global AI training chip production. The National Science and Technology Council is coordinating talent retention programs to counter engineer poaching from mainland China. Tainan's Southern Taiwan Science Park is expanding advanced packaging capacity for high-bandwidth memory integration.
South Korea
Samsung Electronics is leveraging memory-to-logic synergies in Pyeongtaek and Hwaseong complexes. The Ministry of Trade, Industry and Energy is extending tax credits for semiconductor equipment investment through 2030. Yongin's emerging cluster is specializing in gate-all-around transistor ramp-up for mobile applications.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg are qualifying domestic foundry alternatives for ISO 26262 ASIL-D microcontroller supply. The European Chips Act is concentrating subsidy allocation toward Dresden's Silicon Saxony cluster. Infineon's Villach and Dresden fabs are expanding 300mm capacity for power semiconductor integration.
China
SMIC and Hua Hong Semiconductor are advancing mature-node production in Shanghai and Wuxi despite equipment access constraints. MIIT's domestic substitution mandates are accelerating RISC-V ecosystem development for server and telecommunications applications. Beijing's Zhongguancun software corridor is concentrating AI chip design houses seeking local tape-out options.
Logic Semiconductor Market Vendor Landscape
Concentration sits with vertically integrated IDMs and pure-play foundries that control extreme ultraviolet lithography access. The vendor base stratifies into three tiers: node leaders with live 3nm production, specialty houses serving automotive and industrial qualification cycles, and fabless designers dependent on external fabrication. Strategic moves center on captive customer co-development programs and advanced packaging substrate integration.
Among Taiwan-based fabricators, Taiwan Semiconductor Manufacturing Company exemplifies the pure-play foundry archetype through its concentrated advanced-node ecosystem. Intel Corporation occupies a transitional position as it pursues external foundry contracts while rebuilding internal manufacturing capabilities. Samsung Electronics represents the diversified conglomerate model, anchoring logic ambitions within broader semiconductor and electronics portfolios.
| Leading Market Players |
|---|
| Intel Corporation |
| Qualcomm Incorporated |
| NVIDIA Corporation |
| ASML Holding |
| Applied Materials |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Broadcom Inc. |
| Samsung Electronics |
| Advanced Micro Devices (AMD) |
| Others |
Supply Flow & Price Mechanics
TSMC's 3nm capacity utilization above ninety percent creates asymmetric pricing power across advanced-node tiers. Scale concentration in Taiwan's Hsinchu Science Park ecosystem simultaneously elevates price floors for leading-edge logic devices and compresses margins for trailing-node commodity production.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term wafer supply agreements that dominate high-volume procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive microcontrollers from consumer-grade application processors and mature-node industrial controllers. Cost compression in mature-node segments is intensifying because secondhand 200mm lithography equipment scarcity extends depreciation schedules. Automotive tier-one suppliers exhibit lowest price sensitivity due to ISO 26262 certification requirements, while consumer electronics OEMs drive hardest volume discount negotiations.
Supply Chain Analysis
Strait of Malacca transit underwrites photoresist and specialty gas shipments to Southeast Asian packaging hubs. Taiwan, South Korea, and the United States concentrate advanced-node fabrication capacity while drawing from Japanese photoresist, Dutch EUV systems, and German specialty gas inputs. Single-source vulnerability in Ajinomoto Build-up Film substrate supply threatens chiplet integration throughput. Distribution runs through direct foundry partnerships for hyperscalers and authorized distributor networks for mid-volume FPGA and DSP customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification tiers constitute a regulatory inflection accelerating demand for traceable, certified logic semiconductor supply chains. This disruption compresses qualification timelines for foundries with European Economic Area manufacturing footprints.
For Market Incumbents: Fortify captive customer co-development programs with hyperscaler cloud operators to lock in multi-year wafer supply commitments. Expand advanced packaging substrate integration through backward integration into glass core substrate capacity. Gate-all-around transistor yield leadership at Samsung and Intel represents the primary competitive threat to TSMC's node leadership.
For New Entrants and Emerging Players: ISO 26262 ASIL-D certification fast-track through German TÜV or Japanese JQA accreditation opens automotive microcontroller white space. India's Gujarat and Tamil Nadu packaging hubs offer the most penetrable geography for assembly and test investment. Target robotics edge AI deployments with FPGA-ASIC hybrid architectures as the specific go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fabless designers with multi-year licensing agreements for AI accelerator IP blocks. Long-term viability over the five-to-ten year horizon favors vertically integrated IDMs with captive EUV access and automotive certification portfolios. Foundry utilization rates at TSMC and Samsung serve as the critical signal to watch for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Gate-All-Around Transistor Ramp-Up | Samsung's Yongin complex accelerates 3nm-class production for mobile power efficiency gains. |
| Advanced Packaging Substrate Integration | TSMC's Tainan facility expands high-bandwidth memory logic stack capacity for AI training chips. |
| Automotive Functional Safety Certification | Infineon's Dresden fab secures ASIL-D compliance for fault-tolerant microcontroller supply to German tier-ones. |
| Direct Foundry Partnership Consolidation | Hyperscalers in Virginia and Oregon bypass distributors for TSMC wafer supply agreements. |
| RISC-V Ecosystem Development | Chinese design houses under MIIT mandates pursue domestic server chip tape-out options. |
Methodological Framework
A spread of perspectives from foundry customer engineering leads, fabless semiconductor CTOs, automotive tier-one procurement directors, and equipment supplier account managers converged on the working assumptions. Primary interview intelligence combined with SEC 10-K filings, hyperscaler capex disclosures, EU Chips Act subsidy announcements, and customs trade data. Bottom-up wafer supply estimates and top-down end-use demand aggregation provided cross-validation.
Segmentation dimensions modeled span product type, technology node class, end-use vertical, and application workload intensity across the projection horizon. CAGRs derive from installed base replacement cycles, node migration timelines, and AI training infrastructure deployment trajectories. Specific forecast inputs include ASML EUV system delivery schedules and automotive electrification content-per-vehicle assumptions.
Underlying assumptions cover sustained hyperscaler capital expenditure commitment and EU subsidy disbursement velocity, with deviation risk concentrated in China-Taiwan geopolitical friction and EPA perfluorinated compound abatement mandate timing. Practitioners should keep alternative scenarios live as EU AI Act enforcement discretion and gate-all-around yield learning curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Compound Semiconductor Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Chiplets Market
Semiconductors
Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Analog Semiconductor Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Gaas Wafer Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
China Semiconductor Market