
 Power Inverter Market | 2026-2036
Power Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Power Inverter Market Intelligence
Chinese photovoltaic component manufacturers is broadening inverter production capacity across Southeast Asian assembly nodes to circumvent trade barriers and secure tariff-advantaged access. Huawei Technologies leverages vertically integrated semiconductor sourcing to sustain cost leadership in utility-scale string inverter architectures. SMA Solar Technology AG anchors European market presence through specialized service networks and IEC-certified product portfolios for rooftop segments.
A power inverter is an electronic device that converts direct current electricity into alternating current through pulse-width modulation or resonant switching topologies, operating at efficiencies typically exceeding 95% in modern silicon carbide designs. Its primary commercial purpose lies in enabling grid-compatible power output from solar arrays, battery banks, and electric vehicle drivetrains. Pure sine wave inverter configurations command premium positioning in residential and medical applications where waveform fidelity protects sensitive loads, while grid-tie architectures dominate utility-scale renewable energy deployments through net-interconnection functionality. Solar inverter technology segments are displacing standalone units as distributed generation penetration deepens across commercial and industrial end-user categories.
Grid codes issued by FERC in the United States and the EU Green Deal's renewable energy directives are tightening harmonic distortion and anti-islanding requirements for inverter-connected generation assets. China's GB standards and India's CEA technical regulations mandate specific fault-ride-through capabilities and reactive power support functions that reshape product development priorities for manufacturers targeting these markets. Stakeholders must monitor evolving interconnection standards and semiconductor supply resilience as decisive variables for procurement and capacity planning.
Market Dynamics
Silicon carbide power semiconductors are compressing inverter form factors while elevating switching frequencies beyond traditional silicon limits, forcing incumbent manufacturers to retool fabrication lines or cede efficiency leadership to vertically integrated semiconductor-inverter hybrids.
Growth Catalysts
- India's CEA Technical Standards:Mandatory fault-ride-through and reactive power support functions for grid-connected solar inverters are accelerating replacement cycles in utility-scale photovoltaic installations.
- Residential Battery Pairing:Hybrid inverter architectures enabling DC-coupled storage are capturing homeowner demand in Germany and Australia where time-of-use tariffs reshape electricity economics.
- Silicon Carbide Adoption:Wide-bandgap semiconductor substrates are enabling 99% peak efficiency ratings in string inverter designs, opening premium positioning in commercial rooftop segments.
Market Restraints
- IGBT Supply Concentration:Power module fabrication for entry-level inverters clusters in Chinese and Japanese foundries, exposing procurement to export control volatility and capacity allocation disputes.
- Electrolytic Capacitor Lifespan:Thermal cycling in outdoor installations degrades aluminum electrolytic components before semiconductor failure, elevating warranty reserve requirements for manufacturers.
- String Inverter Substitution:Module-level power electronics with integrated DC-AC conversion are encroaching on traditional string architectures in commercial rooftop applications.
Strategic Opportunities
- Vietnam Utility-Scale Deployment:Feed-in tariff mechanisms and solar auction programs are concentrating gigawatt-scale inverter procurement in Southeast Asian assembly nodes.
- Vehicle-to-Grid Integration:Bidirectional onboard charger-inverter convergence is creating aftermarket retrofit demand for residential energy management systems.
- EU Green Deal Directives:Renewable energy mandates with harmonized grid code requirements are standardizing product certification across 27 member states, reducing fragmentation costs.
Industry Challenges
- Power Electronics Talent Scarcity:Specialized expertise in magnetics design and thermal management for high-frequency converters commands premium compensation, constraining R&D scaling.
- Multi-Standard Certification Burden:Parallel UL 1741-SA, IEC 62109, and GB/T testing protocols extend product launch timelines by 8-14 months for multi-region portfolios.
- Legacy Fleet Integration Complexity:Retrofit inverter replacements must synchronize with existing string configurations and monitoring infrastructure, elevating commissioning costs.
Report Scope
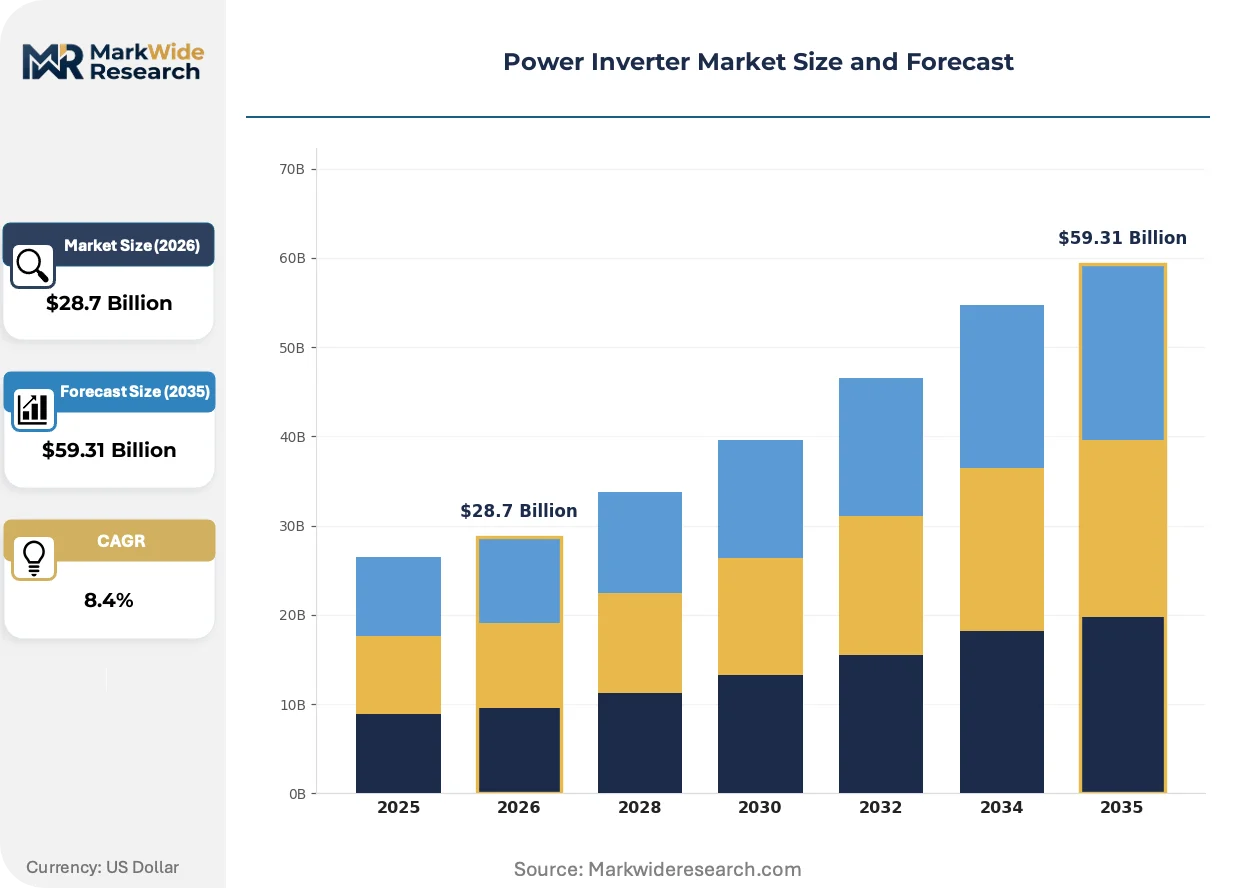
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Inverter Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Modified Sine Wave, Pure Sine Wave, Grid Tie, Off-Grid Technology: Inverter Charger, Standalone Inverter, Solar Inverter, Battery Inverter Application: Renewable Energy, Automotive, Industrial Machinery, Consumer Electronics End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Huawei Technologies Co., Ltd., Sungrow Power Supply Co., Ltd., SMA Solar Technology AG, ABB Ltd., Delta Electronics, Enphase Energy, Fimer Group, Power Electronics S.L., Growatt New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Inverter Market Strategic Shifts & Innovations
Power inverter architecture is bifurcating between silicon carbide-enabled high-frequency designs and integrated module-level electronics, with regulatory pressure on harmonic distortion and anti-islanding capabilities accelerating obsolescence of transformer-based legacy units.
Silicon carbide MOSFETs and Schottky diodes are enabling switching frequencies above 50 kHz in string inverter topologies, shrinking magnetic component volume by 40-60% versus silicon IGBT equivalents. Utility-scale developers in India and China are specifying SiC-based units for 1500V DC bus architectures to reduce copper and aluminum content in balance-of-systems. This frequency expansion is compressing bill-of-materials costs while elevating thermal management requirements for enclosure design.
The EU Green Deal's renewable energy directives are tightening harmonic distortion limits and mandating enhanced anti-islanding protection for distributed generation assets. FERC Order 2023 in the United States is synchronizing interconnection standards across regional transmission organizations, reducing jurisdictional fragmentation for inverter manufacturers. Utility-scale string architectures face the steepest compliance redesign burden as they must integrate ride-through capabilities previously reserved for central inverter platforms.
Buyer procurement for commercial and industrial installations is consolidating around lifecycle cost metrics rather than upfront capital expenditure, elevating importance of warranty terms and predictive maintenance analytics. Engineering-procurement-construction firms are unbundling inverter supply from installation contracts, creating direct manufacturer-to-developer relationships. This specification authority concentration is most pronounced in Germany's commercial rooftop segment, where energy yield guarantees now hinge on inverter performance forecasting.
Power Inverter Market Segmentation
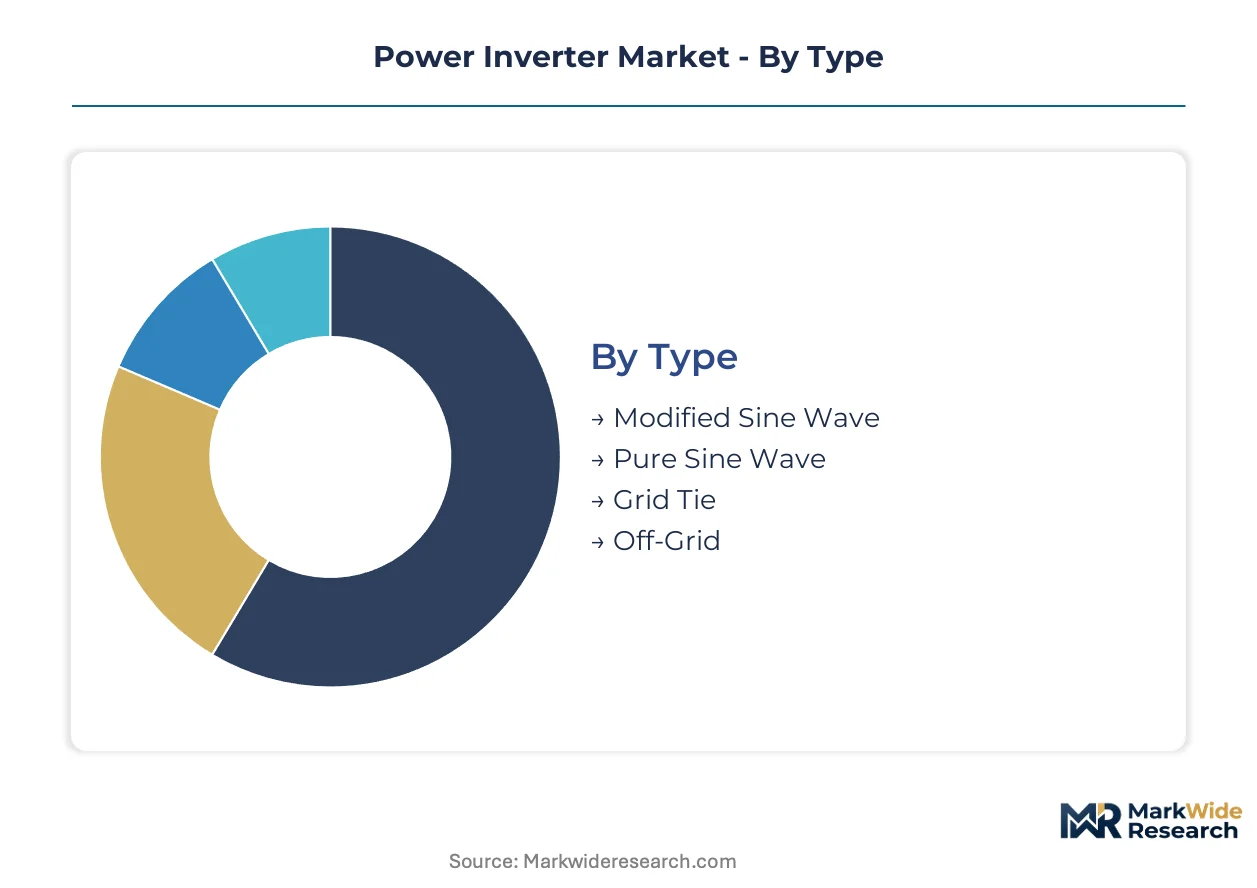
Power inverter segmentation reveals divergent margin structures across waveform fidelity tiers and installation contexts. Technology choices determine semiconductor content and thermal design complexity, while application verticals impose distinct certification burdens and lifecycle requirements.
Type:
Volume deployment clusters in entry-level waveform configurations, while premium positioning attaches to grid-synchronous architectures with harmonic compliance.
- Pure Sine Wave:Delivers waveform fidelity matching grid-quality alternating current through pulse-width modulation with low total harmonic distortion. Medical imaging equipment and residential solar installations in Germany and Australia specify these units where load sensitivity demands clean power. Premium pricing reflects silicon carbide switching components and magnetics precision.
- Grid Tie:Synchronizes output voltage and frequency with utility infrastructure through phase-locked loop control and anti-islanding protection. Utility-scale photovoltaic developers in India and China procure these units under CEA and GB standards mandating fault-ride-through capabilities. Net metering reforms in the United States accelerate residential adoption.
- Modified Sine Wave:Generates stepped approximation of sinusoidal output through simpler switching arrays at lower semiconductor cost. Recreational vehicles and basic power tools in price-sensitive markets absorb volume production from Chinese assembly nodes.
- Off-Grid:Operates as autonomous power conversion without utility reference, incorporating battery charge control and load management logic. Remote telecommunications infrastructure and rural electrification programs in Southeast Asia drive specification.
Mature deployment sits with Modified Sine Wave units in established mobile power applications. Newer deployment is concentrated in Grid Tie architectures as renewable portfolio standards tighten across multiple jurisdictions.
Technology:
Integration depth separates captive power conversion from standalone units, with solar-specific designs commanding dedicated R&D investment.
- Solar Inverter:Optimizes maximum power point tracking algorithms for photovoltaic array voltage-current curves across varying irradiance conditions. String and central configurations dominate utility-scale procurement in India and China where 1500V DC bus architectures reduce conductor mass. Anti-islanding protection and reactive power support functions satisfy evolving grid codes.
- Battery Inverter:Manages bidirectional power flow between electrochemical storage and alternating current loads, enabling peak shaving and backup functionality. Hybrid architectures pairing DC-coupled batteries with solar arrays concentrate demand in German and Australian residential segments under time-of-use tariff structures.
- Standalone Inverter:Provides simple DC-AC conversion without integrated charge control or grid synchronization, serving basic backup power needs. Price competition from integrated alternatives erodes positioning in developed markets.
- Inverter Charger:Combines power conversion with battery charging circuitry in unified enclosures, reducing installation complexity for marine and recreational vehicle applications. Niche positioning limits volume scale.
Standalone Inverter technology represents legacy architecture with stable but contracting share. Battery Inverter integration is expanding most quickly as distributed storage penetration deepens.
Application:
Renewable energy absorption dwarfs other verticals in unit volume, though automotive and industrial segments impose distinct reliability specifications.
- Renewable Energy:Encompasses photovoltaic array integration, wind turbine power conversion, and battery energy storage system coupling. Utility-scale developers in India and China specify silicon carbide-enabled string inverters for 1500V architectures, while residential rooftop installations in Germany and Australia drive hybrid inverter demand. FERC interconnection standards and EU Green Deal directives reshape product requirements.
- Automotive:Converts high-voltage battery direct current to alternating current for traction motors in electric and hybrid drivetrains. Bidirectional onboard charger-inverter convergence creates vehicle-to-grid retrofit opportunities in residential energy management systems. Thermal cycling specifications exceed stationary applications.
- Industrial Machinery:Provides adjustable frequency drive functionality for motor control and uninterruptible power supply backup for critical processes. Manufacturing clusters in Germany specify IEC-certified units with predictive maintenance analytics.
- Consumer Electronics:Supplies portable power conversion for laptops, mobile devices, and small appliances through compact, low-wattage units. Commoditization pressure limits margin capture.
Consumer Electronics application shows saturated penetration with replacement-cycle dynamics. Renewable Energy application is gaining share fastest as national clean energy targets accelerate deployment.
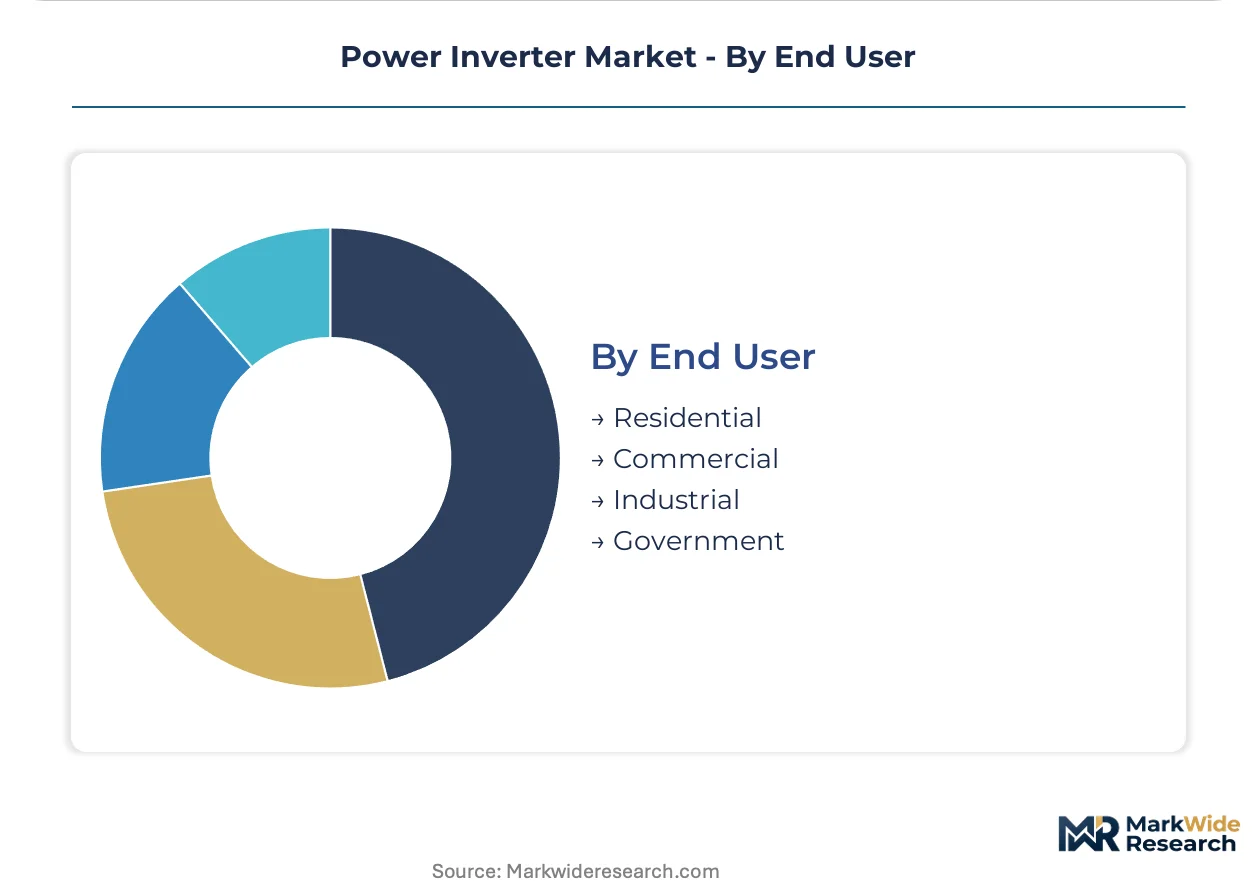
End User:
Project scale and procurement authority concentration separate residential fragmentation from industrial consolidation.
- Residential:Encompasses homeowner-owned rooftop solar, backup power systems, and battery storage integration. Net metering reforms in the United States and time-of-use tariffs in Germany and Australia reshape economics toward hybrid inverter architectures. Procurement scatters across individual decision-makers with high price sensitivity.
- Industrial:Absorbs megawatt-scale power conversion for manufacturing facilities, data centers, and process industries. Engineering-procurement-construction firms consolidate specification authority, unbundling inverter supply from installation contracts. Lifecycle cost metrics displace upfront capital expenditure in vendor selection.
- Commercial:Covers office buildings, retail installations, and agricultural operations with intermediate capacity requirements. Germany's commercial rooftop segment concentrates demand for energy yield guarantees tied to inverter performance forecasting.
- Government:Includes military, public infrastructure, and rural electrification programs with procurement through tender mechanisms. Specifications emphasize domestic content requirements and extended warranty terms.
Government procurement maintains steady but bureaucratically constrained volume. Industrial end user segment shows the steepest expansion trajectory as commercial and industrial solar penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate fabrication concentrates in Chinese and Japanese foundries, anchoring inverter supply chains to East Asian semiconductor nodes. Regional deployment patterns diverge sharply between mature rooftop markets and emerging utility-scale programs.
China
Utility-scale photovoltaic procurement drives inverter demand as GB standards mandate 1500V DC bus architectures and fault-ride-through capabilities. MIIT industrial policy prioritizes domestic semiconductor content in power electronics. Yangtze River Delta manufacturing clusters host vertically integrated producers serving both domestic installations and Southeast Asian export assembly.
Germany
Residential battery storage paired with hybrid inverters accelerates under time-of-use tariff restructuring and net metering reform. EU Green Deal directives harmonize grid code requirements across member states, reducing certification fragmentation. Bavaria and Baden-Württemberg concentrate commercial rooftop installations where energy yield guarantees hinge on inverter performance forecasting.
United States
FERC Order 2023 synchronizes interconnection standards across regional transmission organizations, reshaping product development priorities for utility-scale developers. IRA clean energy tax credits accelerate commercial and industrial solar deployment. California and Texas lead procurement concentration, with Southwest utility-scale projects specifying silicon carbide-enabled string architectures.
India
CEA technical regulations mandate reactive power support and anti-islanding protection, accelerating replacement cycles in existing photovoltaic fleets. National renewable portfolio standards tighten grid-interconnection rules for distributed energy resources. Gujarat and Rajasthan host gigawatt-scale solar parks where string inverter procurement concentrates under domestic content requirements.
Australia
Time-of-use tariffs and declining feed-in rates reshape homeowner economics toward DC-coupled battery storage with hybrid inverter architectures. State-level renewable energy targets exceed national commitments in Victoria and New South Wales. Distributed generation penetration drives module-level power electronics adoption in commercial rooftop segments.
Power Inverter Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue vehicle-to-grid integration and residential energy management convergence. Market structure shows moderate consolidation around vertically integrated semiconductor-inverter hybrids and specialized service-network operators. Three archetypes dominate: silicon carbide technology leaders, utility-scale project specialists, and residential storage integrators. Capacity expansion and strategic partnerships constitute the primary competitive vectors as manufacturers secure tariff-advantaged assembly nodes.
Among Chinese producers, Huawei Technologies Co., Ltd. and Sungrow Power Supply Co., Ltd. exemplify vertically integrated scale positions, while SMA Solar Technology AG represents European specialization in IEC-certified rooftop segments. These anchors illustrate divergent strategic postures: East Asian players leverage captive semiconductor sourcing for cost leadership, whereas German-based operators emphasize service density and certification breadth.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Sungrow Power Supply Co., Ltd. |
| SMA Solar Technology AG |
| ABB Ltd. |
| Delta Electronics |
| Enphase Energy |
| Fimer Group |
| Power Electronics S.L. |
| Growatt New Energy |
| Others |
Cost & Logistics Intelligence
Utility-scale developers in India and China specifying 1500V DC bus architectures with silicon carbide-enabled string inverters are forcing supply chains to absorb premium semiconductor content while compressing balance-of-systems costs, creating asymmetric pricing pressure across waveform fidelity tiers.
Pricing Analysis
Warranty bundling separates premium inverter positioning from unbundled transactional sales, with German and Australian residential buyers paying service-inclusive rates for hybrid architectures while Indian utility developers negotiate stripped hardware-only contracts. Three-tier pricing structure across pure sine wave, grid-tie, and modified sine wave configurations reflects certification grade divergence and semiconductor content. Cost compression in entry-level modified sine wave units is intensifying because Chinese assembly nodes compete on volume scale. Industrial end users show least price sensitivity as lifecycle cost metrics displace upfront capital expenditure in vendor selection.
Supply Chain Analysis
Dual-sourcing mandates from European EPC firms and American utility developers are forcing inverter manufacturers to qualify silicon carbide substrates from both Chinese and Japanese foundries alongside magnetics from Vietnamese and Thai winding facilities. Raw material dependencies center on silicon carbide wafers, aluminum electrolytic capacitors, and copper magnet wire. Single-source vulnerability concentrates in Chinese IGBT module fabrication for entry-level string architectures. Distribution runs through direct manufacturer-to-developer relationships in utility-scale segments and specialized electrical distributors in residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive semiconductor supply determines cost leadership, with Huawei and Sungrow leveraging in-house silicon carbide sourcing against European competitors dependent on external foundry allocation.
For Market Incumbents: Cement service network density in Germany's commercial rooftop segment where energy yield guarantees hinge on inverter performance forecasting. Lock in multi-year silicon carbide supply agreements with Yangtze River Delta foundries before capacity allocation disputes intensify. Module-level power electronics substitution threatens string architecture share in commercial applications.
For New Entrants and Emerging Players: Begin with vehicle-to-grid integration hardware for bidirectional residential energy management systems in California and Texas where FERC Order 2023 standardization reduces certification burden. Australia's time-of-use tariff restructuring creates penetrable hybrid inverter demand among homeowners seeking DC-coupled battery pairing. Partner with automotive Tier 1 suppliers for onboard charger-inverter convergence technology.
For Investors and Strategic Acquirers: The window for entry favors silicon carbide technology specialists with captive semiconductor sourcing or IEC-certified European service networks. Long-term viability over the coming decade rests on backward integration into wide-bandgap substrate fabrication or forward integration into residential energy management software. Watch for CEA technical regulation amendments in India as inflection indicators for utility-scale replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Investment | Captive substrate supply secures cost leadership against tariff-exposed competitors in utility-scale procurement. |
| Hybrid Inverter Platform Launch | DC-coupled battery integration captures German and Australian residential demand under time-of-use restructuring. |
| Vehicle-to-Grid Certification Pathway | Bidirectional hardware qualification opens California and Texas aftermarket retrofit opportunities. |
| Southeast Asian Assembly Expansion | Vietnamese and Thai nodes circumvent trade barriers for tariff-advantaged access to Indian utility tenders. |
| Predictive Maintenance Analytics Integration | Performance forecasting capabilities satisfy German commercial rooftop energy yield guarantee requirements. |
Research Approach
Independent corroboration across inverter procurement officers at Indian and Chinese utility developers, EPC contract managers in Germany and the United States, and residential installer networks in Australia underwrites the qualitative findings. Primary interviews with power electronics R&D directors, semiconductor supply chain managers, and grid interconnection compliance specialists combined with secondary validation from FERC filings, CEA technical regulations, EU Green Deal directive texts, and MIIT industrial policy announcements. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Rate-of-change decomposition across the analysis window separates volume expansion from price trajectory and mix shift effects. Segmentation dimensions modeled include waveform fidelity tier, technology integration depth, application vertical, and end-user scale category alongside regional regulatory framework clustering. CAGRs derive from logistic diffusion curves fitted to historical deployment data and policy-mandated installation targets. Industry-specific forecast inputs incorporate silicon carbide adoption curves and grid code amendment implementation timelines.
Underlying measurement precision varies by segment; utility-scale procurement data carries tighter precision than fragmented residential sales. Forecasts reflect documented assumptions regarding semiconductor supply resilience and interconnection standard harmonization. A model refresh is warranted upon material change in CEA or GB standards implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Synchrophasors Market
Power Systems
Power Integrated Modules Market
Power Systems
Power Supply and Charger Market
Power Systems
Battery Cyclers Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
EV Power Module Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Synchronous Condenser Market
Power Systems
Thermal Management Systems Market
Power Systems
Embedded Power Generation Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Low Voltage DC Circuit Breaker Market