
 Miniature-Circuit Breaker Market | 2026-2036
Miniature-Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Miniature-Circuit Breaker Market Intelligence
Silver-cadmium oxide contact material is recalibrating cost-performance trade-offs across the Miniature-Circuit Breaker landscape as manufacturers seek alternatives to cadmium under REACH pressure. Schneider Electric leverages its captive supply of bimetallic strips to sustain margin control in European distribution channels. Siemens anchors its position through R&D intensity focused on solid-state trip units, while ABB competes on manufacturing scale across Asian assembly hubs.
A miniature circuit breaker is an electromechanical protection device rated typically between 6A and 125A, designed to interrupt overcurrent faults through thermal-magnetic or electronic trip mechanisms without requiring replacement after operation. Its primary purpose is safeguarding branch circuits in low-voltage electrical installations against overload and short-circuit conditions. The electromechanical technology segment retains the dominant installed base due to its cost simplicity and decades of contractor familiarity, while smart breakers with embedded metering and remote trip capability represent the fastest-expanding margin pool as building automation systems proliferate. Single-pole units occupy the highest volume tier in residential construction, though three-pole configurations command premium positioning in industrial motor protection applications.
The European Chemicals Agency restricts cadmium content under REACH Annex XVII, compelling contact material reformulation across export-oriented suppliers. The US National Electrical Code, administered by the National Fire Protection Association, mandates arc-fault circuit interrupter compatibility in residential panels, elevating product complexity for OEMs serving North American contractors. China's State Administration for Market Regulation enforces GB 10963 standards that increasingly align with IEC performance benchmarks, smoothing market access for multinational producers. Stakeholders must weigh material transition costs against the pricing power that certified smart-breaker portfolios confer in specification-driven segments.
Market Dynamics
Smart grid infrastructure buildouts are compressing replacement cycles for electromechanical breakers while simultaneously elevating specifications for solid-state trip units with embedded metering capabilities. This dual pressure is fragmenting supplier portfolios between cost-optimized residential units and premium industrial-grade protection systems.
Growth Catalysts
- Data center power density:Hyperscale facilities require compact protection devices capable of handling elevated thermal loads without panel space expansion. Schneider Electric and ABB have expanded dedicated product lines for colocation operators.
- China residential electrification:State Grid Corporation's rural grid modernization is accelerating MCB installation rates in tier-three and tier-four cities. GB 10963 standard alignment with IEC benchmarks reduces import friction for multinational producers.
- AFCI mandate expansion:The US National Electrical Code's arc-fault circuit interrupter requirements for residential panels elevate product complexity and average selling prices for OEMs serving North American electrical contractors.
Market Restraints
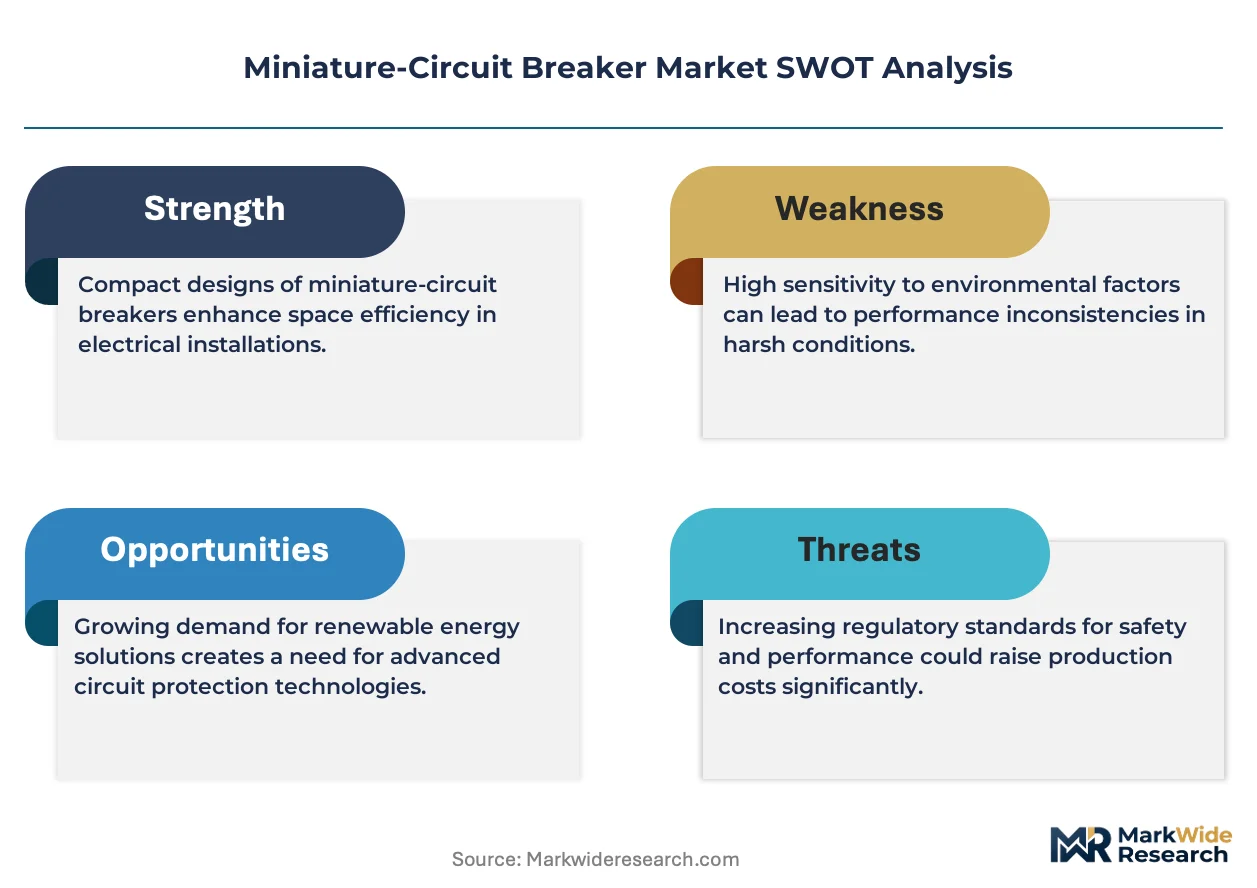
- Silver-cadmium oxide phaseout:ECHA REACH Annex XVII restrictions on cadmium content compel contact material reformulation. Alternative silver-metal oxide composites carry 15-25% raw material cost premiums.
- Bimetallic strip supply concentration:Captive production of thermal trip elements concentrates among three European metallurgical suppliers. Disruptions affect lead times for electromechanical breaker manufacturers.
- Solid-state trip unit cost floor:Electronic protection modules require precision current sensors and microcontrollers that resist cost reduction at volumes below 500,000 units annually.
Strategic Opportunities
- India smart meter integration:Ministry of Power mandates for prepaid metering create demand for breakers with remote trip capability and power quality logging. Domestic manufacturers lack certified portfolios.
- Building automation convergence:BACnet and Modbus protocol integration enables MCBs to function as edge nodes in energy management systems. This positions protection devices within facility software procurement budgets.
- EU Green Deal refurbishment:Energy Performance of Buildings Directive renovations require panel upgrades in commercial structures over 1,000 square meters. Contractors specify smart breakers to demonstrate compliance.
Industry Challenges
- IEC 60898-1:2015 testing backlog:Certification bodies face 14-18 month queues for trip-curve validation. Manufacturers delay product launches or ship uncertified units with liability exposure.
- Legacy panel interoperability:DIN rail dimensions from 1980s installations conflict with contemporary smart breaker form factors. Retrofit adapters erode margins and complicate contractor training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miniature-Circuit Breaker Market |
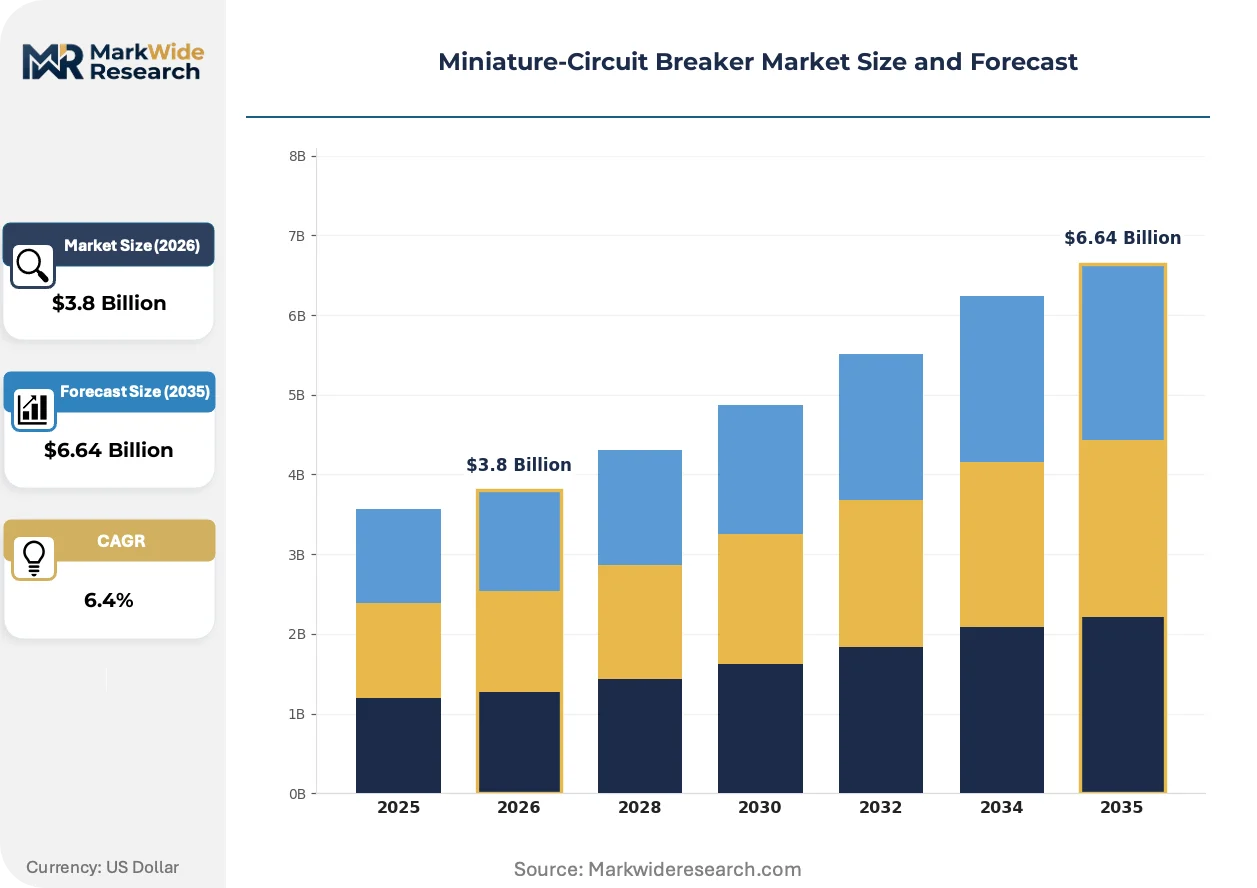
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Pole, Double Pole, Triple Pole, Four Pole Application: Residential, Commercial, Industrial, Automotive Technology: Electromechanical, Electronic, Smart, Hybrid End User: OEMs, Contractors, Utilities, Distributors |
| Companies Covered | Schneider Electric, ABB, Siemens, Eaton Corporation, Mitsubishi Electric, Legrand, LS ELECTRIC, Hager Group, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miniature-Circuit Breaker Market Strategic Shifts & Innovations
Solid-state protection technology is automating fault detection and response workflows that previously required manual intervention. This shift compresses maintenance intervals while generating operational data streams that building managers now expect as standard.
Electronic trip units with embedded Rogowski coils are automating precise current measurement across harmonic-rich loads. Data center operators deploy these devices to isolate server rack faults without upstream nuisance tripping. The technology is automating selective coordination studies that previously required external engineering consultants.
ECHA REACH restrictions on cadmium compounds are forcing contact material transitions toward silver-tin oxide and silver-zinc oxide composites. German manufacturers face the steepest compliance timelines due to domestic environmental enforcement intensity. Export-oriented suppliers in China and India accelerate reformulation to maintain EU market access.
Electrical contractors increasingly bundle breaker procurement with predictive maintenance software subscriptions. Industrial end-users in Germany and the Netherlands prefer outcome-based contracts covering protection device lifecycle replacement. This procurement evolution compresses distributor margins while elevating manufacturer direct sales capabilities.
Miniature-Circuit Breaker Market Segmentation
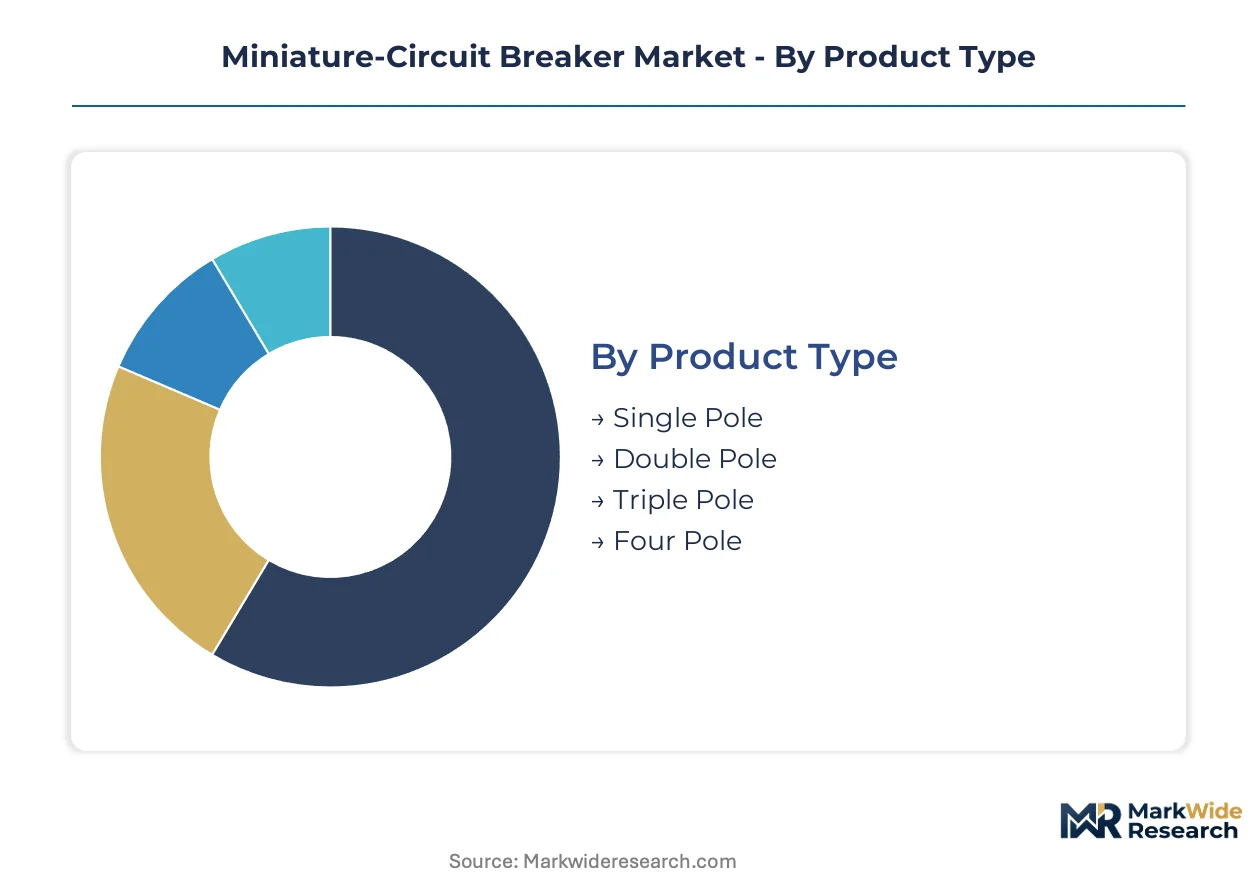
MCB procurement patterns diverge sharply across installation environments, with specification complexity and replacement frequency varying by end-use intensity. Understanding these fault lines enables suppliers to align R&D spend with margin-accretive segments.
Product Type:
Contractors select pole configurations based on phase requirements and panel density constraints, not unit economics alone.
- Single Pole:Rated for 230V single-phase circuits, these units protect lighting and small appliance branch circuits in residential distribution boards. Demand concentrates in China's tier-three and tier-four cities where State Grid Corporation's rural electrification drives volume installation in multi-story housing.
- Triple Pole:Designed for three-phase 400V industrial motor protection, these configurations integrate thermal-magnetic trip elements calibrated for inrush tolerance. German manufacturing clusters and Indian automotive supplier parks generate specification-intensive procurement for machine tool circuits.
- Double Pole:Serve split-phase residential mains and commercial HVAC disconnects where neutral switching is mandated.
- Four Pole:Protect three-phase circuits with neutral isolation requirements in data center UPS distribution and medical facility critical power.
Volume sits with Single Pole; growth tilts toward Triple Pole.
Application:
Installation standards and fault-current exposure create four distinct specification tiers with diverging certification burdens.
- Residential:AFCI compatibility requirements under the US National Electrical Code elevate product complexity for North American contractors. IEC 60898-1 certification suffices for most European and Asian installations, though arc-fault variants command 40-60% price premiums.
- Industrial:Motor protection applications demand magnetic trip curves with precise inrush tolerance and short-circuit breaking capacity above 10kA. German automotive stamping plants and Chinese steel mills specify selective coordination with upstream protection.
- Commercial:Office and retail installations prioritize DIN rail compatibility and visual trip indication for faster maintenance response.
- Automotive:EV charging infrastructure and battery assembly lines require DC-rated variants with modified arc-quenching chambers.
Margins peak in Industrial; unit velocity concentrates in Residential.
Technology:
Trip mechanism architecture determines maintenance intervals, diagnostic capability, and integration potential with building management systems.
- Smart:Embedded metering, remote trip capability, and BACnet/Modbus protocol support position these units as edge nodes in energy management platforms. EU Energy Performance of Buildings Directive compliance drives specification in German and Dutch commercial renovations.
- Electromechanical:Bimetallic thermal elements and magnetic solenoids deliver cost-optimized protection without external power requirements. China's residential electrification and India's rural grid expansion sustain volume demand despite functional limitations.
- Electronic:Solid-state trip units with Rogowski coil sensors enable precise harmonic-rich load measurement for data center selective coordination.
- Hybrid:Combine electromechanical reliability with electronic monitoring for critical infrastructure where redundancy matters.
Electromechanical dominates installed base; Smart gains share fastest.
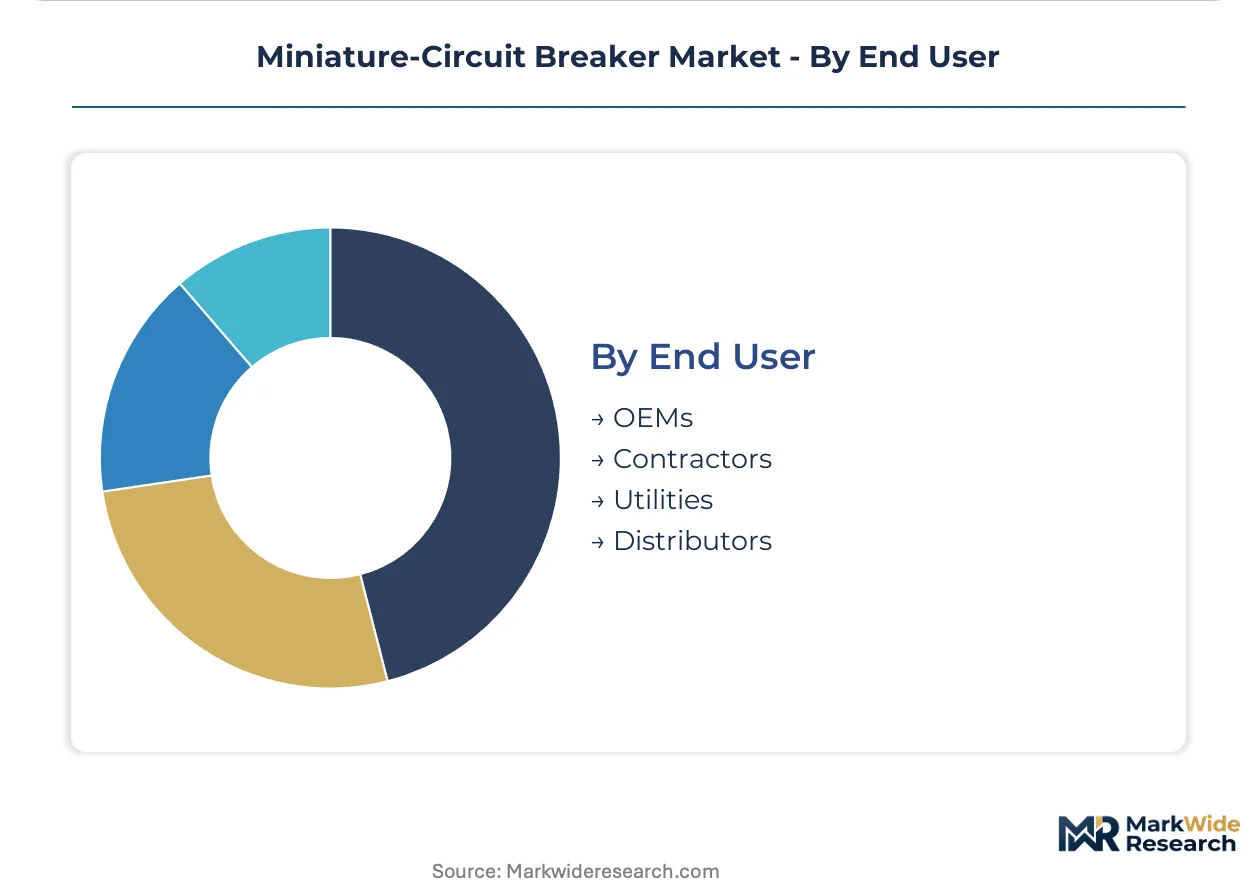
End User:
Procurement authority and technical sophistication vary across the value chain, shaping pricing power and support requirements.
- Contractors:Electrical installation professionals prioritize availability, familiar trip curves, and compatibility with legacy DIN rail configurations. German and French contractor associations influence specification through preferred manufacturer lists.
- Utilities:Grid operators in India and China mandate remote trip capability and prepaid metering integration for smart grid rollouts. Ministry of Power directives in India create certified-product shortages.
- OEMs:Panel builders and switchgear manufacturers source breakers as bill-of-materials components with volume pricing and private-label options.
- Distributors:Electrical wholesalers intermediate between manufacturers and fragmented contractor bases, carrying inventory risk and technical support obligations.
Contractors drive volume throughput; Utilities command specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of miniature-circuit breaker demand through State Grid Corporation's rural electrification campaigns and smart grid buildouts. India and Germany follow as high-growth specification markets with diverging regulatory drivers.
China
Tier-three and tier-four cities drive volume installation through State Grid's rural grid modernization. GB 10963 standards alignment with IEC benchmarks reduces import friction for multinational producers. The Yangtze River Delta hosts dense manufacturing clusters where local suppliers compete on cost-optimized electromechanical units.
India
Ministry of Power mandates for prepaid smart metering create certified-product shortages in remote trip-capable breakers. Domestic manufacturers lack portfolios matching utility specifications. Gujarat and Maharashtra industrial corridors generate procurement for three-pole motor protection configurations in automotive supplier parks.
Germany
EU Energy Performance of Buildings Directive renovations mandate panel upgrades in commercial structures exceeding 1,000 square meters. ECHA REACH Annex XVII enforcement accelerates cadmium-phaseout timelines for contact materials. Bavarian automotive stamping plants specify selective coordination with upstream protection systems.
United States
AFCI compatibility requirements under the National Electrical Code elevate product complexity for residential panel OEMs. NEC 2020 and 2023 cycle updates expand arc-fault mandates to additional circuit types. Texas and California data center clusters drive specification for compact protection devices handling elevated thermal loads.
Japan
METI efficiency standards for building energy management systems elevate smart breaker specifications in commercial retrofits. JIS C 8201 alignment with IEC performance benchmarks smooths certification for imported electronic trip units. Kanto region facility managers prioritize BACnet protocol integration for energy management platforms.
Miniature-Circuit Breaker Market Key Industry Players
Portfolio diversification dominates the current landscape as suppliers fragment between cost-optimized residential units and premium industrial-grade protection systems. The vendor base separates into three tiers: integrated electrical conglomerates with captive component supply, specialized protection device manufacturers with regional density, and emerging Asian fabricators competing on electromechanical volume. Two competitive moves define positioning: backward integration into bimetallic strip and contact material production, and technology licensing partnerships for solid-state trip unit architectures.
Among integrated electrical conglomerates, Schneider Electric, ABB, and Siemens exemplify divergent strategic archetypes. Schneider Electric represents the captive supply model with in-house bimetallic strip production sustaining margin control in European distribution channels. ABB anchors the manufacturing scale archetype through Asian assembly hub density. Siemens occupies the R&D intensity position with solid-state trip unit development focus. These three entities collectively represent the competitive tension between electromechanical cost optimization and electronic protection premiumization.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens |
| Eaton Corporation |
| Mitsubishi Electric |
| Legrand |
| LS ELECTRIC |
| Hager Group |
| General Electric |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between IEC 60898-1 certified smart breakers and commodity electromechanical units manifests in divergent pricing architectures and supply chain configurations across the Miniature-Circuit Breaker landscape. Smart units with embedded metering and remote trip capability command substantial premiums through dedicated semiconductor foundry partnerships, while cost-optimized residential units anchor pricing through high-volume bimetallic strip sourcing from Yangtze River Delta metallurgical clusters.
Pricing Analysis
Volume concentrates in single-pole electromechanical units where price differentiation rests on bimetallic strip sourcing efficiency and DIN rail compatibility certification. Smart breakers with BACnet protocol integration and prepaid metering capability face upward pricing pressure from precision current sensor costs and microcontroller procurement constraints. Contractors in China's tier-three cities exhibit the highest price sensitivity, while German automotive stamping plants prioritize selective coordination performance over unit economics.
Supply Chain Analysis
Freight cost escalation from Asian assembly hubs to European distribution centers is compressing margins on electromechanical units that compete primarily on landed cost. Manufacturing concentrates in China, Germany, and India, with raw material dependencies spanning silver-tin oxide contact composites, copper busbar stock, and thermoset plastic housings. Single-source vulnerability in European bimetallic strip supply creates lead time risk for thermal trip element procurement. Distribution runs through electrical wholesalers who intermediate technical support and inventory carrying obligations for fragmented contractor bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Miniature-Circuit Breaker market operates under supply-constrained conditions where ECHA REACH Annex XVII cadmium phaseout timelines have compressed qualified contact material capacity, propping pricing power for certified reformulation suppliers.
For Market Incumbents: Deploy captive bimetallic strip production as a defensive moat against lead time volatility from European metallurgical suppliers. Incumbent manufacturers should accelerate silver-tin oxide and silver-zinc oxide composite qualification to preempt regulatory enforcement intensity in German export markets, while consolidating distribution channel control through predictive maintenance software bundling that elevates direct sales penetration. For New Entrants and Emerging Players: India's Ministry of Power smart metering mandates in Gujarat and Maharashtra open a window for certified remote-trip breaker portfolios where domestic manufacturers lack accredited offerings. New entrants should target utility procurement specifications with prepaid metering integration as the most penetrable wedge, leveraging third-party certification acceleration services to compress IEC 60898-1 validation timelines. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state trip unit specialists given data center selective coordination demand and building automation convergence catalysts. Acquisition targets with Rogowski coil sensor integration and BACnet protocol stacks offer the strongest long-term viability within a five-to-ten year electrification and refurbishment cycle. Investors should monitor ECHA enforcement intensity against cadmium compound residues as the primary inflection signal for contact material transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Materials | Captive silver-metal oxide composite production insulates margin control against ECHA REACH raw material cost premiums. |
| Smart Meter Protocol Certification | IEC 62056 DLMS/COSEM stack integration unlocks utility procurement specifications in India's prepaid metering rollout. |
| Selective Coordination Software Bundling | Predictive maintenance subscriptions reposition breakers within facility software budgets, compressing distributor intermediation. |
| Asian Assembly Hub Expansion | Yangtze River Delta manufacturing density reduces freight exposure to European electromechanical unit distribution channels. |
| DC-Rated Variant Development | Modified arc-quenching chambers for EV charging infrastructure capture automotive electrification specification demand. |
Research Approach
Independent corroboration across plant engineers at German automotive stamping facilities, procurement leads at Indian State Grid Corporation distribution utilities, and electrical contractor associations in France and the Netherlands underwrites the qualitative findings. Primary interviews with thermal trip element metallurgists, solid-state protection R&D directors, and electrical wholesale distribution heads combined with secondary validation from IEC certification body disclosure records, ECHA REACH restriction entry documentation, and National Electrical Code amendment filings. Bottom-up unit shipment estimates triangulate against top-down construction spend allocation models across residential, commercial, and industrial installation environments.
Comparable-period anchoring to historical electromechanical replacement cycles and smart grid infrastructure deployment waves structured the forecast window across the analysis window. The analytical framework models segmentation dimensions spanning pole configuration, trip mechanism architecture, application intensity, and end-user procurement authority. CAGRs derive from installation rate projections calibrated to State Grid rural electrification targets, EU Energy Performance of Buildings Directive renovation mandates, and data center power density escalation curves. Industry-specific inputs include AFCI mandate expansion timelines under NEC cycles and solid-state trip unit cost floor trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state protection displacement of electromechanical units would alter the outlook if cost reduction curves steepen beyond precision sensor volume thresholds. Forecasts reflect documented assumptions regarding ECHA enforcement intensity, IEC certification queue durations, and bimetallic strip supply concentration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Contactor-based Transfer Switch Market
Switches
Asia Pacific Safety Switches Market
Switches
India Switchgear Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Smart Pole-Mounted Switch Market
Switches
Electromechanical Microwave Switch Market
Switches
North America MV Switchgear Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
5G Solid State Switches Market
Switches
Global Safety Switches Market
Switches
United States X by Wire Systems Market
Switches
Panel Mounted Disconnect Switch Market
Switches
Japan Reed Sensors Switches Market
Switches
Global Switchgear Market
Switches
Solid State Relay Market
Switches
Navigation Switches Market