
 Global Uninterruptible Power Supply (UPS) Market | 2026-2036
Global Uninterruptible Power Supply (UPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Uninterruptible Power Supply (UPS) Market Outlook
The EU Green Deal is broadening the addressable market for high-efficiency UPS architectures across European data center buildouts. Schneider Electric leverages its integrated power management portfolio to anchor large-scale deployments in France and Germany. Eaton Corporation competes through specialized three-phase systems for industrial microgrids. Huawei Technologies extends its presence in modular UPS configurations for telecommunications infrastructure across Asia.
A Global Uninterruptible Power Supply (UPS) is an electrical apparatus that provides emergency power through battery, flywheel, or supercapacitor storage when input power fails, with on-line systems delivering zero transfer time through double-conversion rectifier-inverter chains. Its primary purpose is protecting mission-critical loads—servers, medical imaging equipment, process controllers—from voltage sags, frequency deviations, and complete outages. Modular product types are capturing disproportionate capital allocation as operators prioritize scalable redundancy and reduced mean time to repair. Above 10 kVA power rating segments dominate value pools given data center and healthcare concentration, while rack-mounted formats sustain growth in edge computing and 5G telecommunications deployments. On-line technology leads where power quality tolerance approaches zero, though line-interactive designs occupy cost-sensitive commercial segments.
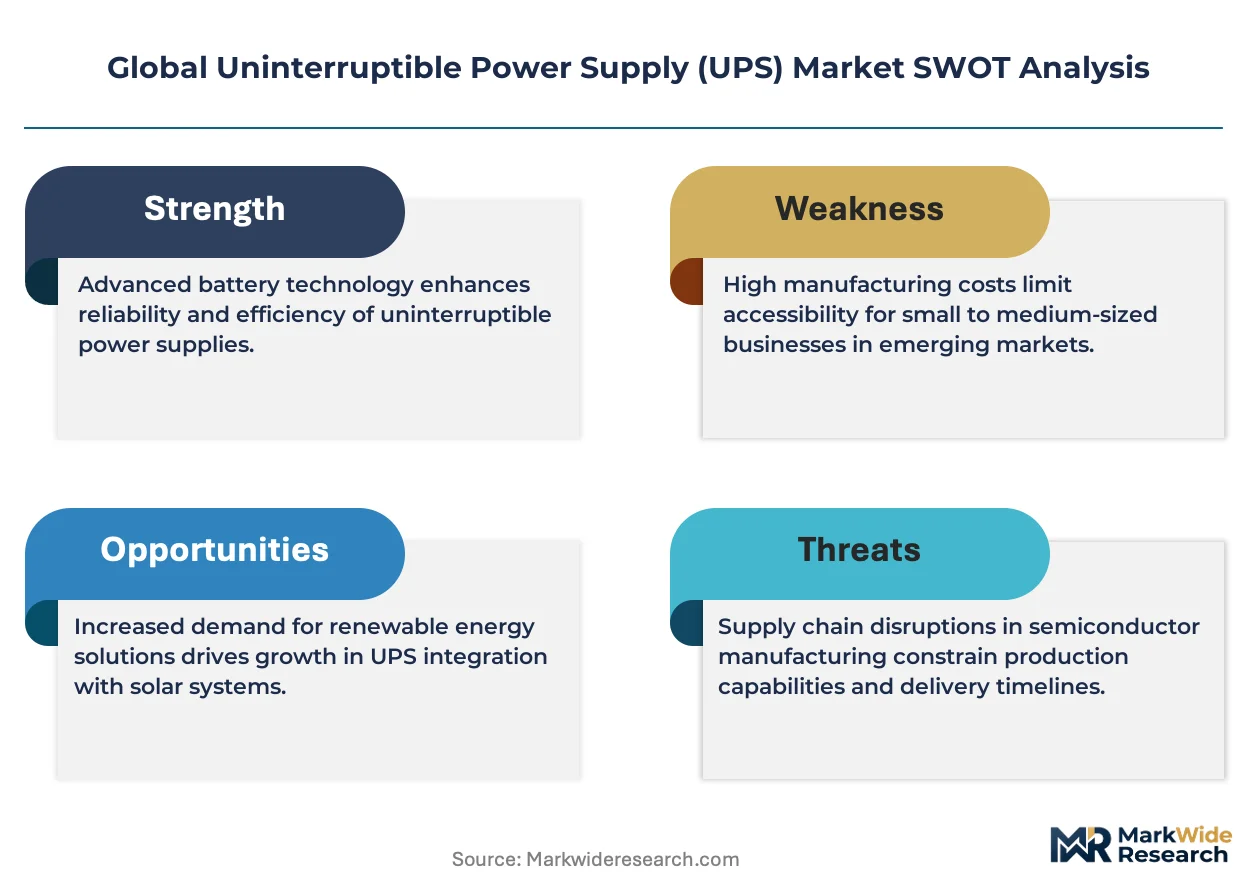
The EU F-Gas Regulation and EPA energy efficiency standards are tightening refrigerant and conversion loss thresholds for thermal management and power conditioning equipment, directly shaping UPS product roadmaps and certification requirements. EMA and FDA uptime mandates for pharmaceutical manufacturing and hospital networks further harden backup power specifications across Europe and North America. IEC 62040 testing protocols and regional grid codes in China, India, and Brazil create layered compliance barriers that favor established multinationals with certification depth. Stakeholders must monitor how solid-state transformer integration and silicon carbide switching architectures alter efficiency benchmarks and incumbent competitive moats.
Market Dynamics
Silicon carbide switching architectures are compressing conversion losses below 2% in double-conversion UPS topologies, forcing incumbents to retool manufacturing lines and recertify product portfolios under tightening IEC 62040 efficiency tiers.
Growth Catalysts
- Lithium-ion chemistry maturation:Cell costs below nickel-cadmium alternatives enable 40% footprint reduction in data center white space. Operators in Frankfurt and Singapore are specifying lithium-ion as default for new builds.
- EU F-Gas Regulation:Phase-down of synthetic refrigerants in thermal management systems is accelerating demand for air-cooled UPS architectures that eliminate dependency on chilled water infrastructure.
- Hyperscale data center construction:Amazon Web Services, Microsoft Azure, and Google Cloud facility commitments in Northern Virginia, Dublin, and Singapore are concentrating procurement of 500 kVA and above three-phase systems.
Market Restraints
- Raw material concentration:Lithium carbonate processing capacity concentrates in Sichuan province and Chilean salares, exposing battery pack assemblers to geopolitical and climate-related supply interruptions.
- Copper winding cost volatility:Transformer and inductor manufacturers face margin compression from London Metal Exchange price swings, particularly affecting line-interactive product lines where copper represents 15-20% of bill-of-materials.
- Certification timeline friction:IEC 62040-3 testing protocols require 6-12 month validation cycles for new silicon carbide designs, delaying product launches and freezing R&D amortization schedules.
Strategic Opportunities
- Edge computing infrastructure:5G base station deployments and autonomous vehicle roadside units in India and Brazil remain 60-70% underpenetrated by on-line UPS protection, creating white space for 1-10 kVA rack-mounted formats.
- EU Green Deal public procurement:Member state tender rules now mandate lifecycle carbon accounting for backup power systems, advantaging suppliers with verified battery recycling partnerships and renewable manufacturing energy certificates.
- Solid-state transformer convergence:Integration of wide-bandgap power electronics with intelligent UPS control is enabling 98.5% efficiency at partial loads, opening hospital and semiconductor fabrication segments previously served by motor-generator sets.
Industry Challenges
- Power electronics talent scarcity:Design engineers with silicon carbide MOSFET gate drive expertise command 40% salary premiums over silicon IGBT specialists, constraining OEM expansion in Germany and Japan.
- Legacy SCADA integration complexity:Brownfield industrial sites running Modbus RTU and proprietary protocols require custom protocol gateways, extending commissioning timelines and eroding project margins.
- Battery thermal runaway containment:UL 9540A cell-to-cell propagation testing demands redundant detection and suppression systems, adding 8-12% to lithium-ion UPS system costs versus earlier nickel-cadmium installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Uninterruptible Power Supply (UPS) Market |
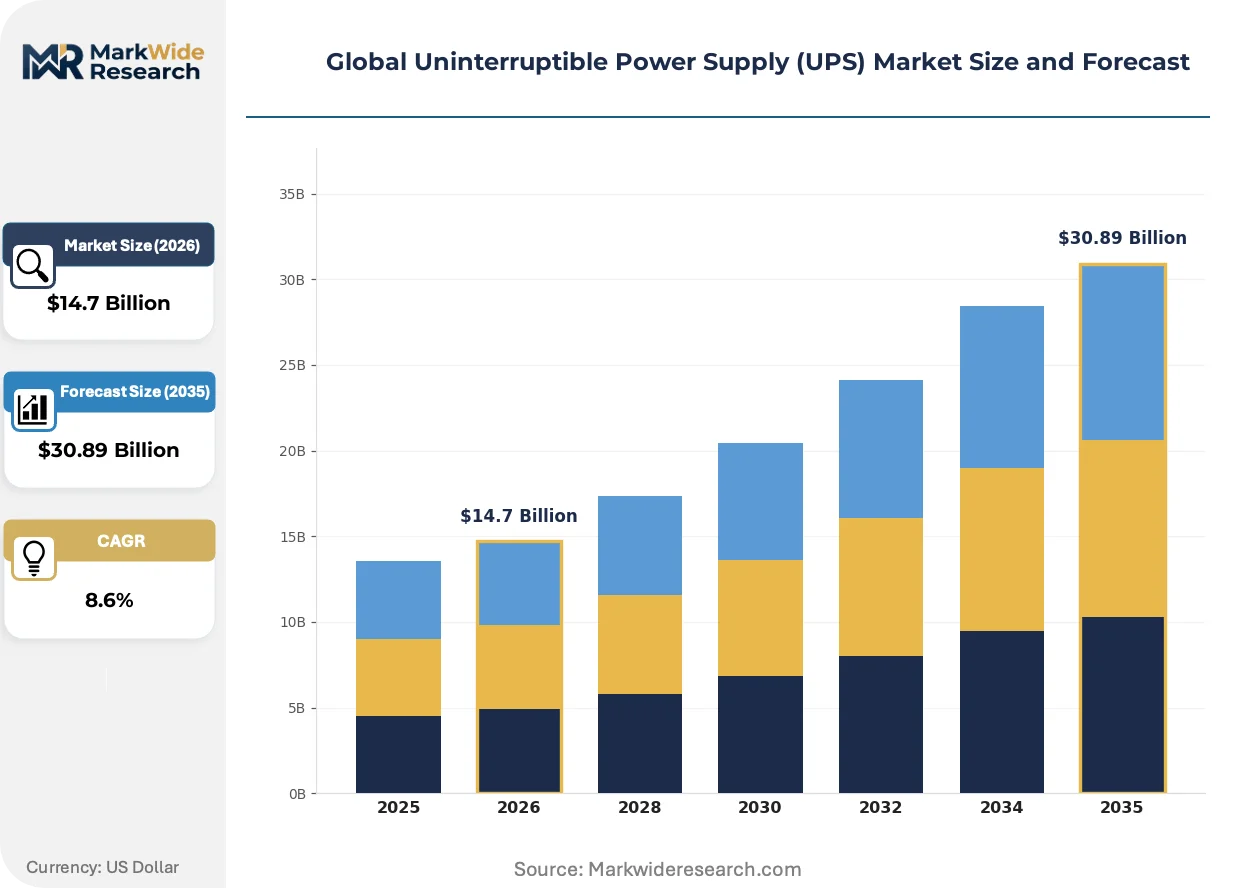
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Rack-mounted, Modular, Three-phase Power Rating: Below 1 kVA, 1-5 kVA, 5-10 kVA, Above 10 kVA End User: Data Centers, Telecommunications, Healthcare, Industrial Technology: On-line, Line-interactive, Off-line, Ferroresonant |
| Companies Covered | ABB, Huawei Technologies, Schneider Electric, Riello UPS, Socomec, Eaton Corporation, Delta Electronics, Toshiba Corporation, Vertiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Uninterruptible Power Supply (UPS) Market Strategic Shifts
Power semiconductor materials, thermal management architectures, and procurement contracting models are simultaneously evolving, compressing product lifecycles and fragmenting vendor competitive moats across voltage classes.
Wide-bandgap devices built on silicon carbide substrates are modularizing UPS power stages into standardized 50 kVA building blocks. Data center operators in Singapore and Frankfurt are specifying these configurations for 2N redundant architectures that permit hot-swappable module replacement without load transfer. The technology is modularizing vendor business models away from monolithic system sales toward recurring-revenue service contracts tied to availability guarantees.
EPA energy efficiency standards under the ENERGY STAR 2.0 specification are tightening minimum efficiency requirements for 1-10 kVA products to 94% at 25% load. Chinese manufacturers exporting to the United States must redesign magnetics and cooling systems to maintain certification eligibility. The regulation is compressing margins in the volume commercial segment while advantaging suppliers with captive transformer winding capabilities.
Colocation and hyperscale buyers are consolidating procurement through master service agreements that bundle UPS hardware, installation, and 10-year battery replacement into single-contract lifecycle pricing. Channel partners in Northern Virginia and Amsterdam are losing standalone equipment margins as direct OEM relationships displace traditional distribution. The shift is visible in Requests for Proposal that exclude distributor markups and mandate factory-authorized commissioning engineers.
Global Uninterruptible Power Supply (UPS) Market Segmentation
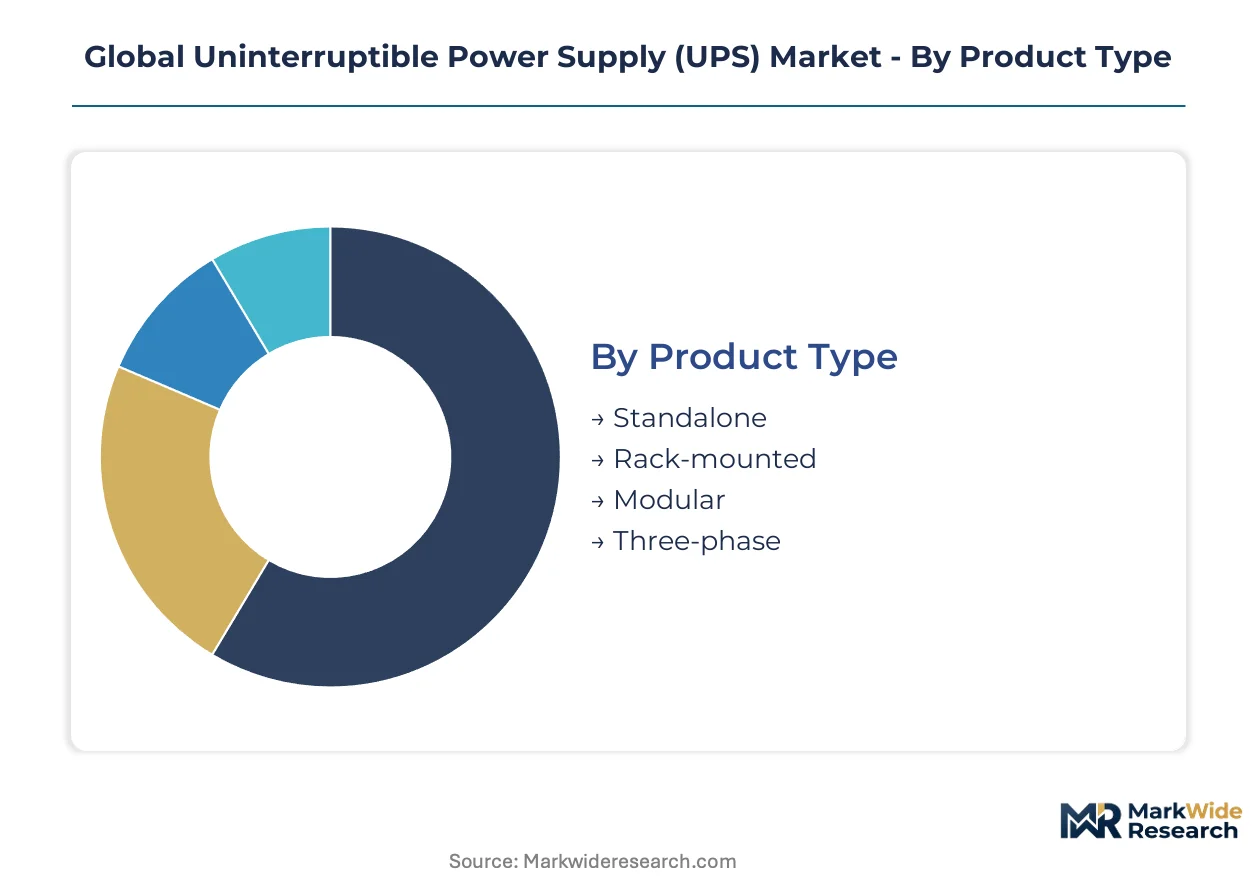
UPS procurement patterns diverge sharply across deployment contexts. Capital allocation, physical footprint constraints, and uptime tolerance collectively determine which configurations operators specify for data centers versus edge telecommunications or hospital networks.
Product Type:
Modular architectures command the highest upfront capital outlays per kilovolt-ampere of protected load, driven by redundant power modules and hot-swappable chassis engineering.
- Standalone:Self-contained tower enclosures serve small-to-medium server rooms and medical imaging suites. Demand concentrates in Germany and Japan where facility managers prioritize acoustic isolation from occupied workspaces.
- Rack-mounted:19-inch chassis integrate directly into IT equipment racks, preserving floor space in constrained edge computing closets. Procurement is accelerating across India and Brazil for 5G base station deployments.
- Modular:Scalable 50 kVA building blocks enable pay-as-you-grow expansion without system shutdown. Frankfurt and Singapore data center operators specify these for 2N redundant architectures demanding 99.999% availability.
- Three-phase:Industrial-grade systems protect manufacturing lines and semiconductor fabrication equipment. Installations cluster in East Asian electronics manufacturing clusters where voltage sag tolerance approaches zero.
Most installed capacity flows through Standalone units in legacy commercial buildings. Expansion is steepest in Modular configurations as hyperscale operators prioritize scalable redundancy.
Power Rating:
Unit economics and customer procurement scale invert across this dimension, with sub-5 kVA products serving high-volume, low-margin commercial segments.
- Below 1 kVA:Desktop and workstation protection for financial trading floors and diagnostic equipment. Volume sales dominate in North American small business networks.
- 1-5 kVA:Server rack and network closet protection. Brazilian telecommunications infrastructure expansion is absorbing significant volumes of rack-mounted formats in this range.
- 5-10 kVA:Mid-tier data center and healthcare imaging applications. EPA ENERGY STAR 2.0 efficiency mandates are forcing magnetics redesigns for products targeting the United States.
- Above 10 kVA:Double-conversion on-line systems with silicon carbide switching achieve sub-2% conversion losses. Northern Virginia and Dublin hyperscale facilities concentrate procurement of 500 kVA and above three-phase systems.
Shipment volumes peak in the 1-5 kVA band. Value concentration and margin expansion concentrate in Above 10 kVA systems serving mission-critical loads.
End User:
Regulatory stringency and uptime liability create divergent purchasing criteria across verticals.
- Data Centers:Colocation and cloud operators specify lithium-ion based modular systems with 10-year lifecycle service contracts. EU Green Deal carbon accounting requirements now penetrate procurement specifications in France and Germany.
- Telecommunications:5G base station and fiber hub protection demands rack-mounted 1-10 kVA formats. Indian and Brazilian network buildouts remain 60-70% underpenetrated by on-line UPS protection.
- Healthcare:FDA and EMA uptime mandates for pharmaceutical manufacturing and hospital networks harden backup power specifications. Motor-generator set replacement is accelerating in semiconductor fabrication segments.
- Industrial:Brownfield sites running Modbus RTU and proprietary SCADA protocols require custom protocol gateways, extending commissioning timelines. IEC 62040-3 certification cycles delay product launches for silicon carbide designs.
Capital deployment is heaviest in Data Centers. Telecommunications infrastructure is gaining share fastest as 5G rollout accelerates across emerging markets.
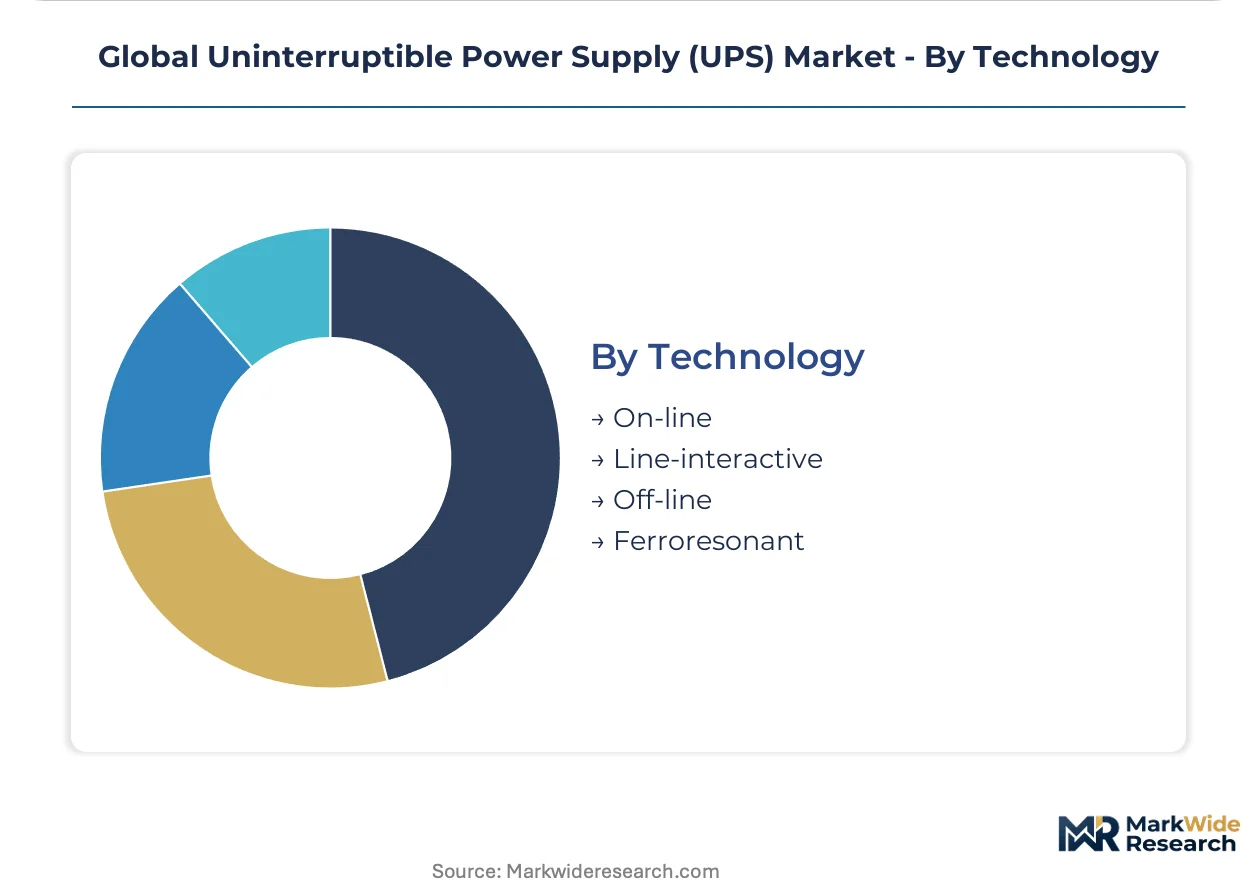
Technology:
Conversion topology determines efficiency, transfer time, and cost position in customer specifications.
- On-line:Double-conversion rectifier-inverter chains deliver zero transfer time through continuous AC-to-DC-to-AC regeneration. Silicon carbide MOSFET architectures are compressing losses below 2% in Frankfurt and Singapore deployments.
- Line-interactive:Tap-changing transformers correct voltage sags without full conversion, occupying cost-sensitive commercial segments. Copper winding cost volatility from London Metal Exchange price swings squeezes margins.
- Off-line:Standby switching engages only during complete outages, serving price-sensitive residential and small office applications. Limited penetration in mission-critical infrastructure.
- Ferroresonant:Saturable transformer designs provide inherent voltage regulation for legacy industrial motor loads. Declining share as silicon-controlled rectifier and IGBT technologies displace magnetic solutions.
Installed base dominance sits with Line-interactive systems in commercial buildings. On-line technology is climbing the fastest as data center power quality tolerance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UPS industry traces its modern scaling to American data center buildouts during the 1990s internet infrastructure boom. German engineering houses subsequently refined three-phase industrial systems for manufacturing automation. Today, procurement concentrates in five national markets where regulatory stringency and digital infrastructure investment intersect.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are consolidating 500 kVA and above procurement through direct OEM relationships. EPA ENERGY STAR 2.0 standards now mandate 94% minimum efficiency at 25% load for sub-10 kVA products. Chicago colocation facilities are retrofitting legacy static UPS with silicon carbide architectures to meet tightening conversion loss thresholds.
Germany
Frankfurt's data center cluster anchors European demand for lithium-ion modular systems with 2N redundancy. The EU F-Gas Regulation is phasing down synthetic refrigerants in thermal management, accelerating air-cooled UPS specifications. Bavarian automotive manufacturers are specifying three-phase protection for robotic welding lines under Industry 4.0 automation mandates.
China
Sichuan province's lithium carbonate processing concentration supplies battery pack assemblers serving East Asian manufacturing clusters. MIIT efficiency standards and dual carbon goals are reshaping procurement specifications for telecommunications infrastructure. Shenzhen and Shanghai data center operators are piloting solid-state transformer integration in hyperscale facilities.
Japan
METI energy efficiency mandates are compressing conversion loss tolerances for semiconductor fabrication equipment protection. Tokyo and Osaka data centers are specifying hot-swappable modular configurations to minimize mean time to repair. Kanto region telecommunications operators are deploying rack-mounted 1-10 kVA systems for 5G base station densification.
India
TRAI infrastructure mandates and 5G spectrum auctions are driving rack-mounted UPS procurement for base station deployments across Maharashtra and Karnataka. CEA grid code compliance requirements are layering certification complexity for imported silicon carbide designs. Bangalore and Hyderabad data center buildouts remain 60-70% underpenetrated by on-line protection, creating expansion headroom.
Global Uninterruptible Power Supply (UPS) Market Competitive Environment
Premium-margin players sit above commodity-margin players across power rating and technology sophistication tiers. The vendor base organizes into three distinct strata: integrated power management conglomerates with full-stack portfolios, specialized three-phase industrial specialists, and modular telecommunications-focused suppliers. Consolidation pressure is intensifying as hyperscale buyers bypass distribution channels through master service agreements. Technology licensing partnerships and captive silicon carbide component sourcing represent the dominant competitive vectors reshaping positioning.
Within the integrated power management tier, Schneider Electric and Eaton Corporation exemplify archetypes spanning commercial through hyperscale segments. Huawei Technologies occupies a position bridging telecommunications infrastructure and modular data center configurations. Delta Electronics represents the East Asian manufacturing cluster specialist with captive supply chain integration. These three anchors illustrate how geographic origin and historical end-market focus determine strategic optionality across lithium-ion chemistry maturation and wide-bandgap semiconductor transitions.
| Leading Market Players |
|---|
| ABB |
| Huawei Technologies |
| Schneider Electric |
| Riello UPS |
| Socomec |
| Eaton Corporation |
| Delta Electronics |
| Toshiba Corporation |
| Vertiv |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in European power electronics have consolidated transformer winding and magnetics capabilities, tightening supply discipline while compressing procurement leverage for mid-tier system integrators seeking copper-intensive line-interactive designs.
Pricing Analysis
Lifecycle service contracting with 10-year battery replacement bundling now dominates hyperscale procurement, separating direct OEM relationships from distributor-tagged transactions. Price differentiation hinges on IEC 62040-3 certification tier and silicon carbide switching architecture adoption. Cost compression in sub-10 kVA commercial segments is intensifying because EPA ENERGY STAR 2.0 mandates force magnetics redesigns. Edge computing buyers in India and Brazil exhibit highest price sensitivity; Frankfurt and Singapore data center operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
India's phased manufacturing program and local-content mandates for telecommunications infrastructure are reshaping sourcing patterns for rack-mounted 1-10 kVA systems. Lithium carbonate processing concentrates in Sichuan province and Chilean salares; silicon carbide substrates draw from Japanese and German wafer fabrication. Single-source vulnerability in Sichuan battery-grade chemical refining exposes assemblers to climate-related supply interruptions. Distribution runs through direct OEM master service agreements displacing traditional channel partners in Northern Virginia and Amsterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: lithium-ion cell costs and conversion efficiency standards diverge sharply between EU carbon-accounting regimes and Indian volume manufacturing zones.
For Market Incumbents: Anticipate silicon carbide MOSFET gate drive talent scarcity constraining German and Japanese expansion by captive hiring in Taiwanese power semiconductor clusters. Defend position by deepening backward integration into lithium carbonate offtake agreements with Chilean salares operators. IEC 62040-3 recertification timelines represent the critical margin pressure point.
For New Entrants and Emerging Players: Brazilian telecommunications infrastructure operators remain 60-70% underpenetrated by on-line UPS protection, presenting white-space expansion for 1-10 kVA rack-mounted formats. Target CEA grid code compliance as a differentiated entry barrier against unvalidated silicon carbide designs. Go-to-market through Brazilian tower company managed service contracts bypasses incumbent distribution lock-in.
For Investors and Strategic Acquirers: Valuations sit cheapest among captive-winding specialists with stranded copper transformer capabilities facing EPA efficiency mandates. Five-to-ten year viability favors suppliers with verified battery recycling partnerships under EU Green Deal lifecycle accounting rules. Watch solid-state transformer pilot deployments in Shenzhen and Shanghai hyperscale facilities as inflection signal for wide-bandgap convergence plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Switching Architecture Adoption | Compresses conversion losses below 2% in Frankfurt double-conversion deployments, forcing incumbent manufacturing line retooling. |
| Lithium-Ion Battery Recycling Partnership | Secures EU Green Deal tender eligibility through verified lifecycle carbon accounting and renewable manufacturing certificates. |
| Direct OEM Master Service Agreement | Displaces Northern Virginia and Amsterdam channel partners by bundling hardware, installation, and 10-year battery replacement. |
| Local-Content Manufacturing in India | Aligns with TRAI infrastructure mandates and CEA grid code compliance for 5G base station rack-mounted deployments. |
| Solid-State Transformer Integration | Enables 98.5% efficiency at partial loads, opening hospital and semiconductor fabrication segments from motor-generator sets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged data center infrastructure directors, telecommunications procurement leads, power electronics design engineers, battery system integrators, and industrial plant maintenance heads. Secondary validation drew from IEC 62040 certification registries, EPA ENERGY STAR product databases, EU F-Gas Regulation implementation reports, and hyperscaler capital expenditure disclosures. Bottom-up unit shipment modeling and top-down value chain sizing were triangulated against regional grid code compliance filings.
Segment-weighting across product type, power rating, end user vertical, and technology topology anchored the analytical framework. CAGRs were derived from installed base replacement cycles, efficiency regulation phase-in schedules, and hyperscale construction pipeline tracking. Forecast inputs incorporated lithium-ion cell cost curves, copper LME price volatility bands, and silicon carbide wafer supply expansion timelines.
Underlying measurement precision varies by segment; modular and above-10 kVA systems carry tighter precision than line-interactive commercial volumes given consolidated procurement transparency. Forecasts reflect documented assumptions on battery chemistry transition rates, regulatory enforcement intensity, and grid stability investment patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Thermoelectric Coolers Market
Power Systems
Medium Voltage Drives Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Power Diode Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Automotive Inverters Market
Power Systems
Asia Pacific Transformer Monitoring System Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
Global Data Center Transformer Market
Power Systems
South America Battery Management System Market