
 Wi-Fi Chipset Market | 2026-2036
Wi-Fi Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Chipset Market Analysis
The EU Green Deal's embodied carbon reporting requirements for electronics is broadening procurement criteria across European telecom operators and enterprise buyers. Qualcomm Technologies Inc. leverages its integrated modem-RF platform to sustain design wins across premium smartphone tiers. Broadcom Inc. anchors supply for enterprise access points through vertical control over Wi-Fi 7 reference designs. MediaTek Inc. competes aggressively in mid-range IoT modules where cost-optimized dual-band architectures dominate bill-of-material decisions.
A Wi-Fi chipset integrates baseband processors, radio transceivers, and media access control layers into a single silicon package operating across 2.4 GHz, 5 GHz, and 6 GHz bands with throughput specifications scaling from 1 Gbps to over 30 Gbps. These devices enable wireless local area network connectivity in consumer, enterprise, and industrial environments by converting digital data streams into modulated radio signals compliant with IEEE 802.11 protocols. Tri-band and Wi-Fi 7 segments command premium positioning as enterprise buyers prioritize deterministic latency for augmented reality and real-time automation workloads. Combo chipsets that merge Bluetooth and Wi-Fi on single die attract design wins in smart home devices where board space constraints dominate hardware engineering tradeoffs.
The FCC governs spectrum allocation and device certification through Part 15 rules that dictate permissible output power and channel access protocols for 6 GHz unlicensed operation. ETSI harmonizes European conformance requirements under EN 303 687 for Wi-Fi 6E, while China's MIIT administers type approval and GB standards for domestic radio transmission equipment. Japan's MIC and South Korea's MSIT maintain parallel certification regimes that fragment go-to-market timelines for new radio architectures. Stakeholders must monitor regulatory harmonization progress across these jurisdictions to anticipate design validation costs and first-mover positioning in emerging spectrum bands.
Market Dynamics
Enterprise wireless infrastructure upgrades across manufacturing campuses are accelerating procurement of Wi-Fi 6E and Wi-Fi 7 chipsets, while the FCC's 6 GHz spectrum allocation opened contiguous bandwidth for low-latency industrial applications. China, South Korea, and Taiwan dominate fabrication capacity for advanced radio-frequency front-end modules.
Growth Catalysts
- 6 GHz Spectrum Allocation:The FCC's Part 15 rules for unlicensed 6 GHz operation unlocked contiguous bandwidth for augmented reality and real-time automation workloads in manufacturing environments.
- Enterprise Campus Modernization:Manufacturing facilities are replacing legacy Wi-Fi 5 infrastructure with Wi-Fi 6E and Wi-Fi 7 chipsets to support deterministic latency requirements for robotic control systems.
- Radio-FFront-End Module Concentration:Taiwan and South Korea fabrication clusters provide cost-competitive supply for tri-band architectures serving premium smartphone and access point tiers.
Market Restraints
- Advanced Node Wafer Costs:7nm and 5nm process nodes for baseband processors carry significant foundry premiums that compress margins on mid-range IoT modules.
- Geographic Supply Concentration:Taiwan's dominance in RF front-end module fabrication creates vulnerability to seismic and geopolitical disruption for the entire Wi-Fi chipset supply chain.
- Power Amplifier Efficiency Limits:Gallium arsenide power amplifiers face thermal constraints at 6 GHz that restrict output power and range for battery-operated devices.
Strategic Opportunities
- EU Green Deal Compliance:The EU Green Deal's embodied carbon reporting requirements for electronics is broadening procurement criteria across European telecom operators and enterprise buyers seeking lower-carbon chipsets.
- Industrial IoT Convergence:Integration of Wi-Fi 7 with Time-Sensitive Networking protocols creates deterministic wireless backhaul for smart factory sensor arrays and automated guided vehicles.
- Combo Chipset Expansion:Single-die Wi-Fi and Bluetooth integration attracts design wins in smart home devices where board space constraints dominate hardware engineering tradeoffs.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Japan's MIC, South Korea's MSIT, and China's MIIT maintain parallel type approval regimes that fragment go-to-market timelines for new radio architectures.
- Legacy Infrastructure Integration:Enterprise buyers face complex migration paths from Wi-Fi 5 to Wi-Fi 6E/7 requiring controller upgrades and client device refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Chipset Market |
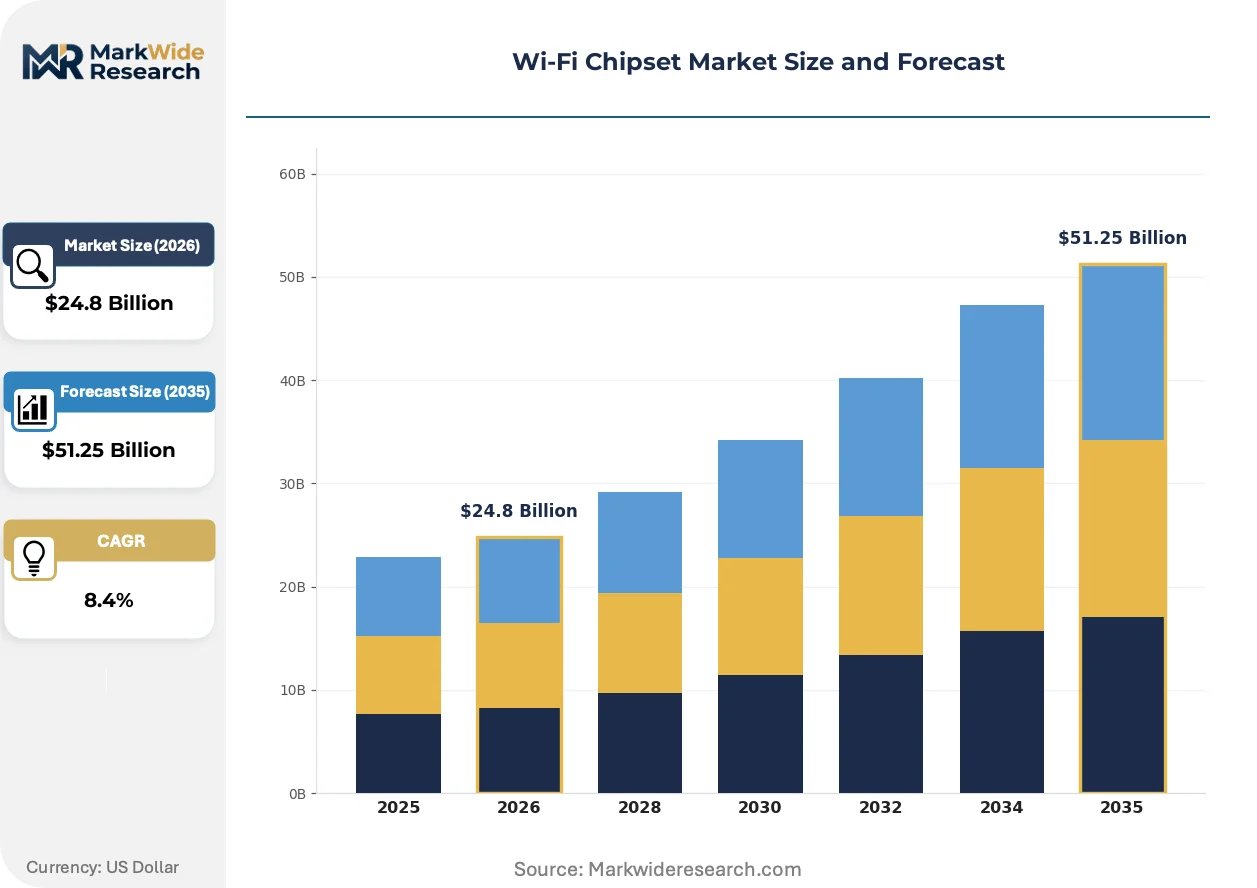
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual-Band, Tri-Band, Single-Band, Combo Chipset Application: Smartphones, Laptops, Smart Home Devices, IoT Applications Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7 End User: Consumer Electronics, Telecommunications, Automotive, Industrial |
| Companies Covered | Intel Corporation, NXP Semiconductors N.V., Qualcomm Technologies Inc., Realtek Semiconductor Corporation, STMicroelectronics N.V., Broadcom Inc., Texas Instruments Incorporated, Marvell Technology, Inc., MediaTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Chipset Market Emerging Trajectories
Wi-Fi 7's 320 MHz channel bonding and 4K-QAM modulation are rewriting throughput ceilings for enterprise wireless, while regulatory harmonization efforts across major economies seek to streamline 6 GHz device certification. These forces are compressing product development cycles and reshaping competitive positioning among chipset vendors.
Wi-Fi 7's Multi-Link Operation enables simultaneous transmission across 2.4 GHz, 5 GHz, and 6 GHz bands to aggregate bandwidth and reduce latency. Enterprise access point manufacturers are adopting this capability aggressively for campus environments serving augmented reality headsets and real-time video analytics. This is rewriting performance benchmarks for wireless backhaul, forcing incumbent Wi-Fi 6E designs into mid-tier positioning.
The EU's EN 303 687 harmonization for Wi-Fi 6E conformance is creating a template for 6 GHz device certification that other regulators are referencing. ETSI's framework reduces testing redundancy for manufacturers seeking multi-country approval. European telecom operators are leveraging this regulatory clarity to accelerate 6 GHz infrastructure deployment ahead of markets with fragmented approval processes.
Enterprise procurement teams are consolidating vendor relationships around integrated modem-RF platforms that reduce qualification overhead. Manufacturing buyers favor chipsets with pre-certified reference designs that accelerate time-to-production for industrial wireless access points. This pattern is most visible in Germany and Japan, where automotive and precision manufacturing sectors prioritize supply chain simplification over component-level cost optimization.
Wi-Fi Chipset Market Segmentation
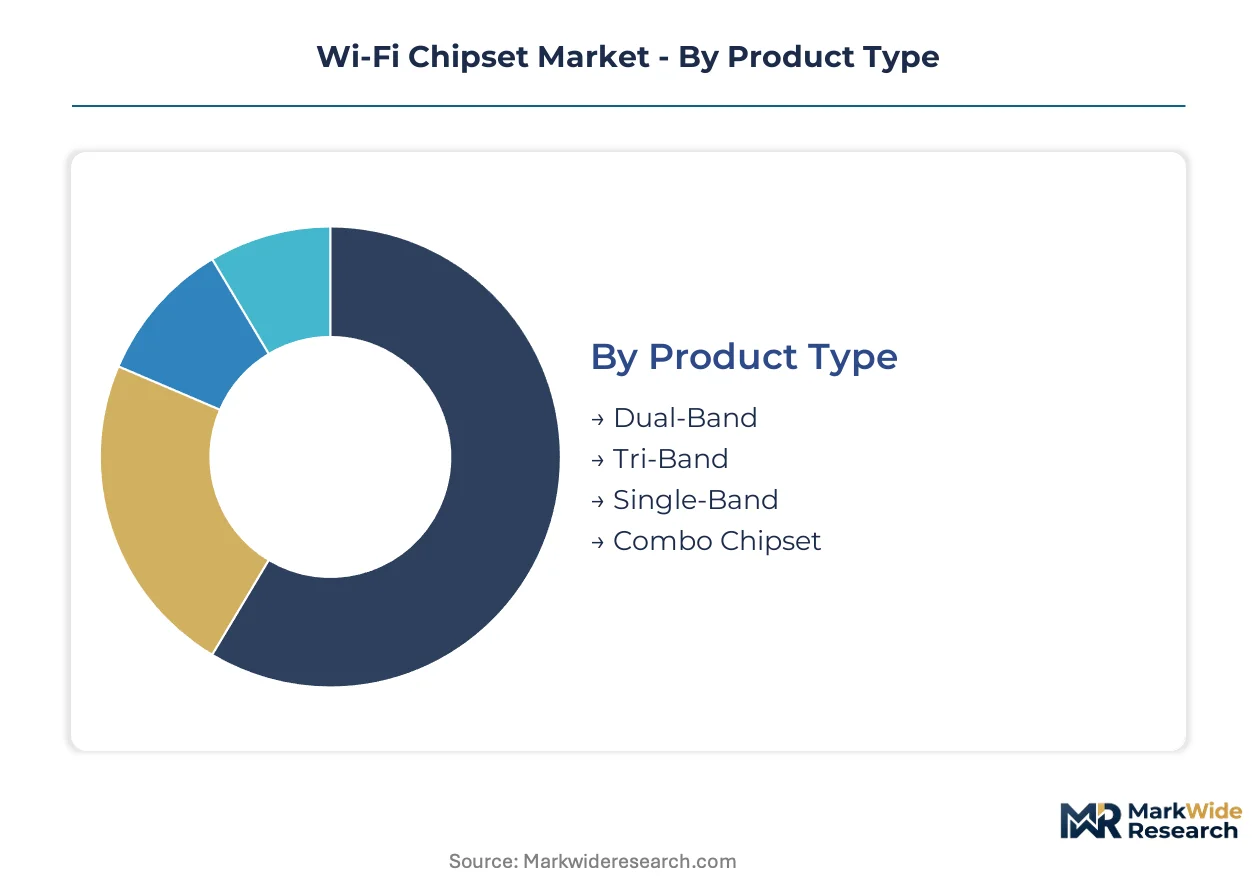
Wi-Fi chipset segmentation reveals how technical specifications, deployment environments, and buyer procurement criteria fragment demand across divergent price-performance tiers. Product architecture choices directly constrain which frequency bands, throughput ceilings, and power budgets engineers can access.
Product Type:
Cost tier and board space constraints drive divergent silicon integration strategies across consumer and enterprise buyers.
- Dual-Band:Operates across 2.4 GHz and 5 GHz spectrum with integrated MAC and baseband processors on single die. Mid-range smartphones and mainstream laptops in China and India concentrate procurement here, constrained by bill-of-material ceilings that exclude 6 GHz support.
- Tri-Band:Adds 6 GHz capability alongside 2.4 GHz and 5 GHz for Wi-Fi 6E and Wi-Fi 7 compliance. Enterprise access point manufacturers in Germany and Japan prioritize this architecture for campus deployments serving augmented reality headsets and automated guided vehicles.
- Single-Band:Legacy 2.4 GHz-only designs persist in cost-optimized IoT sensors where throughput demands remain minimal.
- Combo Chipset:Integrates Wi-Fi and Bluetooth transceivers on unified silicon to reduce board footprint and qualification overhead for smart home devices.
Dual-Band leads volumes today; Tri-Band is gaining share fastest.
Application:
End-use performance requirements determine which IEEE protocol generations and channel bandwidths buyers can justify.
- Smartphones:Premium tiers demand Wi-Fi 7 with 320 MHz channel bonding and 4K-QAM modulation for low-latency cloud gaming and high-resolution video streaming. Qualcomm's integrated modem-RF platforms dominate design wins here.
- Laptops:Enterprise procurement teams specify Wi-Fi 6E minimum for hybrid work deployments, with Wi-Fi 7 emerging in mobile workstation segments requiring deterministic wireless backhaul.
- Smart Home Devices:Combo chipsets with Bluetooth LE integration attract thermostat, security camera, and voice assistant manufacturers prioritizing compact PCB layouts.
- IoT Applications:Industrial sensor networks and agricultural monitoring systems specify sub-gigahertz or 2.4 GHz-only variants where battery life trumps throughput.
Smartphones lead volumes today; IoT Applications are expanding most quickly.
Technology:
Protocol generation migration timelines fragment procurement across installed base refresh cycles and greenfield deployments.
- Wi-Fi 5:IEEE 802.11ac designs with 80 MHz channel width and 256-QAM modulation remain entrenched in legacy enterprise infrastructure and budget consumer routers.
- Wi-Fi 6:OFDMA and 1024-QAM improvements target high-density environments; still dominant in mid-range smartphones and access points shipping to Latin American and Southeast Asian markets.
- Wi-Fi 6E:Extends Wi-Fi 6 into 6 GHz spectrum with 160 MHz channels; FCC Part 15 rules in the United States and ETSI EN 303 687 in Europe enabled commercial deployment for campus and industrial use cases.
- Wi-Fi 7:Multi-Link Operation across 2.4 GHz, 5 GHz, and 6 GHz simultaneously with 320 MHz bonding and 4K-QAM; premium smartphones and enterprise access points in South Korea and Taiwan are first adopters.
Wi-Fi 6 leads volumes today; Wi-Fi 7 is climbing the fastest.
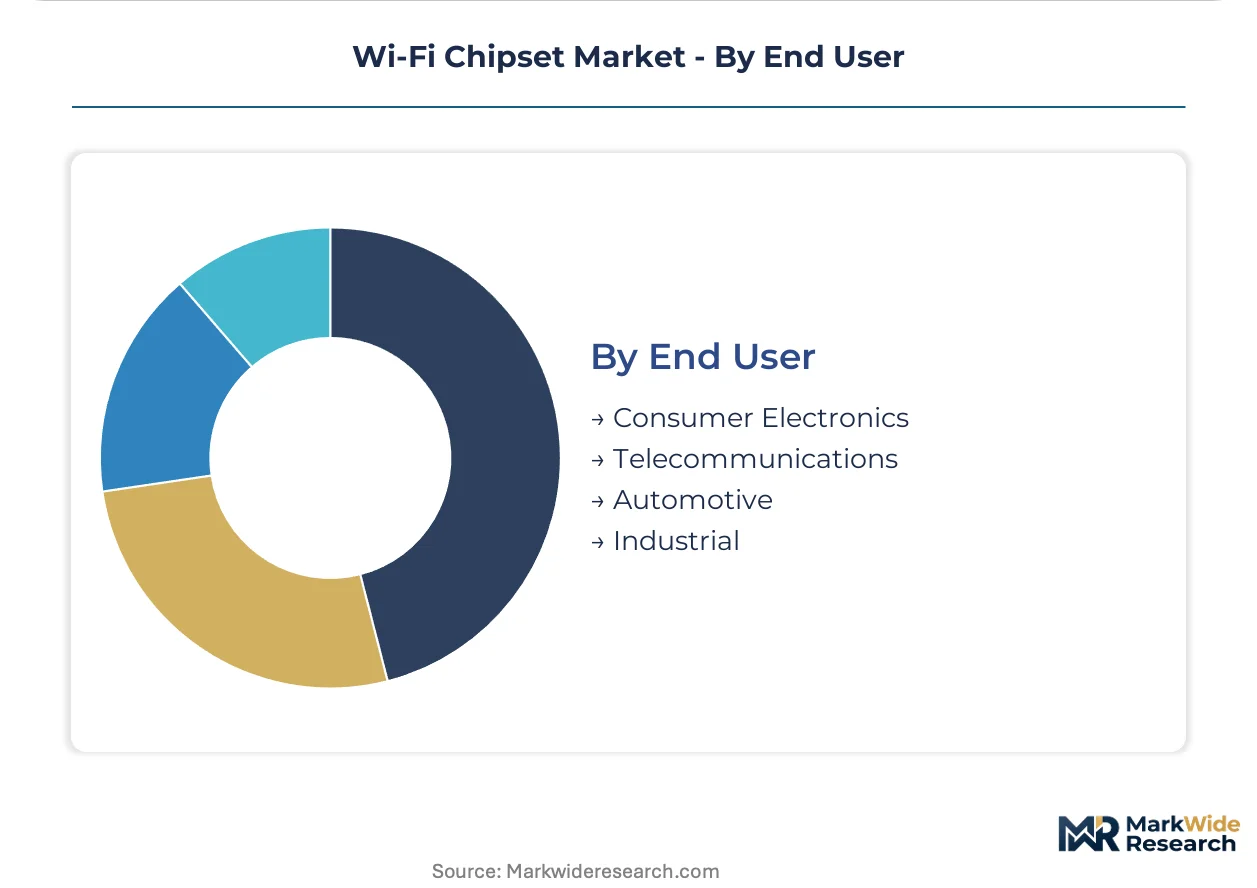
End User:
Certification complexity and supply chain reliability requirements separate consumer from industrial procurement patterns.
- Consumer Electronics:Smartphone OEMs and laptop manufacturers drive the largest absolute volumes, with procurement concentrated around annual product refresh cycles and cost-optimized reference designs.
- Telecommunications:Carriers specify carrier-grade Wi-Fi 6E and Wi-Fi 7 for residential gateways and mesh systems, with pre-certification requirements extending qualification timelines.
- Automotive:Infotainment and telematics modules demand AEC-Q100 qualified chipsets with extended temperature ranges; Wi-Fi 6 dominates current design wins while Wi-Fi 7 trials proceed for autonomous vehicle data offload.
- Industrial:Manufacturing facilities prioritize deterministic latency and Time-Sensitive Networking integration for robotic control; procurement favors vendors with pre-certified industrial reference designs.
Consumer Electronics leads volumes today; Industrial is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF design engineers cluster in Hsinchu Science Park, Seoul's Pangyo Techno Valley, and San Diego's telecom corridor anchor the industry's geographic footprint. These talent concentrations drive process node migration and protocol standardization timelines.
United States
Enterprise campus modernization and defense contractor demand for secure wireless backhaul propel chipset procurement. The FCC's Part 15 rules governing 6 GHz unlicensed spectrum enable low-latency industrial deployments. San Diego hosts Qualcomm Technologies Inc.'s integrated modem-RF platform development, while Austin's semiconductor corridor attracts Wi-Fi 7 reference design teams.
China
Domestic smartphone OEMs and smart home device manufacturers drive dual-band and combo chipset volumes. MIIT administers type approval and GB standards certification for radio transmission equipment. Shanghai and Shenzhen fabrication clusters produce cost-optimized IoT modules for export markets across Southeast Asia and Africa.
South Korea
Samsung Electronics and LG Electronics smartphone divisions anchor premium-tier Wi-Fi 7 adoption. MSIT maintains parallel certification regimes for new radio architectures that fragment go-to-market timelines. Seoul's Pangyo Techno Valley concentrates RF front-end module design houses serving tri-band access point manufacturers.
Taiwan
TSMC's advanced node capacity supports baseband processor production for global fabless designers. The National Communications Commission harmonizes 6 GHz device standards with regional counterparts. Hsinchu Science Park hosts MediaTek Inc.'s mid-range IoT module development and Realtek Semiconductor Corporation's reference design teams.
Germany
Automotive infotainment and industrial automation sectors demand AEC-Q100 qualified chipsets with deterministic latency. The EU Green Deal's embodied carbon reporting requirements broaden procurement criteria for lower-carbon chipsets. Munich and Stuttgart engineering centers specify pre-certified industrial reference designs for robotic control systems.
Wi-Fi Chipset Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the Wi-Fi chipset landscape. Foundry-dependent fabless vendors dominate protocol innovation while integrated device manufacturers retain captive capacity for premium-tier production. The market structure stratifies into three archetypes: integrated platform vendors, discrete RF specialists, and cost-optimized module suppliers. Consolidation pressures intensify as enterprise buyers consolidate vendor relationships around pre-certified reference designs.
Within the integrated platform tier, Qualcomm Technologies Inc. and Broadcom Inc. occupy positions exemplifying modem-RF convergence strategies. MediaTek Inc. anchors the cost-optimized module segment where dual-band architectures dominate bill-of-material decisions. These three companies represent divergent responses to enterprise procurement patterns favoring supply chain simplification over component-level cost optimization.
| Leading Market Players |
|---|
| Intel Corporation |
| NXP Semiconductors N.V. |
| Qualcomm Technologies Inc. |
| Realtek Semiconductor Corporation |
| STMicroelectronics N.V. |
| Broadcom Inc. |
| Texas Instruments Incorporated |
| Marvell Technology, Inc. |
| MediaTek Inc. |
| Others |
Supply Flow & Price Mechanics
Captive foundry partnerships anchor supply positioning and pricing power for Wi-Fi chipset vendors serving premium smartphone and enterprise access point tiers. Taiwan Semiconductor Manufacturing Company's advanced node capacity underpins baseband processor costs while South Korean RF front-end module fabrication shapes tiered pricing across tri-band architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi 7 with Multi-Link Operation from Wi-Fi 6E tri-band and legacy dual-band alternatives. Certification grade under AEC-Q100 automotive standards and volume scale drive price differentiation, with industrial buyers absorbing premiums for deterministic latency guarantees. Cost compression in mid-range IoT modules intensifies because 7nm and 5nm wafer foundry premiums compress margins. Smartphone OEMs exhibit highest price sensitivity, while German automotive and Japanese precision manufacturing buyers prioritize supply chain reliability over component-level cost optimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Samsung Electronics and Apple procurement teams, while distributor networks serve mid-tier IoT module manufacturers across Southeast Asia. Taiwan, South Korea, and China concentrate fabrication capacity for advanced radio-frequency front-end modules and baseband processors. Supply chains draw from gallium arsenide substrate suppliers, 300mm silicon wafer foundries, and 6 GHz filter component specialists. Single-source vulnerability around Taiwan's seismic and geopolitical risk exposure threatens continuity for global Wi-Fi chipset availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi chipset market reads as a late-cycle quality story as enterprise buyers shift procurement criteria toward Wi-Fi 7's deterministic latency specifications for augmented reality and real-time automation workloads.
For Market Incumbents: Deploy pre-certified reference design programs to lock in enterprise access point manufacturers and automotive Tier 1 suppliers before second-source qualification completes. Threat from MediaTek's cost-optimized dual-band architectures intensifies margin pressure in mid-range IoT modules. Capacity addition in South Korean RF front-end module fabrication secures supply continuity against Taiwan concentration risk.
For New Entrants and Emerging Players: Begin with industrial IoT sensor networks specifying sub-gigahertz or 2.4 GHz-only variants where incumbent reference design investments remain minimal. Agricultural monitoring systems and smart building environmental controls represent penetrable white-space segments. Channel partnership with European telecom operators seeking EU Green Deal-compliant lower-carbon chipset suppliers offers go-to-market leverage.
For Investors and Strategic Acquirers: Roll-up economics work for mid-range IoT module specialists because enterprise procurement consolidation around integrated modem-RF platforms is displacing discrete component vendors. Long-term viability hinges on Wi-Fi 7 adoption velocity across industrial automation and automotive telematics. Signal to watch: FCC Part 15 rule modifications expanding 6 GHz power limits for outdoor industrial deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Qualcomm's modem-RF convergence reduces qualification overhead for premium smartphone OEMs. |
| Strategic Partnership | Enterprise access point manufacturers favor vendors with pre-certified industrial reference designs. |
| Acquisition of Specialist Firm | RF front-end module design houses in Pangyo Techno Valley command scarcity premiums. |
| Geographic Expansion | EU Green Deal compliance investments open procurement channels with European telecom operators. |
| Product Launch | Wi-Fi 7 Multi-Link Operation adoption rewrites performance benchmarks for wireless backhaul. |
Methodological Framework
Direct dialogue with RF design engineers, enterprise procurement managers, semiconductor foundry planning officers, and carrier equipment qualification leads grounded qualitative findings in operational reality. Secondary validation drew from FCC Part 15 rulemaking dockets, ETSI EN 303 687 conformance documentation, MIIT type approval filings, and SEC 10-K semiconductor segment disclosures. Bottom-up bill-of-material analysis across dual-band, tri-band, and combo chipset architectures triangulated with top-down market sizing.
Segment-level projections across product type, application, technology generation, and end-user category fed into analytical framework spanning the projection horizon. Modeled dimensions included IEEE protocol generation migration timelines, foundry node transition schedules, and regional regulatory harmonization progress. CAGRs derived from regression analysis against historical smartphone refresh cycles, enterprise infrastructure replacement rates, and industrial automation capital expenditure patterns. Wi-Fi 7 penetration assumptions and 6 GHz spectrum allocation timelines served as key forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory spectrum reallocations, seismic disruption to Taiwan fabrication clusters, and breakthrough substitution technologies. Forecasts reflect documented assumptions about enterprise buyer procurement consolidation and foundry capacity expansion schedules. Periodic stress-testing of base assumptions is recommended given geopolitical volatility affecting RF front-end module supply continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Micro Server IC Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
DNA Sequencing Chip Market