
 Laptop Panels Market | 2026-2036
Laptop Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Laptop Panels Market Analytics
OEM-direct procurement is fragmenting as notebook brands diversify sourcing away from single-supplier LCD contracts. Samsung Display leverages its OLED pilot lines in South Korea to capture premium-tier notebook assignments. BOE Technology anchors massive Gen 8.6 capacity in China and competes aggressively on cost for mainstream IPS volumes. AU Optronics specializes in high-refresh gaming panels and sustains margins through narrow SKU focus.
Laptop panels are thin-film transistor liquid-crystal or organic-emitting-diode display modules, typically 0.3–1.2 mm in cell thickness, bonded with driver integrated circuits and backlight units to render visual output for portable computing devices. IPS technology dominates volume shipments due to color accuracy requirements in business and creative workflows, while OLED commands the fastest value growth as burn-in mitigation improves and gaming brands spec emissive displays. The 15-inch size band occupies the largest revenue pool, though 17-inch and 20-inch segments are expanding with desktop-replacement gaming chassis and mobile workstation form factors.
China's MIIT enforces GB 21520 display energy efficiency standards that constrain backlight power budgets and favor lower-wattage panel designs. REACH and RoHS in Europe restrict hazardous substances in driver IC packaging and backlight phosphor chemistry, elevating compliance costs for panel makers serving EU-bound notebook brands. Stakeholders must monitor how OLED inkjet-printing scale-up and oxide-TFT backplane yields reshape the cost curve between emissive and LCD architectures.
Market Dynamics
GB 21520 energy efficiency standards from China's MIIT are forcing panel makers to redesign backlight architectures and driver IC power budgets, compressing margins on mainstream IPS volumes while accelerating OLED adoption in premium tiers.
Growth Catalysts
- Gaming Display Specifications:High-refresh-rate panels above 165 Hz are becoming standard requirements for esports-tier notebooks, pulling procurement toward advanced IPS and OLED cell technologies.
- REACH Substance Restrictions:European regulations on hazardous materials in driver IC packaging and backlight phosphors are elevating compliance costs but also creating competitive separation for certified suppliers.
- Assembly Migration to Vietnam:Final notebook production lines relocating from coastal China to northern Vietnam are reshaping regional logistics and panel inventory positioning.
Market Restraints
- OLED Burn-In Risk:Static UI elements in productivity software create persistent image retention concerns that limit OLED penetration in commercial fleet deployments.
- Driver IC Supply Concentration:Taiwan and South Korea dominate display driver semiconductor fabrication, creating vulnerability to geopolitical disruption or foundry allocation shifts.
- GB Standard Compliance Costs:China's tightening display energy efficiency mandates require expensive backlight redesigns and power management firmware updates for legacy panel SKUs.
Strategic Opportunities
- India Domestic Manufacturing:PLI scheme incentives for electronics assembly are attracting panel bonding and module integration investments to serve South Asian demand.
- Foldable Notebook Form Factors:OLED flexible substrate technology is converging with hinge mechanics from smartphone supply chains to enable new convertible designs.
- Mexico Nearshoring Demand:Notebook brands serving US enterprise customers are qualifying panel suppliers for direct shipment to Guadalajara and Tijuana assembly plants.
Industry Challenges
- Oxide-TFT Yield Engineering:Migration to indium-gallium-zinc-oxide backplanes for OLED and high-refresh LCD requires scarce semiconductor process expertise and extended fab qualification timelines.
- Dual-Carbon Reporting Burden:China's MEE enforcement of corporate carbon disclosure rules is adding documentation overhead to panel makers serving domestic notebook brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laptop Panels Market |
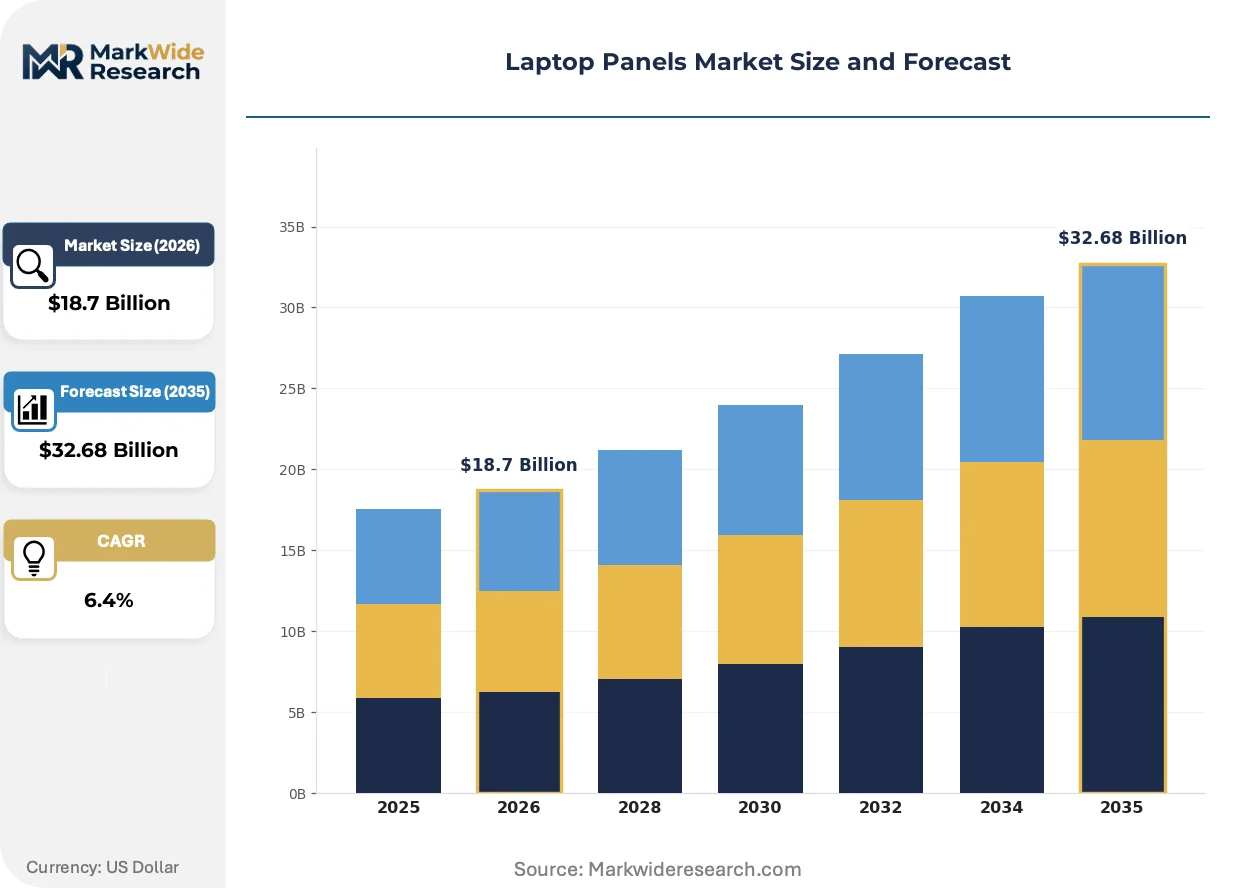
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IPS, TN, VA, OLED Size: 13-inch, 15-inch, 17-inch, 20-inch Technology: Touchscreen, Non-Touchscreen, Anti-Glare, Anti-Reflection Application: Gaming, Business, Personal Use, Educational |
| Companies Covered | Samsung Display, LG Display, BOE Technology, Innolux Corporation, AU Optronics, Sharp, Tianma Microelectronics, TCL CSOT, JDI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laptop Panels Market Evolving Landscape
Display technology is fragmenting across multiple performance tiers simultaneously, with liquid-crystal and organic-emitting architectures evolving on parallel tracks rather than simple substitution. Panel makers must now optimize for three distinct buyer constituencies: cost-sensitive fleet procurement, color-critical creative workflows, and latency-obsessed gaming segments.
Hybrid LCD-OLED stack architectures are hybridizing to bridge cost and performance gaps. BOE Technology and other Chinese panel makers are developing dual-cell LCD structures with mini-LED backlights that approximate OLED contrast at lower price points. Gaming notebook brands are qualifying these panels for mid-tier SKUs where full OLED remains prohibitively expensive. The technology is hybridizing the competitive landscape by creating a viable intermediate tier between mainstream IPS and premium emissive displays.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in semiconductor etching and cleaning processes essential to TFT backplane fabrication. Panel makers serving EU-bound notebook brands must qualify alternative chemistries or absorb carbon credit costs. Display foundries in Taiwan and South Korea are most affected, with some redirecting fluorinated gas-dependent processes to lines serving non-European customers.
Direct-to-OEM panel procurement is displacing traditional distributor intermediaries in high-volume notebook segments. Dell, HP, and Lenovo are negotiating annual cell supply agreements directly with Samsung Display, BOE, and AU Optronics, bypassing regional panel traders. This pattern is most visible in Vietnam and Mexico, where assembly plant proximity enables just-in-time delivery models that eliminate inventory carrying costs for middlemen.
Laptop Panels Market Segmentation
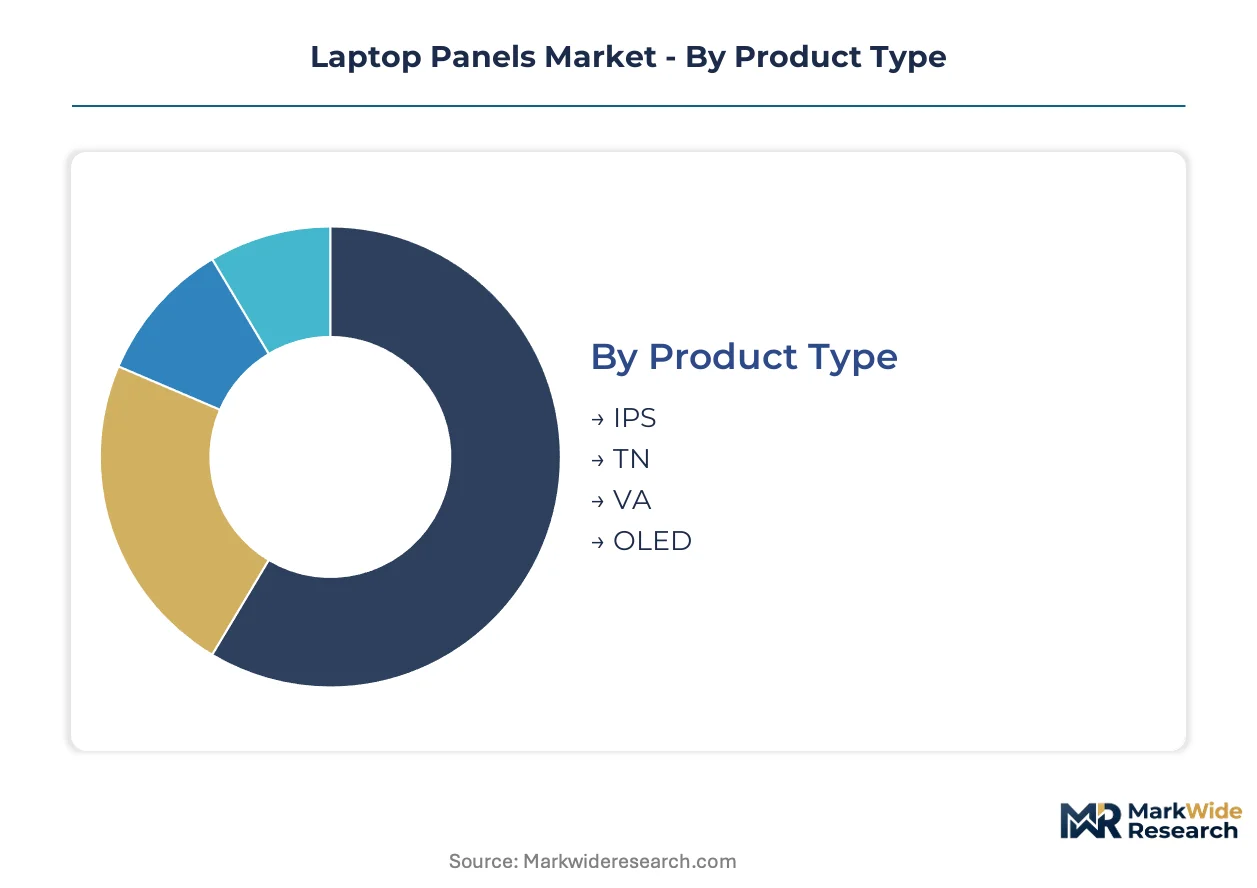
Panel procurement decisions fragment across four distinct dimensions. Technology choices determine power budgets and color performance. Size bands align with chassis thermal limits and mobility requirements. End-use applications impose divergent refresh rate and durability specifications.
Product Type:
Cost tier separates emissive from liquid-crystal architectures, with premium positioning commanding fundamentally different supply chains and margin structures.
- IPS:In-plane switching cells rotate liquid crystals parallel to the substrate, delivering 178-degree viewing angles and sRGB color gamut coverage. Business fleet procurement in Vietnam and Mexico concentrates here, constrained by GB 21520 power budgets forcing backlight redesigns.
- OLED:Organic light-emitting diode stacks deposit red, green, and blue emissive layers on thin-film transistor backplanes, achieving true blacks and sub-millisecond response times. Gaming brands from ASUS to Razer are pulling procurement upward as burn-in mitigation improves.
- TN:Twisted nematic cells twist liquid crystals 90 degrees between substrates, offering the lowest manufacturing cost among active-matrix technologies. Entry-level educational notebooks in India leverage TN panels under PLI scheme cost pressures.
- VA:Vertical alignment cells tilt liquid crystals perpendicular to substrates, delivering contrast ratios between IPS and OLED at mid-tier price points. Desktop-replacement chassis in the 17-inch band favor VA for multimedia consumption.
IPS holds installed capacity. OLED is rotating up the share rankings.
Size:
Volume concentration follows chassis thermal design power and battery chemistry constraints, with mobility-application trade-offs defining each band's procurement profile.
- 15-inch:The dominant revenue pool balances screen real estate against portable weight limits. Business and creative workflows standardize here, with BOE Technology and AU Optronics competing aggressively for mainstream notebook brand allocation.
- 17-inch:Desktop-replacement gaming chassis and mobile workstations expand this segment through enhanced thermal headroom. Assembly plants in Guadalajara and Tijuana are qualifying direct panel shipments for US-bound gaming SKUs.
- 13-inch:Ultraportable form factors prioritize battery endurance over display area. REACH and RoHS compliance costs in Europe elevate panel selection scrutiny for corporate fleet deployments.
- 20-inch:Emerging mobile workstation category pushes panel mechanics and hinge engineering limits. Foldable OLED substrate technology from smartphone supply chains is converging with this unconventional form factor.
15-inch maintains procurement dominance. 17-inch is climbing the fastest among size bands.
Technology:
Surface treatment and input modality create four distinct specification tiers with overlapping but non-identical buyer constituencies.
- Touchscreen:Capacitive sensor layers bonded to the cell stack enable direct input interaction. Educational and business convertible designs concentrate demand, with Windows 11 gesture requirements accelerating integration.
- Non-Touchscreen:Standard cell-glass construction without digitizer layers maximizes brightness and minimizes cost. Gaming notebooks prioritize this configuration for weight reduction and thermal dissipation.
- Anti-Glare:Matte surface etching diffuses ambient light reflection for office environments. China's MIIT energy efficiency standards favor lower-wattage backlight designs compatible with anti-glare transmission losses.
- Anti-Reflection:Multi-layer optical coatings suppress specular reflection without sacrificing clarity. Color-critical creative workflows in European markets specify anti-reflection for daylight editing conditions.
Non-Touchscreen holds volume leadership. Touchscreen is gaining share fastest through convertible adoption.
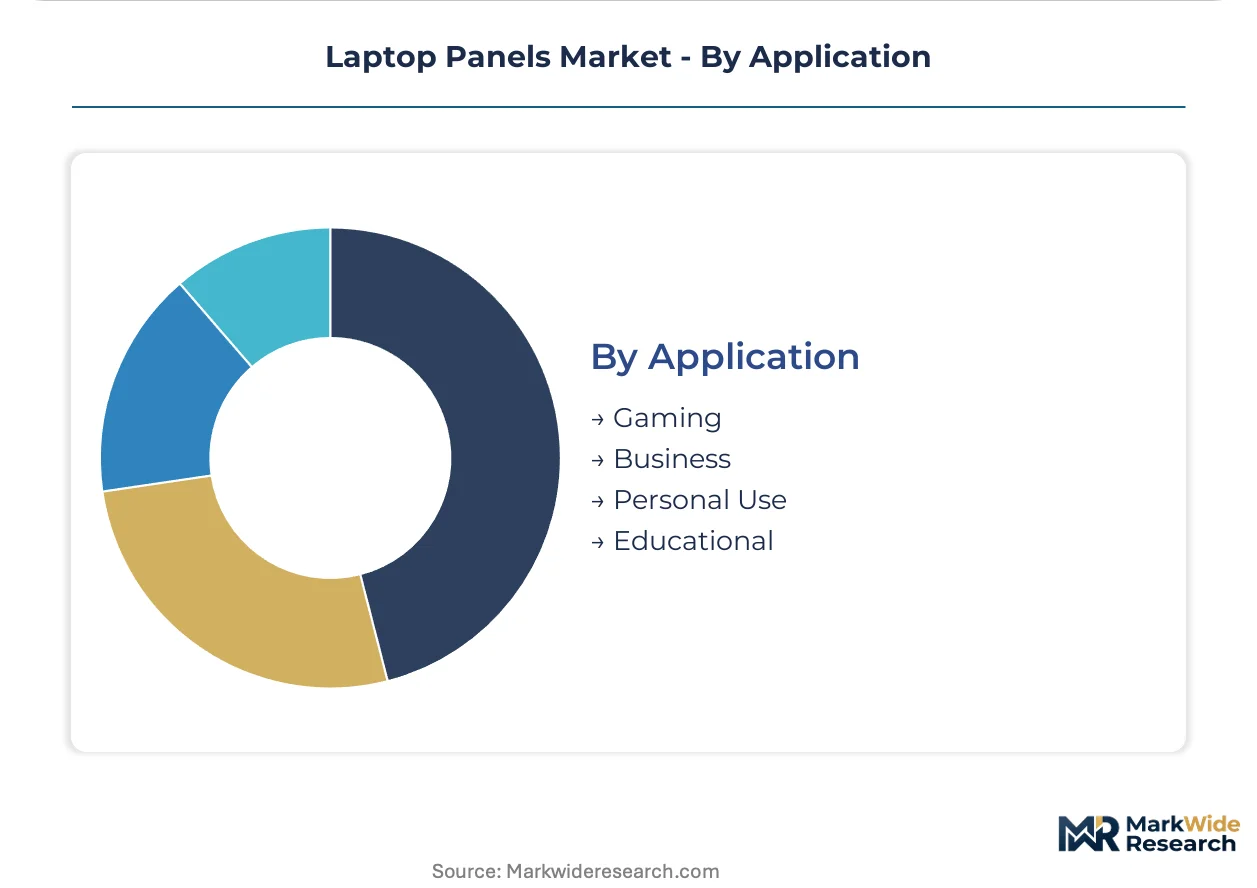
Application:
End-use requirements diverge sharply on refresh rate, color accuracy, and durability specifications, fragmenting panel maker R&D allocation.
- Gaming:Esports-tier specifications demand 165 Hz and above refresh rates with sub-3ms gray-to-gray response. High-refresh IPS and OLED procurement is concentrating among specialized panel makers with oxide-TFT backplane expertise.
- Business:Fleet procurement prioritizes color consistency, power efficiency, and multi-year availability guarantees. GB 21520 compliance is forcing backlight architecture redesigns for legacy IPS SKUs serving this segment.
- Personal Use:Consumer retail channels balance price sensitivity against streaming and casual gaming requirements. Mini-LED backlight dual-cell LCD structures from BOE Technology are penetrating this cost-conscious tier.
- Educational:K-12 and higher institutional procurement emphasizes durability, anti-microbial surfaces, and aggressive cost targets. India's PLI scheme incentives are attracting module integration investments to serve South Asian educational demand.
Business commands procurement volume. Gaming shows the steepest expansion trajectory among application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen-Hong Kong-Macau Bridge and adjacent port infrastructure anchor Guangdong Province's role in panel logistics, while Vietnam's Lach Huyen deep-water port in Hai Phong enables direct deep-sea container access for northern assembly zones. These maritime assets determine how display cells flow from Korean and Chinese fabs to final notebook configuration.
China
BOE Technology anchors massive Gen 8.6 fabrication capacity in Hefei and Wuhan, serving both domestic notebook brands and export-bound assembly. MIIT's GB 21520 energy efficiency standards force backlight power budget redesigns across legacy IPS volumes. The Yangtze River Delta cluster around Suzhou and Kunshan concentrates driver IC packaging and module bonding operations for Dell and HP procurement.
Vietnam
Final assembly migration from coastal China pulls panel inventory positioning toward northern industrial zones. Samsung Display and BOE Technology are qualifying direct cell shipments to Bac Ninh and Thai Nguyen plants serving ASUS and Lenovo gaming SKUs. The Lach Huyen port development eliminates transshipment through Hong Kong for deep-sea routes to US West Coast distribution.
South Korea
Samsung Display leverages OLED pilot lines in Tangjeong to capture premium-tier notebook assignments from Razer and other gaming brands. The country's display semiconductor ecosystem dominates oxide-TFT backplane expertise, creating scarcity value in high-refresh panel supply. REACH substance restrictions from European procurement are elevating compliance documentation requirements for driver IC packaging exports.
Mexico
Guadalajara and Tijuana assembly plants serving US enterprise customers are qualifying direct panel supplier relationships to bypass distributor intermediaries. The Guadalajara electronics corridor concentrates Dell and HP configuration operations for North American commercial fleet deployment. Nearshoring demand from notebook brands is reshaping logistics patterns away from Asia-Pacific transshipment.
India
PLI scheme incentives for electronics assembly are attracting panel bonding and module integration investments to serve South Asian educational and consumer demand. Tamil Nadu and Karnataka states host emerging configuration operations for entry-level notebook SKUs. BIS certification requirements for display modules are creating qualification timelines that favor established suppliers with compliance infrastructure.
Laptop Panels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, with the laptop panels market consolidating around a handful of display foundries that control critical TFT backplane and OLED deposition capacity. Three archetypes define competitive positioning: Korean OLED specialists leveraging emissive technology leadership, Chinese scale players optimizing Gen 8.6+ line economics, and Taiwanese high-refresh specialists maintaining margin through narrow SKU focus. Capacity expansion and direct-to-OEM procurement agreements constitute the dominant competitive moves, displacing traditional distributor intermediaries in high-volume segments.
Within the Korean specialist tier, Samsung Display and LG Display occupy positions defined by OLED pilot line heritage and vertical integration into semiconductor backplane fabrication. BOE Technology anchors the Chinese scale-driven archetype, with its Hefei and Wuhan fab complexes exemplifying the cost-optimization model for mainstream IPS volumes. AU Optronics represents the Taiwanese high-refresh specialist archetype, sustaining positioning through concentrated gaming panel expertise rather than portfolio breadth.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| BOE Technology |
| Innolux Corporation |
| AU Optronics |
| Sharp |
| Tianma Microelectronics |
| TCL CSOT |
| JDI |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese Gen 8.6 fabs is compressing spot pricing for mainstream IPS volumes while tightening supply discipline among Korean OLED specialists. BOE Technology's aggressive capacity utilization targets force rival panel makers to absorb margin erosion or cede share in Vietnam and Mexico assembly corridors.
Pricing Analysis
Volume-discount tiering structures separate annual offtake agreements from spot procurement. Dell and HP negotiate contract pricing anchored to 500K+ unit commitments with direct-to-OEM suppliers. Price differentiation rests on GB 21520 compliance certification and oxide-TFT backplane yields. Cost compression in mainstream IPS tiers is intensifying because Chinese scale players prioritize utilization over margin. Educational procurement in India shows highest price sensitivity; gaming brands spec'ing OLED panels demonstrate lowest.
Supply Chain Analysis
Export-control regimes limiting advanced lithography equipment flows to Chinese fabs are constraining oxide-TFT backplane expansion timelines. Panel supply concentrates in China, South Korea, and Taiwan. Manufacturing draws from indium and gallium feedstocks for IGZO deposition, plus driver IC silicon from foundry partners. Single-source vulnerability in Taiwan and South Korean driver IC fabrication creates geopolitical exposure. Distribution runs through direct OEM agreements displacing regional panel traders in Vietnam and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating as Dell, HP, and Lenovo negotiate direct annual cell supply agreements, fragmenting supplier pricing leverage across fewer procurement decision-makers.
For Market Incumbents: Entrench oxide-TFT backplane expertise through captive semiconductor process development in South Korea or Taiwan. Defend margin position by qualifying foldable OLED substrate capacity before smartphone supply chain convergence accelerates. GB 21520 compliance infrastructure represents a certification moat against Chinese scale players prioritizing cost over efficiency redesigns. For New Entrants and Emerging Players: Build out module bonding and integration capacity in Tamil Nadu or Karnataka under India's PLI scheme incentives. Educational notebook procurement in South Asia offers the most penetrable volume tier given aggressive institutional cost targets and BIS certification barriers that favor new local investments. Pursue direct relationships with Indian OEMs assembling entry-level SKUs for K-12 deployment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among panel makers with gaming-specialist positioning and narrow SKU focus. Long-term viability over the next decade hinges on OLED technology transition completion and burn-in mitigation advancement. Acquisition targets should demonstrate oxide-TFT yield engineering capabilities and direct OEM contract visibility. Watch for inflection when foldable notebook form factors achieve commercial volume qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Oxide-TFT Backplane Investment | Captures high-refresh gaming panel premiums as ASUS and Razer specifications tighten. |
| Direct-to-OEM Procurement Agreement | Eliminates distributor intermediaries in Vietnam and Mexico assembly corridors. |
| GB 21520 Compliance Certification | Unlocks Chinese domestic notebook brand procurement constrained by MIIT efficiency mandates. |
| Foldable OLED Substrate Development | Converges smartphone hinge mechanics with emerging 20-inch mobile workstation form factors. |
| India PLI Scheme Manufacturing Footprint | Positions module integration capacity for South Asian educational and consumer demand growth. |
Research Methodology
The analysis maps IPS, OLED, TN, and VA technology sub-sectors, each validated through procurement directors at notebook OEMs, panel maker sales executives, and driver IC packaging specialists. Primary interviews with Dell, HP, and Lenovo supply chain managers combined with secondary validation from SEC filings, customs trade records, and MIIT GB standard documentation. Bottom-up cell shipment aggregation and top-down display fab capacity modeling provide triangulation.
Assumption sets held GB 21520 enforcement timelines and OLED burn-in mitigation improvement curves fixed while varying gaming notebook specification trajectories and assembly migration patterns across the projection horizon. Segmentation dimensions modeled include technology architecture, size band, surface treatment, and end-use application. CAGRs derive from panel shipment volumes weighted by average selling price evolution. Forecast inputs incorporate oxide-TFT yield ramp schedules and PLI scheme incentive qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese scale players or accelerated foldable adoption by gaming brands would shift outcomes. Material shifts in US export-control regime stringency or Taiwan semiconductor foundry allocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Digital Holographic Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Commercial Display Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Global Medical Display Market
Display Technologies
Computer Monitor Market
Display Technologies
Display Mask Market
Display Technologies
Vietnam Displays Market
Display Technologies
Wireless Display Market
Display Technologies
TFT LCD Panel Market
Display Technologies
4K Drawing Tablet with Screen Market