
 Automotive Battery Management System (BMS) Chip Market | 2026-2036
Automotive Battery Management System (BMS) Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Management System (BMS) Chip Market Insights
Direct semiconductor procurement between chip designers and vehicle OEMs is reshaping traditional tier-1 supplier relationships in automotive electronics. Infineon Technologies leverages its vertically integrated fab network to sustain pricing power in high-voltage cell monitoring ICs. Texas Instruments anchors its position through analog front-end specialization, while NXP Semiconductors competes on ASIL-D safety architecture integration.
An Automotive Battery Management System (BMS) Chip is a mixed-signal integrated circuit that measures cell voltage, current, and temperature with precision typically within one millivolt, executing state estimation algorithms to prevent thermal runaway and optimize cycle life in lithium-ion packs. Cell monitoring ICs dominate unit shipments due to per-cell granularity requirements in 800-volt architectures, while wireless BMS technology captures the fastest growth trajectory by eliminating harness weight and connector failure modes. Hybrid analog-digital architectures concentrate margin pools where OEMs demand software-defined calibration without sacrificing hard-real-time safety response.
ISO 26262 functional safety standards and UN ECE R100 battery regulations compel ASIL-C or ASIL-D certification for all passenger-vehicle BMS designs, raising R&D barriers for entrants. NHTSA defect investigation protocols in the United States and China's GB/T standards for electric vehicle safety create divergent compliance pathways that fragment firmware validation cycles. Stakeholders must monitor foundry allocation priority shifts between automotive and consumer AI accelerators, as BMS chip tape-out slots compete for mature-node capacity at TSMC and GlobalFoundries.
Market Dynamics
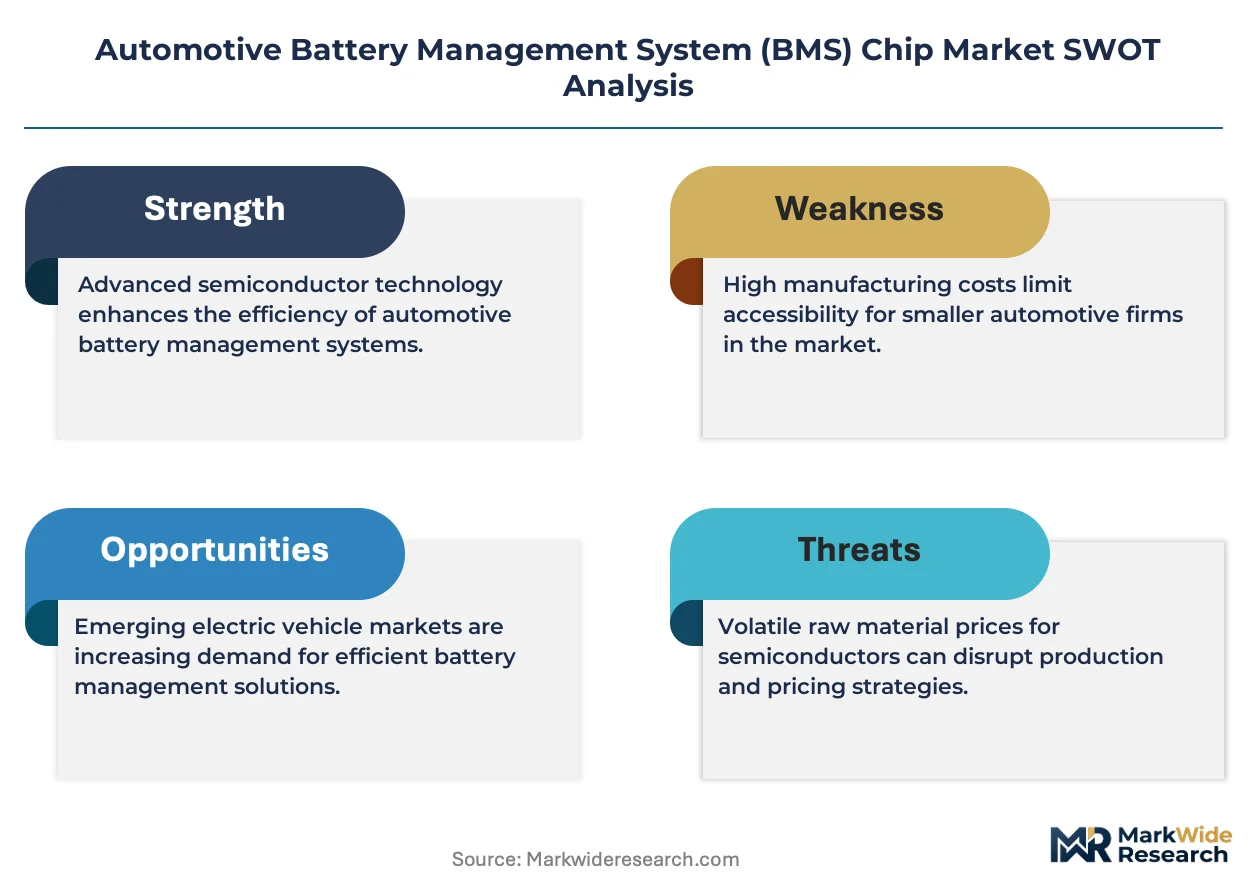
Silicon carbide integration in 800-volt traction systems is forcing cell monitoring IC architectures toward sub-millivolt precision at higher voltage isolation ratings, compressing design cycles and concentrating procurement authority within OEM powertrain divisions.
Growth Catalysts
- UN ECE R100 battery safety mandates:European passenger-vehicle OEMs must achieve ASIL-D certification for thermal runaway detection, expanding validation service demand and hardened firmware development.
- China NEV volume scale:Domestic foundry capacity at SMIC and Hua Hong Semiconductor creates captive supply advantages for local battery pack integrators, accelerating tape-out velocity for cell balancing algorithms.
- Wireless BMS communication protocols:Elimination of wire harness weight and connector failure modes in commercial vehicle platforms reduces pack assembly labor and improves service accessibility.
Market Restraints
- Mature-node foundry allocation:Automotive BMS tape-outs at TSMC and GlobalFoundries compete for 180nm-130nm capacity against consumer AI accelerators, extending lead times for mixed-signal wafers.
- ISO 26262 functional safety compliance:ASIL-C and ASIL-D certification requires redundant voltage reference architectures and fault injection testing, raising non-recurring engineering outlays for new entrants.
- Cell chemistry heterogeneity:Lithium iron phosphate and high-nickel cathode variants demand distinct state-of-charge estimation models, fragmenting firmware development resources across OEM programs.
Strategic Opportunities
- India PLI scheme for advanced chemistry cell manufacturing:Domestic battery gigafactory investments create demand for localized BMS chip design centers and joint validation laboratories with semiconductor vendors.
- Second-life stationary storage:Decommissioned automotive packs require simplified monitoring electronics for grid-scale deployment, opening mid-tier ASIL-B product categories with relaxed safety margins.
- AI-driven predictive maintenance:Edge inference on cell degradation patterns enables warranty risk transfer to component suppliers, creating software subscription revenue streams alongside silicon sales.
Industry Challenges
- Functional safety firmware talent scarcity:ASIL-D certified embedded engineers command premium compensation in automotive electronics, constraining headcount expansion at mid-tier chip design houses.
- Legacy vehicle platform integration:Retrofit BMS architectures must communicate over CAN bus protocols designed for lead-acid monitoring, complicating state estimation algorithm porting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Management System (BMS) Chip Market |
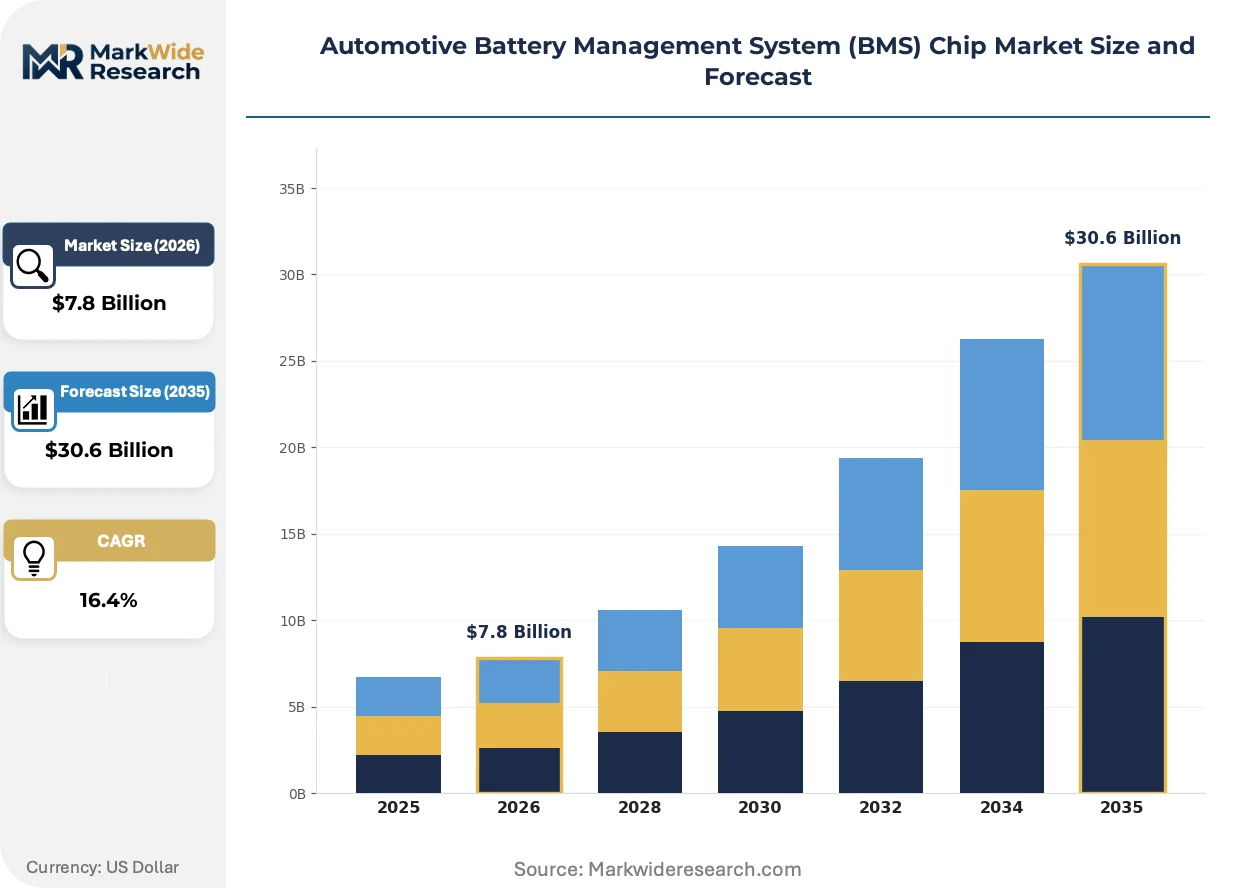
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $30.6 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Monitoring, Battery Protection, State of Charge, Balancing Circuit Technology: Analog, Digital, Hybrid, Wireless End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Electric Vehicles, Hybrid Vehicles, E-Bikes, Energy Storage Systems |
| Companies Covered | Texas Instruments, Infineon Technologies, NXP Semiconductors, Analog Devices, STMicroelectronics, Renesas Electronics, Sensata Technologies, Maxim Integrated, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Management System (BMS) Chip Market Trends and Innovations
Wireless communication topologies and edge intelligence architectures are compressing the traditional tier-1 supplier interface, enabling direct chip-to-OEM relationships that reshape margin distribution and intellectual property ownership.
Hybrid analog-digital BMS architectures is hybridizing precision voltage measurement with software-defined calibration paths. Tier-1 suppliers in Germany and Japan are adopting these designs for premium electric sedan programs. The approach enables post-manufacturing firmware updates without sacrificing hard-real-time safety response, collapsing the traditional boundary between hardware qualification and software iteration cycles.
China's GB/T electric vehicle safety standards and MIIT battery passport requirements are mandating cell-level traceability data retention. Pack assemblers must implement secure element integration for cryptographic authentication of monitoring IC origin. High-voltage commercial vehicle segments face the steepest compliance burden, with OEMs pre-qualifying only domestic semiconductor vendors for government procurement tenders.
Direct semiconductor procurement between powertrain divisions and chip designers is displacing traditional tier-1 distributor relationships in automotive electronics. Battery pack integrators in South Korea and the United States are establishing technical account manager positions with analog front-end specialists, bypassing module-level suppliers for cell monitoring IC specifications. This pattern concentrates most visibly in 800-volt platforms where millivolt precision requirements exceed standard catalog component capabilities.
Automotive Battery Management System (BMS) Chip Market Segmentation
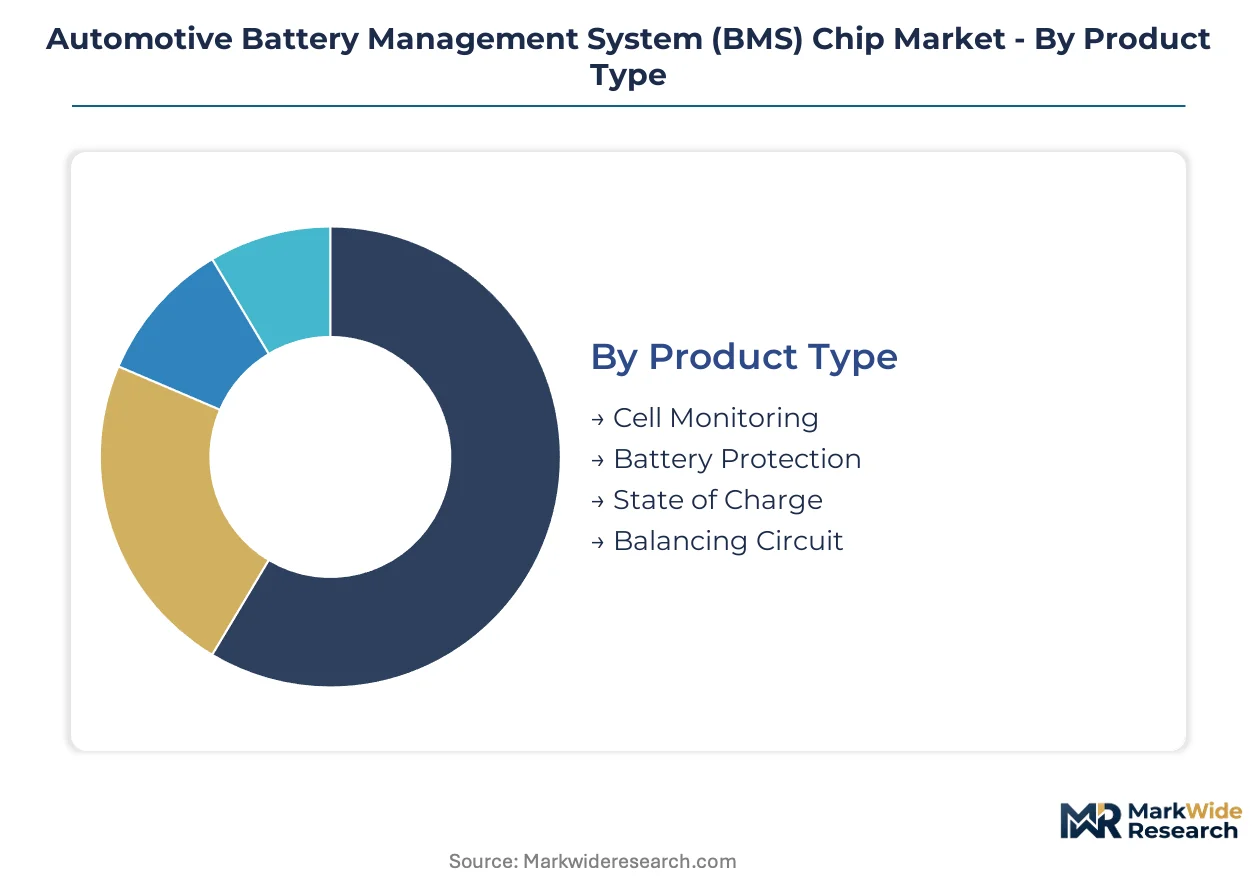
Automotive BMS chip segmentation reflects divergent technical requirements across voltage architectures and procurement models. Product type and technology dimensions capture the most consequential margin stratification, while end-user and application splits reveal where direct OEM engagement is displacing traditional supply hierarchies.
Product Type:
Mature precision electronics dominate established vehicle platforms, while emerging functional categories reshape firmware development priorities for next-generation pack architectures.
- Cell Monitoring:These mixed-signal ICs measure individual cell voltages with sub-millivolt precision across 800-volt series strings. Demand concentrates in premium electric sedan programs from Germany and South Korea where silicon carbide traction systems demand tighter voltage isolation tolerances.
- Balancing Circuit:Active and passive balancing topologies redistribute charge across series-connected cells to prevent capacity fade. Chinese NEV volume scale drives the fastest tape-out velocity for these designs as domestic pack integrators optimize for lithium iron phosphate chemistry cycles.
- Battery Protection:Hardware-level cutoff electronics interrupt current flow during fault conditions.
- State of Charge:Algorithmic estimation engines fuse voltage, current, and temperature inputs into usable range calculations.
Cell Monitoring retains volume leadership; Balancing Circuit holds the steepest expansion curve.
Technology:
Cost tier stratification separates catalog components from custom-engineered solutions requiring specialized foundry processes and extended qualification cycles.
- Hybrid:Architectures combining precision analog front-ends with software-configurable digital backends enable post-manufacturing calibration without sacrificing ASIL-D safety response. European premium OEMs specify these designs for 800-volt platforms where millivolt accuracy must coexist with over-the-air update capability.
- Wireless:Radio-frequency communication topologies eliminate wire harness weight and connector failure modes in commercial vehicle battery packs. North American electric truck manufacturers are pre-qualifying these architectures for severe-service duty cycles where vibration tolerance is paramount.
- Analog:Continuous-time voltage and current measurement circuits dominate legacy 400-volt architectures.
- Digital:Fully digitized signal chains with integrated ADCs serve cost-optimized entry-level electric vehicle segments.
Hybrid captures the highest average selling prices; Wireless is expanding most quickly across new vehicle programs.
End User:
Customer type determines whether procurement flows through established tier-1 distributors or shifts toward direct semiconductor vendor relationships.
- OEMs:Vehicle manufacturers with in-house powertrain divisions are establishing technical account manager positions directly with analog front-end specialists, bypassing module-level suppliers for cell monitoring specifications. This pattern concentrates most visibly in 800-volt platforms where standard catalog components fail precision requirements.
- Tier-1 Suppliers:Established battery pack integrators retain procurement authority for 400-volt mass-market programs where validated reference designs reduce integration risk.
- Aftermarket Providers:Replacement and retrofit specialists source BMS electronics for second-life stationary storage applications.
- Vehicle Assemblers:Contract manufacturing operations rely on specified vendor lists from platform owners.
OEMs are capturing procurement authority fastest; Tier-1 Suppliers retain the largest transaction volumes.
Application:
Application scope spans mobility platforms and stationary infrastructure with divergent safety certification requirements and environmental exposure profiles.
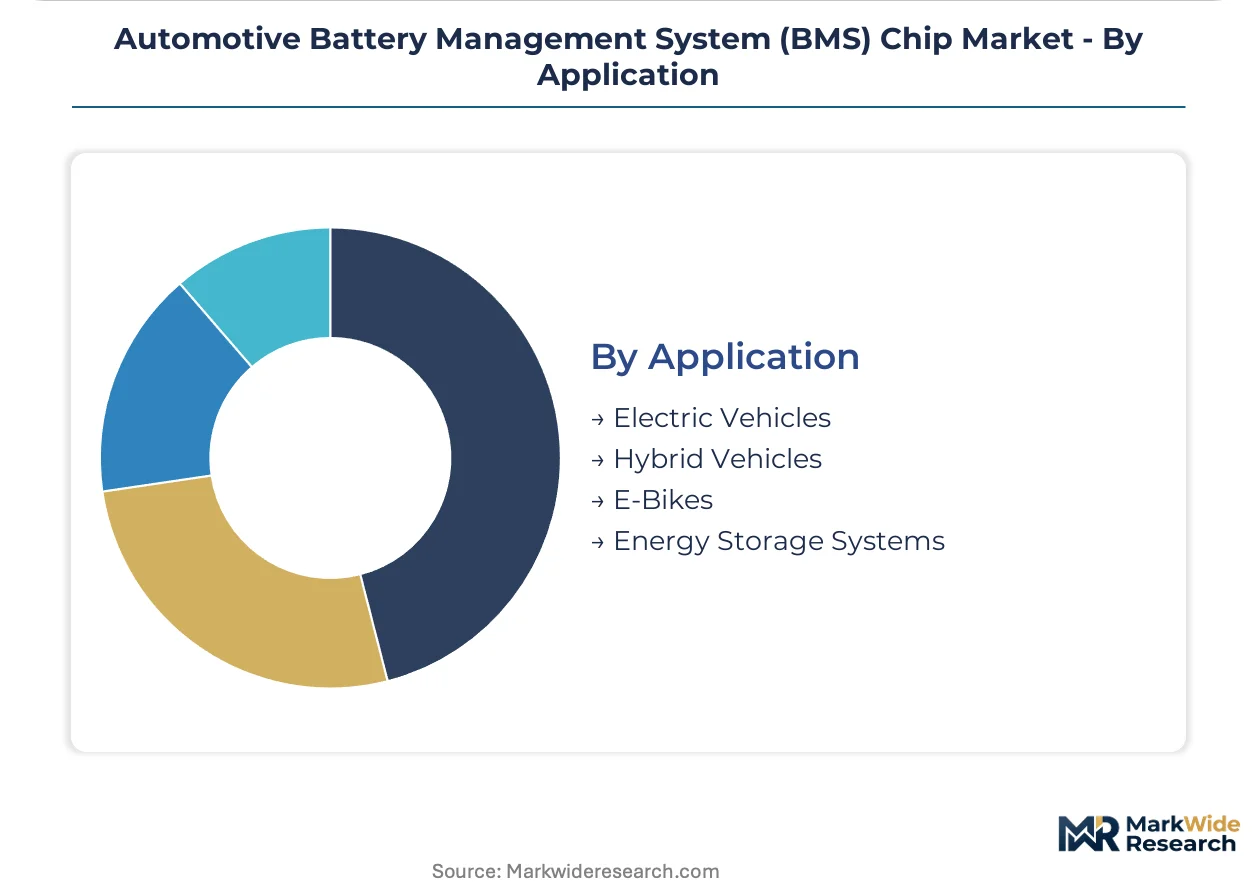
- Electric Vehicles:Passenger and commercial platforms require ASIL-D certified electronics with full ISO 26262 documentation. Demand clusters in China where GB/T standards and MIIT battery passport mandates create compliance pathways distinct from European UN ECE R100 requirements.
- Energy Storage Systems:Grid-scale and residential battery installations utilize simplified monitoring electronics with relaxed safety margins. Decommissioned automotive packs entering second-life deployment drive mid-tier ASIL-B product categories.
- Hybrid Vehicles:Smaller battery capacities with lower voltage architectures tolerate less sophisticated cell monitoring granularity.
- E-Bikes:Micromobility applications prioritize cost minimization over precision measurement.
Electric Vehicles command the highest silicon content per pack; Energy Storage Systems are gaining share fastest as battery retirement volumes accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT battery passport requirements and GB/T electric vehicle safety standards anchor demand concentration in China, where domestic foundry capacity creates captive supply advantages for local pack integrators. Regulatory divergence between UN ECE R100 in Europe and NHTSA protocols in the United States fragments firmware validation cycles across major automotive markets.
China
NEV volume scale and domestic foundry capacity at SMIC and Hua Hong Semiconductor accelerate tape-out velocity for cell balancing algorithms. MIIT battery passport mandates require cell-level traceability data retention with secure element integration for cryptographic authentication. Pack assemblers in the Yangtze River Delta and Pearl River Delta pre-qualify only domestic semiconductor vendors for government procurement tenders.
United States
North American electric truck manufacturers drive wireless BMS adoption for severe-service duty cycles where vibration tolerance is paramount. NHTSA defect investigation protocols create compliance pathways distinct from European UN ECE R100 requirements. Battery pack integrators in Michigan and California establish technical account manager positions directly with analog front-end specialists, bypassing traditional tier-1 distributors.
Germany
Premium electric sedan programs from German OEMs demand sub-millivolt precision in 800-volt silicon carbide traction systems. KBA type approval processes enforce ASIL-D certification for thermal runaway detection, expanding validation service demand. Tier-1 suppliers in Bavaria and Baden-Württemberg adopt hybrid analog-digital architectures enabling post-manufacturing firmware updates without sacrificing hard-real-time safety response.
South Korea
Battery pack integrators establish direct technical account relationships with cell monitoring IC specialists for 800-volt platform specifications. MFDS automotive electronics guidelines align with ISO 26262 functional safety mandates. Seoul-based powertrain divisions concentrate procurement authority for millivolt-precision components that exceed standard catalog capabilities.
India
Domestic battery gigafactory investments under the PLI scheme for advanced chemistry cell manufacturing create demand for localized BMS chip design centers. CEA grid integration standards and BIS automotive electronics certifications shape compliance requirements. Joint validation laboratories with semiconductor vendors concentrate in Maharashtra and Tamil Nadu as OEMs expand technical partnerships.
Automotive Battery Management System (BMS) Chip Market Competitive Landscape
Vertically integrated analog specialists and fabless mixed-signal designers split the market based on foundry access and safety certification depth. The vendor base concentrates around three strategic archetypes: captive fab operators sustaining pricing power in high-voltage isolation components, analog front-end specialists anchoring through precision measurement IP, and diversified semiconductor conglomerates competing on ASIL-D safety architecture integration. Dominant competitive moves include backward integration into mature-node foundry capacity and direct OEM technical account relationships that displace traditional tier-1 distributor channels.
Within the vertically integrated tier, Infineon Technologies and Texas Instruments exemplify divergent approaches to market positioning. Infineon's German corporate structure and captive fab network represent the archetype of upstream-controlled supply security for automotive qualification cycles. Texas Instruments anchors the analog specialization vector through front-end measurement IP that commands premium positioning in precision-intensive applications. NXP Semiconductors occupies a diversified-conglomerate position, competing through safety architecture integration that spans multiple automotive electronics categories beyond battery management.
| Leading Market Players |
|---|
| Texas Instruments |
| Infineon Technologies |
| NXP Semiconductors |
| Analog Devices |
| STMicroelectronics |
| Renesas Electronics |
| Sensata Technologies |
| Maxim Integrated |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
Mature-node foundry undercapacity at TSMC and GlobalFoundries is forcing automotive BMS chip suppliers into allocation negotiations that simultaneously extend lead times and compress margin structures for mixed-signal wafer procurement.
Pricing Analysis
Geographic price spreads between Chinese domestic suppliers and European premium vendors exceed three-to-one ratios for equivalent cell monitoring IC specifications. Three-tier pricing structure across ASIL-D certified, ASIL-C compliant, and uncatalogued commercial-grade components anchors the market. Cost compression in entry-level electric vehicle segments intensifies as lithium iron phosphate chemistry standardization reduces firmware customization premiums. Tier-1 battery pack integrators exhibit highest price sensitivity, while OEM powertrain divisions with direct semiconductor procurement tolerate premium positioning for 800-volt precision requirements.
Supply Chain Analysis
Contract manufacturing concentration at TSMC, GlobalFoundries, and SMIC controls wafer supply for automotive BMS tape-outs across 180nm through 40nm process nodes. Raw material dependencies on silicon wafers, copper interconnects, and ceramic substrate packaging materials draw from Taiwan, Japan, and South Korean supply bases. Single-source vulnerability concentrates in high-voltage isolation transformer manufacturing where German and Japanese component specialists dominate. Distribution runs through authorized semiconductor distributors serving tier-1 battery pack integrators, with direct OEM technical account relationships bypassing traditional channels in premium electric vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined calibration subscriptions and predictive maintenance service layers are expanding faster than hardware unit shipments, creating recurring-revenue architectures that reshape vendor valuation multiples in automotive battery electronics.
For Market Incumbents: Insulate margin structures through captive foundry capacity investments in Germany and Malaysia that reduce allocation vulnerability to consumer AI accelerator demand. Deepen ASIL-D certification moats by embedding redundant voltage reference architectures that new entrants cannot replicate without eighteen-month validation cycles. Counter wireless BMS displacement threats by acquiring radio-frequency communication IP specialists before commercial vehicle platforms standardize. For New Entrants and Emerging Players: Establish a beachhead in second-life stationary storage applications where ASIL-B safety margins tolerate less hardened firmware architectures. Target Indian battery gigafactory investments under the PLI scheme, where localized design centers face limited incumbent penetration. Pursue joint validation laboratory partnerships with domestic semiconductor vendors to accelerate tape-out velocity for lithium iron phosphate cell balancing algorithms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid analog-digital architecture specialists with software-defined calibration paths that enable post-manufacturing firmware update monetization. Long-term viability favors vendors with backward integration into mature-node foundry capacity and direct OEM technical account relationships that displace tier-1 distributor channels. Monitor foundry allocation priority shifts between automotive and consumer AI accelerators as the primary inflection signal for BMS chip availability and pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mature-Node Foundry Capacity | Captive wafer supply at SMIC and GlobalFoundries reduces allocation vulnerability to AI accelerator demand. |
| Direct OEM Technical Account Relationships | Bypassing tier-1 distributors concentrates procurement authority for 800-volt precision specifications. |
| ASIL-D Safety Architecture Certification Investment | Redundant voltage reference designs create eighteen-month validation moats against emerging competitors. |
| Wireless BMS Communication Protocol Development | Eliminating wire harness weight captures North American electric truck manufacturer pre-qualifications. |
| Second-Life Stationary Storage Product Line Expansion | ASIL-B relaxed margins open mid-tier revenue as automotive battery retirement volumes accumulate. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, MIIT battery passport disclosures, and ISO 26262 certification databases. Interviews with OEM powertrain procurement directors, tier-1 battery pack integration engineers, and analog front-end IC design leads informed demand-side validation. Foundry capacity utilization reports from TSMC and GlobalFoundries, combined with vehicle production databases from IHS Markit, anchored supply-side triangulation through bottom-up and top-down reconciliation.
Forecast inputs include vehicle class stratification, propulsion architecture voltage tier, silicon content per pack, OEM procurement model, and regional production cluster concentration. Segmentation dimensions span product type, technology topology, end-user procurement authority, and application safety certification level. CAGRs derive from unit shipment trajectories mapped against average selling price erosion curves for catalog versus custom-engineered components. Foundry allocation priority modeling and ISO 26262 compliance timeline assumptions shape the projection horizon.
Sensitivities concentrate around foundry capacity reallocation to AI accelerators, UN ECE R100 regulatory amendments, and lithium iron phosphate chemistry standardization velocity. Forecasts reflect documented assumptions regarding NEV volume scale and domestic foundry expansion timelines. Quarterly review of MIIT battery passport implementation progress and KBA type approval queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Automotive Infotainment SOC Market