
 Global Wireless Chipsets Market | 2026-2036
Global Wireless Chipsets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Chipsets Market Outlook
Taiwanese foundry capacity for advanced radio frequency silicon is decoupling from legacy node commitments. Qualcomm Technologies, Inc. leverages its Snapdragon platform dominance to anchor premium-tier smartphone sockets across North American and South Korean OEMs. MediaTek Inc. competes aggressively on price-performance in mid-range 5G chipsets for Indian and Southeast Asian device makers. Broadcom Inc. specializes in high-performance Wi-Fi 6E and emerging Wi-Fi 7 access point silicon for enterprise infrastructure.
Wireless chipsets are integrated semiconductor devices combining baseband processors, RF transceivers, and power management units on single or multi-die packages, typically fabricated at 7nm to 28nm process nodes depending on performance tier, enabling bidirectional radio communication across licensed and unlicensed spectrum bands. Their primary purpose is to provide standardized connectivity subsystems for electronic devices without requiring discrete component design by OEMs. Wi-Fi and 5G technology segments command the largest revenue pools as infrastructure upgrade cycles and device refresh patterns concentrate spending on next-generation standards. Bluetooth and LPWAN categories occupy distinct margin structures where volume scale in audio accessories and industrial sensor networks respectively offset lower per-unit pricing.
FCC spectrum auctions in the United States, EU Radio Equipment Directive compliance requirements, and MIIT type-approval processes in China collectively shape product certification timelines and regional feature availability for chipset vendors. REACH substance restrictions and evolving CE marking obligations under the EU's Cybersecurity Act add compliance layers that influence packaging material selection and firmware update architectures. Stakeholders must monitor spectrum harmonization negotiations between national regulators to anticipate which connectivity standards will achieve cross-border interoperability and therefore justify unified silicon platform investments.
Market Dynamics
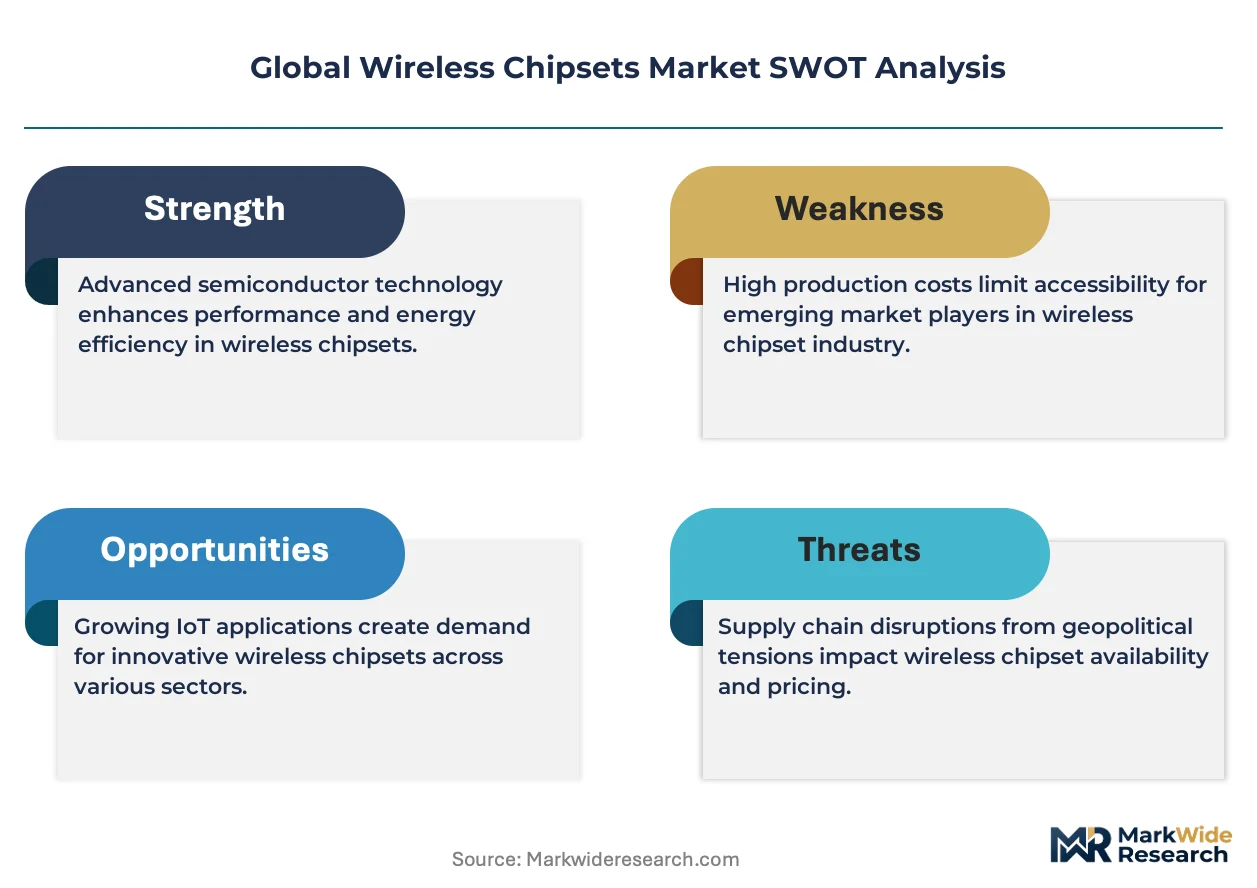
Advanced node allocation for radio frequency silicon is diverting foundry capacity from mature processes, creating a supply bottleneck for mid-tier 5G modems while premium smartphone sockets capture available 7nm and 5nm output.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic sourcing mandates for wireless connectivity components are accelerating local assembly of 5G-enabled devices. Component vendors are establishing captive testing facilities in Gujarat and Tamil Nadu to meet BIS certification timelines.
- Wi-Fi 6E spectrum harmonization:FCC allocations in the United States and parallel EU Radio Equipment Directive amendments are unlocking 6 GHz band utilization. Enterprise infrastructure refresh cycles are compressing as IT departments prioritize interference-resistant wireless backhaul.
- Integrated modem-antenna modules:System-in-package architectures are reducing board space requirements for smartphone OEMs. This consolidation is displacing discrete RF front-end assemblies in mid-range device categories.
Market Restraints
- Advanced node cost escalation:5nm and 3nm tape-out expenses for cellular basebands have crossed thresholds that exclude fabless entrants without pre-paid capacity reservations.
- Taiwanese foundry concentration:Over 80 percent of leading-edge RF silicon capacity resides with two pure-play manufacturers, creating single-source vulnerability for Qualcomm and MediaTek roadmaps.
- Legacy 4G inventory overhang:Accumulated modem stockpiles from 2022-2023 production cycles are delaying 5G upgrade decisions among cost-sensitive OEMs in Southeast Asia.
Strategic Opportunities
- Industrial IoT sensor networks:LPWAN chipset volumes in Brazil's agricultural monitoring sector remain underpenetrated relative to cellular module deployment. Local ANVISA type-approval pathways for unlicensed spectrum devices are shortening.
- Automotive V2X integration:DSRC and C-V2X convergence is creating unified platform demand for dual-mode transceivers. NHTSA rulemaking on connected vehicle mandates is accelerating Tier 1 supplier qualification timelines.
- Open RAN disaggregation:Interface standardization is enabling merchant silicon entry into baseband processing units previously served by integrated vendor stacks.
Industry Challenges
- RF analog design expertise scarcity:Foundry process migration from 28nm to 16nm FinFET geometries demands specialized transistor noise modeling capabilities that limited engineering teams possess.
- Multi-jurisdiction certification parallelism:Simultaneous FCC, CE marking, and MIIT type-approval processes for 5G NR bands are extending product launch windows by 8-14 months.
- Legacy enterprise Wi-Fi replacement friction:Controller-based architectures in installed infrastructure complicate migration to cloud-managed Wi-Fi 6E access points without forklift hardware swaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Chipsets Market |
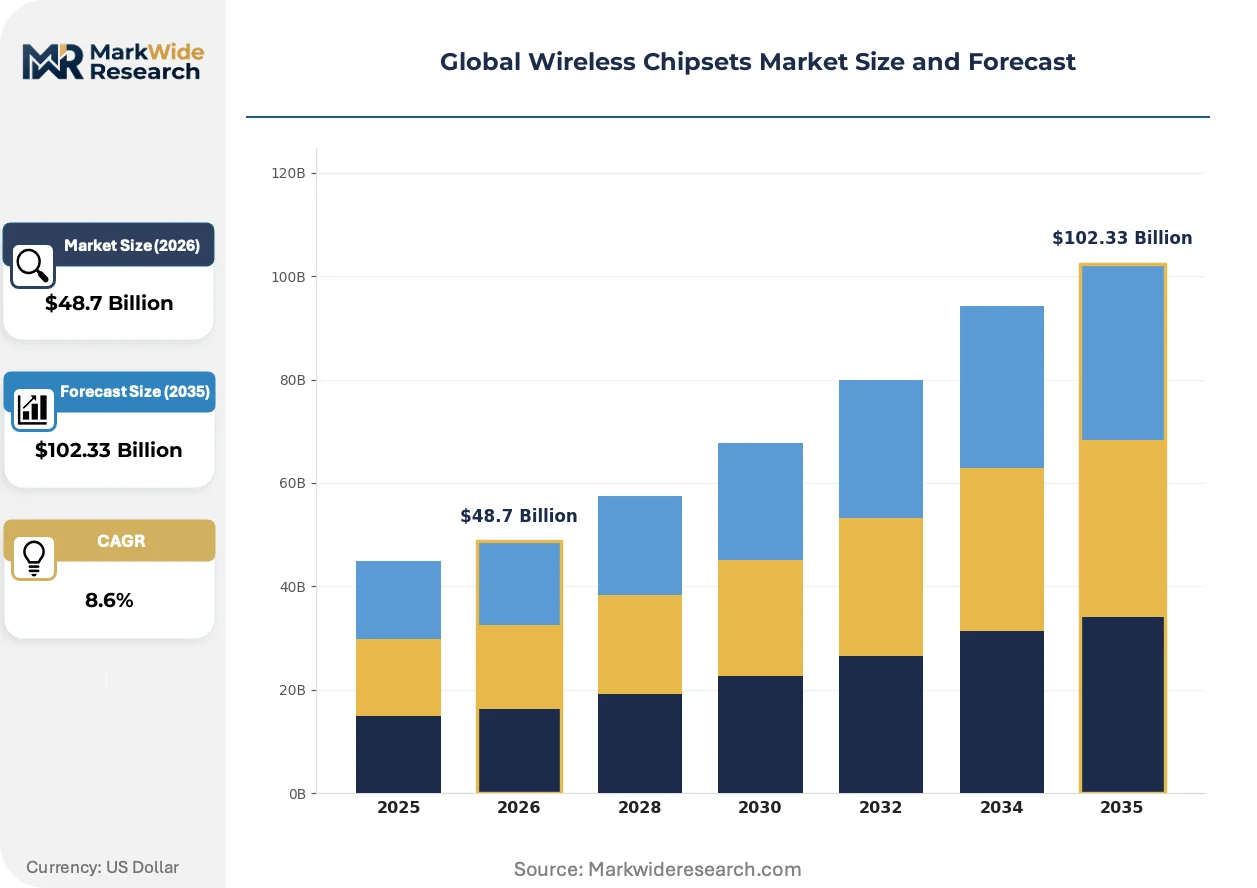
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth, Wi-Fi, NFC, Zigbee Technology: 4G LTE, 5G, Wi-Fi 6, LPWAN Application: Automotive, Smart Home, Industrial Automation, Wearables End User: Telecommunications, Consumer Electronics, Healthcare, Retail |
| Companies Covered | Qualcomm Technologies, Inc., Broadcom Inc., MediaTek Inc., Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors NV, STMicroelectronics NV, Infineon Technologies AG, Skyworks Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Chipsets Market Strategic Shifts
Silicon architectures are converging around system-in-package designs that merge heterogeneous dies, reshaping competitive boundaries between discrete component specialists and integrated platform vendors.
Chiplet-based baseband-RF partitioning is overtaking monolithic die strategies for flagship smartphone modems. Qualcomm and MediaTek are both adopting 3D stacking to separate digital logic from analog front-end functions. This disaggregation is compressing time-to-market for new band support while increasing thermal management complexity in compact device form factors.
REACH substance restrictions on halogenated flame retardants are forcing substrate material transitions in high-frequency laminate packages. ECHA's 2023 SVHC candidate list expansion specifically targets brominated compounds common in millimeter-wave antenna-in-package substrates. Vendors are accelerating glass-core substrate qualification to maintain EU market access for Wi-Fi 7 reference designs.
Enterprise buyers are consolidating wireless infrastructure procurement under managed service contracts rather than capital equipment purchases. This transition is displacing traditional distributor-led volume purchasing in North American healthcare and education verticals. IT departments now prioritize subscription-based network assurance over upfront hardware acquisition, compressing vendor margin structures while extending customer lifetime value calculations.
Global Wireless Chipsets Market Segmentation
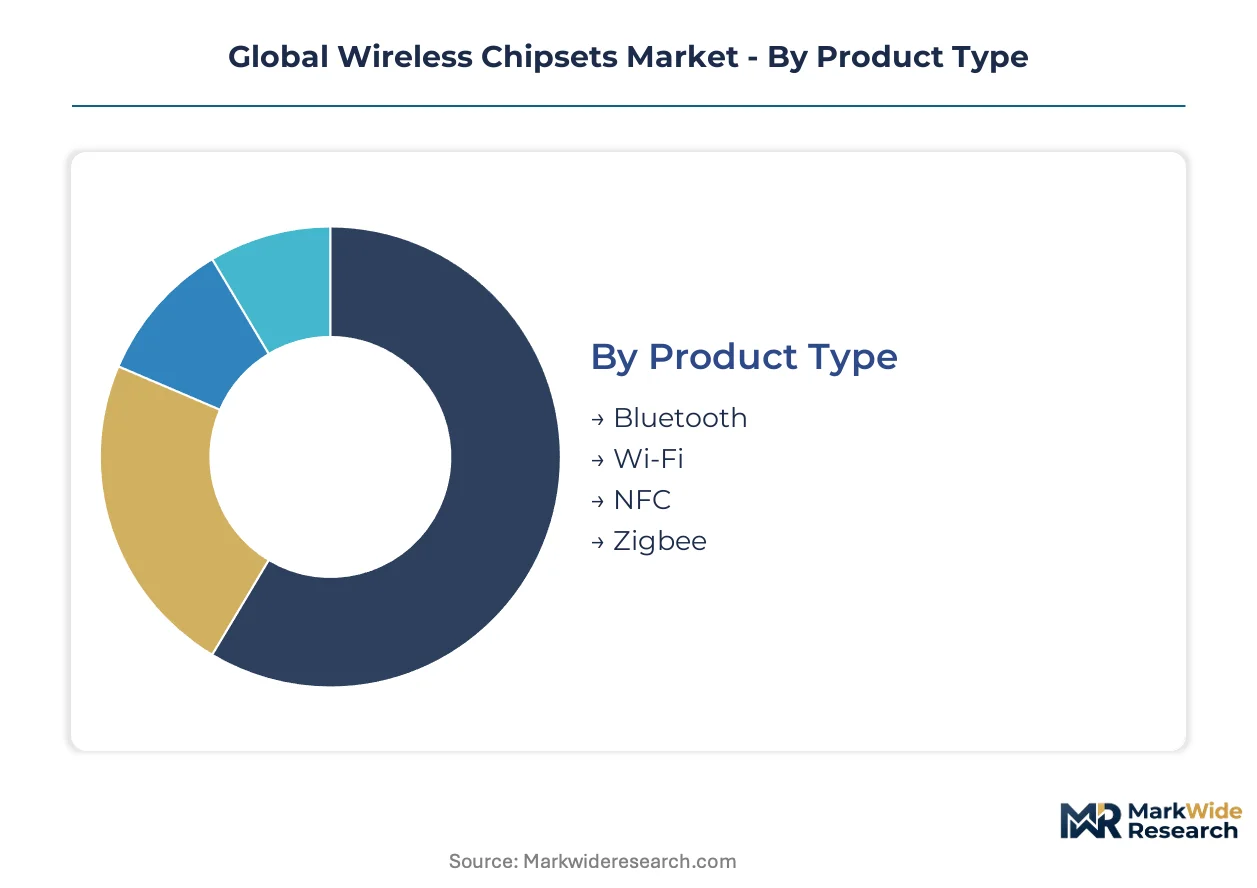
Wireless chipset segmentation reveals how connectivity standards fragment across device categories and performance tiers. Vendors architect product portfolios around spectrum licensing models, power budgets, and certification complexity rather than pursuing universal platforms.
Product Type:
Radio protocols diverge sharply in power consumption, range, and data throughput specifications. OEMs select protocols based on duty cycle requirements and coexistence constraints in crowded spectrum environments.
- Bluetooth:Low-energy variants dominate audio accessories and fitness wearables. Nordic Semiconductor and Qualcomm split volume leadership in true wireless stereo earbuds shipping from Dongguan and Ho Chi Minh City assembly lines.
- Wi-Fi:Dual-band 2.4/5 GHz silicon saturates residential routers and streaming devices. Enterprise access point refresh cycles in Germany and Japan are compressing as IT departments prioritize Wi-Fi 6E migration for interference-resistant backhaul.
- NFC:Secure element integration for contactless payments requires Common Criteria certification. Deployment concentrates in point-of-sale terminals across Brazilian retail chains and Japanese transit gate infrastructure.
- Zigbee:Mesh networking protocols serve smart lighting and HVAC control systems. Silicon Labs and Texas Instruments supply Thread-compatible variants for Matter-certified home automation hubs.
Mature deployment sits with Wi-Fi. Newer deployment is concentrated in Bluetooth Low Energy for audio streaming.
Technology:
Cellular and unlicensed standards occupy distinct margin structures. Premium sockets command advanced node silicon while LPWAN categories optimize for decade-long battery life.
- 4G LTE:Cat-1 and Cat-M1 modems sustain industrial telemetry and telematics applications. Indian agricultural sensor networks and Brazilian fleet management platforms continue sourcing legacy silicon amid 5G upgrade delays.
- 5G:Sub-6 GHz and millimeter-wave basebands require 7nm to 4nm process nodes. Qualcomm Snapdragon and MediaTek Dimensity platforms anchor premium smartphone sockets in South Korea and the United States where carrier aggregation complexity justifies integrated modem-antenna modules.
- Wi-Fi 6:OFDMA scheduling and 1024-QAM modulation boost spectral efficiency in dense environments. Enterprise infrastructure in Singapore and Australia is replacing 802.11ac controllers with cloud-managed Wi-Fi 6 access points.
- LPWAN:LoRa and NB-IoT chipsets enable decade-long battery life for utility meters and environmental monitors. Unlicensed spectrum deployment in France and Spain accelerates as ANFR and CNMC harmonize sub-GHz channel plans.
Volume leadership belongs to 4G LTE. Steepest expansion trajectory is concentrated in 5G as spectrum auctions conclude across India and Southeast Asia.
Application:
End-use verticals impose divergent reliability and latency requirements. Automotive and industrial segments demand AEC-Q100 and IEC 61508 functional safety certifications that consumer categories bypass.
- Automotive:DSRC and C-V2X transceivers enable vehicle-to-infrastructure communication for collision avoidance. NHTSA rulemaking on connected vehicle mandates is accelerating Tier 1 supplier qualification timelines for dual-mode silicon.
- Smart Home:Multi-protocol hubs integrate Zigbee, Thread, and Wi-Fi on single boards. Amazon and Google reference designs from Shenzhen ODMs are displacing discrete router-extender combinations in North American residential construction.
- Industrial Automation:Time-sensitive networking over Wi-Fi 6 supports deterministic control loops. German automotive assembly lines and Japanese precision manufacturing facilities are piloting wireless deterministic protocols for mobile robot coordination.
- Wearables:Ultra-low-power Bluetooth SoCs with integrated sensor hubs dominate fitness bands and smartwatches. Assembly in Vietnam and Indonesia is climbing fastest as OEMs diversify from Chinese manufacturing.
Established volume sits with Smart Home. Emerging deployment is concentrated in Automotive V2X as regulatory mandates crystallize.
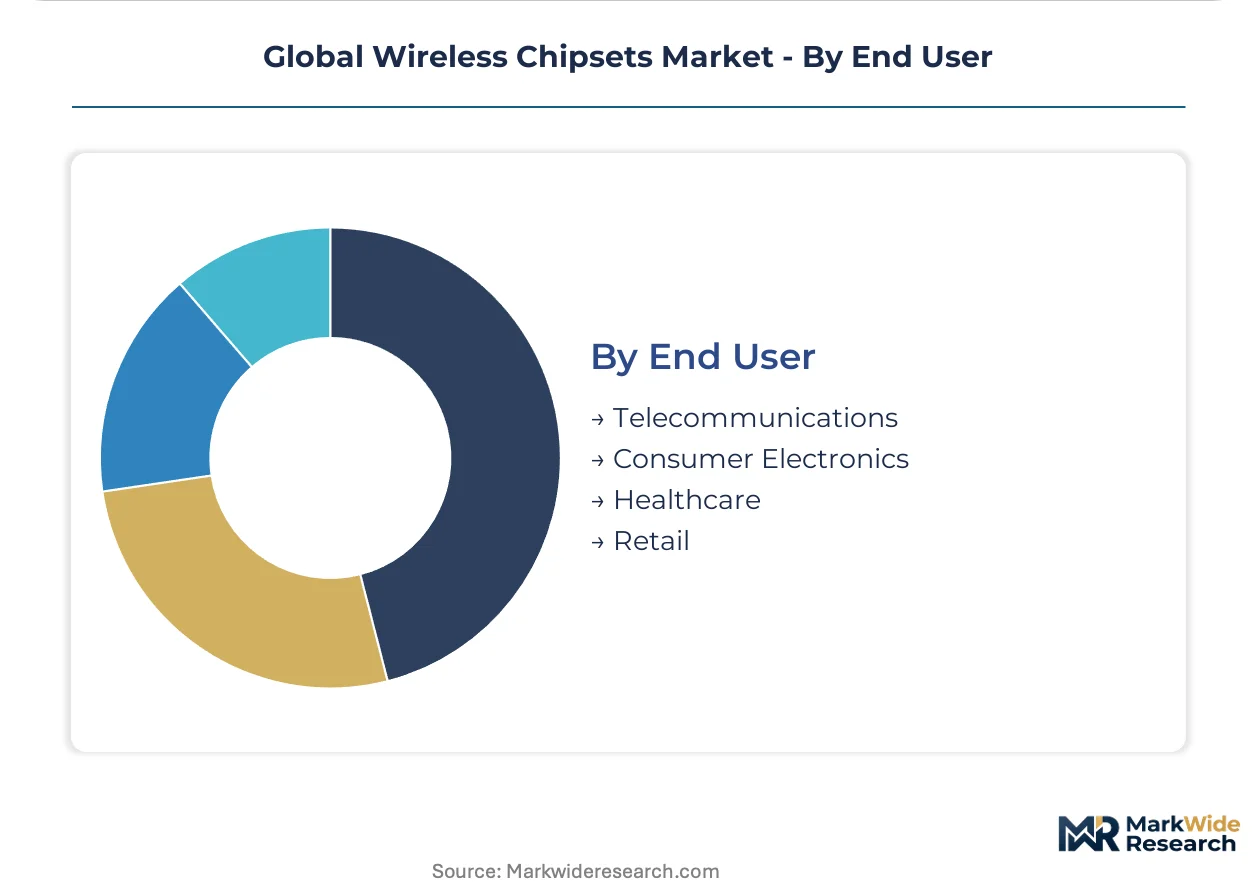
End User:
Procurement patterns separate capital equipment buyers from subscription-driven managed service adopters. Healthcare and retail verticals prioritize cybersecurity certifications that telecommunications and consumer electronics categories treat as secondary.
- Telecommunications:Baseband processing units and massive MIMO radio units require carrier-grade reliability. Open RAN disaggregation is enabling merchant silicon entry into baseband processing previously served by integrated vendor stacks.
- Consumer Electronics:Smartphone OEMs in India and Indonesia are expanding orders for integrated 5G modems as domestic electronics manufacturing incentives accelerate local sourcing requirements.
- Healthcare:FDA and HIPAA compliance for wireless patient monitors demands encrypted over-the-air update architectures. Philips and GE Healthcare specify chipsets with hardware root-of-trust for bedside telemetry.
- Retail:Electronic shelf labels and inventory tracking tags deploy unlicensed spectrum mesh networks. French hypermarket chains and Japanese convenience store operators are scaling LPWAN infrastructure for real-time price synchronization.
Revenue concentration rests with Telecommunications. Fastest share gain is occurring in Healthcare as remote patient monitoring reimbursement codes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon feedstock from German chemical clusters and Taiwanese foundry-grade polysilicon anchors the geographic distribution of wireless chipset fabrication. Advanced lithography capacity concentrates in East Asian manufacturing hubs while design engineering gravitates toward North American and European R&D centers.
United States
Enterprise infrastructure refresh cycles drive Wi-Fi 6E and Wi-Fi 7 chipset procurement from IT departments prioritizing interference-resistant wireless backhaul. FCC spectrum auctions in the 6 GHz band unlock new unlicensed spectrum utilization for access point silicon. Austin and San Diego host design centers where fabless vendors architect baseband processors for North American carrier aggregation requirements.
China
Domestic smartphone OEMs expand orders for integrated 5G modems as MIIT type-approval processes accelerate local certification timelines. The country's dual carbon goals influence packaging material selection for millimeter-wave antenna-in-package substrates. Shenzhen and Shanghai manufacturing clusters assemble reference designs for multi-protocol smart home hubs targeting Matter certification.
India
Domestic electronics manufacturing incentives accelerate local sourcing requirements for wireless connectivity components under the PLI scheme. BIS certification timelines compress as component vendors establish captive testing facilities in Gujarat and Tamil Nadu. Bangalore and Hyderabad design centers support mid-range 5G chipset adaptation for cost-sensitive device makers.
Germany
Automotive Tier 1 suppliers accelerate qualification timelines for DSRC and C-V2X dual-mode transceivers as KBA regulatory frameworks crystallize. REACH substance restrictions on halogenated flame retardants force substrate material transitions in high-frequency laminate packages. Munich and Stuttgart engineering clusters develop time-sensitive networking silicon for deterministic industrial control loops.
South Korea
Premium-tier smartphone OEMs anchor integrated modem-antenna module procurement for carrier aggregation complexity in sub-6 GHz and millimeter-wave bands. MFDS cybersecurity certification requirements influence firmware update architectures for healthcare and enterprise verticals. Seoul and Suwon R&D centers drive 3D stacking adoption for digital-analog die disaggregation in flagship baseband designs.
Global Wireless Chipsets Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty RF front-end and LPWAN segments. The vendor base stratifies between integrated platform architects and discrete component specialists. Three archetypes dominate: fabless semiconductor designers with captive foundry relationships, diversified analog-mixed-signal conglomerates, and RF front-end specialists with filter and amplifier expertise. Capacity reservation strategies and strategic licensing agreements constitute the dominant competitive moves.
Among fabless platform architects, Qualcomm Technologies, Inc. and MediaTek Inc. occupy positions exemplifying premium-tier and mid-range segmentation strategies respectively. Broadcom Inc. represents the diversified analog-mixed-signal archetype with enterprise infrastructure specialization. These three anchors illustrate how competitive positioning diverges across smartphone OEM procurement tiers and enterprise access point refresh cycles.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Broadcom Inc. |
| MediaTek Inc. |
| Intel Corporation |
| Texas Instruments Incorporated |
| NXP Semiconductors NV |
| STMicroelectronics NV |
| Infineon Technologies AG |
| Skyworks Solutions Inc. |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on halogenated flame retardants gate qualified substrate supply for Wi-Fi 7 reference designs, compressing vendor pools capable of commanding premium-tier socket access while forcing material transitions that reshape cost structures across laminate package tiers.
Pricing Analysis
Warranty and firmware-update bundling separates enterprise infrastructure procurement from bare-silicon transactional sales in the Wi-Fi 6E and Wi-Fi 7 categories. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity and foundry node geometry, with 7nm and 5nm cellular basebands commanding substantial premiums over 28nm LPWAN alternatives. Pricing pressure stems from accumulated 4G LTE modem inventory overhangs in Southeast Asian channels, compressing upgrade cycle urgency. Cost-sensitive Indian and Indonesian smartphone OEMs exhibit highest price elasticity, while North American carrier-qualification requirements insulate premium-tier sockets from comparable margin erosion.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam anchor hub-and-spoke fulfillment patterns for reference design kits and antenna-in-package substrates. Foundry-grade polysilicon feedstock draws from German chemical clusters and Taiwanese purification facilities, with advanced lithography capacity concentrating in South Korea and Taiwan. Single-source vulnerability pervades leading-edge RF silicon where over 80 percent of capacity resides with two pure-play manufacturers. Distribution runs through authorized component distributors and direct OEM contracts, with PLI scheme incentives in India accelerating captive testing facility buildouts that bypass traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH substance restrictions and multi-jurisdiction certification parallelism erect barrier-to-entry moats favoring incumbents with pre-qualified substrate portfolios and established regulatory affairs infrastructure.
For Market Incumbents: Lock in captive foundry capacity reservations at 5nm and 3nm nodes to preclude fabless entrant participation in premium smartphone sockets. Accelerate glass-core substrate qualification timelines to maintain EU market access against ECHA SVHC list expansion. Vertical integration into antenna-in-package assembly insulates margin structures from laminate material cost volatility. For New Entrants and Emerging Players: Open RAN interface standardization offers a technology-first wedge into baseband processing units previously served by integrated vendor stacks. Target LPWAN chipset deployment in Brazil's agricultural monitoring sector where ANVISA type-approval pathways for unlicensed spectrum devices are shortening. Pursue white-label reference design partnerships with Shenzhen ODMs to bypass direct carrier qualification burdens. For Investors and Strategic Acquirers: NHTSA rulemaking finalization on connected vehicle mandates is the leading indicator that automotive V2X silicon qualification timelines will compress, creating acquisition window urgency. Over a 5-10 year viability horizon, dual-mode DSRC and C-V2X transceiver specialists represent consolidation targets as platform convergence accelerates. Monitor BIS certification facility establishment rates in Gujarat and Tamil Nadu as inflection signals for India PLI scheme maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Pre-paid 5nm and 3nm commitments at TSMC and Samsung secure roadmap continuity for Qualcomm and MediaTek. |
| Glass-Core Substrate Qualification | ECHA SVHC compliance enables EU market retention for Wi-Fi 7 reference designs amid REACH flame-retardant restrictions. |
| Open RAN Merchant Silicon Entry | Interface standardization displaces integrated vendor stacks in telecommunications baseband processing units. |
| PLI Scheme Testing Facility Buildout | BIS certification compression in Gujarat and Tamil Nadu accelerates local sourcing compliance for Indian smartphone OEMs. |
| Automotive V2X Platform Convergence | Dual-mode transceiver integration addresses NHTSA connected vehicle mandates and KBA regulatory frameworks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with FCC spectrum auction results, EU Radio Equipment Directive amendments, and MIIT type-approval databases providing certification timeline benchmarks. Primary interviews with RF design engineers, foundry account managers, semiconductor procurement leads at smartphone OEMs, and regulatory affairs specialists at chipset vendors cross-validated capacity allocation trends and pricing dynamics. SEC 10-K disclosures from fabless platform architects and foundry utilization reports supplied financial triangulation against bottom-up volume estimates across smartphone, enterprise infrastructure, and automotive verticals.
Data-stream reconciliation merged shipment volume tracking from ODM assembly lines in Vietnam and Indonesia with carrier aggregation requirement specifications from North American and South Korean operators. Segmentation dimensions modeled include radio protocol, cellular generation tier, process node geometry, end-use vertical, and regional regulatory cluster. CAGRs were derived from S-curve adoption modeling for Wi-Fi 6E and 5G NR standards, with foundry capacity expansion schedules and spectrum auction conclusion timelines serving as key forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions to Taiwanese foundry operations, abrupt shifts in FCC or MIIT spectrum allocation priorities, and faster-than-anticipated legacy 4G inventory absorption rates. Forecasts reflect documented assumptions regarding sustained PLI scheme incentive levels and REACH substance restriction enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that RF analog design expertise scarcity and multi-jurisdiction certification parallelism introduce execution risk not fully captured in quantitative projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Chiplet Technology Market