
 Edge AI Chipset Market | 2026-2036
Edge AI Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Edge AI Chipset Market Foresight
On-device neural inference is tilting the computing paradigm from centralized data centers toward distributed edge nodes. NVIDIA Corporation leverages its CUDA software ecosystem to lock in developer loyalty across robotics and autonomous systems. Qualcomm Technologies, Inc. anchors the smartphone-to-automotive pipeline with its Snapdragon platforms purpose-built for low-wattage inference. Intel Corporation sustains manufacturing scale through foundry investments that supply x86 and emerging RISC-V architectures for industrial gateways.
An edge AI chipset is a dedicated integrated circuit or system-on-chip that performs machine learning inference locally at the network periphery, typically operating within sub-15 watt thermal envelopes and integrating tensor processing units alongside CPU and GPU cores for heterogeneous compute. These devices process sensor data in real time for latency-critical decisions in factory automation, medical imaging, and vehicular perception without cloud dependency. ASIC designs now capture the highest margin pools in surveillance and autonomous vehicle applications where unit volumes justify mask costs. FPGA architectures lead in manufacturing and robotics prototyping due to reconfigurable logic that adapts to evolving neural network topologies. Deep learning accelerators within the technology segment outpace natural language processing chips as computer vision workloads proliferate across retail and transportation end users.
The US Department of Commerce's Bureau of Industry and Security export controls restrict advanced AI chip shipments to specific foreign entities, fragmenting supply chains and spurring domestic foundry construction. The EU AI Act mandates conformity assessments for high-risk AI systems, compelling chipset vendors to embed audit trails and deterministic behavior into hardware architectures. China's GB standards and MIIT directives accelerate local alternatives to foreign IP cores. Stakeholders must now decide whether to pursue multi-source foundry strategies or deepen captive silicon design capabilities before regulatory bifurcation hardens into irreversible supply chain structures.
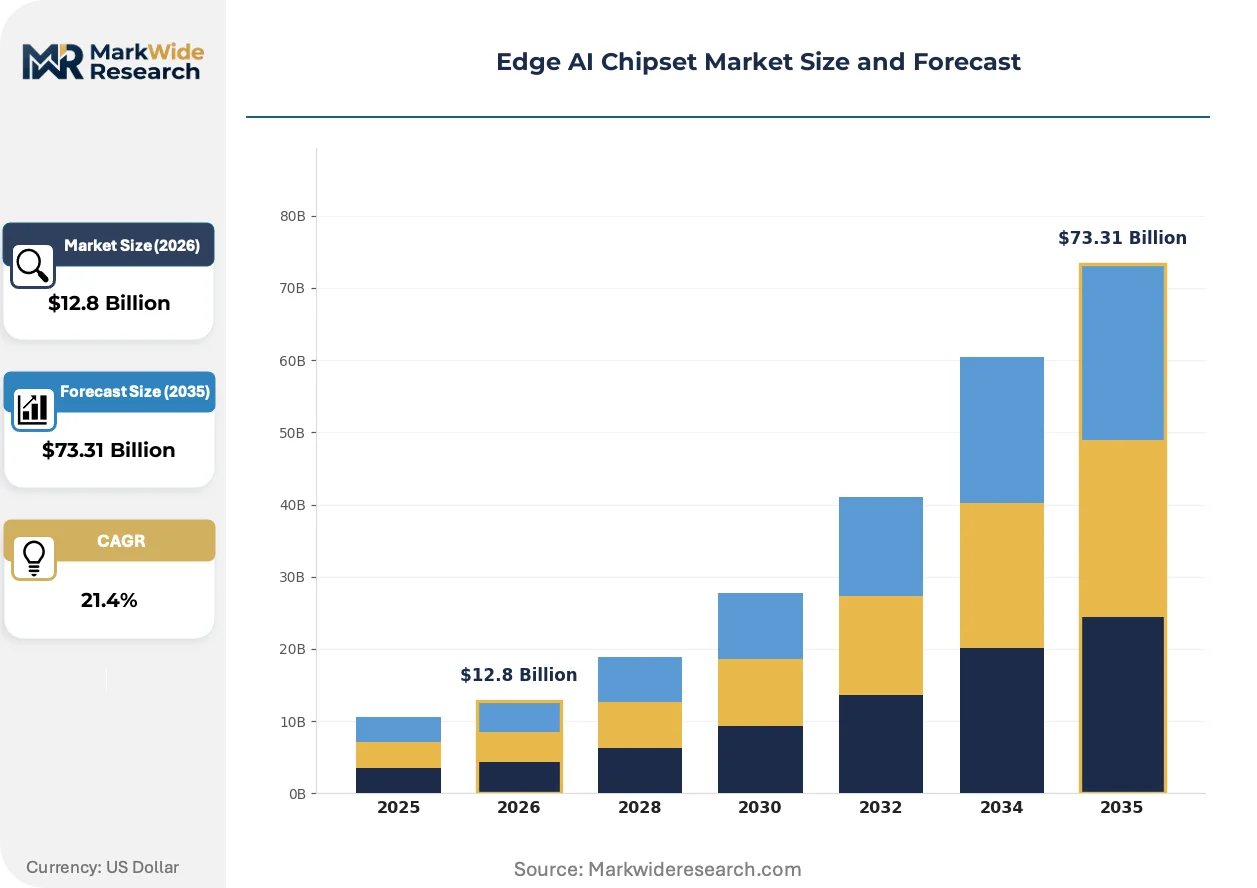
Market Dynamics
Automotive OEMs now embed inference engines directly into vehicle ECUs rather than routing through cloud gateways, redistributing compute loads from centralized data centers toward distributed edge nodes. This architectural pivot concentrates procurement decisions within Tier 1 suppliers and foundry partnerships.
Growth Catalysts
- EU AI Act conformity mandates:High-risk AI systems require embedded audit trails and deterministic hardware behavior, compelling chipset vendors to redesign architectures for regulatory compliance.
- Computer vision workload proliferation:Retail and transportation end users deploy real-time object detection at scale, driving demand for tensor processing units with sub-15 watt thermal envelopes.
- Hsinchu Science Park ecosystem concentration:TSMC's foundry capacity anchors fabless design houses, creating cluster effects that accelerate tape-out cycles for ASIC designs.
Market Restraints
- Advanced node capacity scarcity:Leading-edge foundry output remains concentrated among three suppliers, creating allocation bottlenecks for 5nm and below process technologies.
- US Bureau of Industry and Security export controls:Restrictions on AI chip shipments to specific foreign entities fragment supply chains and force duplicate mask sets for regional variants.
- FPGA power-performance ceiling:Reconfigurable logic architectures hit thermal limits in sustained inference workloads, ceding volume markets to fixed-function ASICs.
Strategic Opportunities
- RISC-V open ISA adoption:Industrial gateway manufacturers bypass ARM licensing fees by migrating control plane functions to royalty-free cores, opening margin expansion for captive silicon design.
- Medical imaging edge deployment:Real-time pathology screening at point-of-care sites creates demand for deterministic inference with FDA 510(k) pathway hardware.
- China MIIT localization directives:Domestic alternatives to foreign IP cores receive state funding, creating captive demand for locally-certified tensor accelerators.
Industry Challenges
- Neural architecture search talent scarcity:Automated chip design toolchains require rare combinations of hardware description language expertise and machine learning optimization skills.
- Multi-source foundry qualification timelines:Porting designs across process nodes demands 18-24 month revalidation cycles that compress product windows.
- Legacy automotive ECU integration complexity:New inference engines must interface with CAN bus architectures and ASIL-D safety systems through rigid certification frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge AI Chipset Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $73.31 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGA, ASIC, DSP, Microcontroller Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision End User: Manufacturing, Healthcare, Retail, Transportation Application: Smart Home, Robotics, Autonomous Vehicles, Surveillance |
| Companies Covered | NVIDIA Corporation, Qualcomm Technologies, Inc., Intel Corporation, Apple Inc., Samsung Electronics, Advanced Micro Devices, Inc., Alphabet Inc., Arm Limited, HiSilicon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge AI Chipset Market Shifts & Advancements
Chiplet-based disaggregation is fragmenting monolithic SoC designs into modular die assemblies, enabling mix-and-match compute, memory, and I/O components from heterogeneous process nodes. This architectural shift reconfigures vendor specialization and procurement patterns.
Deep learning accelerators are migrating from general-purpose GPU architectures toward domain-specific integrated circuits optimized for transformer and convolutional workloads. Automotive perception stacks adopt these fixed-function engines to compress latency budgets below 10 milliseconds for collision avoidance systems. The transition is migrating from prototyping phases into volume production contracts with foundry capacity reservations extending through 2027.
The EU AI Act's risk classification framework mandates hardware-level logging capabilities for high-risk deployment categories. Chipset vendors now embed non-volatile event counters and deterministic execution units to satisfy conformity assessment body requirements. Medical device manufacturers face the steepest compliance ramps as notified bodies interpret neural network interpretability standards.
Automotive OEMs now specify outcome-based performance guarantees rather than component specifications in procurement contracts. Tier 1 suppliers assume liability for perception system accuracy across defined operational design domains, shifting technical risk downstream. This contracting evolution is most visible in German and Japanese automotive supply chains where KBA and METI safety guidelines reinforce functional safety integration requirements.
Edge AI Chipset Market Segmentation
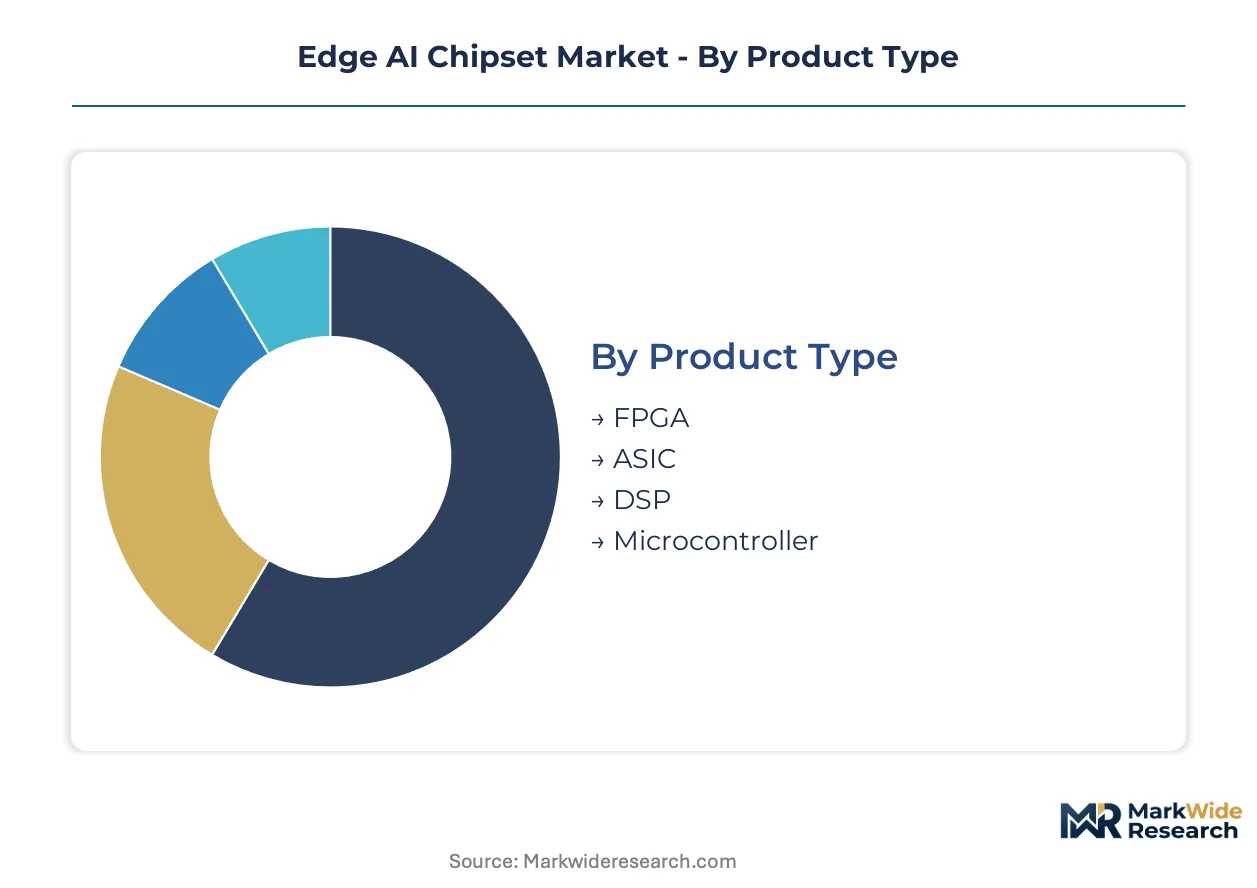
Edge AI chipset architectures fragment across competing implementation strategies. Product form factors, algorithmic workloads, deployment environments, and functional use cases each impose distinct thermal, latency, and cost constraints that reshape procurement patterns.
Product Type:
Cost tier stratification separates reprogrammable prototyping platforms from mass-production silicon optimized for unit economics at scale.
- FPGA:Field-programmable gate arrays deploy reconfigurable logic blocks that adapt to evolving neural network topologies without mask respins. Manufacturing and robotics prototyping in Germany's industrial corridors drives sustained demand despite thermal ceilings in sustained inference workloads.
- ASIC:Application-specific integrated circuits integrate fixed-function tensor processing units that minimize die area per operation. Surveillance networks across Taiwan and autonomous vehicle perception stacks in Japan justify mask costs through volume concentration.
- DSP:Digital signal processors handle audio and sensor fusion workloads with deterministic latency guarantees.
- Microcontroller:Low-wattage cores with embedded neural accelerators serve battery-constrained IoT endpoints.
ASIC commands the established base. The steepest expansion runs through FPGA as industrial prototyping cycles compress.
Technology:
Application maturity determines which algorithmic paradigms warrant dedicated silicon investment versus software emulation.
- Deep Learning:Convolutional and transformer architectures demand matrix multiplication engines with sparse weight compression. Computer vision workloads proliferate across retail inventory tracking in South Korea and transportation safety systems in Singapore.
- Computer Vision:Dedicated image signal processing pipelines with neural accelerators enable real-time object detection at the network edge.
- Machine Learning:Traditional statistical inference on structured data persists in industrial predictive maintenance gateways.
- Natural Language Processing:Transformer-based speech recognition and semantic parsing remain concentrated in cloud-assisted hybrid deployments due to model size constraints.
Deep Learning anchors volume shipments. Computer Vision climbs the fastest as edge camera deployments multiply.
End User:
Customer type segmentation reflects divergent certification requirements and procurement authority structures across vertical markets.
- Transportation:Automotive OEMs embed inference engines directly into vehicle ECUs, redistributing compute from centralized data centers. KBA safety guidelines and METI certification frameworks in Japan impose ASIL-D functional safety mandates on chipset architectures.
- Manufacturing:Factory automation systems demand deterministic latency below 10 milliseconds for robotic control loops.
- Healthcare:Point-of-care medical imaging requires FDA 510(k) pathway hardware with embedded audit trails for neural network interpretability.
- Retail:Inventory tracking and customer analytics deploy sub-15 watt thermal envelopes across distributed store footprints.
Transportation commands the established base. Healthcare shows the steepest expansion trajectory as regulatory clarity emerges for edge-based diagnostic screening.
Application:
Functional use cases impose distinct latency budgets and safety integrity levels that reshape silicon specification requirements.
- Autonomous Vehicles:Perception stacks compress collision avoidance response below 10 milliseconds through fixed-function inference engines. Tier 1 suppliers in Germany and Japan now assume liability for accuracy across defined operational design domains.
- Robotics:Proprioception and manipulation workloads favor reconfigurable architectures that adapt to task-specific neural topologies.
- Surveillance:Fixed-function ASICs dominate camera-on-chip designs where volume justifies mask costs and thermal constraints are relaxed.
- Smart Home:Voice assistants and ambient sensing operate within strict privacy boundaries that limit cloud dependency.
Surveillance commands the established base. Autonomous Vehicles gain share fastest as production contracts extend foundry reservations through 2027.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement offices in Stuttgart, Toyota City, and Detroit now dominate chipset demand as Tier 1 suppliers assume liability for perception system accuracy. Fabless design houses cluster near foundry capacity, creating geographic lock-in around Hsinchu, Austin, and Dresden. Regulatory fragmentation accelerates regional sourcing strategies.
United States
Autonomous vehicle developers in Austin and Detroit drive inference engine demand through outcome-based procurement contracts. The Bureau of Industry and Security export controls restrict advanced node shipments to specific foreign entities, fragmenting supply chains. TSMC's Arizona fab construction anchors Southwestern manufacturing expansion through 2027.
China
MIIT localization directives accelerate domestic alternatives to foreign IP cores for surveillance and industrial gateways. GB standards mandate conformity assessments for high-risk AI deployments, compelling hardware-level audit trails. The Yangtze River Delta cluster around Shanghai concentrates fabless design houses serving state-funded tensor accelerator programs.
Germany
KBA safety guidelines impose ASIL-D functional safety mandates on automotive inference architectures. Industrial automation corridors in Bavaria and Baden-Württemberg demand deterministic latency below 10 milliseconds for robotic control loops. Stuttgart-based OEMs now specify perception system guarantees rather than component specifications in Tier 1 contracts.
Japan
METI certification frameworks reinforce functional safety integration requirements for vehicular perception stacks. Robotics manufacturers in Nagoya and Osaka favor reconfigurable architectures adapting to task-specific neural topologies. The Kanto region around Tokyo anchors RISC-V adoption for industrial gateway control plane functions.
Taiwan
Hsinchu Science Park ecosystem concentration creates cluster effects accelerating ASIC tape-out cycles for computer vision workloads. TSMC foundry capacity anchors fabless design houses serving surveillance and autonomous vehicle markets. The island's advanced node output remains allocation-constrained for 5nm and below process technologies.
Edge AI Chipset Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market strategies. The vendor base stratifies between CUDA-anchored software ecosystems, Snapdragon-platform smartphone-to-automotive pipelines, and foundry-dependent fabless design houses. Three archetypes dominate: integrated device manufacturers with captive fabrication, fabless specialists with architecture-specific optimization, and intellectual property licensors with ISA control. Competitive moves concentrate on multi-source foundry qualification and deterministic hardware certification for regulatory compliance.
Within the integrated device manufacturer tier, NVIDIA Corporation and Intel Corporation exemplify divergent scale strategies. NVIDIA leverages CUDA software lock-in across robotics and autonomous systems. Intel sustains manufacturing scale through foundry investments supplying x86 and emerging RISC-V architectures. Qualcomm Technologies, Inc. occupies a position between these poles, anchoring the smartphone-to-automotive pipeline with Snapdragon platforms purpose-built for low-wattage inference.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Qualcomm Technologies, Inc. |
| Intel Corporation |
| Apple Inc. |
| Samsung Electronics |
| Advanced Micro Devices, Inc. |
| Alphabet Inc. |
| Arm Limited |
| HiSilicon Technologies |
| Others |
Supply & Pricing Matrix
TSMC's Hsinchu Science Park foundry concentration anchors wafer pricing power, compressing margin pools for fabless design houses while concentrating value capture upstream in Taiwan's advanced node ecosystem. Automotive OEMs and Tier 1 suppliers absorb this pricing pressure through long-term capacity reservation contracts that lock in allocation before tape-out cycles complete.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate procurement between fabless vendors and foundry partners, transferring commodity risk to buyers while securing margin for fabricators. Pricing stratifies across automotive-grade ASIL-D certification, industrial gateway reliability tiers, and consumer IoT economy segments. Cost compression in smartphone-derived inference chips is intensifying because Snapdragon-platform commoditization erodes premium positioning. Automotive OEMs exhibit the lowest price sensitivity due to liability exposure in perception systems, while retail surveillance integrators face acute margin pressure from volume-driven procurement.
Supply Chain Analysis
TSMC, Samsung Foundry, and Intel Foundry Services hold contract-manufacturing concentration for sub-7nm logic, with trailing-node capacity fragmented across GlobalFoundries, UMC, and SMIC. Geographic supply concentration centers on Taiwan, South Korea, and the southwestern United States where TSMC's Arizona fab construction proceeds. Raw material dependencies draw from neon gas extraction in Ukraine, fluorinated polyimide from Japan, and high-purity silicon wafers from Germany and Japan. Single-source vulnerability in EUV lithography equipment from ASML in the Netherlands creates chokepoint exposure. Distribution runs through direct foundry-fabless relationships for volume production, with FPGA prototyping flowing through Arrow and Avnet distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in edge AI chipsets rest on CUDA software ecosystem network effects that multiply switching costs for robotics and autonomous system developers. Regulatory entrenchment through EU AI Act conformity assessments further hardens incumbent positioning.
For Market Incumbents: Insulate architecture-specific optimization advantages by deepening RISC-V ISA control investments and securing multi-source foundry qualification across TSMC Arizona and Intel Foundry Services. Threats from Chinese MIIT-funded tensor accelerator programs demand accelerated deterministic hardware certification to maintain automotive Tier 1 supplier status. Capacity addition in southwestern US foundry nodes provides geographic diversification leverage against Taiwan Strait disruption scenarios.
For New Entrants and Emerging Players: Medical imaging edge deployment in German and Japanese point-of-care networks offers underpenetrated white space where FDA 510(k) and PMDA certification barriers filter incumbent competition. Industrial gateway control plane functions in Japan's Kanto region present a second penetrable segment through RISC-V royalty-free core migration. Go-to-market positioning should emphasize deterministic inference with embedded audit trail hardware to satisfy EU AI Act conformity mandates ahead of notified body interpretation solidification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless specialists holding automotive ASIC tape-out expertise but lacking foundry capacity reservation scale. Long-term viability across a 5-10 year window hinges on regulatory bifurcation hardening into irreversible supply chain structures. Acquisition target archetypes include domain-specific integrated circuit designers with transformer-optimized architectures and existing KBA or METI functional safety certification. Watch for Bureau of Industry and Security export control expansion signals as inflection indicators for regional sourcing strategy acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Foundry Qualification | Porting designs across TSMC, Intel, and Samsung nodes reduces allocation risk for automotive perception stacks. |
| Deterministic Hardware Certification | Embedded audit trails satisfy EU AI Act conformity assessments for high-risk AI system deployments. |
| RISC-V ISA Adoption | Royalty-free cores bypass ARM licensing fees for industrial gateway control plane functions in Japan. |
| Medical Imaging Edge Deployment | FDA 510(k) pathway hardware captures point-of-care pathology screening demand in German healthcare networks. |
| Automotive Tier 1 Partnership Deepening | Outcome-based procurement contracts shift liability downstream to suppliers with ASIL-D certified inference engines. |
Research Methodology
Cross-validation between primary interviews with automotive platform engineers, fabless design house technical leads, foundry procurement managers, and Tier 1 supplier quality directors anchors the qualitative findings. Secondary validation draws from SEC 10-K semiconductor filings, TSMC investor day capacity disclosures, EU AI Act implementing regulation texts, and MIIT directive announcements. Bottom-up triangulation across product type segmentation and top-down macroeconomic calibration ensures consistency across volume and value estimates.
Calibration against historical foundry utilization rates and automotive ECU production databases refines the analytical framework across the projection horizon. Segmentation dimensions modeled include chipset architecture, algorithmic workload type, end-user vertical, and regional regulatory cluster. CAGRs derive from weighted average growth across these segments with foundry capacity expansion schedules and export control policy trajectory as key forecast inputs.
Practitioners should monitor Bureau of Industry and Security entity list expansion, EU AI Act notified body guidance publication, and TSMC advanced node allocation announcements for early signals of forecast revision. Quarterly review of foundry utilization rates and automotive OEM perception stack procurement contract structures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
China Data Center Processor Market