
 Automotive Chip Market | 2026-2036
Automotive Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Chip Market Intelligence
Fleet operators and EV-native OEMs are gaining procurement influence as automotive chip demand is bifurcating between legacy internal-combustion architectures and electrified platforms. Infineon Technologies leverages its insulated-gate bipolar transistor and silicon carbide portfolio to anchor high-voltage powertrain contracts with European and Asian manufacturers. NXP Semiconductors dominates vehicle networking and secure connectivity solutions, sustaining design wins across gateway and domain-controller architectures.
Automotive chips are semiconductor devices engineered to operate across temperature extremes from minus 40 to 150 degrees Celsius, fabricated on 40-nanometer to 7-nanometer process nodes depending on compute intensity, and purpose-built for real-time control, sensing, and power conversion in vehicular environments. Microcontrollers retain the largest volume share as distributed electronic control units persist even with centralization trends, while silicon carbide power semiconductors command the fastest expansion due to their efficiency advantages in 800-volt EV architectures. Memory chips for autonomous driving data logging and over-the-air update buffering represent an emerging margin pool as compute requirements intensify.
The U.S. NHTSA and the European Union's F-Gas Regulation are reshaping chip specifications by mandating stricter thermal management and refrigerant compatibility in climate control systems, directly influencing sensor chip and analog IC designs. China's MIIT enforces domestic content requirements through GB standards and dual carbon goals, redirecting supply chain localization for power semiconductors and microcontrollers. Stakeholders must monitor how divergent regulatory timelines for autonomous vehicle certification across the U.S., Europe, and China fragment R&D investment and create asymmetric market access conditions.
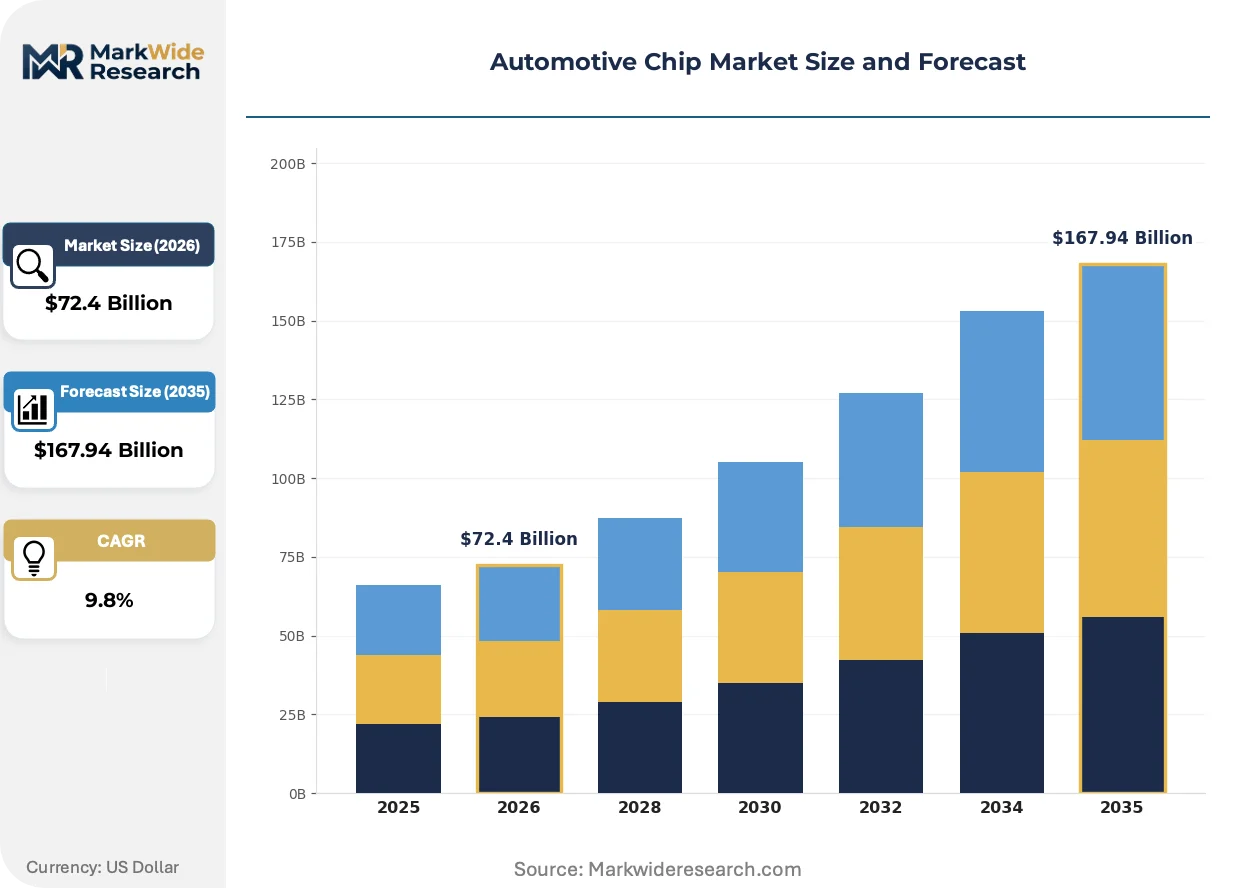
Market Dynamics
The automotive chip market is bifurcating as 800-volt EV architectures demand silicon carbide power semiconductors while legacy combustion platforms sustain microcontroller volumes, creating parallel procurement tracks with divergent qualification timelines and supplier bases.
Growth Catalysts
- EU F-Gas Regulation:Mandates refrigerant compatibility in climate control systems, forcing sensor chip redesigns that expand analog IC demand across European vehicle programs.
- Silicon carbide substrates:Enable 800-volt powertrains with 70% lower switching losses, accelerating adoption in premium EV platforms from domestic Chinese and Korean manufacturers.
- China's dual carbon goals:Drive MIIT enforcement of domestic content requirements through GB standards, redirecting power semiconductor procurement toward local foundries.
Market Restraints
- Neon gas supply concentration:Ukrainian and Russian neon purification facilities supply 90% of semiconductor-grade gas, exposing lithography operations to geopolitical disruption.
- 28-nanometer legacy node dependency:Automotive microcontrollers remain locked on mature processes where foundry capacity expansion lags behind EV production ramps.
- ISO 26262 functional safety certification:18-24 month validation timelines for ASIL-D rated components delay new supplier qualification and freeze design wins.
Strategic Opportunities
- India's PLI scheme for automotive:Creates captive demand for power semiconductors as Tata Motors and Mahindra electrify domestic fleets and export to ASEAN markets.
- Memory integration for autonomous data logging:LPDDR5 and GDDR6 buffers for sensor fusion represent unclaimed margin pools as compute intensity exceeds current DRAM provisioning.
- Over-the-air update infrastructure:Secure gateway chips for firmware delivery create recurring revenue attachment as OEMs monetize feature activation post-sale.
Industry Challenges
- Mixed-signal design talent scarcity:Expertise in combining high-voltage power management with precision analog sensing concentrates in Munich, Tokyo, and Austin, constraining new entrant hiring.
- Substrate thinning yield losses:Silicon carbide wafer dicing and back-grinding operations suffer 15-20% crack rates at 175-micron thicknesses, consuming capital without output guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chip Market |
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $167.94 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chip Type: Microcontrollers, Power Semiconductors, Sensor Chips, Analog ICs, Memory Chips, Digital Signal Processors Technology: CMOS, Bipolar, BiCMOS, Gallium Nitride, Silicon Carbide, Thin-Film Transistor Application: Infotainment Systems, Advanced Driver-Assistance Systems, Powertrain Control, Vehicle Networking, Energy Management, Climate Control End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Dealerships, Fleet Operators |
| Companies Covered | Infineon Technologies, NXP Semiconductors, STMicroelectronics, Texas Instruments, Renesas Electronics, ON Semiconductor, Robert Bosch, Analog Devices, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chip Market Strategic Shifts & Innovations
Chiplet-based architectures are fragmenting monolithic SoC designs, allowing automakers to mix process nodes and swap functional blocks without full retapes. This modularity is compressing development cycles and redrawing competitive boundaries between IDMs and fabless suppliers.
Gate-all-around transistor structures are miniaturizing logic density at 3-nanometer nodes for autonomous driving compute. NVIDIA and Qualcomm are adopting these geometries for central vehicle computers, though thermal constraints in engine-bay mounting locations limit deployment to cabin-domain controllers. The technology is miniaturizing form factors while forcing liquid-cooling investments that alter BOM cost structures.
The EU AI Act's risk classification system is mandating deterministic behavior validation for safety-critical neural network accelerators. Chip vendors must submit formal verification evidence for pedestrian detection and lane-keeping models, extending qualification timelines by 8-12 months for European-bound systems. German TÜV and DEKRA certifiers are consolidating preferred supplier lists based on traceability documentation depth.
Fleet operators are consolidating semiconductor procurement through direct foundry relationships, bypassing tier-one module suppliers. Amazon's Rivaria logistics subsidiary and DHL's electric van deployments specify chip-level sourcing contracts with Infineon and NXP, extracting volume pricing unavailable to smaller OEMs. This concentration is visible most acutely in California and the Netherlands where zero-emission fleet mandates accelerate vehicle refresh cycles.
Automotive Chip Market Segmentation
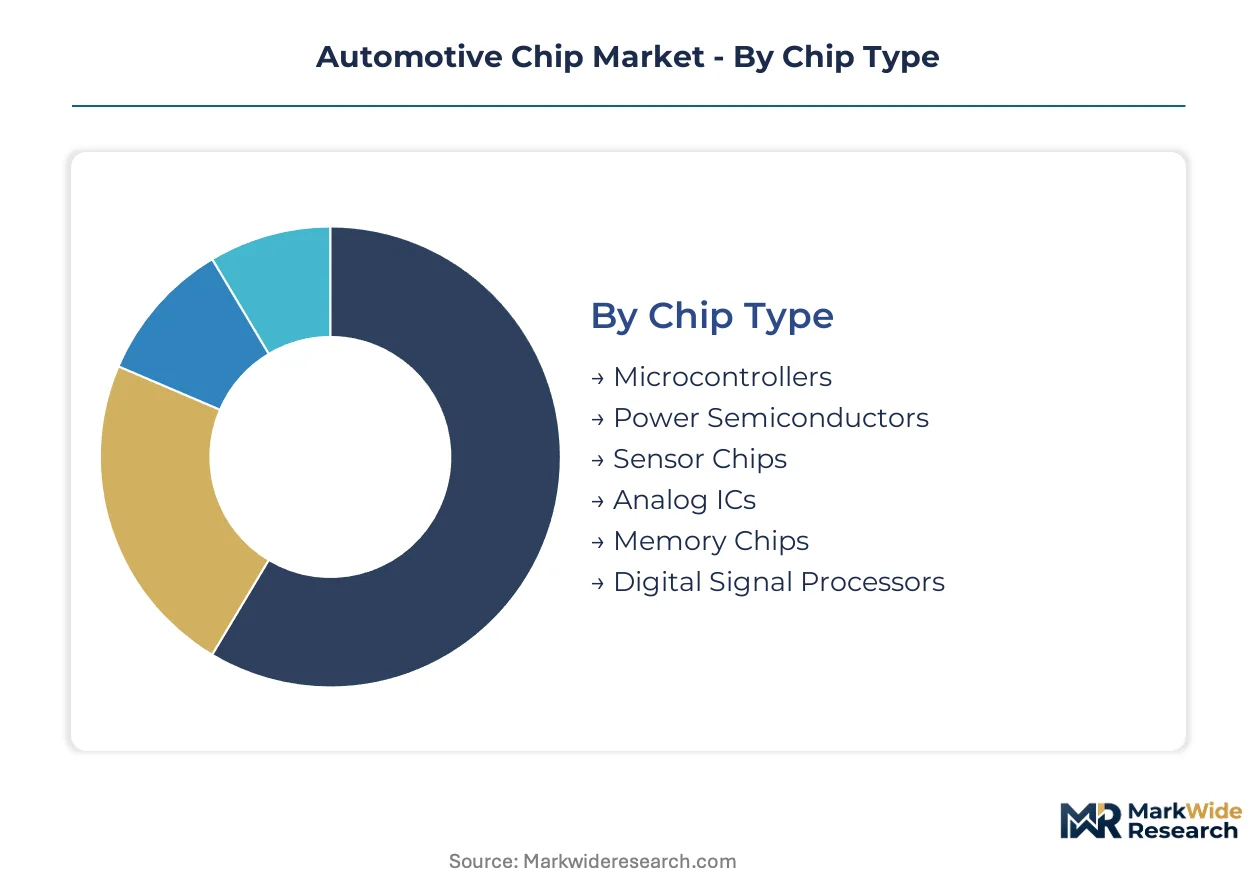
Automotive chip procurement splits across incompatible qualification timelines and divergent margin structures. Powertrain electrification and autonomous driving compute are fragmenting supplier relationships as legacy microcontroller volumes persist alongside silicon carbide expansion.
Chip Type:
Margin pools concentrate in power conversion and precision sensing where thermal performance commands premium pricing.
- Microcontrollers:Distributed electronic control units execute real-time engine management and chassis functions on 40-nanometer to 90-nanometer nodes. Demand concentrates in legacy combustion platforms across German and Japanese OEM supply chains where functional safety certification locks in incumbent suppliers.
- Power Semiconductors:Insulated-gate bipolar transistors and silicon carbide MOSFETs manage 400-volt to 800-volt powertrain architectures with switching efficiencies above 98%. Procurement from Chinese EV manufacturers is accelerating fastest as domestic foundries scale 6-inch silicon carbide substrate capacity.
- Sensor Chips:MEMS accelerometers, radar front-ends, and image sensors enable environmental perception for active safety systems.
- Analog ICs:Voltage regulators and signal conditioning circuits bridge digital processors with physical actuators.
- Memory Chips:LPDDR5 and GDDR6 buffers cache sensor data for autonomous driving compute clusters.
- Digital Signal Processors:Dedicated audio and radar processing engines offload compute from central domain controllers.
The dominant share belongs to Microcontrollers, while Power Semiconductors is closing the gap fastest.
Technology:
Process selection tracks voltage requirements and switching frequency demands across vehicle domains.
- CMOS:Complementary metal-oxide-semiconductor logic dominates digital compute and networking functions from 7-nanometer advanced nodes to 130-nanometer legacy processes. Infotainment system-on-chip designs from Qualcomm and NVIDIA utilize CMOS for cabin-domain centralization.
- Silicon Carbide:Wide-bandgap substrates enable 1,200-volt blocking voltages with thermal conductivity three times silicon. Traction inverter demand from Korean and Chinese battery-electric platforms is expanding most quickly as 800-volt architectures proliferate.
- Bipolar:High-current discrete devices persist in starter motors and legacy lighting control.
- BiCMOS:Mixed-signal integration serves precision sensor interfaces and RF transceivers.
- Gallium Nitride:High-electron-mobility transistors target on-board chargers and DC-DC converters below 650 volts.
- Thin-Film Transistor:Display backplane drivers for curved instrument clusters and head-up displays.
CMOS commands volume leadership, though Silicon Carbide is gaining share fastest in electrified powertrains.
Application:
Content value per vehicle varies tenfold across domains from climate control to autonomous compute.
- Advanced Driver-Assistance Systems:Sensor fusion processors, neural network accelerators, and redundant safety controllers execute lane-keeping and emergency braking. European type-approval requirements under EU AI Act risk classification are extending validation timelines for German-bound vehicle programs.
- Powertrain Control:Battery management systems and motor control units govern torque delivery and cell balancing. Chinese MIIT enforcement of GB standards for domestic semiconductor content is redirecting procurement toward local microcontroller suppliers.
- Infotainment Systems:Cabin-domain processors render navigation, media, and voice interfaces.
- Vehicle Networking:Gateway chips and Ethernet switches manage zonal architecture data flows.
- Energy Management:DC-DC converters and on-board chargers optimize battery-to-motor efficiency.
- Climate Control:Compressor drivers and refrigerant pressure sensors comply with EU F-Gas Regulation thermal specifications.
Powertrain Control holds the largest share, while Advanced Driver-Assistance Systems is climbing the fastest.
End User:
Procurement authority is shifting from tiered supply chains toward direct OEM and fleet operator relationships.
- OEMs:Volkswagen, Toyota, and BYD specify chip-level requirements for domain controllers and power modules. Direct foundry contracting is concentrating in premium EV platforms where semiconductor content exceeds 1,500 dollars per vehicle.
- Fleet Operators:Amazon's Rivaria and DHL specify chip sourcing terms for zero-emission van deployments. California and Netherlands fleet mandates are accelerating volume pricing extraction unavailable to smaller OEMs.
- Tier-1 Suppliers:Bosch and Continental aggregate chip procurement for module-level integration.
- Vehicle Assemblers:Contract manufacturers execute build-to-print assembly with specified component lists.
- Aftermarket Providers:Replacement module suppliers serve aging vehicle parc repair demand.
- Dealerships:Service centers procure diagnostic and reprogramming tools with embedded chipsets.
OEMs retain dominant procurement share, though Fleet Operators are gaining influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater container terminals and Shanghai's wafer fabrication clusters anchor China's procurement dominance in automotive semiconductors.
China
Domestic EV brands BYD and NIO are accelerating silicon carbide procurement for 800-volt platforms. MIIT enforces GB standards for domestic semiconductor content under dual carbon goals. Yangtze River Delta foundries in Shanghai and Wuxi are scaling 6-inch silicon carbide substrate capacity to serve local battery-electric manufacturers.
Germany
Premium OEMs Volkswagen and BMW are specifying domain controllers with ASIL-D functional safety ratings. EU F-Gas Regulation mandates refrigerant-compatible sensor designs for climate control systems. Bavaria's Munich-Stuttgart corridor concentrates mixed-signal design talent at Infineon and Bosch headquarters.
United States
Fleet operators Amazon Rivaria and DHL are extracting volume pricing through direct foundry contracts for zero-emission van deployments. NHTSA thermal management mandates influence sensor chip specifications for climate systems. Austin's semiconductor corridor hosts design centers for power management and precision analog.
Japan
Toyota and Honda sustain microcontroller demand through legacy combustion platform refreshes. METI subsidizes domestic 40-nanometer automotive foundry capacity to reduce import dependency. Kyushu's Kumamoto prefecture hosts Renesas fabrication facilities serving hybrid powertrain control modules.
South Korea
Hyundai and Kia are adopting silicon carbide traction inverters for 800-volt E-GMP architectures. MFDS coordinates with automotive regulators on functional safety certification alignment. Busan-Ulsan's industrial belt concentrates power semiconductor packaging operations for export to ASEAN markets.
Automotive Chip Market Key Industry Players
Concentration sits with integrated device manufacturers possessing captive fabrication and automotive qualification expertise. The vendor base stratifies across three tiers: diversified semiconductor conglomerates with multi-product portfolios, pure-play automotive specialists with deep OEM relationships, and emerging power semiconductor challengers from Asia. Dominant competitive moves include capacity expansion at silicon carbide substrate facilities and strategic partnerships for chiplet-based architecture development.
Within the diversified conglomerate tier, Infineon Technologies and NXP Semiconductors exemplify European-based suppliers with established domain controller and powertrain positions. STMicroelectronics occupies a comparable position with strength in silicon carbide and mixed-signal integration. These three anchors demonstrate how automotive qualification timelines and functional safety certification create defensive moats against new entrant disruption.
| Leading Market Players |
|---|
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| Renesas Electronics |
| ON Semiconductor |
| Robert Bosch |
| Analog Devices |
| Microchip Technology |
| Others |
Cost & Logistics Intelligence
ISO 26262 functional safety certification gates both supplier qualification timelines and price differentiation simultaneously, with ASIL-D rated components commanding sustained premiums while uncertified alternatives face procurement exclusion from German and Japanese OEM supply chains.
Pricing Analysis
Volume-discount tiering separates fleet operators from smaller OEMs and aftermarket providers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with silicon carbide power modules anchoring the premium band. Cost compression in microcontroller tiers is intensifying because 28-nanometer foundry capacity constraints limit supply elasticity. Fleet operators exhibit lowest price sensitivity due to direct foundry contracting power, while aftermarket providers face margin pressure from inventory holding costs.
Supply Chain Analysis
Just-in-time inventory preferences dominate legacy microcontroller procurement, while strategic stockpiling of silicon carbide substrates is accelerating among Chinese and Korean battery-electric manufacturers. Supply concentrates in Taiwan, South Korea, and Japan for advanced node fabrication, with Germany and China anchoring automotive-qualified packaging and testing. Neon gas purification from Ukrainian and Russian facilities feeds lithography operations, exposing the chain to geopolitical disruption. Distribution runs through tier-1 module suppliers for combustion platforms and direct OEM contracting for electrified architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Over-the-air update infrastructure and secure firmware delivery represent a service-attach opportunity expanding faster than hardware, with recurring revenue from feature activation post-sale reshaping supplier economics.
For Market Incumbents: Fortify silicon carbide substrate supply through captive capacity expansion in Shanghai and Dresden corridors, locking in 800-volt platform design wins before Chinese foundries achieve cost parity. Deepen functional safety certification moats by accelerating ASIL-D validation for neural network accelerators ahead of EU AI Act enforcement, neutralizing fabless entrants lacking automotive qualification expertise. For New Entrants and Emerging Players: Differentiate on memory integration for autonomous data logging, where LPDDR5 and GDDR6 buffer demand outstrips current DRAM provisioning from incumbent suppliers. Target India's PLI scheme beneficiary OEMs—Tata Motors and Mahindra—as the most penetrable procurement entry point, leveraging local power semiconductor packaging partnerships to bypass tier-1 gatekeeping. For Investors and Strategic Acquirers: EU AI Act risk classification reshapes the acquisition landscape by extending validation timelines and consolidating preferred supplier lists around traceability documentation depth. Long-term viability favors targets with mixed-signal design talent concentration in Munich, Tokyo, or Austin corridors. Watch neon gas supply diversification efforts as the signal indicating geopolitical risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Captive 6-inch wafer supply locks in 800-volt traction inverter contracts with BYD and Hyundai. |
| Chiplet-Based Architecture Development | Modular SoC designs compress development cycles for NVIDIA and Qualcomm central vehicle computers. |
| Functional Safety Certification Investment | ASIL-D validation ahead of EU AI Act deadlines secures German TÜV preferred supplier status. |
| Direct Foundry Contracting with Fleet Operators | Volume pricing extraction from Amazon Rivaria and DHL bypasses tier-1 margin capture. |
| Memory Integration for Autonomous Compute | LPDDR5 buffers for sensor fusion address unclaimed margin pools in data logging infrastructure. |
Research Approach
Cross-validation between OEM platform engineering disclosures and tier-1 supplier procurement data anchors the qualitative findings, with primary interviews conducted across semiconductor vendor strategy leads, automotive procurement officers, and foundry operations directors triangulated against secondary validation from SEC filings, IHS Markit vehicle production databases, and MIIT GB standards documentation.
Sensitivity analysis frames the forecast construction across vehicle class, propulsion architecture, and content per vehicle dimensions, with CAGRs derived from bottom-up build of semiconductor content per vehicle multiplied by production volume forecasts across the projection horizon. Neon gas supply scenarios and silicon carbide yield improvement curves constitute key automotive-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained 800-volt platform adoption rates or accelerated EU AI Act enforcement timelines would require recalibration. Revision becomes warranted when geopolitical disruption to lithography gas supply crosses threshold levels affecting foundry utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
PC Processor Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Display Driver Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
System on Chip (Soc) Market