
 Indonesia Data Center Processor Market | 2026-2036
Indonesia Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Processor Market Insights
Indonesia is reconfiguring its data center infrastructure landscape through accelerated facility construction in Batam and Greater Jakarta. Intel Corporation leverages its x86 architecture dominance to anchor enterprise on-premises deployments across Indonesian banking and telecom sectors. NVIDIA Corporation specializes in GPU acceleration for AI training workloads, sustaining premium positioning among cloud providers building hyperscale facilities in Cikarang and BSD City.
Data center processors are integrated circuits engineered for continuous high-throughput computation, typically fabricated on advanced process nodes with thermal design power ratings exceeding 150 watts for server-grade units, designed to orchestrate virtualization, database management, and distributed analytics across rack-mounted systems. GPU segments lead value capture as Indonesian cloud providers prioritize parallel compute for generative AI and large language model inference. CPU categories maintain volume dominance in traditional enterprise virtualization and legacy workload consolidation, while TPU adoption remains nascent among early-adopter fintech and e-commerce platforms experimenting with custom silicon.
Indonesia's Ministry of Communication and Informatics, alongside BIS-equivalent standards bodies, enforces electromagnetic compatibility and energy efficiency certification for imported processors, directly shaping supplier eligibility and procurement timelines for domestic data center operators. The country's national cybersecurity regulator mandates data localization requirements that stimulate local processor demand for sovereign cloud deployments. Stakeholders must monitor evolving domestic content regulations and cooling efficiency standards as facility densities rise across the archipelago's emerging digital infrastructure clusters.
Market Dynamics
Indonesia's data center processor market is being fundamentally restructured by the Ministry of Communication and Informatics' data localization mandates, which compel domestic deployment of sovereign cloud infrastructure and reshape procurement patterns across banking and telecommunications verticals.
Growth Catalysts
- Hyperscale Cloud Expansion:Alibaba Cloud, AWS, and Google Cloud are commissioning facilities in Cikarang and BSD City, concentrating demand for high-throughput processors in Greater Jakarta's digital corridor.
- BIS-equivalent Certification Alignment:Streamlined electromagnetic compatibility testing for imported server-grade processors is reducing procurement timelines for domestic operators by eliminating redundant technical validation cycles.
- AI Training Workload Proliferation:Fintech platforms and e-commerce marketplaces are deploying generative AI infrastructure, accelerating GPU adoption for large language model inference.
Market Restraints
- Advanced Node Supply Concentration:Fabrication of sub-5nm server processors depends on TSMC's Taiwan facilities and Samsung's Pyeongtaek complex, exposing Indonesian operators to geopolitical transit risks.
- Cooling Infrastructure Cost Structure:Tropical ambient temperatures necessitate precision liquid cooling systems, elevating facility capex by 40-60% versus temperate climate deployments.
- Custom Silicon Substitution Threat:Google's TPU and Amazon's Trainium are displacing merchant GPU purchases in hyperscale accounts with captive chip development programs.
Strategic Opportunities
- Batam Free Trade Zone Expansion:The island's proximity to Singapore and duty-exempt status positions it for processor assembly and testing operations serving ASEAN cloud markets.
- Edge Computing Convergence:5G network rollouts by Telkomsel and XL Axiata are creating distributed inference nodes requiring low-power AI accelerators outside Jakarta's core.
- Domestic Content Incentives:Ministry of Industry local content certification (TKDN) offers preferential tax treatment for data centers deploying processors with Indonesian assembly or packaging.
Industry Challenges
- Thermal Design Expertise Gap:Local engineering talent shortages in high-density cooling system design are extending facility commissioning timelines by 8-14 months.
- Legacy Virtualization Integration:Banking sector mainframe-to-cloud migrations require x86 processors with mainframe emulation capabilities, complicating vendor selection and certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Processor Market |
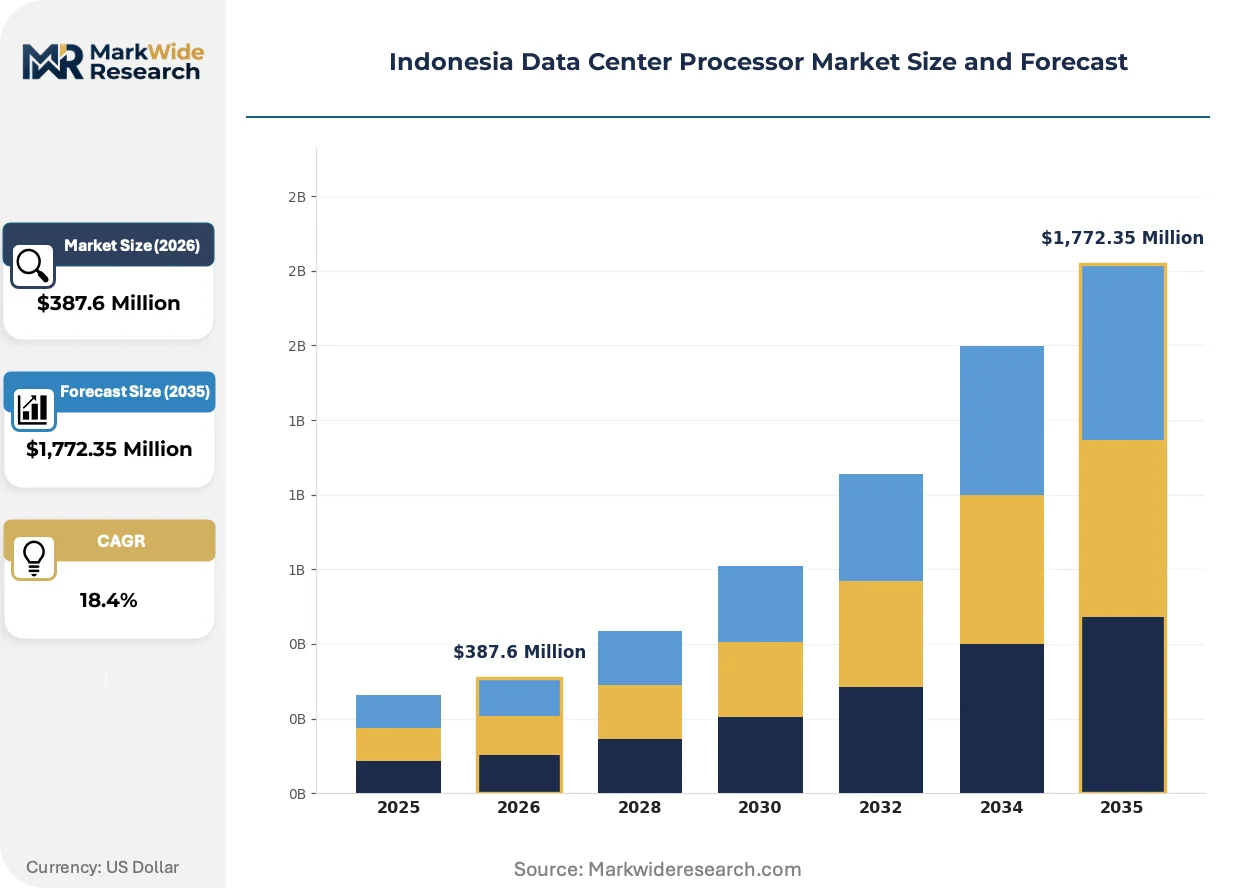
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPUs, GPUs, TPUs, FPGAs End User: Cloud Providers, Telecom Operators, Enterprises, Managed Service Providers Application: Cloud Computing, Big Data Analytics, AI Processing, Virtualization Deployment Model: On-Premises, Colocation, Hybrid, Public Cloud |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices, Inc., Ampere Computing LLC, IBM Corporation, Qualcomm Incorporated, ARM Holdings, Marvell Technology, Broadcom Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Processor Market Trends and Innovations
Processor architectures are fragmenting across workload-specific optimization, with Indonesian operators navigating competing imperatives for AI acceleration, legacy compatibility, and sovereign compliance.
Chiplet-based modular processor designs are decomposing monolithic server CPUs into discrete compute, memory, and I/O tiles. Indonesian cloud providers are evaluating AMD's EPYC and Intel's Granite Rapids implementations for flexibility in customizing core-to-memory ratios. This disaggregation is rendering obsolete the one-size-fits-all socket strategy that dominated enterprise procurement through 2023.
Indonesia's Ministry of Communication and Informatics is enforcing stricter energy efficiency standards for imported data center equipment, modeled on EU Code of Conduct for Data Centre Energy Efficiency frameworks. Facility operators must now submit power usage effectiveness documentation alongside processor procurement applications. Hyperscale deployments in Cikarang are responding by specifying processors with dynamic frequency scaling and advanced sleep-state management.
Cloud providers are consolidating vendor relationships around direct-to-OEM procurement models, bypassing traditional distribution channels for high-volume GPU and CPU purchases. This concentration is compressing margins for Indonesian systems integrators while accelerating technical support responsiveness. The shift is most visible among e-commerce platforms building proprietary inference infrastructure in Jakarta's digital corridor.
Indonesia Data Center Processor Market Segmentation
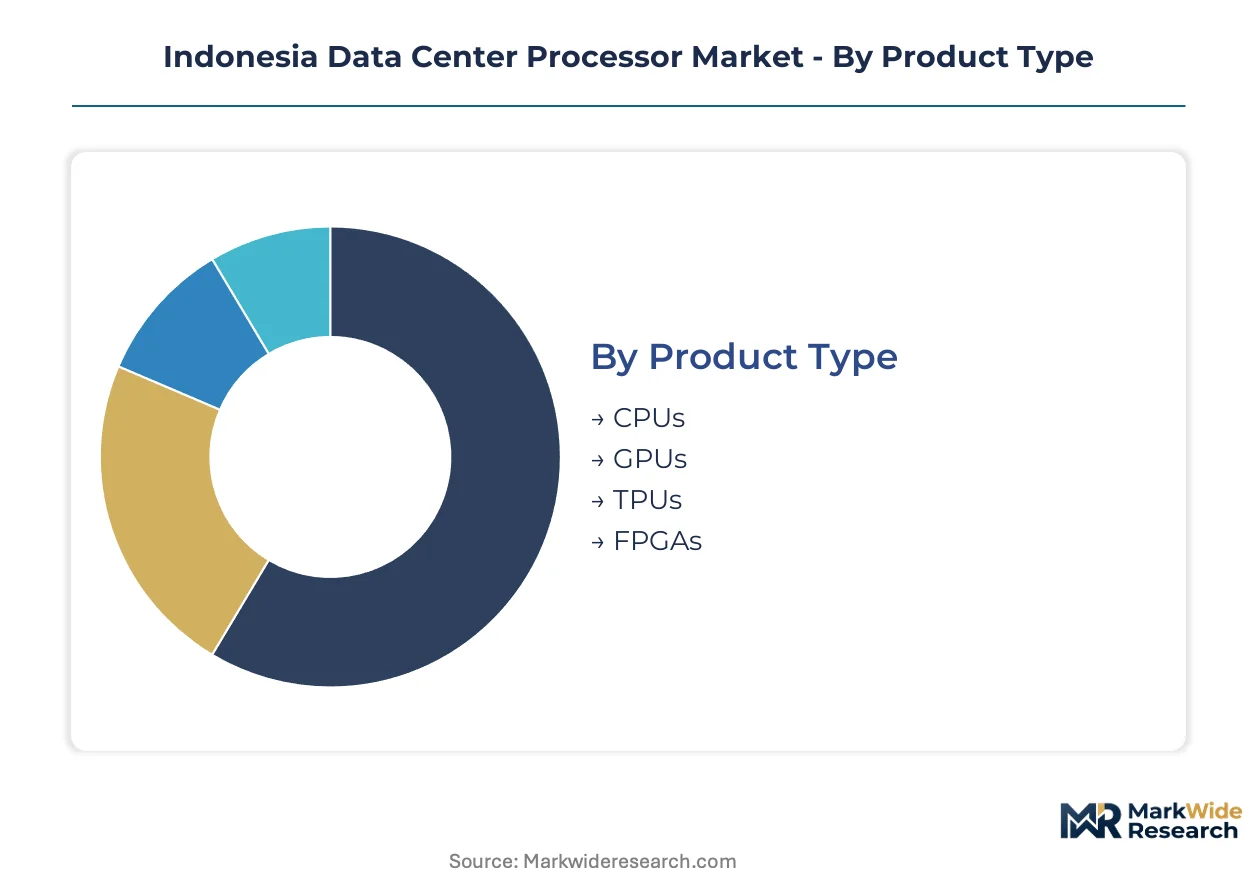
Processor segmentation in Indonesia reflects divergent workload requirements across sovereign cloud mandates, tropical thermal constraints, and AI infrastructure buildouts. Understanding category boundaries enables operators to optimize procurement against BIS-equivalent certification timelines and cooling capex differentials.
Product Type:
Processing architectures span general-purpose compute through workload-optimized accelerators, with thermal design power and parallelization granularity driving deployment economics across Java and Sumatra facilities.
- CPUs:x86 and ARM-based processors orchestrate virtualization, database management, and legacy enterprise workloads. Banking and telecommunications operators in Jakarta's digital corridor deploy these for mainframe emulation and sovereign cloud control planes, constrained by per-socket software licensing models that favor high core-count configurations.
- GPUs:Massively parallel tensor processors fabricated on advanced nodes enable training and inference for large language models. Cloud providers building hyperscale facilities in Cikarang and BSD City concentrate procurement here, driven by generative AI service rollouts and fintech model development pipelines.
- TPUs:Google's custom matrix multiplication accelerators offer deterministic latency for specific TensorFlow workloads. Early adoption concentrates among e-commerce platforms with captive ML engineering teams experimenting with custom silicon procurement outside merchant GPU supply chains.
- FPGAs:Reconfigurable logic devices provide deterministic low-latency processing for network function virtualization and financial tick analytics. Telkomsel and XL Axiata evaluate these for 5G core user plane acceleration at distributed edge nodes.
The dominant share belongs to CPUs, while GPUs are closing the gap fastest.
End User:
Customer archetypes exhibit distinct procurement rhythms, with hyperscale cloud operators driving volume through direct OEM relationships while enterprises navigate extended certification cycles.
- Cloud Providers:Alibaba Cloud, AWS, and Google Cloud commission facilities with 50+ megawatt capacities, specifying processors through confidential supply agreements that bypass distribution channels. Their procurement velocity sets price discovery for the entire Indonesian market.
- Telecom Operators:Telkomsel, Indosat Ooredoo Hutchison, and XL Axiata deploy processors for 5G core infrastructure and edge computing nodes. These operators balance capital efficiency against network latency requirements for fixed wireless access and mobile broadband services.
- Enterprises:Banking conglomerates and state-owned enterprises maintain on-premises deployments for regulatory data localization compliance. Their procurement cycles extend 12-18 months due to BIS-equivalent certification requirements and internal security review boards.
- Managed Service Providers:Domestic systems integrators and global IT outsourcers aggregate demand across mid-market clients. These intermediaries face margin compression as cloud providers consolidate direct vendor relationships.
Cloud providers command volume leadership, though telecom operators are expanding procurement fastest as 5G infrastructure scales.
Application:
Workload categories map directly to processor architecture selection, with AI training demands reshaping silicon priorities across the archipelago.
- Cloud Computing:General-purpose Infrastructure-as-a-Service and Platform-as-a-Service workloads. Indonesian sovereign cloud deployments prioritize x86 processors with virtualization extensions for multi-tenant isolation.
- Big Data Analytics:Distributed batch processing across petabyte-scale datasets. Financial services and e-commerce marketplaces in Jakarta drive demand for high-memory-bandwidth configurations.
- AI Processing:Training and inference for computer vision, natural language processing, and recommendation systems. This application category commands premium processor pricing and concentrates GPU procurement among hyperscale operators.
- Virtualization:Legacy workload consolidation and private cloud infrastructure. Enterprise data centers across Java deploy processors with hardware-assisted virtualization for mainframe migration projects.
Cloud Computing retains the largest installed base, yet AI Processing exhibits the steepest expansion trajectory.
Deployment Model:
Facility ownership structures determine processor procurement autonomy, with colocation and hybrid models gaining traction among cost-conscious enterprises.
- On-Premises:Enterprise-owned facilities with full hardware control. Banking regulators mandate this model for core banking systems, driving demand for processors with hardware security modules and tamper-evident packaging.
- Colocation:Leased space in third-party data centers with customer-supplied or landlord-supplied IT equipment. DCI Indonesia and NTT Ltd. facilities in Greater Jakarta offer processor procurement flexibility with standardized power and cooling.
- Hybrid:Orchestrated workloads across on-premises and cloud infrastructure. Enterprises adopt processors with consistent instruction set architectures to minimize application refactoring costs.
- Public Cloud:Fully managed infrastructure with abstracted hardware layers. End customers cede processor selection to cloud operators, who optimize for density and thermal efficiency at fleet scale.
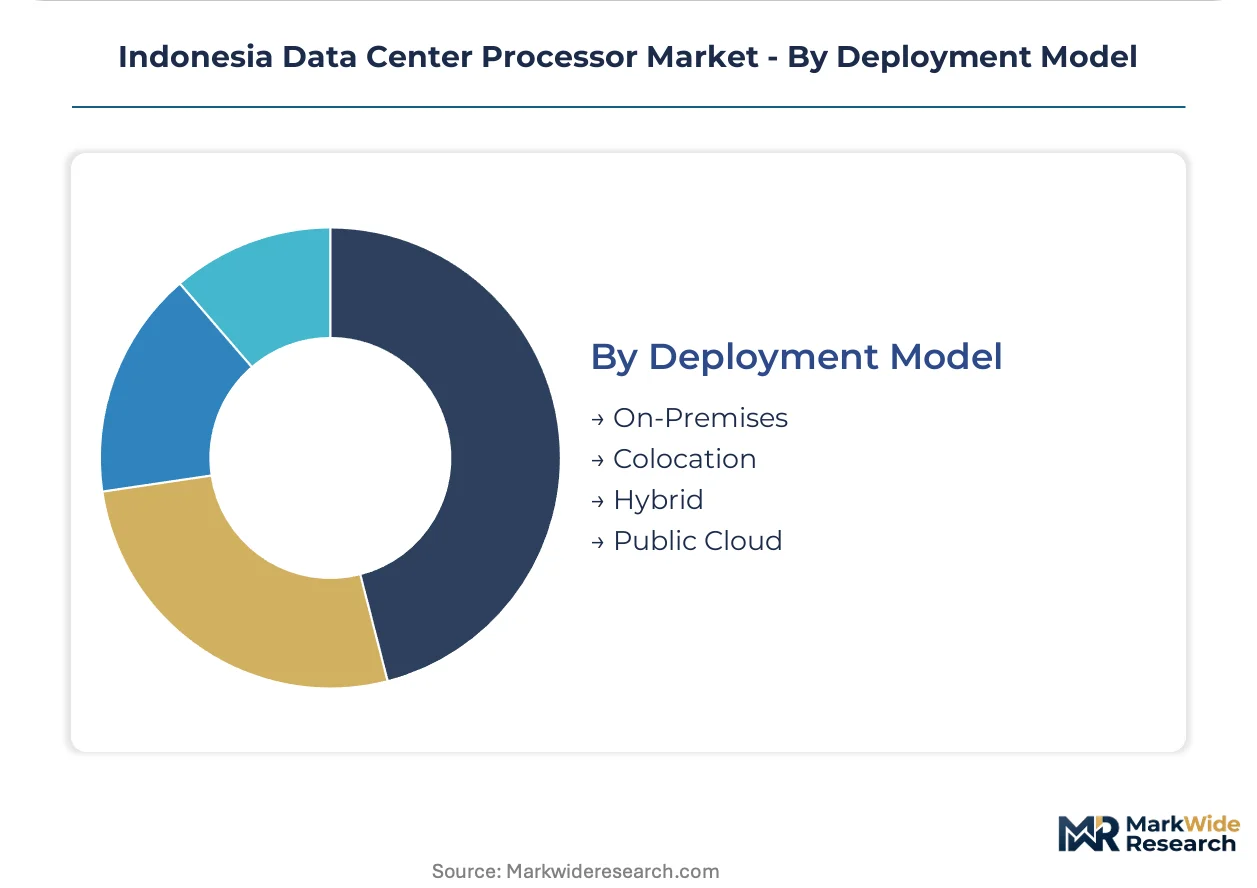
On-Premises deployments still dominate regulated verticals, while Colocation is gaining share fastest among mid-market enterprises seeking capex flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Java toll road and Jakarta-Surabaya fiber backbone anchor Indonesia's data center processor demand, concentrating procurement in Greater Jakarta while Batam's free trade zone attracts assembly operations serving ASEAN cloud markets.
Greater Jakarta
Hyperscale cloud operators Alibaba Cloud, AWS, and Google Cloud commission 50+ megawatt facilities in Cikarang and BSD City. The Ministry of Communication and Informatics enforces data localization mandates that compel domestic processor deployment for sovereign cloud infrastructure. Jakarta's digital corridor concentrates GPU procurement for generative AI training workloads across fintech and e-commerce platforms.
West Java
Enterprise banking and telecommunications operators maintain on-premises deployments for regulatory compliance in Bandung and Bogor. BIS-equivalent certification requirements extend procurement timelines to 12-18 months for server-grade processors. Industrial zones around Cikarang host colocation facilities from DCI Indonesia and NTT Ltd. offering standardized power and cooling infrastructure.
Batam
The free trade zone's duty-exempt status and proximity to Singapore position it for processor assembly and testing operations. Ministry of Industry TKDN certification offers preferential tax treatment for data centers deploying processors with Indonesian packaging. Cloud providers evaluate Batam for edge computing nodes serving Riau Islands and Sumatra distributed workloads.
East Java
Surabaya's emerging digital infrastructure attracts secondary data center development from domestic operators seeking lower land costs than Jakarta. Telkomsel and Indosat Ooredoo Hutchison deploy 5G core processors for network function virtualization across East Java's industrial corridor. Cooling infrastructure costs run 40-60% above temperate benchmarks due to tropical ambient temperatures.
North Sumatra
Medan serves as a distribution node for processor shipments to Sumatra's expanding enterprise market. XL Axiata evaluates low-power AI accelerators for distributed inference nodes outside Jakarta's core. Local engineering talent shortages in high-density cooling design extend facility commissioning timelines by 8-14 months across the region.
Indonesia Data Center Processor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base concentrates around x86 architecture incumbents and GPU acceleration specialists, with ARM-based challengers gaining traction in cloud-native workloads. Three archetypes dominate: full-stack platform vendors with captive silicon development, merchant semiconductor suppliers selling through OEM channels, and fabless architecture licensors enabling custom processor designs. Competitive dynamics center on direct-to-hyperscale procurement consolidation and chiplet-based modular design partnerships that bypass traditional distribution.
Among US-based semiconductor giants, Intel Corporation and NVIDIA Corporation anchor the established tier, their presence exemplifying divergent strategic positioning around general-purpose compute versus parallel acceleration. Advanced Micro Devices, Inc. occupies a hybrid position, challenging incumbents across both CPU and GPU segments. These three names represent the competitive core around which Indonesian cloud providers and enterprises structure procurement decisions, with each anchoring distinct workload optimization philosophies.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Advanced Micro Devices, Inc. |
| Ampere Computing LLC |
| IBM Corporation |
| Qualcomm Incorporated |
| ARM Holdings |
| Marvell Technology |
| Broadcom Inc. |
| Others |
Pricing and Supply Chain Analysis
TSMC's N3E node undercapacity across Hsinchu and Taichung Science Parks is compressing lead times for Indonesian cloud providers while elevating spot-market premiums for GPU allocations, forcing procurement teams to pre-commit volumes eighteen months ahead of facility commissioning.
Pricing Analysis
BIS-equivalent certification dictates the pricing tier structure across Indonesian data center processor procurement. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade silicon with full TKDN compliance from uncertified merchant volumes and refurbished server pulls. Price differentiation stems from certification grade and volume scale, with hyperscale direct-of-take agreements commanding 30-40 point discounts over distributor-mediated enterprise purchases. Cost compression in the standard tier is intensifying because Alibaba Cloud and AWS are consolidating vendor relationships around confidential supply agreements. Banking sector buyers exhibit highest price sensitivity due to extended 12-18 month procurement cycles and board-level capex scrutiny, while sovereign cloud operators demonstrate lowest sensitivity given regulatory mandate urgency.
Supply Chain Analysis
Advanced silicon feedstock draws from Taiwan's foundry complex, South Korea's Pyeongtaek memory cluster, and Malaysia's Penang packaging corridor. Raw material dependencies center on EUV-grade photoresist, high-purity silicon wafers, and cobalt-plated interconnect substrates. Single-source vulnerability concentrates at TSMC's 3nm and 5nm fabrication nodes, exposing Indonesian operators to transit disruption through the Strait of Malacca. Distribution runs through Singapore's entrepôt hub for ASEAN customs clearance, with final-mile logistics handled by domestic systems integrators in Cikarang and BSD City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Processor architecture fragmentation across AI training, sovereign cloud, and edge inference workloads is creating specialized procurement niches that favor focused specialists over generalist distributors.
For Market Incumbents: Harden certification moats by pre-positioning inventory through Batam's free trade zone ahead of TKDN local-content threshold escalations. Defend against custom silicon substitution by embedding field application engineers within hyperscale account teams in Jakarta's digital corridor, accelerating technical support responsiveness beyond captive chip development programs.
For New Entrants and Emerging Players: Pursue thermal design engineering partnerships with Indonesian polytechnic institutes to address the 8-14 month commissioning delay bottleneck plaguing North Sumatra and East Java developments. Target Surabaya's emerging digital infrastructure cluster for colocation processor supply, leveraging lower land costs and underdeveloped vendor presence relative to Greater Jakarta saturation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled GPU deployments as tropical ambient temperatures mandate precision cooling capex premiums. Long-term viability favors acquisition targets with captive thermal engineering capabilities and established BIS-equivalent certification pathways. Watch hyperscaler direct-procurement consolidation rates as the inflection signal for distributor margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| TKDN Certification Investment | Ministry of Industry local-content thresholds unlock preferential tax treatment for sovereign cloud deployments. |
| Liquid Cooling Partnership | Tropical thermal constraints elevate facility capex, favoring vendors with integrated precision cooling architectures. |
| Edge Computing Node Expansion | 5G core virtualization across Telkomsel and XL Axiata networks demands low-power AI accelerators outside Jakarta. |
| Direct-to-Hyperscale Supply Agreement | Confidential procurement with Alibaba Cloud and AWS bypasses distributor margin compression in Cikarang. |
| Chiplet-Based Modular Design Adoption | AMD EPYC and Intel Granite Rapids implementations enable customized core-to-memory ratios for workload-specific optimization. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and Ministry of Communication and Informatics facility licensing records anchors the qualitative findings. Primary interviews with data center procurement directors, thermal engineering consultants, and BIS-equivalent certification auditors combined with secondary validation against customs import manifests, TKDN registry filings, and cloud provider infrastructure announcements. Bottom-up triangulation aggregates processor shipment volumes by socket type and thermal design power class, while top-down reconciliation cross-checks against facility power capacity commissioning across Greater Jakarta, West Java, and Batam.
Calibration against historical procurement cycle data and vendor delivery timelines refines the analytical framework across the projection horizon. Segmentation dimensions model processor architecture, deployment model, end-user vertical, and regional infrastructure cluster. CAGRs derive from fitted growth curves applied to facility commissioning pipelines and sovereign cloud mandate compliance schedules. Hyperscale direct-procurement velocity and TKDN certification throughput serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in rupiah-dollar exchange rates and Taiwan Strait logistics stability would shift the trajectory. Forecasts reflect documented assumptions regarding data localization enforcement intensity and foundry capacity allocation priorities. Cross-checking against BIS-equivalent certification queue lengths is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Automotive Chip Market