
 Brazil Data Center Processor Market | 2026-2036
Brazil Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Processor Market Insights
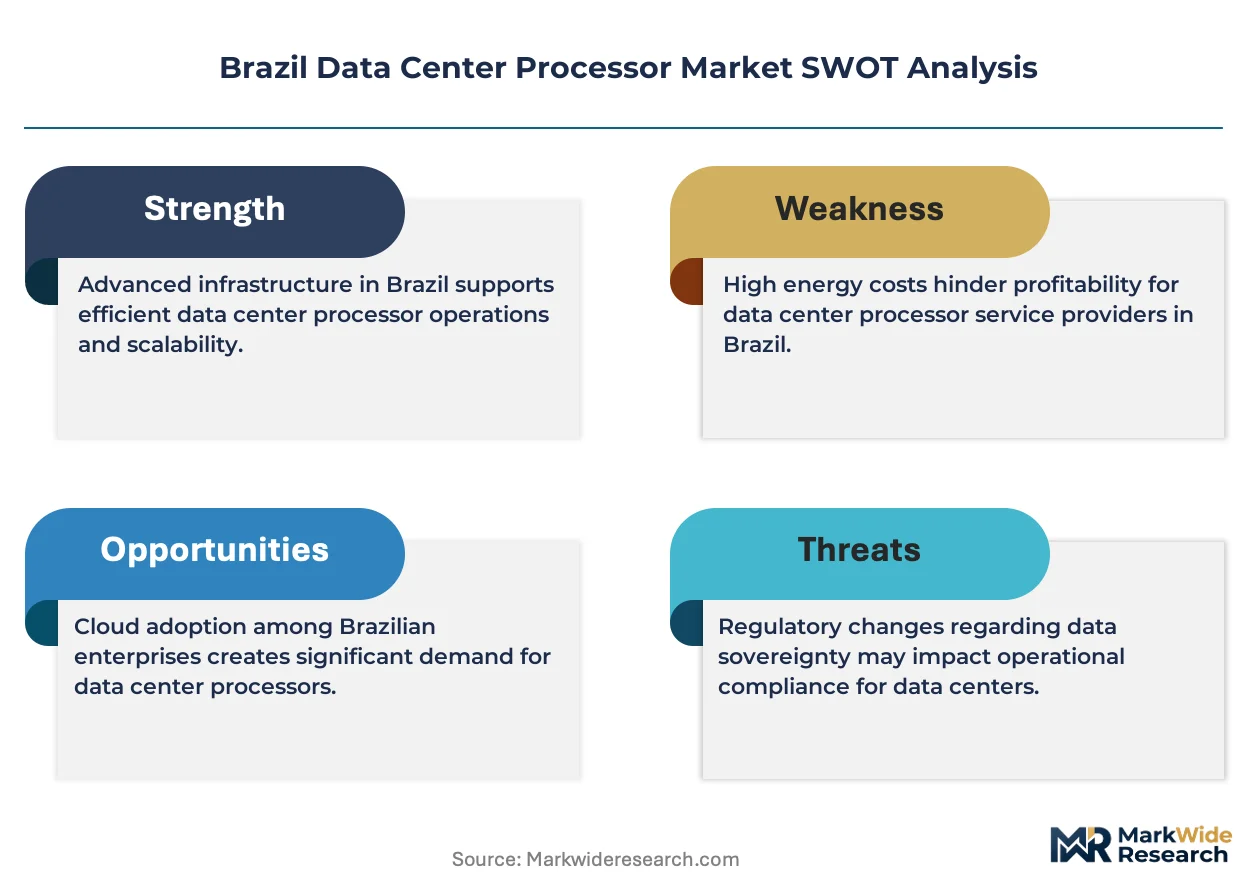
Direct procurement channels between semiconductor vendors and Brazilian hyperscale operators is tilting away from traditional distributor models. Intel anchors the market through its established foundry partnerships and x86 architecture dominance in legacy enterprise workloads. AMD competes aggressively on performance-per-watt metrics for cloud-native deployments. NVIDIA specializes in GPU accelerators that dominate AI training and inference pipelines across local data centers.
A data center processor is a silicon integrated circuit designed to execute computational instructions, typically fabricated on process nodes between 3nm and 7nm, with thermal design power ranging from 65W to over 400W, serving as the primary engine for server virtualization, database operations, and artificial intelligence workloads. CPU products still occupy the largest installed base, though GPU deployments are expanding fastest as Brazilian enterprises adopt generative AI and large language model inference. The colocation deployment model sustains steady processor refresh cycles, while hybrid architectures attract organizations balancing latency-sensitive on-premises workloads with burst capacity from cloud providers.
ANATEL governs telecommunications infrastructure standards affecting inter-data center connectivity, while the Brazilian Central Bank's cybersecurity regulations for BFSI institutions mandate localized data processing that drives domestic processor procurement. ANVISA and the national data protection authority, ANPD, impose data residency requirements that prevent wholesale offshoring of sensitive compute workloads. Stakeholders must weigh sovereign compute mandates against the cost and availability constraints of importing advanced processors subject to multilateral export control frameworks.
Market Dynamics
Hyperscale operators in São Paulo are compressing server refresh cycles to accommodate generative AI inference workloads, creating a structural pull toward high-TDP accelerators that legacy data center infrastructure cannot support without wholesale electrical and cooling upgrades.
Growth Catalysts
- ANATEL Connectivity Mandates:Updated inter-data center fiber regulations reduce latency between São Paulo metro facilities, enabling distributed AI training clusters that drive processor procurement.
- Financial Services Localization:The Brazilian Central Bank's cybersecurity framework for BFSI institutions mandates on-premises transaction processing, preventing cloud offshoring of core banking compute.
- AI Inference Concentration:Large language model deployment across Brazilian enterprises creates sustained demand for GPU-accelerated servers in São Paulo colocation facilities.
Market Restraints
- Advanced Node Import Friction:Multilateral export controls on sub-7nm processors limit supply availability for Brazilian hyperscalers, extending lead times for AI training hardware.
- Power Infrastructure Constraints:São Paulo's electrical grid capacity limits per-rack density below 30kW in older facilities, capping deployment of 400W+ accelerators without facility rebuilds.
- Foreign Exchange Volatility:Dollar-denominated processor procurement exposes Brazilian operators to currency risk that compresses capital planning horizons.
Strategic Opportunities
- Campinas Secondary Cluster:Fiber connectivity improvements and lower real estate costs position Campinas for edge inference deployments serving São Paulo's northern corridor.
- ANPD Data Residency Tailwinds:National data protection authority enforcement creates compliance-driven demand for sovereign cloud infrastructure with locally-procured processors.
- Arm Architecture Convergence:Cloud-native workload optimization creates white space for non-x86 server processors in containerized deployments.
Industry Challenges
- AI Infrastructure Talent Scarcity:Shortage of technicians qualified to deploy and maintain liquid-cooled GPU servers constrains deployment velocity in São Paulo facilities.
- Legacy System Integration Complexity:Enterprise mainframe and RISC-based workloads resist migration to x86/Arm cloud architectures, fragmenting processor procurement across incompatible estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Processor Market |
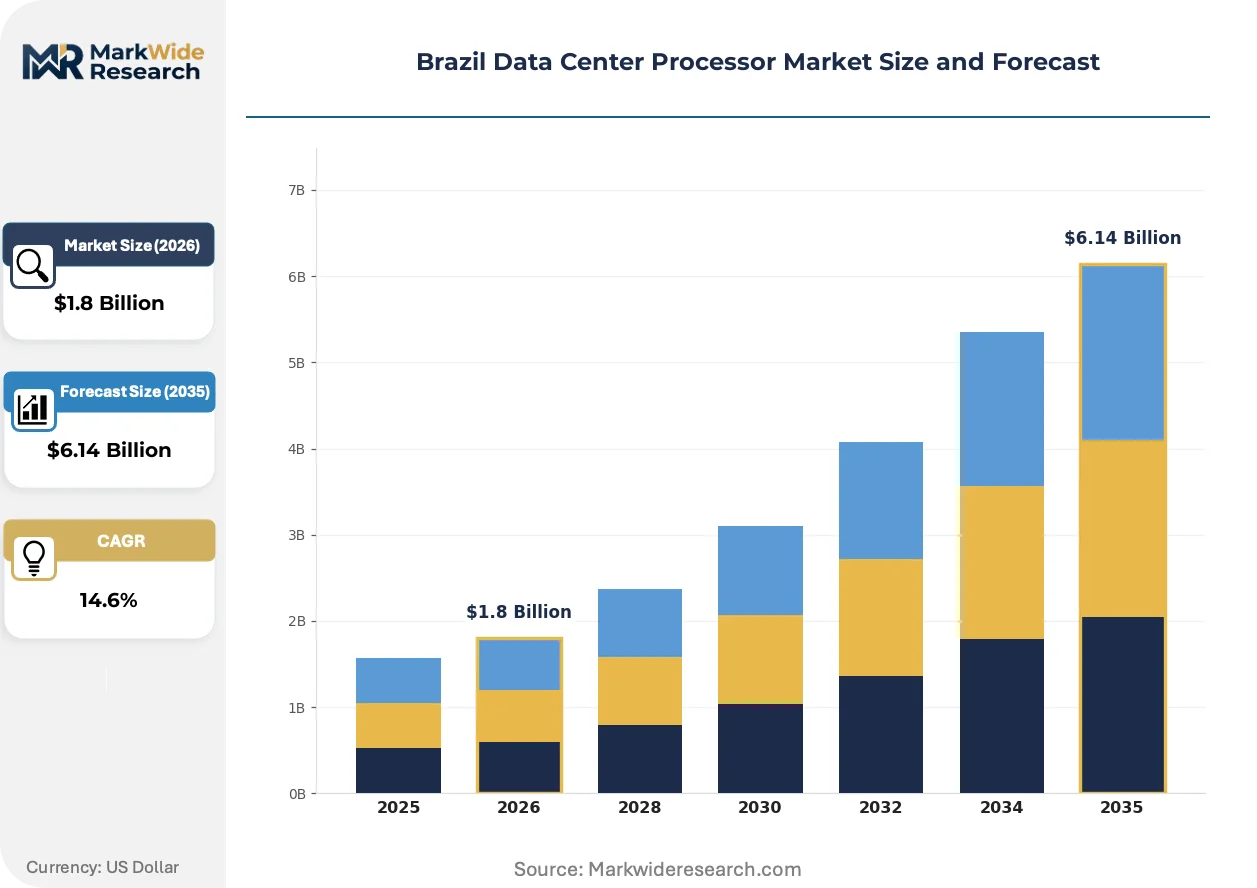
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Deployment Model: On-Premises, Colocation, Cloud, Hybrid End User: IT Services, Telecommunications, BFSI, E-Commerce Processor Architecture: x86, ARM, RISC, Others |
| Companies Covered | Intel, AMD, NVIDIA, Qualcomm, Broadcom, Arm Holdings, IBM, Huawei Technologies, Dell Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Processor Market Trends and Innovations
Computational virtualization and workload abstraction are redrawing hardware procurement patterns across Brazilian data centers, compressing the distinction between CPU-centric and accelerator-centric infrastructure planning.
Software-defined accelerators with programmable logic fabrics are virtualizing hardware functions previously locked to fixed-function silicon. Brazilian cloud operators are piloting these devices for video transcoding and encryption offloading in São Paulo edge locations. This virtualization is collapsing the traditional server-accelerator boundary, enabling dynamic resource allocation that matches processor type to instantaneous workload demands.
ANATEL's revised data center interconnection standards mandate redundant fiber paths between facilities exceeding 10 megawatts of critical load. The regulation forces hyperscale operators to standardize on open optical networking hardware, reducing proprietary switch-processor bundling. São Paulo's three largest colocation campuses are responding with unified procurement specifications that decouple network silicon from server processor vendor selection.
Brazilian enterprises are unbundling hardware procurement from managed service contracts that historically dominated IT outsourcing. Large manufacturers in Rio de Janeiro state now source processors directly through distributor channels, displacing systems integrator markup structures. This disintermediation is most pronounced in organizations with dedicated infrastructure teams, where technical buyers negotiate silicon pricing independent of deployment services.
Brazil Data Center Processor Market Segmentation
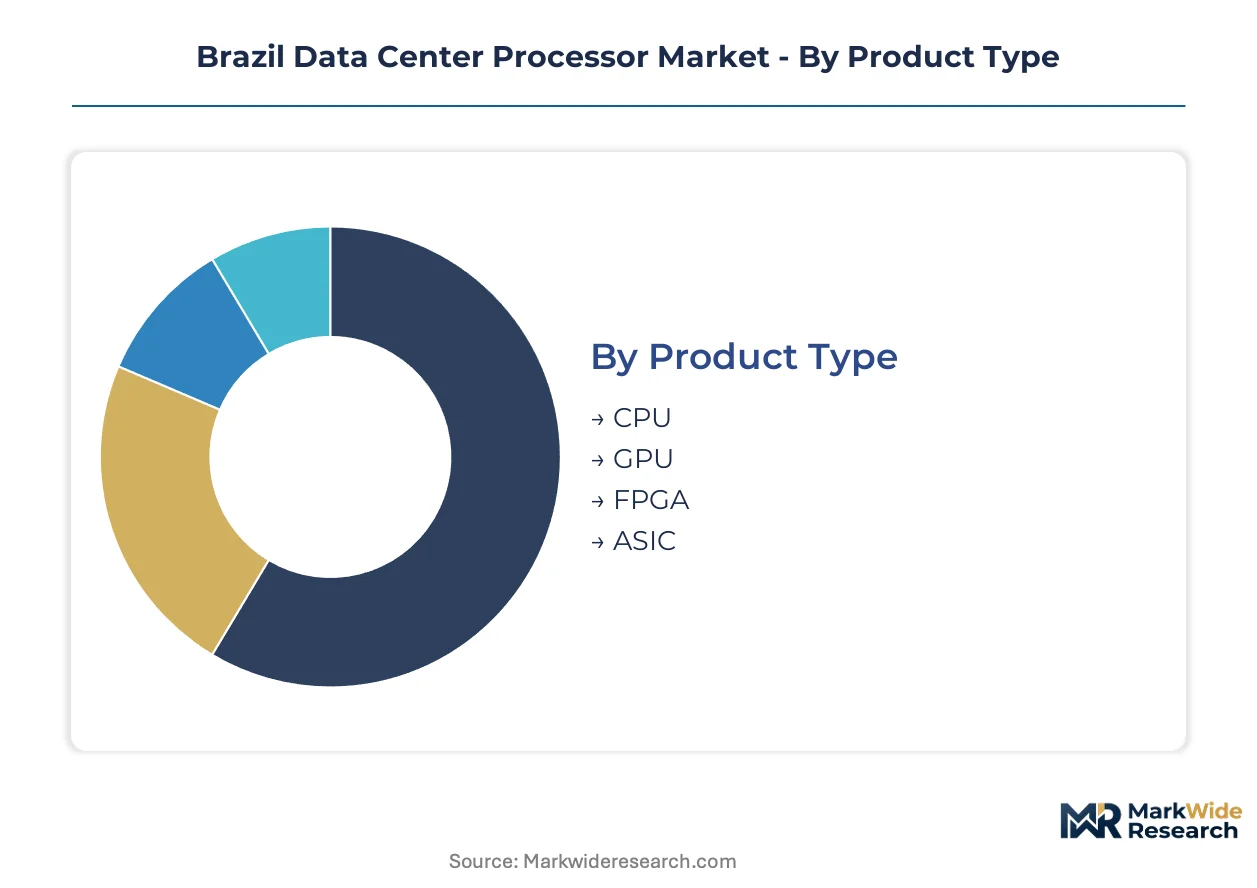
Processor procurement patterns across Brazilian data centers fragment sharply by workload type and deployment constraints. Technical buyers in São Paulo facilities must reconcile sovereign compute mandates with thermal limitations and import availability when selecting silicon categories.
Product Type:
After-sales service intensity varies dramatically across processor categories, with GPU deployments demanding specialized liquid-cooling maintenance contracts that CPU refresh cycles rarely require.
- CPU:General-purpose silicon fabricated on mature process nodes handles virtualization, database operations, and legacy enterprise workloads. São Paulo colocation providers favor CPU-centric servers for BFSI transaction processing under Central Bank cybersecurity mandates. These units generate predictable thermal loads that older facilities accommodate without electrical upgrades.
- GPU:Parallel-processing accelerators with high thermal design power dominate AI training and inference pipelines. Hyperscale operators in São Paulo deploy NVIDIA accelerators for large language model workloads, though 400W+ TDP requirements force facility rebuilds in aging data centers.
- FPGA:Programmable logic devices enable workload-specific hardware acceleration for encryption and video transcoding at São Paulo edge locations.
- ASIC:Custom silicon delivers optimized performance-per-watt for specialized inference tasks in Brazilian cloud-native deployments.
CPU holds the largest share; momentum sits with GPU as generative AI adoption accelerates across Brazilian enterprises.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models favored by mid-market Brazilian enterprises.
- On-Premises:Enterprises in Rio de Janeiro state maintain owned facilities for latency-sensitive manufacturing systems and ANPD compliance. Direct processor procurement through distributor channels displaces systems integrator markups as technical teams mature.
- Colocation:São Paulo metro campuses host the majority of Brazilian hyperscale compute, with Campinas emerging for northern corridor edge inference. ANATEL fiber mandates enable distributed clusters across facilities exceeding 10 megawatts critical load.
- Cloud:Hyperscale operators expand São Paulo capacity to serve burst workloads from enterprises avoiding capital commitments.
- Hybrid:Organizations balance sovereign transaction processing against cloud burst capacity, fragmenting processor procurement across incompatible estates.
Colocation dominates installed capacity; hybrid architectures are gaining share fastest among regulated Brazilian enterprises.
End User:
Application-specific workload characteristics drive divergent processor specifications across Brazilian verticals.
- IT Services:Managed service providers aggregate demand across client portfolios, standardizing on x86 cloud-native configurations with Arm evaluation for containerized workloads.
- Telecommunications:ANATEL-regulated carriers deploy edge processors for low-latency 5G infrastructure across São Paulo state.
- BFSI:Central Bank cybersecurity frameworks mandate localized transaction processing, preventing cloud offshoring and sustaining on-premises CPU refresh cycles.
- E-Commerce:Seasonal demand spikes drive hybrid deployments combining colocation baseline capacity with cloud burst for promotional events.
BFSI sustains the most predictable procurement cadence; e-commerce shows the steepest expansion trajectory as digital retail penetration deepens.
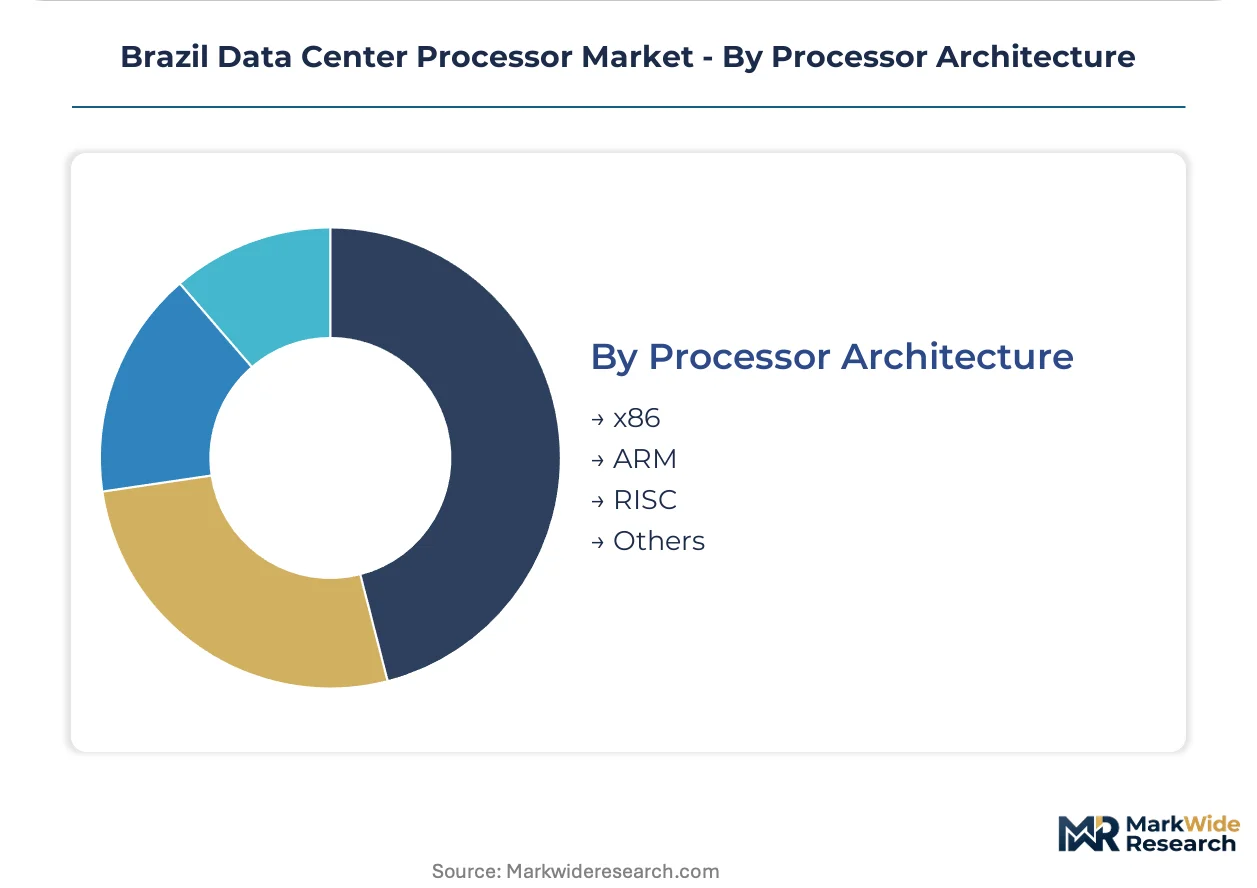
Processor Architecture:
Supply concentration around x86 ecosystems constrains Brazilian buyer leverage despite emerging alternatives.
- x86:Intel and AMD architectures anchor legacy enterprise virtualization and database workloads across Brazilian data centers. Established software compatibility and distributor relationships sustain dominance despite higher power draw.
- ARM:Cloud-native optimization creates white space for non-x86 deployments in containerized environments, with hyperscale operators piloting efficiency gains for inference workloads.
- RISC:Specialized Unix and mainframe workloads persist in BFSI core banking systems, resisting migration to commodity silicon.
- Others:Emerging instruction set architectures target niche acceleration roles in Brazilian research and government computing.
x86 commands current procurement volume; Arm is climbing the fastest as cloud-native adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo-Rio de Janeiro fiber corridor anchors Brazil's data center processor demand, with ANATEL-mandated redundant fiber paths enabling distributed AI clusters across facilities exceeding 10 megawatts of critical load.
São Paulo
São Paulo's metropolitan cluster concentrates over 60% of Brazilian data center processor procurement, driven by hyperscale cloud expansion and BFSI transaction localization. ANATEL's updated inter-data center connectivity rules mandate redundant fiber paths between major facilities. The Campinas northern corridor emerges as a secondary node for edge inference deployments serving latency-sensitive manufacturing workloads.
Rio de Janeiro
Rio de Janeiro state sustains enterprise-owned facilities for oil and gas sector computing and ANPD-compliant data residency. The Brazilian Central Bank's cybersecurity framework prevents cloud offshoring of core banking systems. Large manufacturers in the Baixada Fluminense industrial zone now source processors directly through distributor channels, displacing systems integrator markups.
Minas Gerais
Minas Gerais hosts government and research computing facilities under Brazil's national AI strategy. The state's lower real estate costs attract secondary data center development for disaster recovery and backup workloads. Belo Horizonte's technology park positions for sovereign cloud infrastructure serving federal agencies with data residency mandates.
Rio Grande do Sul
Rio Grande do Sul anchors southern Brazil's enterprise data center footprint, with Porto Alegre serving regional headquarters of multinational manufacturers. Local BFSI institutions maintain on-premises transaction processing under Central Bank regulations. The state's industrial base generates steady CPU refresh cycles for legacy enterprise virtualization workloads.
Paraná
Paraná's Curitiba metro area attracts colocation investment from São Paulo operators seeking geographic diversification. ANATEL fiber connectivity improvements link the city to São Paulo's core cluster within 10 milliseconds. The state's automotive and agribusiness sectors drive hybrid cloud deployments combining local processor capacity with burst workloads from hyperscale providers.
Brazil Data Center Processor Market Competitive Landscape
On the supply side, the industry is consolidated around three dominant semiconductor architectures with clear tiering between established x86 incumbents and emerging accelerator specialists. Intel and AMD anchor the legacy enterprise segment through decades-long distributor relationships and software ecosystem lock-in. NVIDIA occupies a distinct premium tier for AI training and inference workloads. Competitive dynamics center on performance-per-watt optimization for power-constrained São Paulo facilities and direct procurement channel development that bypasses traditional distributor markups.
Within the established x86 tier, Intel and AMD exemplify divergent strategic positioning around thermal efficiency and cloud-native optimization. Intel leverages its foundry partnerships and entrenched software compatibility to defend legacy enterprise refresh cycles in BFSI and government verticals. AMD competes aggressively on performance-per-watt metrics that appeal to hyperscale operators facing São Paulo's 30kW per-rack density constraints. NVIDIA sits outside this architecture contest entirely, representing the AI accelerator archetype with GPU deployments that dominate generative AI inference pipelines across Brazilian colocation facilities.
| Leading Market Players |
|---|
| Intel |
| AMD |
| NVIDIA |
| Qualcomm |
| Broadcom |
| Arm Holdings |
| IBM |
| Huawei Technologies |
| Dell Technologies |
| Others |
Pricing and Supply Chain Analysis
Multilateral export controls on sub-7nm silicon determine both the premium tier spreads between available and restricted accelerators and the supply chain shape that Brazilian hyperscalers must navigate. Dollar-denominated procurement against real volatility compresses capital planning horizons while forcing buyers toward volume-commitment contracts that secure allocation priority.
Pricing Analysis
Volume-discount tiering structures separate hyperscale direct procurement from mid-market distributor channels with 15-20 point spreads. Pricing stratifies across premium AI accelerators, standard server CPUs, and economy-grade legacy silicon with differentiation driven by thermal design power ratings and ANATEL certification requirements. Cost compression in the premium tier is intensifying because hyperscale operators negotiate global frame agreements that override regional markup structures. Mid-market enterprises through Rio de Janeiro manufacturing zones show highest price sensitivity; São Paulo hyperscalers demonstrate lowest sensitivity due to workload-critical latency requirements.
Supply Chain Analysis
Export-control regimes restricting advanced node flows from Taiwan and South Korea anchor supply uncertainty for Brazilian AI infrastructure builds. The processor supply chain draws from Taiwan for leading-edge foundry output, South Korea for memory integration, and the United States for design-house licensing. Single-source vulnerability concentrates in advanced packaging capacity that feeds GPU module assembly. Distribution runs through São Paulo-based authorized distributors serving BFSI and enterprise verticals alongside direct OEM relationships with hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as sovereign compute mandates and AI workload specialization create distinct procurement niches across incompatible infrastructure estates. The divergence between legacy BFSI transaction processing and cloud-native inference deployments splits technical buyer archetypes.
For Market Incumbents: Insulate x86 installed base through firmware-anchored virtualization management tools that raise switching costs for BFSI core banking systems. Deepen foundry partnership commitments with TSMC and Samsung to secure allocation priority under export-control quotas. Channel control investments in São Paulo distributor relationships defend against direct procurement disintermediation.
For New Entrants and Emerging Players: Pursue Arm-based cloud-native server white space in containerized deployments where hyperscale operators pilot efficiency optimization. Campinas edge inference facilities represent the most penetrable geography given fiber connectivity improvements and lower real estate costs versus São Paulo metro. Go-to-market positioning through ANPD compliance advisory bundling addresses data residency anxiety among regulated enterprises.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors liquid-cooling integration specialists and sovereign cloud operators with established ANATEL relationships. Long-term viability centers on 5-10 year compute localization trends rather than cyclical server refresh timing. The signal to watch is Central Bank cybersecurity framework expansion beyond BFSI into adjacent regulated verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Procurement Channel Development | Bypasses distributor markups for hyperscale operators with dedicated infrastructure teams in São Paulo. |
| Liquid-Cooling Infrastructure Partnership | Enables 400W+ GPU deployment in aging São Paulo facilities without wholesale electrical rebuilds. |
| ANPD Compliance Certification Program | Positions sovereign cloud operators for data residency mandates across federal agency procurements. |
| Arm Architecture Platform Integration | Captures cloud-native workload optimization as hyperscale operators evaluate non-x86 efficiency gains. |
| Campinas Edge Facility Expansion | Exploits fiber latency improvements to serve São Paulo northern corridor manufacturing workloads. |
Research Methodology
A spread of perspectives from hyperscale infrastructure planners, colocation facility operators, semiconductor distributor principals, BFSI technology procurement leads, and ANATEL regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ANATEL regulatory filings, Brazilian Central Bank cybersecurity framework documentation, hyperscaler capital expenditure disclosures, and customs import records for advanced semiconductor categories. Bottom-up server deployment estimates across São Paulo metro facilities triangulated against top-down market sizing from foundry allocation data.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling processor procurement by product type, deployment model, end-user vertical, and processor architecture dimensions. CAGRs derived from shipment volume trajectories adjusted for import friction and facility power constraints. Industry-specific forecast inputs included ANATEL fiber mandate implementation timelines and Central Bank localization enforcement patterns.
Macroeconomic conditions sit as an overlay; deviation in real-dollar exchange rates or multilateral export control expansion would shift the trajectory. Forecasts reflect documented assumptions about sovereign compute mandate continuity and foundry capacity allocation stability. Material shifts in ANATEL interconnection standards or advanced node licensing restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Microserver Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Global Microprocessor and GPU Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Cloud AI Chipsets Market