
 Displayport IP Market | 2026-2036
Displayport IP Market Size, Share, and Industry Trends Forecast 2026-2036
Displayport IP Market Analytics
Automotive display integration is broadening the addressable base for DisplayPort IP vendors beyond traditional computing clients. Synopsys leverages its comprehensive verification IP portfolio to capture design-win momentum across infotainment SoC programs. Texas Instruments anchors its position through integrated signal conditioning and timing controller expertise for high-resolution cockpit displays. Parade Technologies specializes in physical-layer retimer and redriver solutions that address electromagnetic compatibility challenges in vehicle architectures.
DisplayPort IP comprises licensable semiconductor intellectual property implementing the VESA DisplayPort standard, typically delivered as synthesizable RTL cores supporting data rates up to 80 Gbps in the UHBR20 specification, enabling uncompressed video transport across internal and external display interfaces. IP Core offerings dominate current licensing revenue as chipmakers seek proven PHY and controller implementations to compress time-to-market for next-generation GPUs and display SoCs. Reference Design segments exhibit faster growth as system houses demand validated subsystem blueprints combining protocol stacks with panel timing controllers for gaming monitor and professional display applications.
The FCC governs electromagnetic emissions for DisplayPort-enabled devices sold in the United States, while VESA's own compliance program certifies interoperability across cable assemblies and source devices. ECHA's REACH restrictions on hazardous substances in electronics manufacturing constrain substrate and packaging material choices for IP licensees targeting European end markets. Stakeholders must monitor VESA's roadmap convergence with MIPI standards for mobile-integrated displays, as this interface consolidation threatens standalone DisplayPort licensing volumes in handset and tablet applications.
Market Dynamics
Automotive OEMs now mandate DisplayPort UHBR20 PHY cores for 8K cockpit displays, compressing IP licensing timelines from 18 months to under 12 months as Tier-1 suppliers race to qualify infotainment SoCs before 2026 model-year lockdowns.
Growth Catalysts
- EU F-Gas Regulation:Halogen-free substrate mandates force semiconductor packaging redesigns, creating fresh demand for IP cores validated against REACH-compliant material sets.
- Advanced driver-assistance systems:Surround-view camera aggregation requires 80 Gbps uncompressed video backbones, pulling DisplayPort IP into safety-critical automotive signal chains previously served by proprietary LVDS.
- South Korea panel concentration:Samsung Display and LG Display anchor 70 percent of global OLED capacity, concentrating royalty negotiations and accelerating UHBR20 adoption timelines.
Market Restraints
- MIPI DSI-2 substitution:Handset and tablet form factors increasingly converge on MIPI standards, threatening standalone DisplayPort licensing volumes in mobile-integrated display applications.
- EUV lithography bottlenecks:Advanced PHY implementations require 3nm-class processes where TSMC and Samsung Foundry capacity constraints extend tape-out schedules by 4-6 months.
- REACH substance restrictions:ECHA's expanding SVHC list constrains substrate and molding compound choices, forcing IP licensees to re-qualify packages for European end markets.
Strategic Opportunities
- India PLI scheme:Display manufacturing incentives under India's production-linked incentive program attract panel assembly investments, opening fresh IP licensing channels as domestic ecosystem localization accelerates.
- AR/VR headset convergence:Micro-OLED near-eye displays require ultra-low-latency compression protocols, positioning DisplayPort DSC as a bridge standard between rendering engines and panel timing controllers.
- Gaming monitor refresh wars:480Hz panel introductions drive demand for reference designs combining PHY cores with adaptive-sync logic, compressing system house integration cycles.
Industry Challenges
- PHY-MAC integration complexity:UHBR20's 128b/132b encoding and link-training state machines demand rare mixed-signal verification expertise, stretching talent pools at fabless design houses.
- VESA certification queues:Interoperability testing backlogs at authorized test centers extend product qualification timelines, delaying revenue recognition for IP vendors.
- Automotive safety integrity:ASIL-B compliance for video paths in instrument clusters requires fault-tolerant PHY architectures that inflate core area and power budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Displayport IP Market |
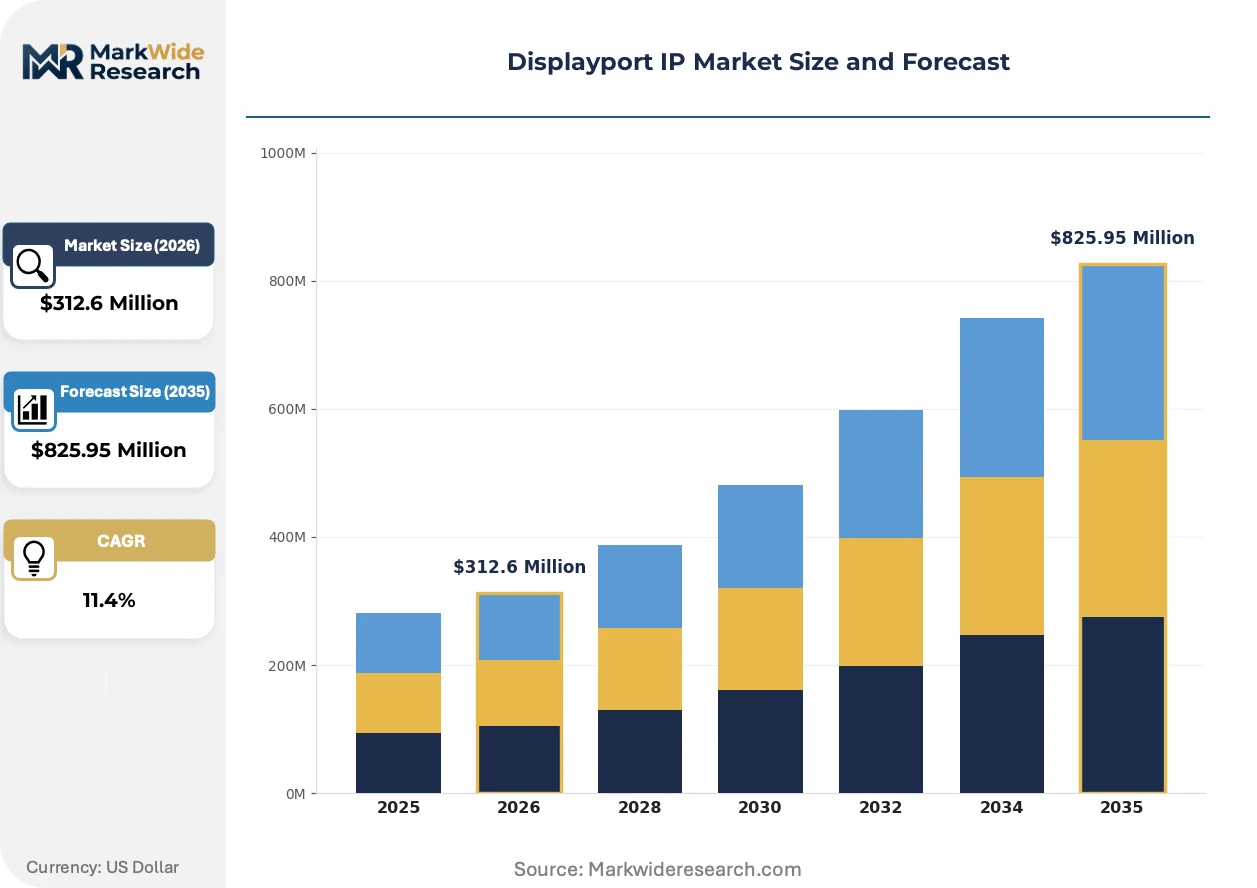
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $825.95 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Core, IP Block, Reference Design, Protocol Stack End User: Consumer Electronics, Automotive, Computing, Telecommunication Technology: Display Technology, Transmission Technology, Interface Standard, Signal Processing Application: Gaming, Streaming, Virtual Reality, Professional Displays |
| Companies Covered | Synopsys, Analog Devices, Texas Instruments, Lattice Semiconductor, Intel, NVIDIA, Parade Technologies, Analogix Semiconductor, Cadence Design Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Displayport IP Market Evolving Landscape
VESA's roadmap convergence with MIPI standards and the compression of display interface development cycles are forcing IP vendors to reposition around subsystem integration rather than standalone protocol cores.
Display Stream Compression 1.4a is rewriting bandwidth economics for 8K60 transport over legacy cable plants. Broadcast monitor manufacturers adopt DSC-enabled DP 2.1 transmitters to avoid costly optical fiber retrofits. The technology is rewriting the upgrade cycle for professional color-grading suites, extending panel replacement intervals by 3-4 years.
ECHA's REACH restrictions on per- and polyfluoroalkyl substances now cover semiconductor molding compounds and substrate laminates. IP licensees targeting European automotive OEMs must validate halogen-free package stacks before design-win commitment. German KBA type-approval processes increasingly reference REACH SVHC screening as a gate for cockpit electronics.
System houses now demand fixed-fee reference design licenses rather than per-unit royalties for gaming monitor and commercial display programs. This procurement compression squeezes IP vendor margins but accelerates time-to-revenue through validated subsystem handoffs. The shift is most visible in Taiwan and China, where ODMs compete on 90-day product cycles.
Displayport IP Market Segmentation
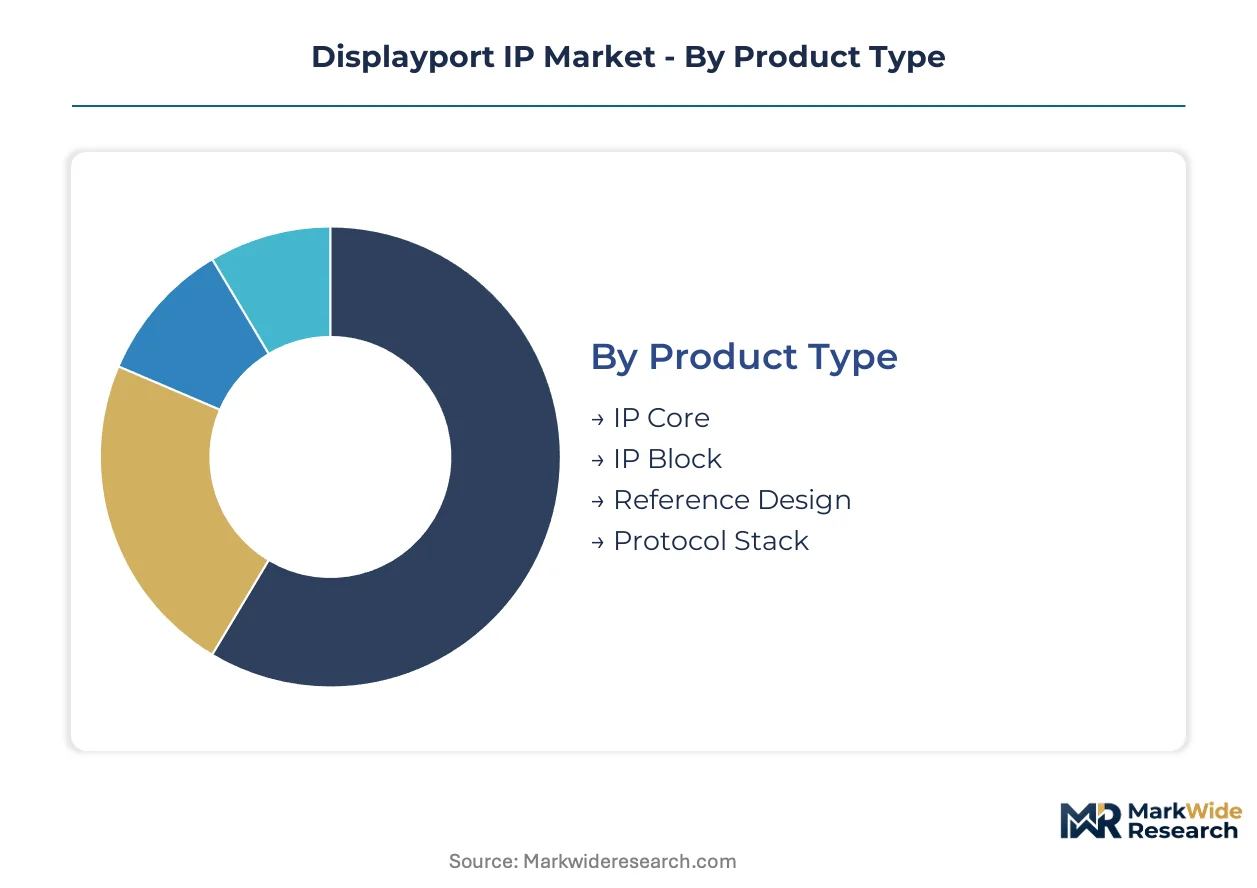
DisplayPort IP licensing revenue concentrates in high-complexity PHY implementations where tape-out costs and verification cycles create natural segmentation tiers. Vendors structure pricing and support models around technical depth, end-market certification requirements, and integration risk profiles rather than commodity volume metrics.
Product Type:
Capital intensity escalates sharply from software protocol stacks to mixed-signal PHY cores, with UHBR20 implementations demanding 3nm-class process nodes and specialized analog design expertise.
- IP Core:Synthesizable RTL implementations of DisplayPort controllers and PHYs carry the heaviest upfront engineering burden. Automotive infotainment SoC programs in Germany and South Korea drive demand for ASIL-B qualified cores with fault-tolerant architectures.
- Reference Design:Validated subsystem blueprints combining protocol stacks with panel timing controllers attract fixed-fee licensing from Taiwan and China ODMs racing 90-day product cycles. Procurement compression here squeezes vendor margins but accelerates time-to-revenue.
- IP Block:Modular PHY or controller components for integration into larger SoC designs serve fabless houses seeking selective capability augmentation without full protocol licensing.
- Protocol Stack:Software-layer implementations of link training, AUX channel management, and EDID parsing occupy the lowest capital tier, with differentiation hinging on certification queue relationships.
Most installed capacity flows through IP Core engagements. Expansion is steepest in Reference Design as system houses prioritize validated handoffs over custom integration.
End User:
Certification burden and safety integrity requirements fragment the customer base, with automotive programs demanding fault-tolerant architectures that consumer electronics eschew.
- Automotive:Cockpit display integration mandates UHBR20 PHY cores for 8K instrument clusters. German KBA type-approval processes and EU REACH compliance constrain package material choices, extending qualification timelines.
- Consumer Electronics:Gaming monitor and television applications concentrate volume demand in South Korea and China, with 480Hz refresh specifications pulling adaptive-sync logic into PHY licensing bundles.
- Computing:Discrete GPU and integrated graphics SoC programs anchor royalty-intensive negotiations, though MIPI convergence in mobile-integrated displays threatens standalone DisplayPort volumes.
- Telecommunication:Broadcast monitor and professional color-grading suites adopt DSC-enabled DP 2.1 transmitters to avoid optical fiber retrofits, extending panel replacement intervals.
Computing retains the largest revenue base. Automotive climbs fastest as OEMs compress IP licensing timelines from 18 months to under 12 months for model-year lockdowns.
Technology:
Technical differentiation concentrates at the physical layer, where signal integrity and electromagnetic compatibility determine design-win outcomes in high-speed applications.
- Display Technology:Micro-OLED near-eye display requirements for AR/VR headsets position DisplayPort DSC as a bridge standard between rendering engines and panel timing controllers.
- Transmission Technology:UHBR20's 80 Gbps uncompressed transport demands 128b/132b encoding and sophisticated link-training state machines, stretching mixed-signal verification talent pools.
- Interface Standard:VESA certification interoperability and roadmap convergence with MIPI standards govern licensing longevity, with standalone DisplayPort volumes threatened by interface consolidation in handsets.
- Signal Processing:Adaptive equalization and jitter cleaning capabilities differentiate retimer and redriver solutions for challenging vehicle electromagnetic environments.
Transmission Technology commands the highest development investment. Signal Processing gains share fastest as automotive electromagnetic compatibility requirements intensify.
Application:
Use-case performance thresholds stratify licensing value, with professional color accuracy and ultra-low latency commanding premium positioning against mainstream consumer applications.
- Gaming:480Hz panel introductions and adaptive-sync logic integration compress system house design cycles. Taiwan ODM procurement patterns favor fixed-fee reference designs over per-unit royalties.
- Professional Displays:Broadcast monitor manufacturers require DSC 1.4a compression for 8K60 transport over legacy cable plants, extending upgrade intervals for color-grading suites.
- Virtual Reality:Micro-OLED near-eye displays demand ultra-low-latency compression protocols, with DisplayPort DSC serving as the bridge between rendering engines and panel controllers.
- Streaming:Content delivery infrastructure relies on DisplayPort for internal video backbones in production equipment, though this segment lacks the refresh-rate pressure of gaming applications.
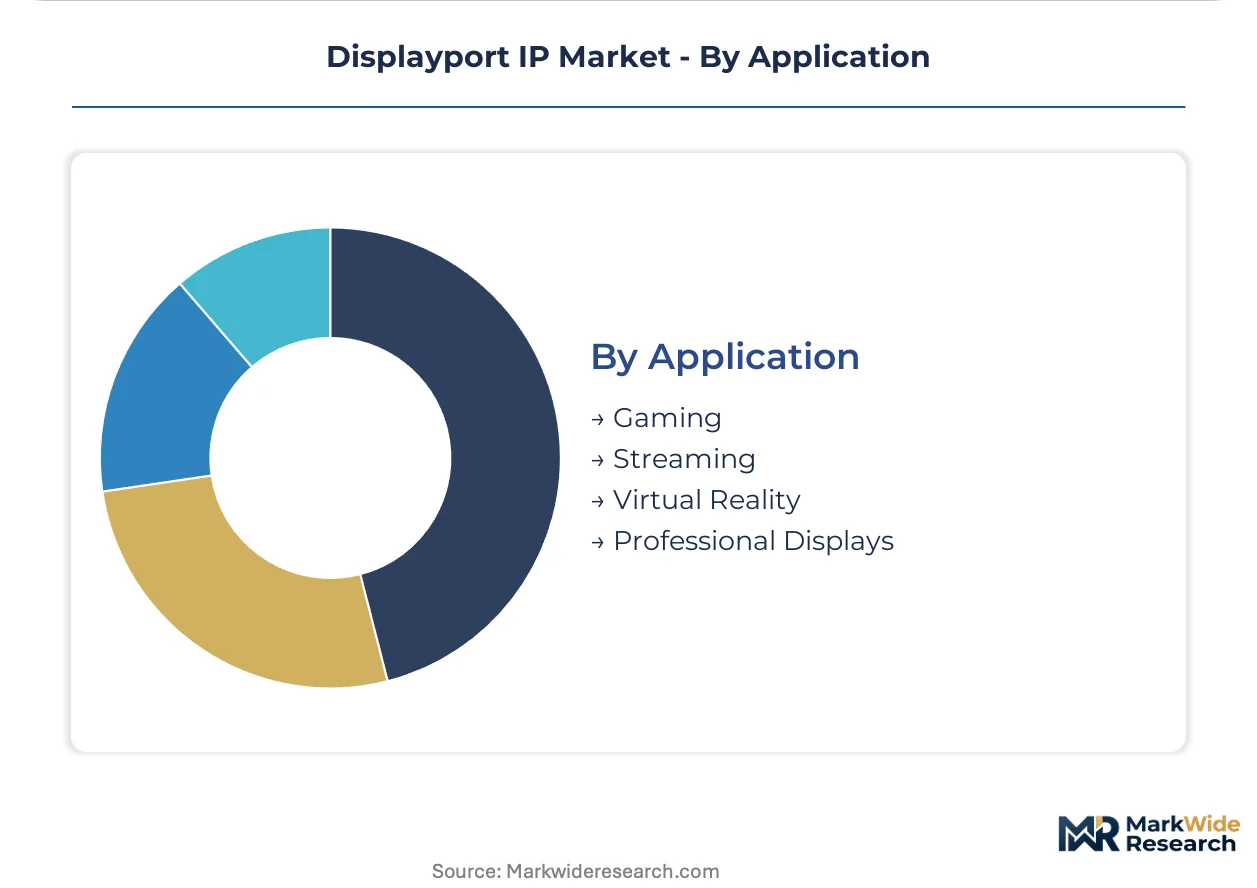
Gaming absorbs the largest licensing volume. Virtual Reality expands most quickly as headset shipments accelerate and near-eye display resolutions climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where DisplayPort IP licensing concentrates, as REACH compliance costs in Europe push some packaging qualification work toward Asian foundries with established halogen-free substrate capabilities. Panel manufacturing gravity and automotive cockpit electronics programs now determine regional IP demand intensity.
South Korea
Samsung Display and LG Display anchor seventy percent of global OLED capacity, concentrating royalty-intensive IP negotiations in Seoul and Gumi. The MFDS regulates hazardous substance reporting for semiconductor packaging materials used in domestic automotive programs. Pangyo's technology corridor hosts multiple IP vendor field application engineering teams supporting Tier-1 infotainment SoC development.
Germany
Automotive OEMs in Stuttgart and Munich mandate UHBR20 PHY cores for 8K instrument clusters ahead of 2026 model-year lockdowns. The KBA type-approval process increasingly references REACH SVHC screening as a gate for cockpit electronics deployment. Dresden's semiconductor cluster attracts IP validation work for ASIL-B qualified fault-tolerant architectures targeting premium vehicle programs.
United States
Gaming monitor manufacturers in California and Texas drive 480Hz refresh specification adoption, pulling adaptive-sync logic into PHY licensing bundles. The FCC governs electromagnetic emissions for DisplayPort-enabled devices sold domestically, shaping retimer and redriver design requirements. Austin's fabless design corridor concentrates mixed-signal verification talent for UHBR20 link-training state machine development.
China
MIIT standards convergence with VESA roadmaps governs interface adoption timelines for domestic handset and tablet manufacturers. GB standards for electromagnetic compatibility constrain physical-layer implementation choices for IP targeting consumer electronics programs. Shenzhen's ODM ecosystem increasingly demands fixed-fee reference design licenses over per-unit royalties for 90-day product cycles.
India
The PLI scheme for display manufacturing attracts panel assembly investments from Korean and Taiwanese anchor tenants, opening fresh IP licensing channels as ecosystem localization accelerates. BIS certification requirements for electronic goods shape import substitution patterns for timing controller and signal conditioning components. Tamil Nadu's electronics manufacturing corridor near Chennai concentrates emerging demand for automotive-grade PHY cores.
Displayport IP Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-protocol IP vendors commanding premium positioning against modular component suppliers. The vendor base concentrates around three tiers: comprehensive verification IP portfolios, integrated signal conditioning specialists, and physical-layer retimer-focused boutiques. Two dominant competitive moves define current positioning: strategic partnerships between IP core vendors and foundries for advanced-node PHY tape-outs, and portfolio diversification into reference design bundles that compress system house integration cycles.
Within the comprehensive IP portfolio tier, Synopsys and Cadence Design Systems exemplify the engineering-heavy archetype that dominates automotive infotainment SoC programs. Among analog-centric specialists, Texas Instruments occupies a position anchored in signal conditioning and timing controller expertise. Parade Technologies represents the physical-layer boutique model, with retimer and redriver solutions addressing electromagnetic compatibility challenges in vehicle architectures.
| Leading Market Players |
|---|
| Synopsys |
| Analog Devices |
| Texas Instruments |
| Lattice Semiconductor |
| Intel |
| NVIDIA |
| Parade Technologies |
| Analogix Semiconductor |
| Cadence Design Systems |
| Others |
Value Network & Pricing Analysis
Silicon wafer costs at 3nm-class nodes cascade through DisplayPort IP licensing tiers, with automotive PHY core premiums absorbing foundry price escalation while consumer reference designs face procurement compression from Taiwan ODMs.
Pricing Analysis
Direct-to-OEM discount structures dominate automotive infotainment SoC programs, compressing channel margins to secure multi-year design wins. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified automotive cores from consumer-grade PHY implementations and modular IP blocks. Cost compression in reference design licensing is intensifying because Shenzhen ODMs demand fixed-fee bundles over per-unit royalties. Gaming monitor manufacturers exhibit highest price sensitivity, while German automotive OEMs prioritize certification pedigree over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with TSMC's N3E process node for UHBR20 PHY tape-outs, where capacity constraints extend delivery schedules. Taiwan, South Korea, and the United States anchor advanced semiconductor manufacturing for DisplayPort IP cores. Raw material dependencies include EUV photoresists, high-purity silicon substrates, and halogen-free molding compounds. Tariff exposure on Chinese-packaged timing controllers threatens cost structures for consumer electronics programs. Distribution runs through direct foundry relationships for IP cores and ODM aggregator channels for reference designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: REACH compliance costs in Europe push packaging qualification toward South Korean foundries with established halogen-free substrate capabilities, creating cost differentials of 15-20 percent on automotive-grade PHY implementations.
For Market Incumbents: Lock in multi-year foundry allocation agreements at Samsung Foundry and TSMC to secure 3nm-class capacity ahead of Tier-1 infotainment SoC ramps. Deepen backward integration into verification IP portfolios to defend against MIPI DSI-2 substitution threats in mobile-integrated display applications. Prioritize ASIL-B certification investments for German KBA type-approval processes. For New Entrants and Emerging Players: Capture white-space in India's PLI scheme corridor near Chennai, where display manufacturing incentives attract Korean anchor tenants without established IP vendor relationships. Target fixed-fee reference design licensing for Taiwan ODMs racing 90-day gaming monitor product cycles. Pursue field application engineering partnerships with emerging automotive Tier-1 suppliers in Stuttgart and Munich. For Investors and Strategic Acquirers: Consolidation pressure builds where mixed-signal verification talent scarcity stretches UHBR20 link-training development timelines at fabless design houses. Long-term viability favors vendors with comprehensive PHY-MAC integration capabilities rather than modular component suppliers. Watch VESA certification queue backlogs as an inflection indicator for revenue recognition delays.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Advanced Node Access | TSMC N3E allocation agreements secure tape-out capacity for UHBR20 automotive PHY cores. |
| ASIL-B Certification Investment | German KBA type-approval processes increasingly mandate fault-tolerant architectures for instrument clusters. |
| Reference Design Bundle Expansion | Fixed-fee licensing to Taiwan ODMs accelerates time-to-revenue through validated subsystem handoffs. |
| Halogen-Free Package Stack Validation | EU REACH SVHC screening gates cockpit electronics deployment for European automotive OEMs. |
| MIPI Convergence Hedging | Dual-protocol IP portfolios defend against interface consolidation threatening standalone DisplayPort volumes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IP vendor product managers, Tier-1 automotive supplier procurement leads, Taiwan ODM engineering directors, and South Korean panel maker technology strategists. Secondary validation drew from VESA specification releases, ECHA SVHC candidate list updates, SEC 10-K filings from listed semiconductor IP vendors, and foundry capacity disclosure reports. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions.
Segment-weighting approaches modeled revenue distribution across IP core, reference design, IP block, and protocol stack product types, with end-user splits for automotive, consumer electronics, computing, and telecommunication applications. Technology dimensions included display, transmission, interface standard, and signal processing categories. CAGRs were derived from regression analysis of historical licensing intensity against panel shipment forecasts and semiconductor content trends. Automotive safety integrity requirements and gaming monitor refresh specifications served as industry-specific demand drivers.
EU F-Gas Regulation expansion, MIPI DSI-2 substitution velocity, and EUV lithography capacity bottlenecks are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about VESA roadmap convergence and REACH substance restriction timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
NFC Chips Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market