
 Precision Measuring Tools Market | 2026-2036
Precision Measuring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Measuring Tools Market Analytics
Software-defined calibration and remote diagnostics is consolidating recurring revenue streams alongside hardware sales. Mitutoyo Corporation leverages its Japanese manufacturing scale to anchor premium digital caliper production. Hexagon AB competes through integrated metrology software platforms that extend hardware functionality. Zeiss specializes in optical coordinate measuring systems for tight-tolerance aerospace applications.
Precision measuring tools encompass dimensional, geometric, and force-quantification instruments engineered to tolerances of ±0.001 mm or finer, typically manufactured from hardened steel, ceramic, or carbide substrates through grinding, lapping, and laser-interferometer verification processes. These instruments serve primarily to validate conformance in subtractive and additive manufacturing workflows. Optical measurement technology leads value capture due to non-contact inspection requirements in semiconductor wafer qualification. Digital measurement systems displace analog variants fastest across automotive powertrain lines where SPC integration demands direct data logging. Force measurement tools occupy narrower margin pools but sustain demand from materials testing laboratories requiring ISO 376-traceable load cell verification.
FDA 21 CFR Part 820 quality system regulations mandate validated inspection equipment for medical device production, while ISO 17025 accreditation requirements shape laboratory procurement specifications across North America and Europe. Japan's JIS B 7507 standard governs micrometer accuracy grades, creating compliance-driven replacement cycles. Stakeholders must monitor convergence between metrology data formats and MES platforms to secure interoperability premiums.
Market Dynamics
ISO 10360 tightening for coordinate measuring machines is forcing quality control laboratories into accelerated replacement cycles, compressing the interval between certification-driven hardware upgrades from seven years toward four.
Growth Catalysts
- Automotive Powertrain Digitization:SPC integration mandates across German and Japanese assembly lines are pulling digital calipers and bore gauges into direct MES connectivity, eliminating manual data transcription.
- Semiconductor Wafer Qualification:Non-contact optical interferometry is displacing stylus-based methods for sub-micron die-level inspection, expanding addressable tool categories in Taiwan and South Korea fabs.
- Medical Device Validation:FDA 21 CFR Part 820 enforcement is elevating inspection equipment to validated system status, triggering procurement of ISO 17025-traceable instruments in US orthopedic implant manufacturing.
Market Restraints
- Input Concentration:Synthetic ruby ball production for probe tips concentrates in Thailand and Switzerland, exposing CMM manufacturers to single-source ceramic supply risk.
- Certification Friction:JIS B 7507 grade distinctions for micrometer accuracy create non-tariff barriers for non-Japanese entrants seeking automotive OEM qualification.
- Substitution Pressure:CT-based volumetric measurement is capturing complex geometry inspection from tactile CMMs in aerospace casting validation, eroding hardware utilization rates.
Strategic Opportunities
- Indian Precision Manufacturing:BIS adoption of ISO 10360 for domestic CMM certification is opening laboratory upgrade demand in Pune and Bangalore automotive supplier parks.
- Cloud-Connected Calibration:Remote diagnostics platforms are unbundling service revenue from hardware margins, creating recurring income streams alongside capital sales.
- Additive Manufacturing Metrology:In-situ laser scanning for powder-bed fusion is converging process monitoring with post-build inspection, collapsing two tool categories into integrated cells.
Industry Challenges
- Interoperability Complexity:Proprietary data formats from Mitutoyo, Hexagon, and Zeiss systems are fragmenting MES integration, forcing buyers into single-vendor lock-in or expensive middleware development.
- Metrology Talent Scarcity:CMM programming and uncertainty budgeting skills are concentrating in aging technician populations across US and European calibration laboratories, constraining throughput expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Measuring Tools Market |
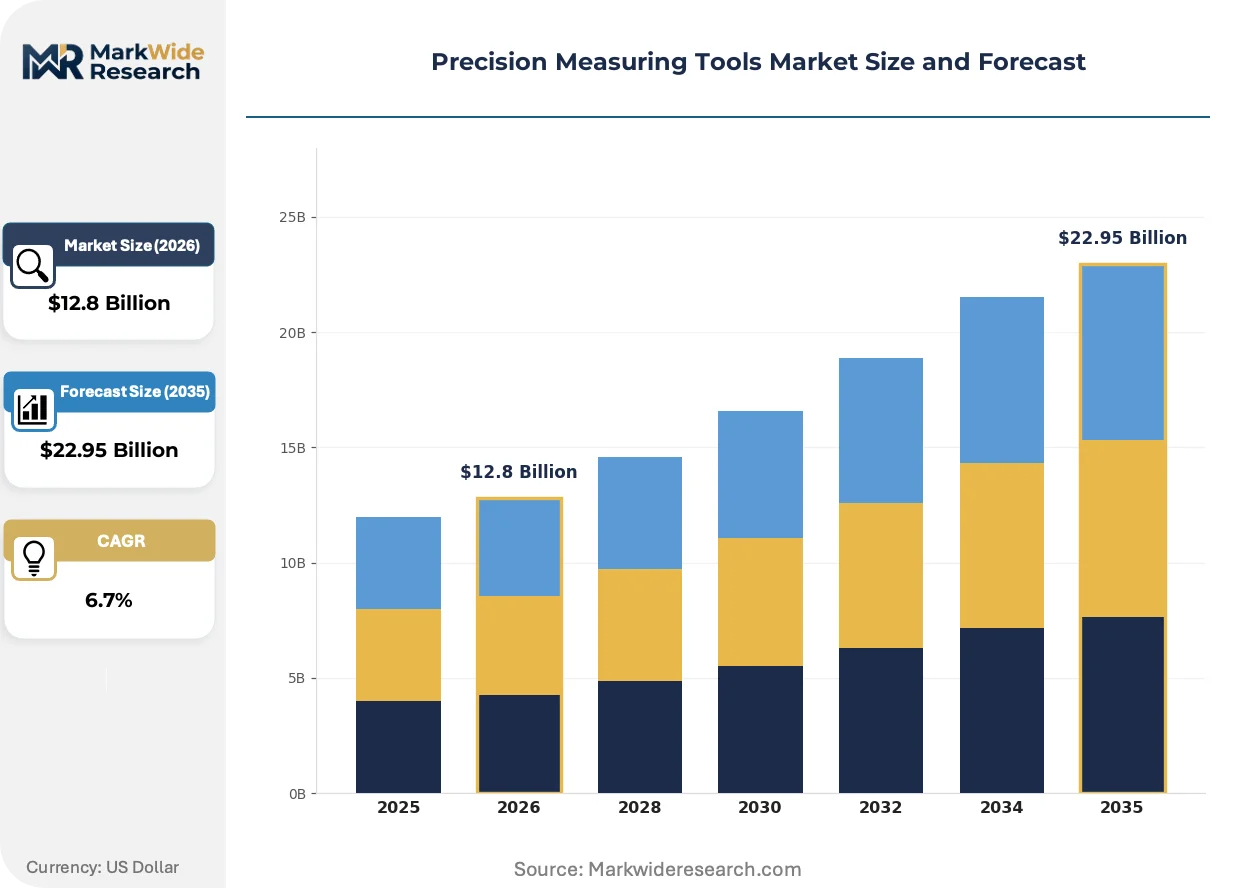
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calipers, Micrometers, Gauge Blocks, Force Measurement Tools Technology: Optical Measurement, Laser Measurement, Digital Measurement, Analog Measurement Application: Aerospace, Automotive Manufacturing, Construction, Medical Device Production End User: Manufacturers, Research Institutions, Quality Control Labs, Educational Institutions |
| Companies Covered | Mitutoyo Corporation, Starrett, Hexagon AB, Zeiss, Renishaw plc, Nikon Metrology, Mahr GmbH, Heidenhain Corporation, FARO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Measuring Tools Market Evolving Landscape
Software-defined functionality is redefining hardware value capture, with calibration algorithms and remote service platforms now contributing margin comparable to physical instrument sales.
Multi-sensor CMM architectures are integrating tactile probing, optical scanning, and CT reconstruction within single coordinate frames. Aerospace turbine blade manufacturers in France and Germany are adopting these systems to collapse sequential inspection stations into unified cells. This convergence is integrating formerly separate capital budgets and compressing vendor consolidation timelines.
REACH restrictions on hexavalent chromium surface treatments are eliminating traditional hard chrome plating for gauge block manufacturing. European metrology houses are shifting toward titanium nitride and diamond-like carbon coatings, raising unit costs but extending calibration intervals. This regulatory pressure is most acute in German and Swiss laboratory supply chains, where coating conversion timelines now determine product launch schedules.
Asset-light rental and subscription models are displacing outright purchase for high-value optical CMMs. Tier-two automotive suppliers in China's Yangtze River Delta are accessing Zeiss and Hexagon systems through third-party fleet operators, converting capital expenditure to operational spend. This financing innovation is most visible in Shenzhen precision manufacturing clusters, where tooling-as-a-service providers now intermediate 15 percent of annual CMM placements.
Precision Measuring Tools Market Segmentation
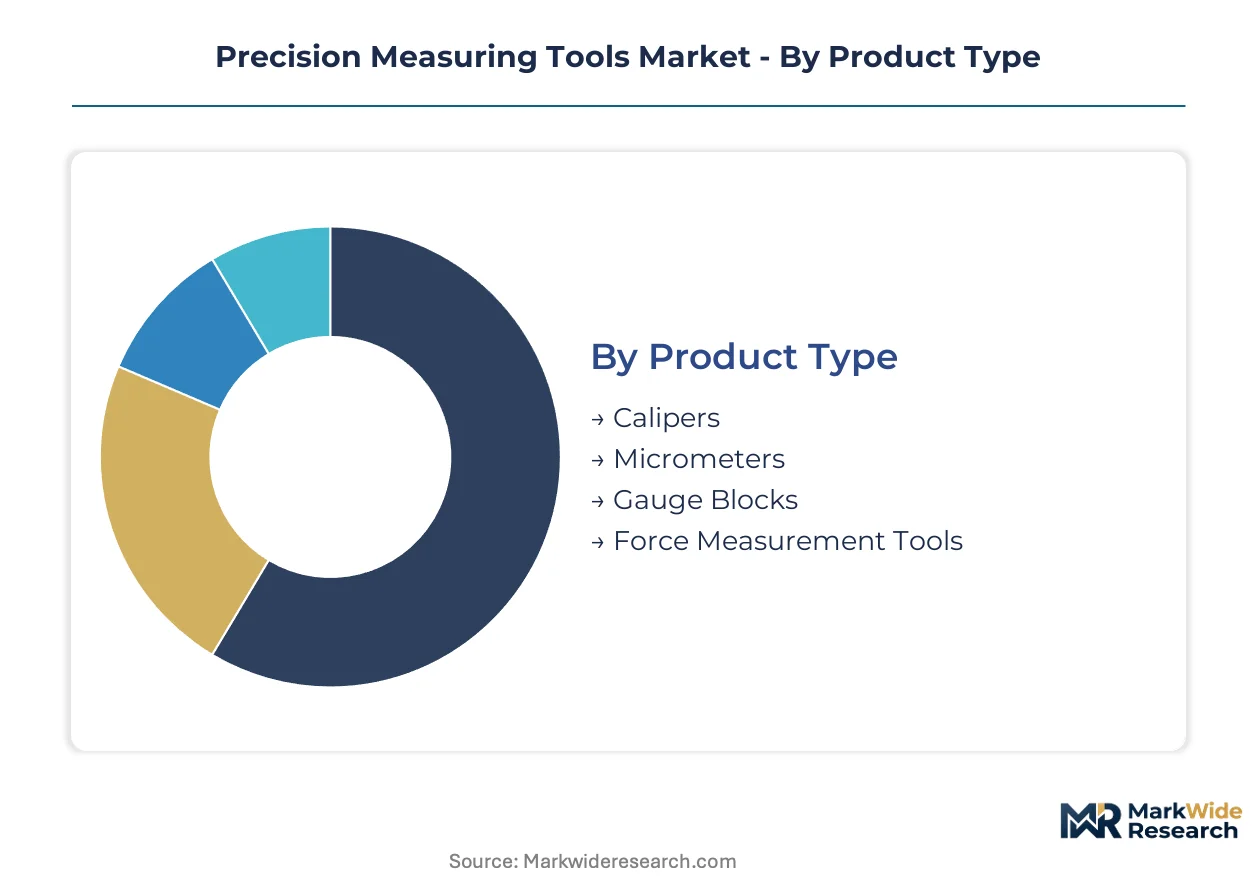
Segmentation in precision measuring tools determines procurement specifications, calibration intervals, and vendor selection criteria. ISO 10360 certification requirements and end-use tolerance demands create distinct upgrade cycles across each category, forcing buyers to align capital planning with segment-specific replacement timelines.
Product Type:
Replacement cycles vary sharply by product type, with digital variants compressing upgrade intervals through software-obsolescence pressure while mechanical tools follow slower physical-wear schedules.
- Calipers:Digital calipers with direct MES connectivity dominate automotive powertrain lines in Germany and Japan, where SPC integration eliminates manual data transcription. Demand concentrates in Shenzhen precision manufacturing clusters, where tooling-as-a-service models now intermediate fleet access.
- Micrometers:These instruments achieve ±0.001 mm resolution through hardened steel or carbide screw-thread mechanisms, with JIS B 7507 accuracy grades governing automotive OEM qualification in Japan. Japanese manufacturers anchor premium production through captive grinding and lapping capacity.
- Gauge Blocks:Hardened steel or ceramic reference standards undergo laser-interferometer verification, with REACH restrictions on hexavalent chromium plating forcing coating conversion toward titanium nitride in European supply chains.
- Force Measurement Tools:ISO 376-traceable load cells serve materials testing laboratories, occupying narrower margin pools but sustaining demand from validation requirements in orthopedic implant manufacturing.
Calipers sit at the top of the volume ranking, with digital variants climbing the fastest as MES integration mandates expand.
Technology:
Cost tiers separate these technologies, with optical and laser systems commanding premium pricing for non-contact applications while analog measurement retains residual share in cost-constrained settings.
- Optical Measurement:Non-contact interferometry systems capture sub-micron semiconductor wafer qualification in Taiwan and South Korea fabs, displacing stylus-based methods for die-level inspection. These systems lead value capture across the technology spectrum.
- Laser Measurement:Laser-based metrology enables in-situ scanning for powder-bed fusion additive manufacturing, converging process monitoring with post-build inspection in aerospace turbine blade production across France and Germany.
- Digital Measurement:Direct data-logging variants displace analog fastest across automotive assembly lines, though proprietary data formats from major vendors fragment MES integration and force single-vendor lock-in.
- Analog Measurement:Mechanical dial indicators and vernier scales persist in educational institutions and developing-market quality control labs where capital constraints override connectivity requirements.
Optical measurement commands the highest price tier, with laser measurement expanding most quickly through additive manufacturing adoption.
Application:
Application segmentation tracks directly to regulatory stringency, with FDA and aerospace tolerance mandates driving specification premiums versus construction's cost-optimized procurement.
- Aerospace:Tight-tolerance turbine blade inspection demands multi-sensor CMM architectures integrating tactile probing, optical scanning, and CT reconstruction, collapsing sequential inspection stations into unified cells.
- Automotive Manufacturing:Powertrain digitization mandates across German and Japanese OEMs pull digital calipers and bore gauges into direct MES connectivity, with ISO 10360 tightening forcing accelerated replacement cycles.
- Construction:Structural steel and concrete dimensional verification employs lower-precision instruments, with procurement prioritizing durability over sub-micron resolution.
- Medical Device Production:FDA 21 CFR Part 820 quality system regulations mandate validated inspection equipment, triggering ISO 17025-traceable instrument procurement in US orthopedic implant manufacturing.
Automotive manufacturing generates the highest unit volume, with medical device production gaining share fastest through regulatory enforcement expansion.
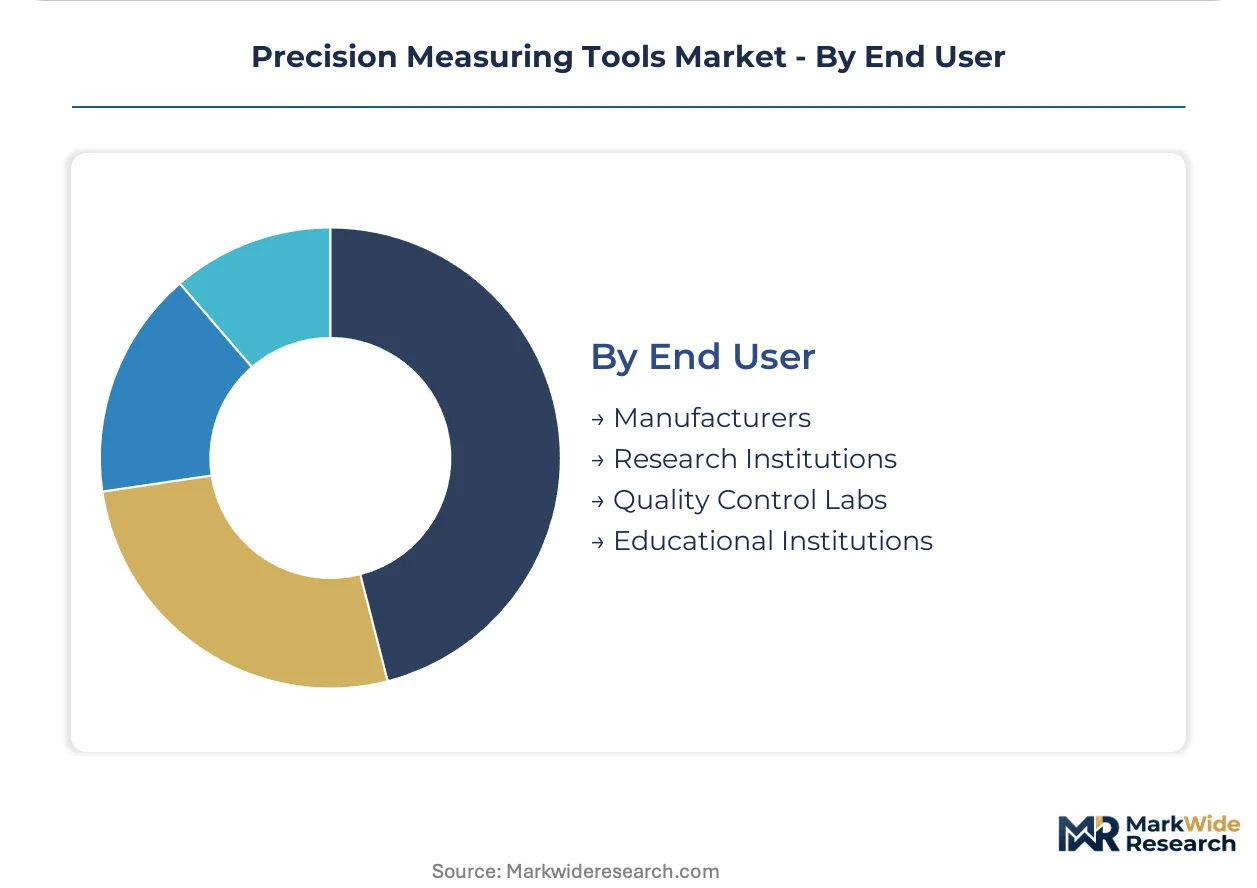
End User:
Customer type determines service-model preferences, with manufacturers prioritizing uptime guarantees while research institutions emphasize calibration-traceable uncertainty budgets.
- Manufacturers:Tier-two automotive suppliers in China's Yangtze River Delta access high-value optical CMMs through third-party fleet operators, converting capital expenditure to operational spend.
- Research Institutions:National metrology laboratories and university engineering departments drive demand for primary reference standards and laser-interferometer verification systems.
- Quality Control Labs:ISO 17025 accreditation requirements shape procurement specifications across North America and Europe, with CMM programming skills concentrating in aging technician populations.
- Educational Institutions:Vocational training programs and university labs sustain residual demand for analog measurement tools where budget constraints limit digital system adoption.
Manufacturers represent the largest end-user segment, with quality control labs climbing fastest through ISO 17025 accreditation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan drive contrasting demand patterns, with German automotive OEMs pulling laser-based metrology systems while Japanese manufacturers anchor premium digital caliper production through captive grinding capacity.
United States
FDA 21 CFR Part 820 enforcement elevates inspection equipment to validated system status across orthopedic implant manufacturing. Quality control laboratories in Massachusetts and Minnesota face ISO 17025 accreditation requirements that shape procurement specifications. Medical device clusters around Boston and Minneapolis-St. Paul are accelerating replacement cycles for coordinate measuring machines.
Germany
Automotive powertrain digitization mandates across BMW and Volkswagen assembly lines pull digital calipers into direct MES connectivity. REACH restrictions on hexavalent chromium plating force coating conversion toward titanium nitride in gauge block manufacturing. Metrology houses in Stuttgart and Munich are shifting supply chains to comply with ECHA substance regulations.
China
Precision manufacturing clusters around Shenzhen and Shanghai concentrate demand for tooling-as-a-service models that convert capital expenditure to operational spend. BIS adoption of ISO 10360 for domestic CMM certification opens laboratory upgrade demand in automotive supplier parks. Yangtze River Delta tier-two suppliers access Zeiss and Hexagon systems through third-party fleet operators.
Japan
JIS B 7507 accuracy grades for micrometers create compliance-driven replacement cycles in automotive OEM qualification. METI industrial standards support captive production of hardened steel and carbide screw-thread mechanisms. Manufacturing scale in Tokyo and Osaka anchors premium digital caliper supply for export markets.
India
BIS harmonization with ISO 10360 standards triggers CMM certification requirements in domestic quality control laboratories. Automotive supplier parks in Pune and Bangalore face tightening metrology specifications from multinational OEMs. Precision manufacturing investments in Maharashtra and Karnataka are pulling ISO 17025-traceable instrument procurement.
Precision Measuring Tools Market Competitive Landscape
Top-tier vendors anchor integrated metrology software platforms, while mid-tier specialists compete through regional manufacturing scale and coating technology differentiation. The vendor base stratifies across three tiers: multinational platform providers with software-defined calibration revenue, regional precision manufacturers with captive substrate production, and niche optical specialists serving semiconductor fabs. Consolidation pressure is accelerating through multi-sensor CMM architectures that collapse sequential inspection stations, while remote diagnostics platforms unbundle service revenue from hardware margins.
Within the multinational platform tier, Mitutoyo Corporation exemplifies Japanese manufacturing scale in premium digital instrument production, while Hexagon AB occupies a position in integrated metrology software that extends hardware functionality. Zeiss represents the optical coordinate measuring specialization for tight-tolerance aerospace applications. These three anchors illustrate how competitive positioning diverges across software integration, manufacturing scale, and optical technology vectors.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Starrett |
| Hexagon AB |
| Zeiss |
| Renishaw plc |
| Nikon Metrology |
| Mahr GmbH |
| Heidenhain Corporation |
| FARO |
| Others |
Value Network & Pricing Analysis
REACH restrictions on hexavalent chromium surface treatments gate qualified supply for European gauge block manufacturers, extending calibration intervals for titanium nitride coatings while raising unit costs and compressing margin pools for buyers lacking premium-tier access.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for digital calipers and bore gauges. Three-tier pricing structure across premium, standard, and economy levels separates MES-integrated systems from analog variants, with ISO 10360 certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from tooling-as-a-service fleet operators converting capital expenditure to operational spend. Tier-two automotive suppliers in China exhibit highest price sensitivity; aerospace turbine blade manufacturers in France and Germany show lowest.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese automotive OEMs require qualified suppliers for synthetic ruby ball probe tips across Thailand and Switzerland. Raw material dependencies center on hardened steel substrates, ceramic substrates, and carbide screw-thread mechanisms. Single-source ceramic supply risk concentrates in Thai ruby ball production. Distribution runs through third-party fleet operators and direct OEM relationships in precision manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through REACH compliance cost differentials between European and Asian coating conversion timelines, with German metrology houses facing accelerated expense recognition against Chinese competitors.
For Market Incumbents: To counter CT-based volumetric measurement substitution in aerospace casting validation, Mitutoyo and Hexagon should deepen backward integration into captive grinding capacity for hardened steel mechanisms while accelerating cloud-connected calibration platform deployment to unbundle recurring service revenue from hardware margins.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in ISO 17025-traceable force measurement tools opens white-space opportunity in Indian orthopedic implant manufacturing. Target Pune and Bangalore automotive supplier parks with BIS-certified CMM offerings. Pursue tooling-as-a-service partnerships with third-party fleet operators to bypass capital-constrained procurement barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional precision manufacturers with captive substrate production because multi-sensor CMM architectures are collapsing sequential inspection stations and compressing vendor consolidation timelines. Five-to-ten year viability hinges on software-defined calibration revenue streams. Monitor convergence between metrology data formats and MES platforms as inflection signal for interoperability premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Platform | Unbundles service revenue from hardware margins for Mitutoyo and Hexagon. |
| Coating Technology Conversion | REACH compliance in German supply chains shifts gauge block production to titanium nitride. |
| Multi-Sensor CMM Architecture | Aerospace turbine blade manufacturers in France collapse sequential inspection stations. |
| Tooling-as-a-Service Expansion | Third-party fleet operators intermediate CMM access in Shenzhen precision clusters. |
| BIS Certification Investment | Opens laboratory upgrade demand in Pune and Bangalore automotive supplier parks. |
Research Methodology
Coverage spans Germany, Japan, China, the United States, and India, with primary inputs from each. Calibration laboratory directors, automotive OEM quality engineers, metrology equipment procurement managers, and semiconductor fab process engineers provided structured interviews. Secondary validation drew from ISO 10360 certification databases, FDA 21 CFR Part 820 inspection records, JIS B 7507 standard documentation, and BIS harmonization filings. Bottom-up unit economics triangulated against top-down industry spend estimates.
Rate-of-change decomposition separated volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user category. CAGRs derived from regression against automotive production indices, semiconductor capital expenditure cycles, and medical device regulatory enforcement intensity. Forecast inputs incorporated additive manufacturing adoption curves and MES integration penetration rates.
The model assumes a particular technology adoption path; alternative pathways for CT-based volumetric measurement would alter the outlook. Forecasts reflect assumptions regarding ISO 10360 tightening timelines, REACH coating conversion completion rates, and metrology talent availability in aging technician populations. Deviation in regulatory enforcement intensity or supply chain reshoring mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Tribometer Market
Test and Measurement
Compression Testers Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
VXI Test Equipment Market