
 Low-Power Wearable Chips Market | 2026-2036
Low-Power Wearable Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Power Wearable Chips Market Foresight
Multi-source procurement for advanced process nodes is recalibrating how wearable chip vendors secure wafer capacity. Qualcomm Incorporated leverages its fabless model to access leading-edge foundry output across multiple geographies. Nordic Semiconductor anchors its position through integrated radio-plus-MCU designs purpose-built for ultra-low-energy Bluetooth applications. Texas Instruments Incorporated sustains manufacturing depth with internal 300mm fabrication for analog-intensive power management circuits.
Low-power wearable chips are mixed-signal integrated circuits fabricated on 22nm to 40nm process nodes, integrating sub-1V microcontrollers with dedicated sensor hubs and wireless transceivers to operate below one milliwatt in active states for continuous biometric data acquisition. Medical monitors command premium pricing due to FDA and EMA validation requirements for clinical-grade photoplethysmography and electrocardiography accuracy. Bluetooth technology dominates connectivity attach rates across fitness trackers and smartwatches, while NFC is displacing magnetic stripe in payment-enabled wearables across European and Asian consumer segments.
FDA premarket clearance timelines and EMA MDR conformity assessments directly shape product development cycles and geographic launch sequencing for health-monitoring wearable chips. The EU AI Act adds algorithmic transparency obligations for chips running on-device inference for arrhythmia detection and fall prediction. Stakeholders must monitor how IEC 62304 software lifecycle requirements propagate from finished devices back to chip-level firmware architectures.
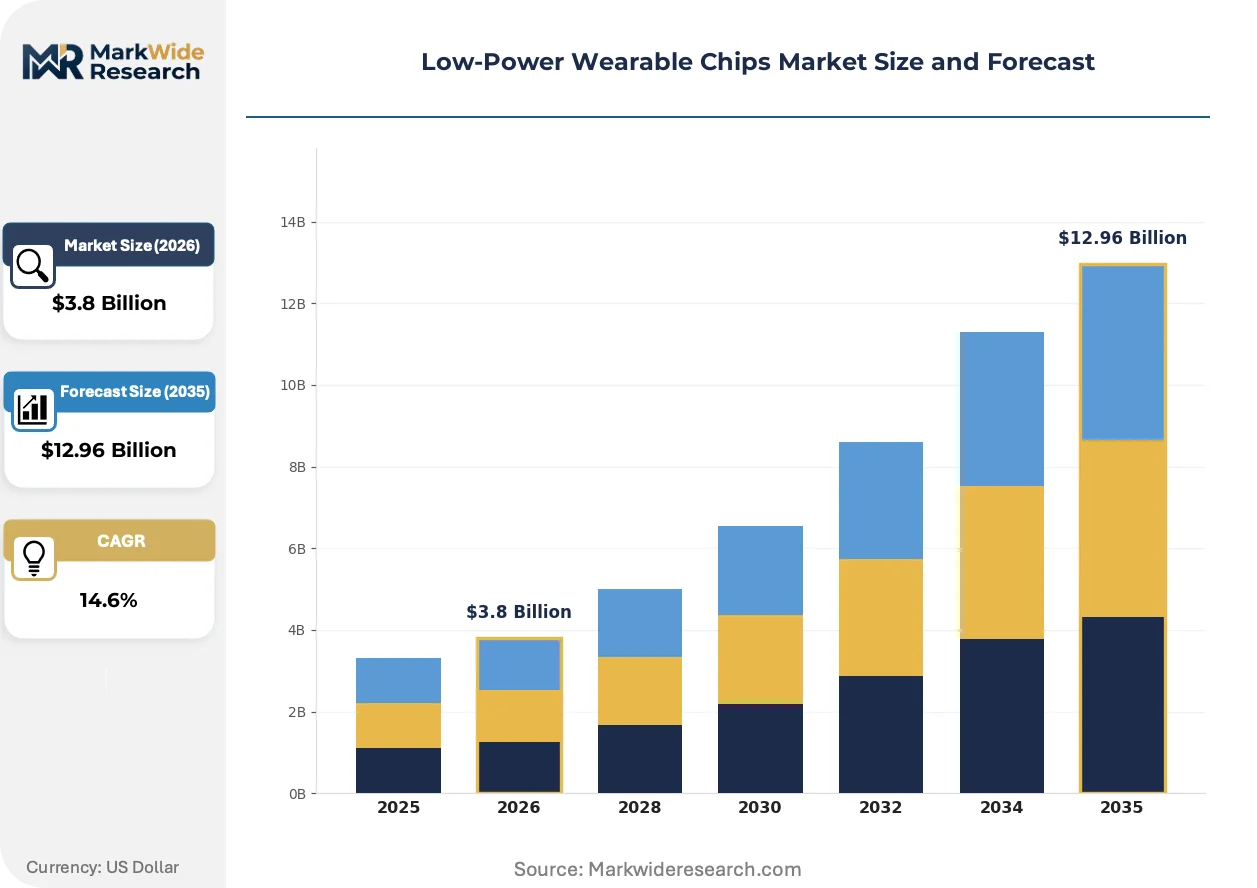
Market Dynamics
Multi-source procurement for advanced process nodes is recalibrating how wearable chip vendors secure wafer capacity across competing foundry ecosystems. The shift from single-source dependency to geographically distributed fabrication partnerships is compressing lead times while introducing new qualification overhead for medical-grade silicon.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket notification timelines for photoplethysmography-enabled devices are pulling clinical-grade silicon into consumer wearables faster than historical medical device cycles permitted.
- Sub-1V microcontroller architectures:Process node scaling to 22nm is enabling continuous biometric monitoring below one milliwatt active power, unlocking multi-day battery life in smartwatch form factors previously constrained to single-day operation.
- South Korea semiconductor cluster density:Co-location of Samsung Foundry, SK Hynix packaging facilities, and wearable OEM headquarters in Gyeonggi Province is shortening NPI cycles for Bluetooth-enabled health monitors.
Market Restraints
- TSMC advanced node allocation scarcity:Fabless wearable chip vendors face 40-week queue positions for 28nm and 22nm capacity as automotive and AI accelerators absorb leading-edge output.
- EMA MDR conformity assessment backlog:Notified body capacity constraints are extending clinical validation timelines for EU-bound medical wearables by 8-14 months versus pre-2021 Medical Device Regulation implementation.
- Indium gallium arsenide photodetector cost volatility:Sporadic supply disruptions from Chinese rare earth processing facilities are inflating bill-of-materials for optical heart rate sensors by double-digit percentages.
Strategic Opportunities
- India PLI scheme for wearables:Production-linked incentives targeting domestic manufacturing of electronic components are attracting chip packaging and testing investments from global suppliers seeking tariff-advantaged access to South Asian consumer markets.
- EU AI Act algorithmic transparency mandates:On-device inference requirements for arrhythmia classification are creating premium silicon tiers with dedicated neural processing units and immutable audit logging.
- Convergence of UWB and Bluetooth Low Energy:Integrated radio architectures enabling precise spatial positioning alongside biometric streaming are opening enterprise safety and access control applications beyond consumer fitness.
Industry Challenges
- Mixed-signal design talent scarcity:The intersection of RF transceiver, analog power management, and digital sensor hub expertise concentrates in a handful of semiconductor design centers, constraining vendor expansion.
- IEC 62304 software lifecycle propagation:Medical device quality system requirements are cascading backward to chip-level firmware architectures, forcing foundry customers to absorb documentation burdens previously borne by finished device manufacturers.
- Legacy hospital IT integration friction:Clinical-grade wearable data streams require HL7 FHIR compliance and on-premise edge gateway deployment, complicating direct-to-cloud architectures favored by consumer-oriented silicon vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Power Wearable Chips Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smartwatches, Medical Monitors, Sleep Trackers Technology: Bluetooth, NFC, Wi-Fi, Zigbee End User: Healthcare Providers, Athletes, Consumers, Enterprises Application: Health Monitoring, Activity Tracking, Communication, Navigation |
| Companies Covered | Qualcomm Incorporated, Nordic Semiconductor, Microchip Technology, Texas Instruments Incorporated, NXP Semiconductors, Infineon Technologies, Analog Devices, Inc., STMicroelectronics, Arm Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Power Wearable Chips Market Shifts & Advancements
Process-node migration and regulatory algorithmic mandates are rewriting the technical specifications and commercial timelines for biometric semiconductor deployment. The convergence of medical certification requirements with consumer electronics velocity is forcing architectural innovations that span both domains simultaneously.
Event-driven sensor hub architectures with asynchronous duty cycling are rewriting power-performance tradeoffs for continuous health monitoring. Medical monitor OEMs in Germany and the United States are adopting these designs for 24-hour Holter replacements that maintain clinical accuracy at consumer-wearable battery budgets. The structural consequence is collapsing the traditional separation between Class II medical devices and lifestyle fitness trackers.
The EU AI Act's risk-based classification system for biometric inference algorithms is mandating deterministic execution paths and explainable decision trees in arrhythmia detection firmware. Chip vendors serving European markets must now implement hardware-isolated audit logs and non-rewritable model versioning. Medical wearable segments targeting EU distribution are responding by pre-integrating certified algorithm IP blocks at the silicon level rather than licensing post-fabrication.
Hospital procurement departments are consolidating vendor relationships around platforms that bundle FDA-cleared sensors with enterprise data integration. Health systems in the United States are displacing point-solution wearable vendors in favor of chip suppliers whose reference designs include pre-validated cybersecurity frameworks and HIPAA-compliant cloud connectors. This concentration is most visible in integrated delivery networks across Texas and California where single-source contracting for remote patient monitoring is becoming standard practice.
Low-Power Wearable Chips Market Segmentation
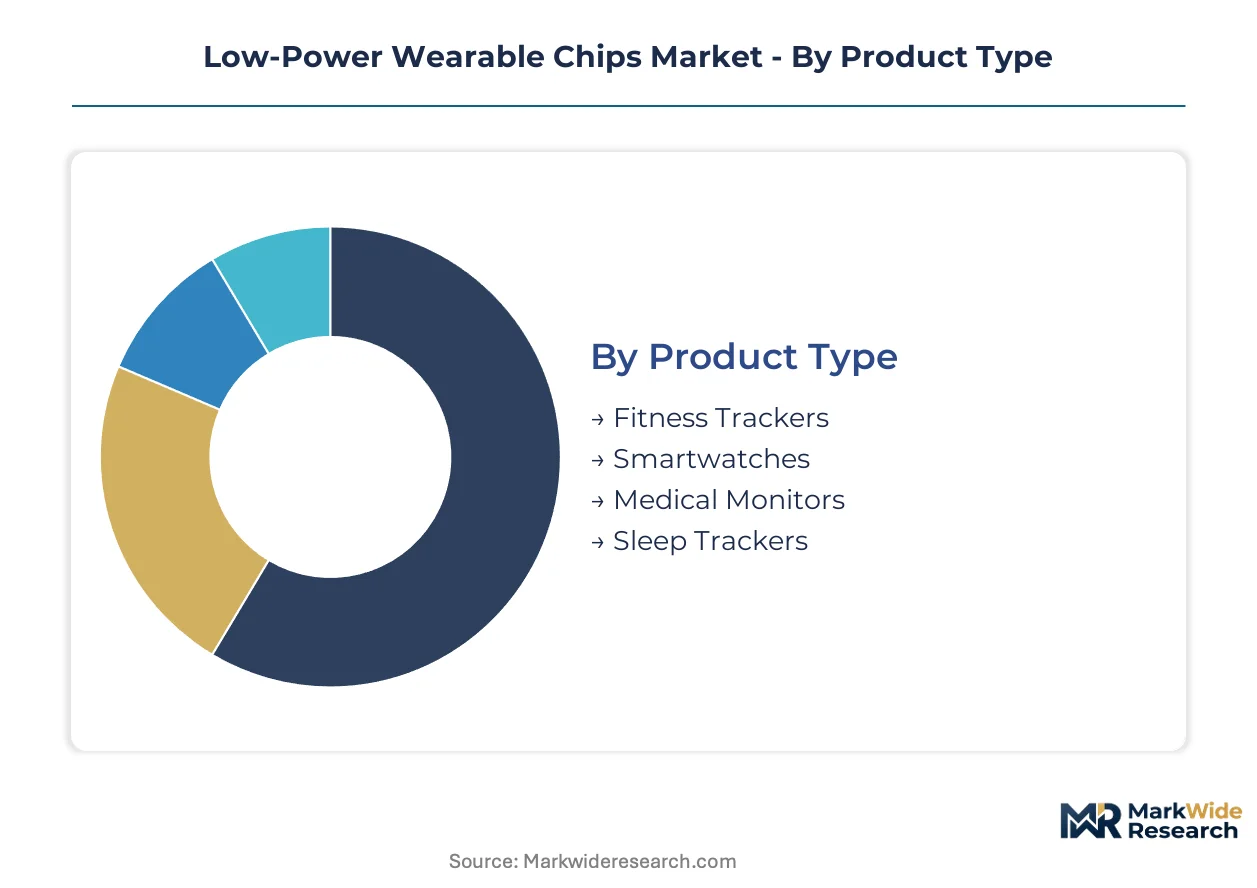
Segmentation in low-power wearable chips reveals how power budgets, certification requirements, and connectivity protocols fragment demand across device categories. Buyers select silicon based on whether clinical validation, consumer battery life, or enterprise security dominates their procurement criteria.
Product Type:
Purchase decisions in this category pivot on FDA and EMA certification requirements versus consumer price elasticity.
- Medical Monitors:Clinical-grade silicon integrates photoplethysmography and electrocardiography acquisition chains with IEC 62304-compliant firmware architectures. German hospital procurement departments and United States integrated delivery networks concentrate demand here, pulled by remote patient monitoring reimbursement codes and FDA 510(k) pathway streamlining for continuous arrhythmia detection.
- Smartwatches:These devices merge sub-1V microcontroller platforms with Bluetooth Low Energy transceivers and NFC payment controllers on 22nm process nodes. South Korean OEM headquarters in Gyeonggi Province drive volume, compressing new product introduction cycles through proximity to Samsung Foundry and SK Hynix packaging facilities.
- Fitness Trackers:Cost-optimized 40nm implementations prioritize step counting and basic heart rate variability over clinical accuracy. Indian PLI scheme incentives are attracting chip packaging investments targeting tariff-advantaged access to South Asian consumer markets.
- Sleep Trackers:Ultra-low-energy accelerometer-plus-PPG configurations operate below 0.5 milliwatts during overnight monitoring. United States direct-to-consumer wellness brands dominate procurement.
Smartwatches lead on scale; medical monitors lead on momentum.
Technology:
Connectivity protocol selection determines RF front-end complexity, antenna integration costs, and geographic certification burdens.
- Bluetooth:Bluetooth Low Energy 5.3 dominates attach rates across fitness and smartwatch segments, with Nordic Semiconductor and Qualcomm driving integrated radio-plus-MCU designs. United States and South Korean OEMs standardize on this protocol for interoperability with iOS and Android ecosystems.
- NFC:Payment-enabled wearables across European and Asian consumer segments are displacing magnetic stripe infrastructure. The EU AI Act adds algorithmic transparency obligations for chips running on-device inference alongside contactless transaction processing.
- Wi-Fi:Higher throughput requirements for clinical-grade wearable data streaming demand more power-intensive 2.4GHz and 5GHz implementations. United States hospital IT departments require HL7 FHIR compliance for these data pipes.
- Zigbee:Enterprise safety applications and industrial wearable deployments leverage this mesh protocol for facility-wide coverage. German manufacturing clusters show concentrated procurement for worker location tracking.
Bluetooth leads on scale; NFC leads on momentum.
End User:
Customer type dictates firmware security tiers, cloud integration architectures, and support contract structures.
- Healthcare Providers:FDA and EMA validation requirements for continuous patient monitoring command premium silicon pricing. Texas and California health systems consolidate vendor relationships around platforms bundling pre-validated cybersecurity frameworks and HIPAA-compliant cloud connectors.
- Consumers:Price sensitivity and multi-day battery life expectations drive demand toward 40nm process implementations with asynchronous duty cycling. South Korean and United States wearable OEM clusters serve this segment.
- Athletes:Specialized biometric accuracy for lactate threshold and VO2 max estimation requires calibrated optical sensor fusion. German sports technology brands concentrate procurement.
- Enterprises:UWB and Bluetooth Low Energy convergence enables precise spatial positioning for access control and safety compliance. United States industrial facilities and German manufacturing plants drive adoption.
Healthcare providers lead on scale; enterprises lead on momentum.
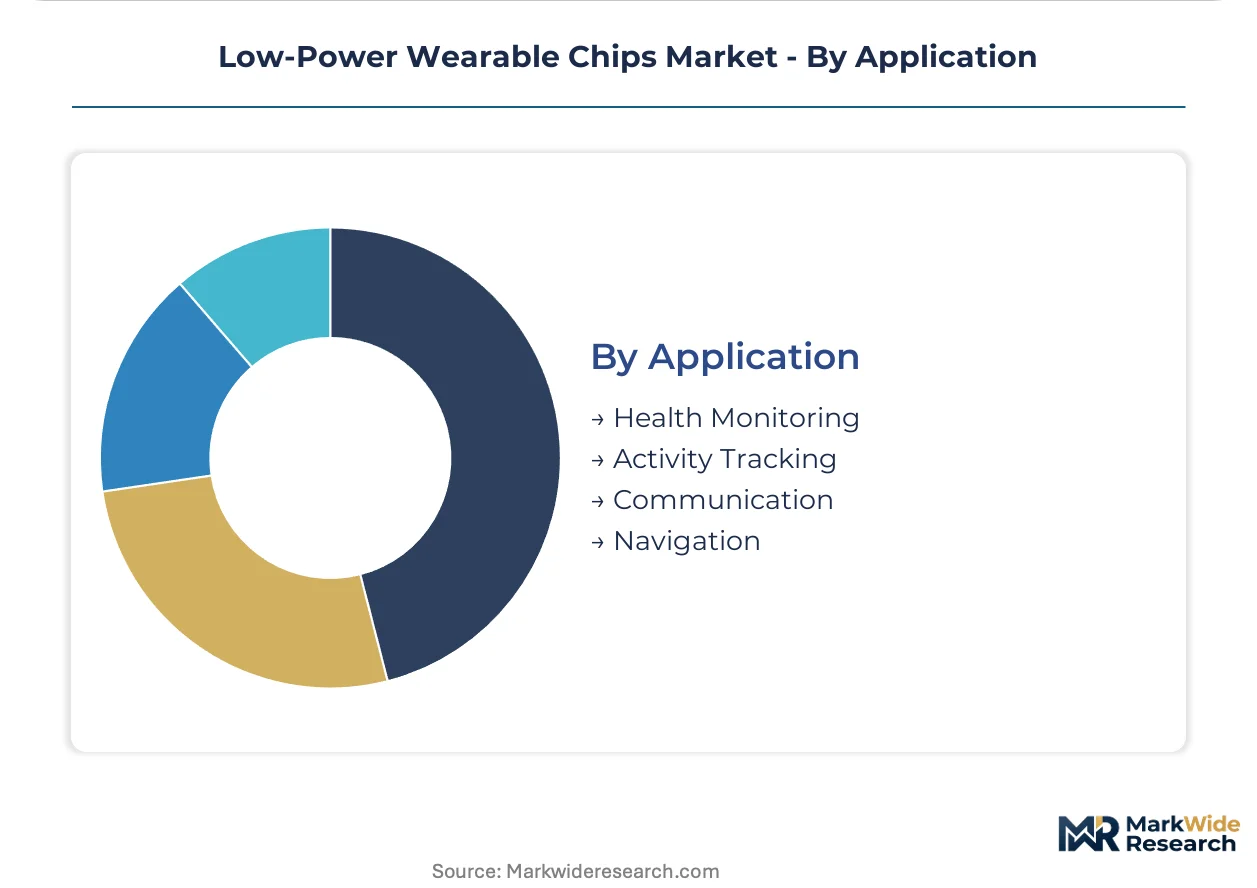
Application:
Use case determines sensor hub complexity, algorithm processing requirements, and regulatory exposure.
- Health Monitoring:Continuous biometric acquisition for arrhythmia detection and fall prediction requires EU AI Act-compliant deterministic execution paths with hardware-isolated audit logs. European medical wearable segments pre-integrate certified algorithm IP blocks at the silicon level.
- Activity Tracking:Step counting and calorie estimation run on minimal microcontroller resources with event-driven sensor hub architectures. Indian and South Asian consumer markets concentrate volume.
- Communication:Voice calling and notification relay demand higher-duty-cycle wireless transceivers with noise-canceling audio DSP integration. United States smartwatch OEMs prioritize this functionality.
- Navigation:GPS and GNSS positioning for outdoor fitness applications adds significant power overhead, requiring larger battery form factors or solar harvesting supplementation. German and United States outdoor wearable specialists concentrate demand.
Health monitoring leads on scale; navigation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province semiconductor cluster density concentrates advanced packaging capacity and wearable OEM headquarters within a single metropolitan radius. FDA 510(k) pathway streamlining in the United States and EMA MDR conformity assessments in Germany are recalibrating geographic launch sequencing for clinical-grade silicon. India PLI scheme incentives are attracting chip testing investments targeting tariff-advantaged South Asian consumer markets.
United States
Texas and California integrated delivery networks consolidate vendor relationships around pre-validated cybersecurity frameworks and HIPAA-compliant cloud connectors. FDA premarket clearance timelines directly compress product development cycles for photoplethysmography-enabled devices. Greater Boston health systems drive procurement concentration for remote patient monitoring reimbursement codes.
Germany
Baden-Württemberg hospital procurement departments command premium silicon pricing for IEC 62304-compliant firmware architectures in continuous arrhythmia detection. EMA MDR conformity assessment backlogs extend clinical validation timelines for EU-bound medical wearables. Bavarian manufacturing clusters show concentrated procurement for Zigbee-enabled worker location tracking in enterprise safety applications.
South Korea
Seoul Capital Area wearable OEM headquarters compress new product introduction cycles through proximity to Samsung Foundry and SK Hynix packaging facilities. MFDS medical device regulations align with FDA 510(k) streamlining for Bluetooth-enabled health monitors. Busan-Ulsan semiconductor fabrication corridors anchor 22nm process node migration for sub-1V microcontroller platforms.
India
Maharashtra and Karnataka electronics manufacturing zones attract chip packaging investments under PLI scheme production-linked incentives for tariff-advantaged South Asian market access. BIS certification requirements for wireless devices shape import substitution strategies for fitness tracker silicon. Delhi-NCR consumer electronics distribution channels concentrate demand for 40nm cost-optimized implementations.
United Kingdom
London-Southeast health technology procurement departments navigate MHRA post-Brexit regulatory alignment with EMA MDR standards for clinical-grade wearable data streams. UKCA marking requirements for radio equipment directive compliance add certification overhead for Bluetooth Low Energy transceiver imports. Cambridge technology clusters concentrate algorithm development for EU AI Act-compliant deterministic execution paths.
Low-Power Wearable Chips Market Competitive Landscape
Global majors compete with regional champions across foundry access and medical certification depth. The vendor base stratifies between fabless designers securing multi-source wafer capacity and integrated device manufacturers sustaining captive fabrication for analog-intensive power management. Three archetypes dominate: radio-plus-MCU integrators, mixed-signal power management specialists, and algorithm-IP licensors. Strategic moves concentrate on backward integration into sensor fusion software and geographic diversification of packaging partnerships.
Within the fabless tier, Qualcomm Incorporated and Nordic Semiconductor occupy positions anchored by multi-source foundry relationships and integrated radio architectures. Texas Instruments Incorporated exemplifies the IDM archetype through internal 300mm fabrication depth. These three companies represent the competitive spectrum spanning wireless connectivity licensing, ultra-low-energy Bluetooth specialization, and analog power management integration.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| Nordic Semiconductor |
| Microchip Technology |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Infineon Technologies |
| Analog Devices, Inc. |
| STMicroelectronics |
| Arm Limited |
| Others |
Supply & Pricing Matrix
Hospital procurement departments in Texas and California integrated delivery networks concentrate purchasing power around pre-validated cybersecurity frameworks, creating a contract-based long-term offtake model that rewards certification depth over unit cost competition. FDA 510(k) pathway streamlining accelerates this consolidation by compressing vendor qualification timelines for clinical-grade silicon.
Pricing Analysis
Indium gallium arsenide photodetector cost volatility passes through directly to optical heart rate sensor bill-of-materials, with sporadic supply disruptions from Chinese rare earth processing facilities inflating component costs by double-digit percentages. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical monitors from consumer fitness trackers and basic step counters. Cost compression in the fitness tracker tier intensifies because Indian PLI scheme incentives attract tariff-advantaged packaging investments targeting South Asian consumer markets. Healthcare providers show least price sensitivity due to reimbursement code coverage, while direct-to-consumer wellness brands exhibit highest elasticity.
Supply Chain Analysis
Mixed-signal design talent scarcity concentrates in Taiwan, South Korea, and the United States, constraining vendor expansion as RF transceiver, analog power management, and digital sensor hub expertise clusters in a handful of semiconductor design centers. Wafer fabrication draws from Samsung Foundry and TSMC for 22nm to 40nm process nodes, while SK Hynix and domestic Indian packaging facilities handle backend assembly. Single-source vulnerability at TSMC advanced node allocation creates 40-week queue positions as automotive and AI accelerators absorb leading-edge output. Distribution runs through Gyeonggi Province OEM headquarters for South Korean brands and direct foundry relationships for United States fabless vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 14.60% CAGR differential between United States FDA-cleared medical monitors and Indian tariff-advantaged fitness trackers creates geographic-arbitrage opportunities for vendors with dual-certification capabilities. EMA MDR conformity assessment backlogs in Germany extend EU launch timelines by 8-14 months versus pre-2021 implementation, compressing returns for single-market players.
For Market Incumbents: Cement multi-source foundry relationships across Samsung Foundry and TSMC to insulate against 28nm and 22nm capacity scarcity driven by automotive and AI accelerator demand. Expand internal 300mm fabrication depth for analog-intensive power management circuits to defend margin position against fabless competitors facing 40-week queue positions. Prioritize IEC 62304 software lifecycle documentation investments to capture hospital procurement consolidation around pre-validated cybersecurity frameworks. For New Entrants and Emerging Players: Enterprise safety applications represent the most penetrable white-space target, with UWB and Bluetooth Low Energy convergence enabling precise spatial positioning for access control beyond consumer fitness. German manufacturing clusters show concentrated procurement for Zigbee-enabled worker location tracking, while United States industrial facilities drive adoption for enterprise security compliance. Pursue algorithm-IP licensing partnerships with Cambridge technology clusters to accelerate EU AI Act-compliant deterministic execution path development. For Investors and Strategic Acquirers: Hospital systems and integrated delivery networks are the most active acquirer in this space, consolidating vendor relationships around platforms bundling FDA-cleared sensors with HIPAA-compliant cloud connectors. Long-term viability hinges on backward integration into sensor fusion software and geographic diversification of packaging partnerships. Watch for MFDS-FDA regulatory alignment completion in South Korea as inflection indicator for Gyeonggi Province cluster acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Foundry Partnership | TSMC and Samsung Foundry diversification insulates against 40-week queue positions for 22nm capacity. |
| IEC 62304 Firmware Certification | Medical device quality system compliance captures Texas and California hospital procurement consolidation. |
| EU AI Act Algorithm Integration | Hardware-isolated audit logs and deterministic execution paths unlock European medical wearable distribution. |
| India PLI Packaging Investment | Tariff-advantaged backend assembly targets South Asian consumer market volume expansion. |
| UWB-Bluetooth Radio Convergence | Precise spatial positioning opens enterprise safety applications beyond consumer fitness tracking. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with semiconductor design executives, foundry account managers, hospital biomedical engineers, and wearable OEM procurement leads with secondary validation from FDA 510(k) filings, EMA MDR submission databases, MFDS regulatory announcements, and SEC 10-K disclosures from fabless vendors. Bottom-up wafer demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Historical reference periods anchored the projection horizon to pre-COVID baseline capacity utilization and post-MDR implementation regulatory timelines. Segmentation dimensions modeled include product type certification tier, connectivity protocol, end-user security requirements, and geographic regulatory cluster. CAGRs derived from foundry capacity expansion schedules, OEM new product introduction cycles, and reimbursement code adoption curves in United States integrated delivery networks.
Inputs from FDA premarket notification databases and EMA notified body capacity reports were available through the study window; gaps in real-time foundry utilization data introduce uncertainty bands around 22nm migration timelines. Forecasts reflect assumptions about regulatory alignment between MFDS and FDA pathways and indium gallium arsenide supply stability. Material deviation in TSMC advanced node allocation or EMA MDR backlog resolution warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
8-Bit MCU Market