
 Wireless Flow Sensors Market | 2026-2036
Wireless Flow Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Flow Sensors Market Analytics
Aftermarket service revenue is tilting toward predictive diagnostics and cloud-connected calibration contracts. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor long-term service relationships with process manufacturers. Siemens AG sustains competitive pressure through its Sitrans product line and integrated automation portfolios. Honeywell International Inc. differentiates via embedded cybersecurity protocols in its wireless instrumentation suite.
Wireless flow sensors are non-contact or minimally invasive measurement devices that transmit flow-rate data via radio-frequency protocols, typically operating in industrial ISM bands with battery lifespans exceeding five years and accuracy tolerances of ±0.5% to ±2.0%. These instruments serve primary industrial purposes including leak detection, custody transfer verification, and real-time process optimization in fluid-handling systems. Ultrasonic sensors lead product type segmentation due to their compatibility with corrosive media and absence of moving parts, while electromagnetic variants occupy high-conductivity applications in water treatment and chemical processing. LoRa technology dominates the connectivity landscape for wide-area municipal deployments, whereas Bluetooth and Wi-Fi concentrate in facility-scale energy monitoring and building automation contexts.
The EPA mandates under the Safe Drinking Water Act and the EU F-Gas Regulation shape product certification requirements and refrigerant monitoring obligations across North American and European deployments. IEEE 802.15.4 and ISA-100.11a standards govern interoperability and security architecture for industrial wireless sensor networks, directly influencing procurement specifications. Stakeholders must monitor evolving cybersecurity mandates from NIST and ETSI as regulatory bodies tighten data integrity requirements for critical infrastructure telemetry.
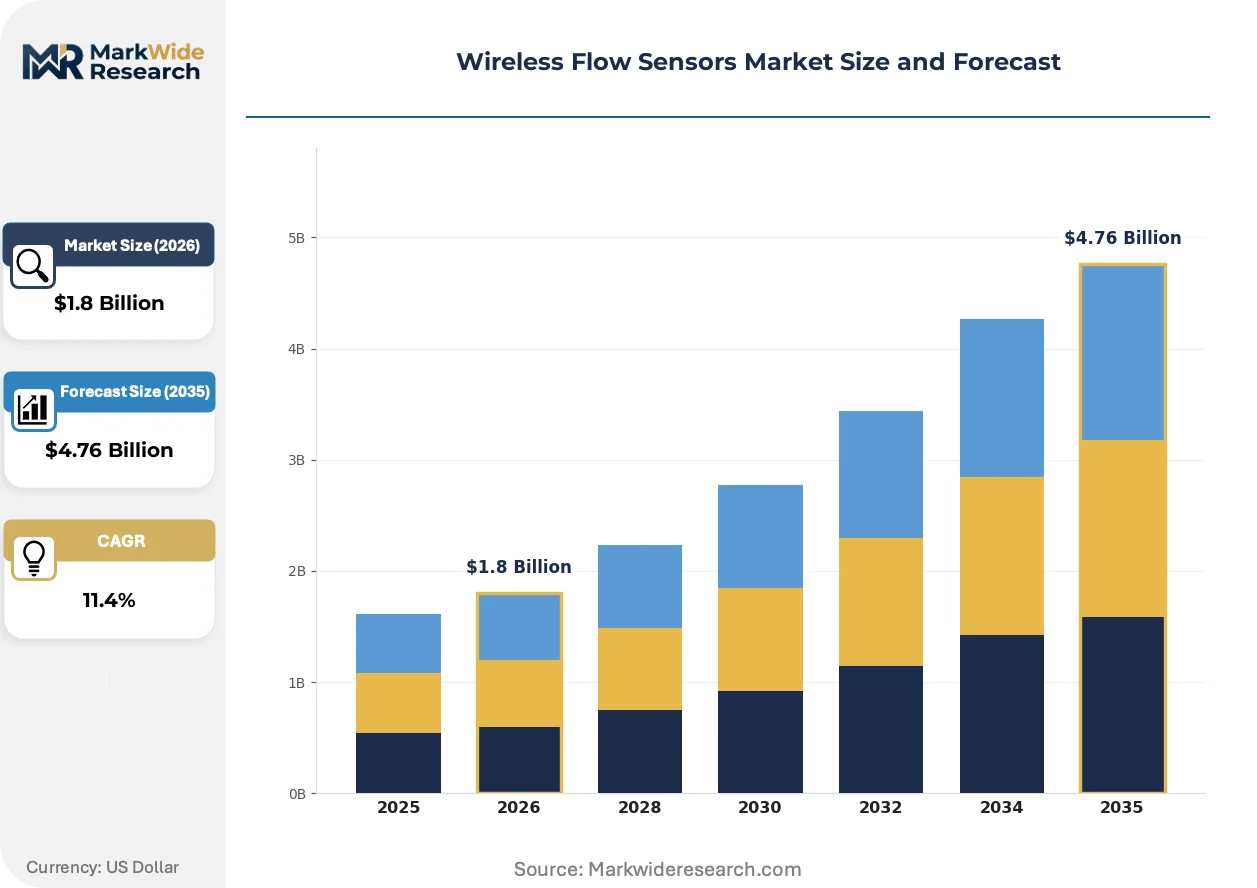
Market Dynamics
EPA lead and copper rule revisions are forcing water utilities toward remote telemetry infrastructure, compressing deployment timelines for non-invasive measurement systems and reshaping vendor procurement specifications across municipal districts.
Growth Catalysts
- Ultrasonic sensor compatibility:Non-contact designs eliminate corrosion risks in chemical processing and wastewater treatment, accelerating replacement of mechanical flow meters in German municipal networks.
- LoRa protocol standardization:Wide-area low-power connectivity enables battery-operated deployments spanning rural distribution networks without cellular infrastructure dependencies.
- EU F-Gas Regulation:Refrigerant leak monitoring mandates create compliance-driven demand for wireless flow instrumentation in HVAC and cold chain logistics across European industrial facilities.
Market Restraints
- Lithium battery supply concentration:Cell production bottlenecks in East Asian manufacturing clusters create procurement risk for five-year battery lifespan specifications.
- ISM band spectrum congestion:Industrial-scientific-medical frequency interference in dense urban deployments degrades signal reliability for real-time custody transfer applications.
- Electromagnetic sensor conductivity limits:Low-conductivity fluid measurement gaps restrict adoption in hydrocarbon processing and pharmaceutical ultrapure water systems.
Strategic Opportunities
- Predictive diagnostics convergence:Cloud-connected calibration contracts combine vibration analysis with flow anomaly detection, creating recurring revenue streams beyond hardware sales.
- Japan's infrastructure digitization:METI smart water initiatives fund ultrasonic retrofit programs in aging Tokyo-Osaka pipeline corridors.
- Bluetooth mesh facility networks:Building automation integrators deploy short-range wireless clusters for energy monitoring in commercial HVAC submetering applications.
Industry Challenges
- Cybersecurity certification timelines:NIST SP 800-53 compliance validation for critical infrastructure telemetry extends product launch cycles by eight to fourteen months.
- Legacy SCADA integration friction:Proprietary protocols in existing water utility control systems require costly gateway middleware for wireless sensor data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Flow Sensors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Electromagnetic Sensors, Thermal Sensors, Differential Pressure Sensors End User: Oil & Gas, Water Utilities, HVAC, Food & Beverage Technology: LoRa, Zigbee, Bluetooth, Wi-Fi Application: Water Management, Industrial Automation, Energy Monitoring, Environmental Monitoring |
| Companies Covered | Emerson Electric Co., Siemens AG, ABB Ltd., Honeywell International Inc., Endress+Hauser Group Services AG, Panasonic Corporation, AW-Lake, Texas Instruments Incorporated, Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Flow Sensors Market Evolving Landscape
Digital twin architectures are virtualizing physical flow infrastructure, compressing the boundary between measurement hardware and simulation software while redistributing value toward data analytics platforms.
Edge computing hardware is virtualizing signal processing functions previously executed in centralized control systems. Water utilities in the United States deploy ultrasonic sensors with onboard FFT analysis, reducing bandwidth requirements for leak detection algorithms. This compression of compute geography is virtualizing the traditional SCADA hierarchy and enabling municipal districts to scale sensor density without proportional infrastructure investment.
REACH substance restrictions are tightening material specifications for sensor housings and sealing compounds in European process industries. Manufacturers reformulate elastomer components to eliminate SVHC candidates, extending certification timelines but creating compliance differentiation for early movers. Chemical processing facilities in Germany and the Netherlands now specify full material disclosure as a procurement gate, prioritizing vendors with established regulatory documentation systems.
Service unbundling is fragmenting traditional equipment procurement into separate hardware, connectivity, and analytics contracts. Municipal water districts in Japan and the United States negotiate predictive maintenance subscriptions independent of sensor capital expenditure, shifting vendor relationships toward outcome-based performance guarantees. This disaggregation is most visible in North American utilities facing EPA compliance deadlines, where operational expenditure flexibility outweighs capital budget constraints for infrastructure monitoring programs.
Wireless Flow Sensors Market Segmentation
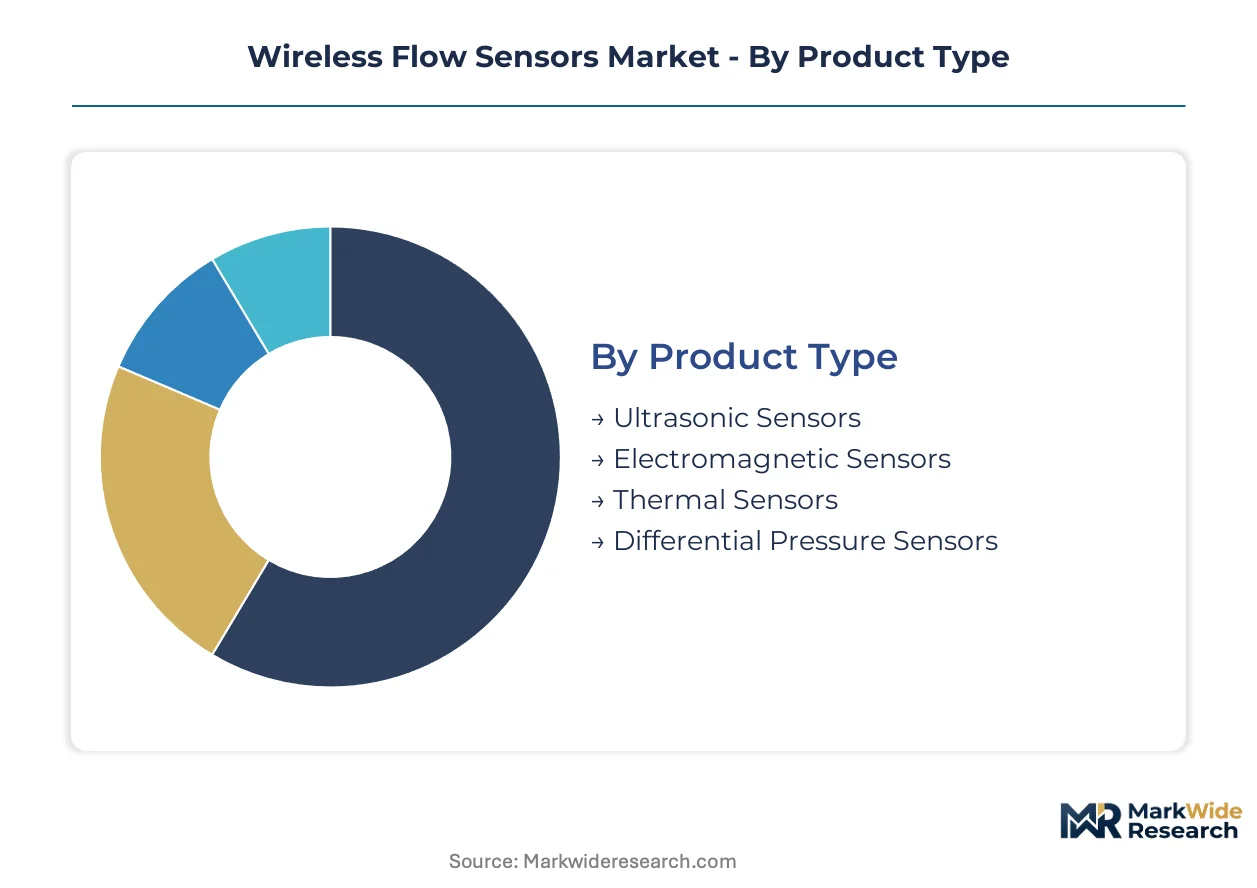
Wireless flow sensors serve divergent operational requirements across fluid-handling infrastructure. Product specifications, connectivity protocols, and end-use environments create distinct procurement criteria that reshape vendor positioning and technology roadmaps.
Product Type:
The use-case spectrum spans corrosive chemical handling to ultrapure pharmaceutical systems, with measurement principles dictating media compatibility and maintenance intervals.
- Ultrasonic Sensors:Non-contact transit-time or Doppler measurement eliminates wetted parts and corrosion vulnerability. German municipal water districts in the Ruhr region deploy these for aging cast-iron pipeline monitoring where invasive installation risks structural integrity.
- Electromagnetic Sensors:Faraday's law-based measurement requires minimum fluid conductivity, typically above 5 μS/cm. These instruments dominate wastewater treatment facilities in Japan's Kansai region where conductive slurries demand robust through-flow designs.
- Thermal Sensors:Calorimetric or hot-wire principles suit low-flow gas measurement in compressed air audit applications.
- Differential Pressure Sensors:Orifice plate and venturi configurations persist in legacy oilfield custody transfer installations requiring mechanical redundancy.
The dominant share belongs to Ultrasonic Sensors, while Electromagnetic Sensors is closing the gap fastest.
End User:
Customer procurement sophistication varies dramatically, with capital expenditure cycles and regulatory exposure driving contract structures.
- Water Utilities:EPA Lead and Copper Rule revisions mandate remote telemetry for lead service line inventory. Municipal districts in California and Texas compress deployment timelines for non-invasive retrofit programs.
- Oil & Gas:Custody transfer accuracy requirements of ±0.25% drive specification of dual-path ultrasonic configurations. Permian Basin operators prioritize battery-operated designs for remote wellpad flowback monitoring.
- HVAC:Building automation integrators specify Bluetooth mesh for chiller plant energy submetering in commercial real estate portfolios.
- Food & Beverage:3-A sanitary standards constrain sensor housing materials and surface finish specifications in dairy processing.
Water Utilities commands the largest installed base, though Oil & Gas is expanding most quickly in absolute unit terms.
Technology:
Connectivity selection hinges on geographic coverage requirements, infrastructure density, and power budget constraints across deployment scenarios.
- LoRa:Sub-GHz unlicensed spectrum enables 10-kilometer range in rural terrain with sub-milliwatt transmit power. Japanese water utilities under METI digitization grants deploy LoRaWAN for agricultural district metered area monitoring.
- Zigbee:IEEE 802.15.4-based mesh networking supports industrial process control with deterministic latency requirements. German chemical processors specify Zigbee 3.0 for intrinsically safe zone 2 instrumentation.
- Bluetooth:Short-range protocols concentrate in facility-scale energy management where smartphone commissioning reduces installation labor.
- Wi-Fi:High-bandwidth backhaul suits video-augmented maintenance workflows in urban water treatment plants with existing enterprise infrastructure.
LoRa holds the dominant protocol share, while Bluetooth is gaining share fastest in building automation retrofit applications.
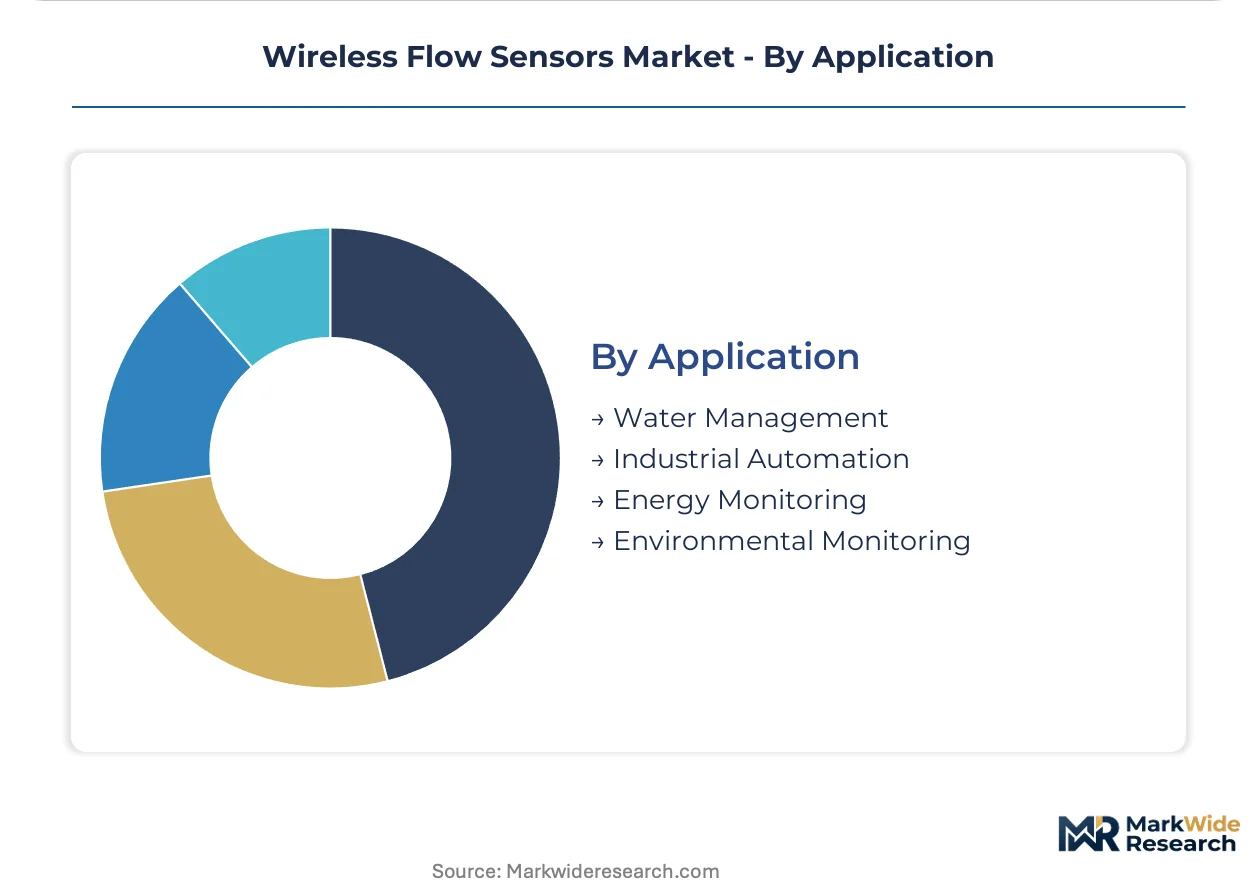
Application:
Functional deployment contexts determine sensor specification, calibration frequency, and data analytics integration depth.
- Water Management:Leak detection algorithms process pressure transient signatures from ultrasonic arrays. Singapore's national water agency PUB mandates acoustic correlation for distribution network integrity assessment.
- Industrial Automation:Real-time process optimization requires millisecond-scale flow feedback for closed-loop control in continuous chemical manufacturing.
- Energy Monitoring:Thermal flow measurement in HVAC chilled water loops supports carbon accounting disclosure under CSRD for European facility operators.
- Environmental Monitoring:Battery-powered deployments in remote watersheds track discharge compliance for EPA NPDES permit holders.
Water Management represents the largest application segment, with Energy Monitoring climbing the fastest on building efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water utilities in Germany exhibit the lowest price elasticity, accepting premium instrumentation for compliance certainty, while commercial HVAC integrators in India prioritize unit economics over feature depth. This demand stratification reshapes vendor go-to-market investments across geographies.
United States
EPA Lead and Copper Rule revisions compress procurement cycles for non-invasive retrofit programs. California's State Water Resources Control Board mandates acoustic leak detection for distribution networks exceeding 100,000 service connections. Los Angeles Department of Water and Power deploys ultrasonic arrays across the San Fernando Valley corridor.
Germany
Ruhr region municipalities prioritize corrosion-resistant instrumentation for aging cast-iron pipeline integrity. REACH substance restrictions tighten elastomer specifications for sensor housings in chemical processing applications. BASF's Ludwigshafen complex specifies full material disclosure as a procurement gate for flow instrumentation.
Japan
METI smart water initiatives fund ultrasonic retrofit programs in the Tokyo-Osaka pipeline corridor. Osaka Prefecture's water bureau deploys LoRaWAN-enabled sensors for agricultural district metered area monitoring. Kansai region wastewater treatment facilities specify electromagnetic designs for conductive slurry applications.
China
Dual carbon goals accelerate building automation submetering for commercial HVAC efficiency verification. MIIT standards govern industrial wireless sensor network interoperability in process manufacturing. Yangtze River Delta chemical processors specify Zigbee 3.0 for intrinsically safe zone 2 instrumentation.
Singapore
PUB mandates acoustic correlation technology for national water distribution integrity assessment. The national water agency's smart grid program specifies millimeter-scale accuracy for custody transfer verification. Jurong Island process complexes deploy edge-computing ultrasonic sensors with onboard FFT analysis.
Wireless Flow Sensors Market Competitive Landscape
Industrial conglomerates and specialized instrumentation houses split the market along integration depth versus application focus. Consolidation pressure intensifies as municipal procurement shifts toward outcome-based performance contracts. Three archetypes dominate: full-stack automation platforms, component-specialist suppliers, and regional system integrators. Geographic expansion and predictive diagnostics convergence represent the dominant competitive vectors reshaping vendor positioning.
Among diversified industrial technology groups, Emerson Electric Co. and Siemens AG exemplify the platform-centric archetype, anchoring long-term service relationships through digital ecosystem integration. Honeywell International Inc. occupies a differentiated position emphasizing embedded cybersecurity protocols. Component specialists including Texas Instruments Incorporated and Microchip Technology Inc. supply radio-frequency and signal processing chipsets that underpin battery-operated sensor architectures. Regional instrumentation houses such as Endress+Hauser Group Services AG and AW-Lake represent the application-engineering tier, translating generic sensor platforms into vertical-specific compliance solutions.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens AG |
| ABB Ltd. |
| Honeywell International Inc. |
| Endress+Hauser Group Services AG |
| Panasonic Corporation |
| AW-Lake |
| Texas Instruments Incorporated |
| Microchip Technology Inc. |
| Others |
Value Network & Pricing Analysis
Lithium cell production bottlenecks in East Asian manufacturing clusters concentrate upstream supply leverage, anchoring margin pools in battery procurement contracts rather than sensor assembly. Pricing power tilts toward vendors with captive five-year power supply agreements, compressing hardware margins for assemblers lacking backward integration into cell sourcing.
Pricing Analysis
Predictive diagnostics and cloud-connected calibration contracts now drive lifetime value, shifting vendor economics toward recurring service revenue. Pricing stratifies across premium certified tiers for EPA compliance applications, standard mid-range instrumentation for municipal retrofits, and economy units for building automation submetering. Cost compression in hardware tiers is intensifying because semiconductor foundry allocation favors automotive and consumer electronics over industrial sensor chipsets. Water utilities facing EPA deadlines exhibit the lowest price sensitivity, accepting premium instrumentation for compliance certainty, while commercial HVAC integrators prioritize unit economics over feature depth.
Supply Chain Analysis
Contract manufacturing capacity for industrial wireless sensors concentrates with Foxconn Industrial Internet, Jabil, and Sanmina in China, Mexico, and Malaysia. Radio-frequency chipsets draw from Taiwan Semiconductor Manufacturing and Texas Instruments fabrication in Taiwan and the United States. Lithium thionyl chloride cells feed from South Korean and Japanese chemical processors. Single-source vulnerability in sub-GHz transceiver modules creates procurement risk for LoRa-enabled deployments. Distribution runs through authorized industrial automation distributors and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless flow sensors trace a cyclical recovery pattern tied to municipal infrastructure replacement waves, with EPA compliance deadlines compressing procurement into concentrated demand windows.
For Market Incumbents: Pre-empt margin erosion in hardware tiers by deepening captive supply of lithium power systems and ultrasonic transducer elements. Consolidate predictive maintenance platforms through acquisition of cloud analytics specialists before outcome-based contracts lock in municipal relationships. Anchor defensive positioning against emerging Bluetooth mesh entrants in commercial building automation. For New Entrants and Emerging Players: Agricultural district metered area monitoring in Japan's Kansai region and Texas water conservation districts represent the most penetrable entry points for ultrasonic retrofit specialists. Target Bluetooth mesh facility networks in North American commercial real estate portfolios where incumbent automation platforms lack wireless commissioning expertise. Lead with smartphone-based installation workflows that reduce field labor costs versus legacy SCADA integration requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional instrumentation houses holding established EPA compliance documentation systems. Five-to-ten year viability hinges on predictive diagnostics revenue mix rather than hardware shipment volume. Watch for inflection in municipal outcome-based contract penetration rates as the signal for platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Platform Acquisition | Cloud analytics specialists with EPA compliance data pipelines command premium multiples from Emerson and Honeywell. |
| Backward Integration into Battery Supply | Captive lithium thionyl chloride sourcing insulates five-year lifespan specifications from East Asian cell allocation constraints. |
| Bluetooth Mesh Certification Investment | 3.0 stack validation for zone 2 intrinsically safe deployments opens German chemical processing procurement specifications. |
| LoRaWAN Network Operator Partnership | Japanese METI digitization grants favor vendors with established carrier relationships for agricultural district monitoring. |
| Edge Computing Hardware Development | Onboard FFT analysis capability differentiates ultrasonic arrays for Singapore PUB acoustic correlation mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal water utility engineering directors, industrial automation procurement managers, OEM sensor platform architects, and aftermarket service contract administrators. Secondary validation drew from EPA enforcement and compliance databases, IEEE 802.15.4 protocol certification registries, METI smart water initiative disbursement records, and SEC filings of listed industrial conglomerates. Bottom-up unit deployment estimates triangulated against top-down infrastructure replacement cycle analysis.
Calibration against historical deployment trajectories in German municipal networks and Japanese METI-funded corridors anchored growth rate derivation across the analysis window. Segmentation modeling incorporated product type measurement principle, connectivity protocol spectrum allocation, end-user capital expenditure cycle, and regional regulatory enforcement intensity. CAGRs reflect fitted adoption curves for ultrasonic retrofit penetration and LoRaWAN network buildout timelines.
Stress conditions across lithium supply disruption scenarios, ISM band spectrum reallocation, and EPA rule implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding battery chemistry stability and municipal procurement authorization timelines. Quarterly review of EPA state revolving fund disbursement rates and METI grant award velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Micropump Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Digital Pump Controller Market