
 Micro Server IC Market | 2026-2036
Micro Server IC Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Server IC Market Analysis
High-density ARM processor configurations is rotating through the Micro Server IC Market as cloud operators prioritize performance-per-watt metrics. Intel Corporation leverages its x86 ecosystem dominance to sustain foundry relationships with enterprise server OEMs. NVIDIA Corporation anchors AI inference workloads through its Grace CPU platforms. Marvell Technology differentiates via custom silicon programs for hyperscale clients.
Micro Server ICs integrate low-power multi-core processors, high-bandwidth memory interfaces, and integrated I/O controllers into thermally constrained packages designed for edge and scale-out data center nodes. ARM-based processors command the fastest expansion trajectory as Amazon Web Services and Microsoft Azure deploy Graviton and Cobalt architectures. Memory Modules concentrate margin pools where DDR5 and HBM3 transitions create supply constraints. Networking Chips face mature pricing dynamics in 1GbE segments while 400GbE and 800GbE controllers capture premium positioning.
FCC equipment authorization rules shape electromagnetic compliance testing for US-deployed micro server hardware, while the EPA ENERGY STAR server specification drives idle-power thresholds. The EU AI Act imposes risk-classification requirements on AI training infrastructure, directly affecting processor validation protocols for European deployments. Stakeholders must monitor how NIST post-quantum cryptography standards will mandate silicon-level security accelerators across federal procurement channels.

Market Dynamics
ARM ISA licensing models are compressing x86 incumbency across hyperscale compute clusters as cloud operators engineer custom silicon roadmaps. This architectural rotation restructures procurement relationships between semiconductor vendors and data center operators.
Growth Catalysts
- EU AI Act risk-classification mandates:European deployments now require validated AI training infrastructure, accelerating processor qualification cycles for vendors with pre-certified security architectures.
- Performance-per-watt optimization:Cloud operators in Northern Virginia and Oregon are specifying ARM-based clusters to meet corporate sustainability commitments and local utility demand-response programs.
- Edge compute node proliferation:Telecommunications infrastructure buildouts for 5G standalone networks are absorbing thermally constrained multi-core packages for distributed processing.
Market Restraints
- Advanced packaging substrate shortages:Organic substrate supply from Taiwan and South Korea concentrates delivery risk for high-density interposer designs.
- Instruction set architecture switching costs:Enterprise software licensing and toolchain migration expenses deter x86-to-ARM transitions outside cloud-native workloads.
- EUV lithography capacity constraints:TSMC and Samsung Foundry node allocation prioritizes smartphone APs over micro server volume production.
Strategic Opportunities
- India data center localization:The country's PLI scheme for semiconductor manufacturing is attracting assembly and test investments for region-specific micro server SKUs.
- Chiplets and 2.5D integration:Modular die disaggregation enables mix-and-match compute, memory, and I/O tiles for workload-optimized configurations.
- EPA ENERGY STAR server specification:Idle-power thresholds below 50 watts create premium positioning for vendors with advanced power-gating implementations.
Industry Challenges
- Post-quantum cryptography silicon validation:NIST algorithm standardization timelines compress hardware security module redesign cycles for federal procurement eligibility.
- Legacy firmware abstraction layers:BIOS and UEFI compatibility gaps between ARM and x86 ecosystems fragment system management software development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Server IC Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processors, Memory Modules, Storage Controllers, Networking Chips End User: Data Centers, Cloud Providers, Enterprises, Research Institutions Form Factor: Compact, Modular, Rack-Mount, Blade Technology: ARM, x86, PowerPC, FPGA |
| Companies Covered | NVIDIA Corporation, Hewlett Packard Enterprise, Intel Corporation, Quanta Computer, Broadcom Inc., Advanced Micro Devices, Marvell Technology, Applied Micro Circuits, Arm Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Server IC Market Emerging Trajectories
Monolithic server processor architectures are fragmenting into disaggregated compute tiles as thermal and yield constraints force design paradigm shifts. This decomposition is accelerating qualification timelines for custom silicon programs.
Chiplet-based micro server designs are decomposing traditional monolithic die structures into specialized compute, memory, and I/O tiles interconnected through advanced packaging. Hyperscale operators including Amazon Web Services and Microsoft Azure are qualifying these modular configurations for 2025-2026 deployments. The approach is decomposing historical vendor lock-in by enabling mix-and-match IP blocks from multiple semiconductor suppliers within single packages.
The EU AI Act's risk-based classification system is mandating formal validation documentation for processors deployed in high-risk AI training infrastructure. Silicon vendors must now maintain technical file repositories and conformity assessment procedures previously associated with medical device or automotive safety standards. European data center operators are prioritizing vendors with pre-established notified body relationships to compress deployment timelines.
Cloud operator procurement is consolidating around direct silicon partnerships that bypass traditional server OEM intermediaries. Amazon Web Services, Microsoft Azure, and Google Cloud are negotiating multi-year wafer supply agreements and custom ISA extensions directly with ARM Holdings and semiconductor foundries. This channel compression is most visible in United States cloud computing hubs where vertical integration into processor design accelerates workload-optimized feature roadmaps.
Micro Server IC Market Segmentation

Micro Server IC segmentation reveals how architectural choices cascade through procurement relationships and compliance obligations. Different product categories carry distinct regulatory footprints across hyperscale deployments.
Product Type:
EU AI Act risk-classification mandates and EPA ENERGY STAR specifications create divergent validation burdens across IC categories.
- Processors:Multi-core CPU dies integrate power management units and security accelerators into thermally constrained packages. Demand concentrates in Northern Virginia and Oregon cloud hubs where Amazon Web Services and Microsoft Azure specify ARM-based clusters for corporate sustainability commitments and local utility demand-response programs.
- Memory Modules:DDR5 and HBM3 interfaces create supply-constrained margin pools as data center operators transition from DDR4. European deployments prioritize vendors with pre-established notified body relationships under EU AI Act technical file requirements.
- Storage Controllers:NVMe and CXL-attached flash interfaces manage endurance and latency tradeoffs for edge node deployments.
- Networking Chips:400GbE and 800GbE controllers capture premium positioning while 1GbE segments face mature pricing dynamics in legacy enterprise refresh cycles.
Established volume favors Processors; emerging adoption favors Memory Modules.
End User:
Customer procurement scale determines silicon partnership depth and custom roadmap access.
- Data Centers:Colocation operators specify standardized SKUs with firmware abstraction layers compatible across x86 and ARM ecosystems.
- Cloud Providers:Hyperscale operators negotiate direct wafer supply agreements and custom ISA extensions with ARM Holdings and semiconductor foundries, bypassing traditional server OEM intermediaries for workload-optimized feature roadmaps.
- Enterprises:Legacy software licensing and toolchain migration expenses deter x86-to-ARM transitions outside cloud-native workloads, preserving incumbent relationships.
- Research Institutions:Federal procurement channels impose NIST post-quantum cryptography requirements that compress hardware security module redesign cycles.
Cloud Providers command the steepest expansion trajectory; Enterprises anchor replacement demand.
Form Factor:
Thermal design power budgets and physical deployment constraints segment packaging approaches.
- Compact:Fanless enclosures with sub-15W TDP targets serve telecommunications infrastructure for 5G standalone distributed processing nodes.
- Modular:Disaggregated compute tiles enable mix-and-match configurations of compute, memory, and I/O blocks from multiple semiconductor suppliers within single packages.
- Rack-Mount:Standard 19-inch chassis accommodate 1U and 2U server densities with shared power and cooling infrastructure.
- Blade:Midplane architectures consolidate management controllers and switch fabrics across multi-node sleds.
Modular form factors gain share fastest; Rack-Mount retains volume dominance.
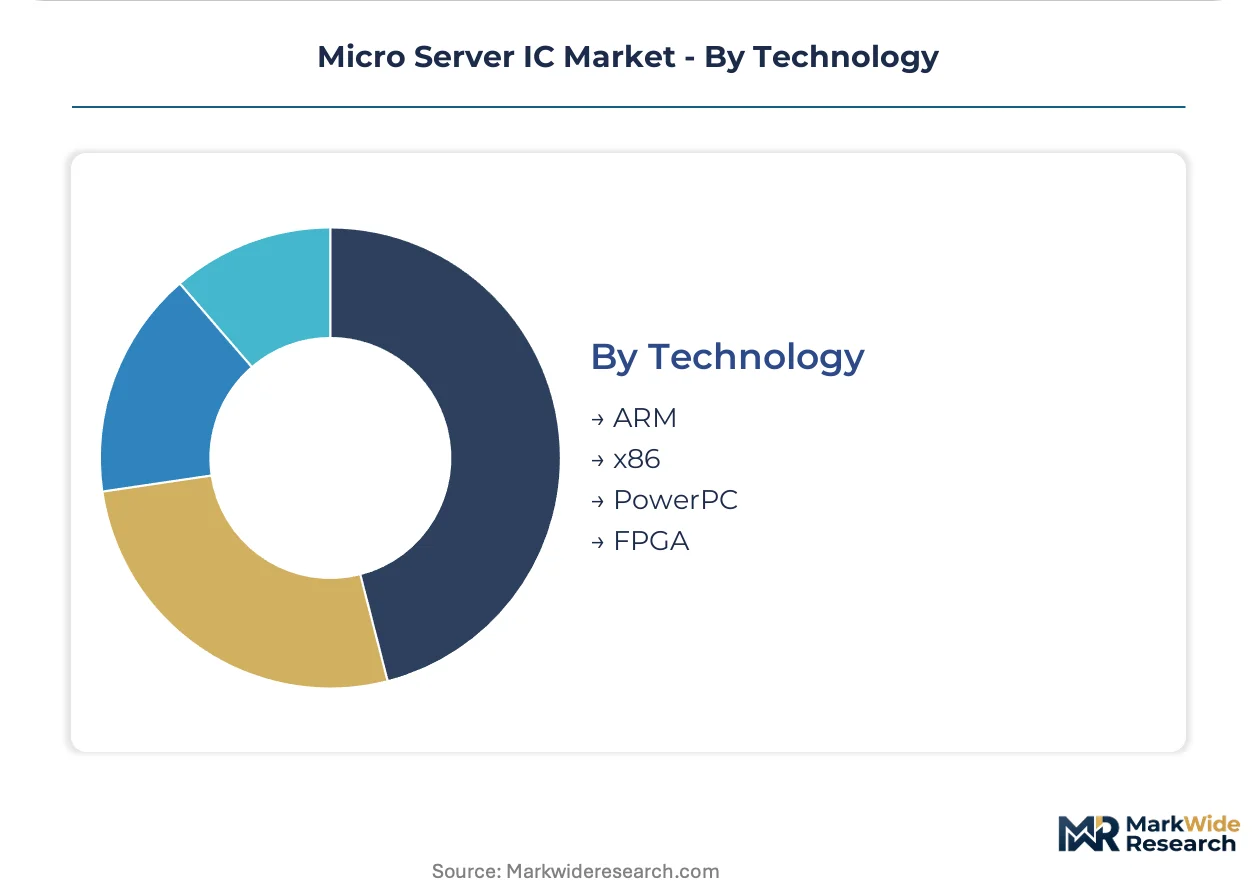
Technology:
Instruction set architecture selection determines software ecosystem compatibility and power efficiency profiles.
- ARM:RISC-based cores with customizable microarchitectures command the fastest expansion trajectory as hyperscale operators engineer custom silicon roadmaps for performance-per-watt optimization.
- x86:Intel Corporation leverages ecosystem dominance to sustain foundry relationships with enterprise server OEMs despite architectural rotation pressures.
- PowerPC:Embedded-focused ISA persists in network appliance and industrial control applications with legacy code bases.
- FPGA:Reconfigurable logic arrays accelerate specialized inference workloads with field-updatable bitstreams.
x86 retains entrenched volume; ARM climbs fastest on hyperscale qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in micro server integrated circuits tilt toward net import dependence across most major economies, with Taiwan and South Korea anchoring wafer fabrication exports while the United States, Germany, and China absorb the dominant import volumes for final system integration.
United States
Cloud computing demand concentrates in Northern Virginia and Oregon utility zones where Amazon Web Services and Microsoft Azure specify ARM-based clusters for corporate sustainability commitments. The FCC equipment authorization rules shape electromagnetic compliance testing for all US-deployed micro server hardware. Dallas-Fort Worth and Phoenix data center corridors are absorbing modular chiplet-based server deployments for edge computing nodes.
China
Domestic cloud operators including Alibaba Cloud and Tencent Cloud are qualifying indigenous ARM-based processor designs for performance-per-watt optimization in hyperscale facilities. The MIIT enforces GB standards for server energy efficiency and electromagnetic compatibility in data center deployments. Yangtze River Delta computing clusters around Shanghai and Hangzhou are prioritizing local silicon assembly under national dual carbon goals.
Germany
Industrial automation and automotive edge computing applications are absorbing thermally constrained multi-core packages for distributed processing nodes. The EU AI Act risk-classification mandates require validated AI training infrastructure, accelerating processor qualification cycles for European deployments. Frankfurt Rhine-Main data center hub operators are prioritizing vendors with pre-established notified body relationships to compress deployment timelines.
Japan
Telecommunications infrastructure buildouts for 5G standalone networks are driving demand for sub-15W TDP fanless enclosures in distributed baseband processing. METI promotes domestic semiconductor manufacturing resurgence through subsidies for advanced packaging investments. Tokyo-Osaka corridor data centers are specifying DDR5 and HBM3 memory modules amid supply-constrained transitions.
India
The PLI scheme for semiconductor manufacturing is attracting assembly and test investments for region-specific micro server SKUs serving domestic cloud operators. The CEA mandates energy efficiency standards for data center power usage effectiveness ratios. Mumbai-Pune and Bengaluru-Chennai industrial corridors are localizing server motherboard fabrication for hyperscale operator procurement.
Micro Server IC Market Vendor Landscape
Concentration sits with x86 ecosystem incumbents and ARM-based custom silicon architects who have secured direct wafer supply agreements with TSMC and Samsung Foundry. The vendor base stratifies across three tiers: hyperscale-captive designers with proprietary ISA extensions, merchant semiconductor suppliers serving enterprise OEMs through traditional channel structures, and fabless specialists focused on networking and storage acceleration silicon. Dominant competitive moves include multi-year foundry capacity reservations and custom chiplet program launches that bypass standard server OEM procurement.
Within the merchant semiconductor tier, Intel Corporation and NVIDIA Corporation exemplify divergent architectural strategies for data center compute. Intel leverages its x86 ecosystem dominance to sustain foundry relationships with enterprise server OEMs despite ARM rotation pressures. NVIDIA anchors AI inference workload positioning through its Grace CPU platforms and NVLink interconnect architectures. Marvell Technology occupies a specialist position in custom silicon programs for hyperscale clients seeking workload-optimized feature roadmaps.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Hewlett Packard Enterprise |
| Intel Corporation |
| Quanta Computer |
| Broadcom Inc. |
| Advanced Micro Devices |
| Marvell Technology |
| Applied Micro Circuits |
| Arm Holdings |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day wafer start lead times for advanced packaging substrates concentrate pricing power with Taiwan and South Korea foundry networks, while cloud operators with multi-year offtake agreements secure allocation priority over spot-market purchasers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale and certification-level differentiation. Premium positioning attaches to EPA ENERGY STAR-qualified idle-power thresholds and EU AI Act pre-certified security architectures. Cost compression in 1GbE networking segments intensifies due to mature technology substitution, while hyperscale direct procurement exhibits lowest price sensitivity.
Supply Chain Analysis
Strategic stockpiling of organic substrates and advanced packaging materials dominates inventory strategy as buyers buffer against Taiwan and South Korea concentration. Raw material dependencies center on silicon wafers, high-bandwidth memory stacks, and organic interposer substrates. Single-source vulnerability in EUV lithography capacity at TSMC and Samsung Foundry creates allocation risk. Distribution runs through direct foundry relationships and server OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity reservations and custom silicon design capabilities represent the scarcest strategic assets, with only three semiconductor vendors holding guaranteed 3nm node access for micro server volume production.
For Market Incumbents: Fortify foundry relationships through multi-year wafer supply agreements and captive packaging investments in Taiwan and South Korea. Prioritize certification investment for EPA ENERGY STAR and EU AI Act technical file repositories to compress qualification cycles against ARM-based entrants. For New Entrants and Emerging Players: Differentiate on chiplet-based modular configurations targeting India PLI scheme localization requirements. The most penetrable white space sits in sub-15W TDP fanless enclosures for 5G telecommunications infrastructure. Pursue direct partnerships with domestic cloud operators in Mumbai-Pune and Bengaluru-Chennai corridors. For Investors and Strategic Acquirers: Long-term, this sits as a custom silicon consolidation play because hyperscale vertical integration is displacing merchant semiconductor channels. Target acquisition profiles should emphasize fabless designers with pre-established ARM ISA licensing and notified body relationships. Watch NIST post-quantum cryptography standardization timelines as inflection signals for hardware security module redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Capacity Reservation | TSMC and Samsung Foundry allocation priority secures 3nm node access for hyperscale chiplet programs. |
| Custom ISA Extension Development | ARM Holdings licensing agreements enable workload-optimized feature roadmaps for AWS Graviton and Azure Cobalt architectures. |
| EU AI Act Pre-Certification Investment | Notified body relationships compress European deployment timelines for high-risk AI training infrastructure. |
| Advanced Packaging Substrate Stockpiling | Strategic inventory buffers Taiwan and South Korea supply concentration for organic interposer designs. |
| India PLI Scheme Localization | Assembly and test investments capture region-specific SKU demand from domestic cloud operators. |
Methodological Framework
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and foundry capacity announcements preceded structured interviews with semiconductor procurement executives, data center operations directors, and custom silicon program managers. Secondary validation drew from Taiwan Semiconductor Industry Association reports, EPA ENERGY STAR server specification documentation, and EU AI Act implementing guidance. Bottom-up unit demand modeling triangulated against top-down addressable market sizing.
Variance decomposition across processor, memory module, and networking chip segments informed analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include instruction set architecture, form factor thermal design power, and end-user procurement scale. CAGRs derived from segment-level volume trajectories weighted by ASP evolution patterns. Forecast inputs incorporated foundry node transition timelines and regulatory compliance cost burdens.
Forecasts assume regulatory continuity in EPA ENERGY STAR specifications and EU AI Act risk-classification regimes; material policy shifts would require re-modeling. Revision becomes warranted when EUV lithography capacity allocation or advanced packaging substrate supply crosses critical shortage thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Power Architecture Market