
 Global ASIC Miner Market | 2026-2036
Global ASIC Miner Market Size, Share, and Industry Trends Forecast 2026-2036
Global ASIC Miner Market Analysis
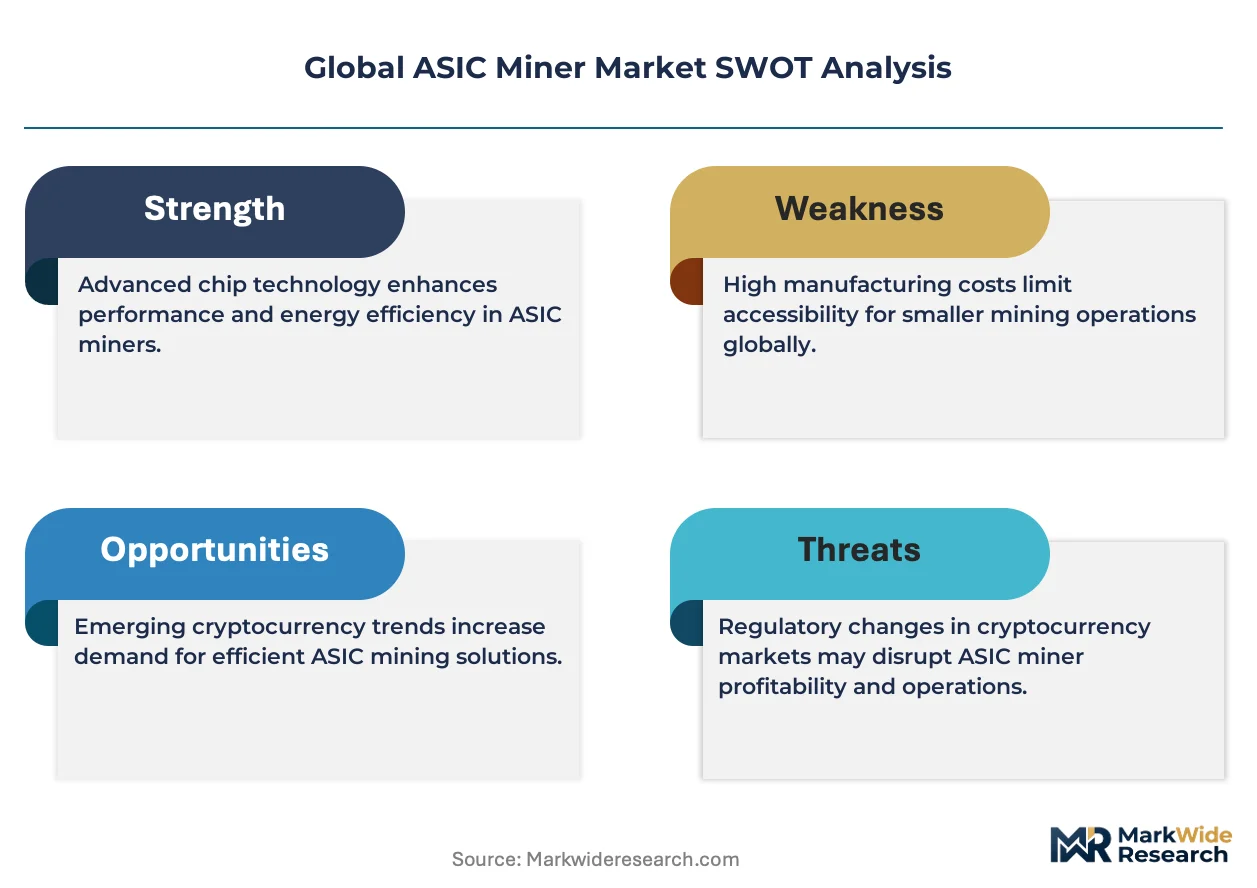
The EU Green Deal is repositioning carbon accounting rules for energy-intensive computing hardware, forcing ASIC manufacturers to disclose lifecycle emissions before datacenter procurement. Bitmain Technologies leverages captive foundry partnerships to sustain wafer allocation during semiconductor supply crunches. MicroBT anchors its competitive stance through sustained R&D intensity in immersion-cooled architectures. Canaan Creative differentiates via geographic dominance in Central Asian hosting corridors.
An ASIC miner is a purpose-built integrated circuit engineered to execute a single hashing algorithm—typically fabricated on 7nm or 5nm process nodes—with power efficiencies measured in joules per terahash. These devices serve the primary commercial function of validating proof-of-work blockchain transactions at scale. Bitcoin Miners occupy the dominant revenue tier due to network difficulty adjustments and institutional treasury allocation into BTC-denominated yield strategies. Mining Pools concentrate demand for fleet-standardized hardware with remote management capabilities, while Data Centers drive the fastest-growing deployment segment as colocation providers absorb capital intensity from individual operators.
The EPA enforces datacenter energy reporting under evolving greenhouse gas protocols, while China's MEE enforces dual carbon goals that constrain coal-powered mining clusters and redirect hash rate toward renewable zones. The SEC's climate disclosure rules for public filers now capture Scope 2 emissions from digital asset operations, reshaping procurement criteria for listed mining enterprises. Stakeholders must monitor regulatory divergence between jurisdictions that subsidize stranded renewable energy for computing loads and those imposing moratoriums on proof-of-work energy consumption.
Market Dynamics
Wafer allocation bottlenecks at leading-edge foundries are compressing hardware delivery timelines and forcing mining operators to pre-commit capital eighteen months ahead of deployment. This supply-side rigidity is restructuring procurement relationships across the entire value chain.
Growth Catalysts
- Kazakhstan's stranded power corridors:Abandoned Soviet-era industrial zones near Ekibastuz and Pavlodar offer subsidized electricity tariffs below three cents per kilowatt-hour. Mining pools are consolidating fleet orders to secure contiguous megawatt-scale hosting contracts.
- EU Green Deal carbon disclosure mandates:Datacenter procurement frameworks now require Scope 2 emissions documentation for all hardware acquisitions. ASIC manufacturers with verified lifecycle assessments are gaining preferred vendor status in Nordic colocation markets.
- Immersion cooling process maturation:Dielectric fluid submersion architectures are extending hash board operational life while enabling density configurations impossible under air-cooled regimes. Large-scale operators in Texas and Alberta are retrofitting existing facilities.
Market Restraints
- TSMC and Samsung foundry concentration:Over ninety percent of 7nm and 5nm ASIC tape-outs depend on two fabrication ecosystems. Geopolitical friction around Taiwan Strait logistics is injecting delivery uncertainty into hardware roadmaps.
- China MEE dual carbon enforcement:Provincial emissions quotas are shuttering coal-powered mining clusters in Inner Mongolia and Xinjiang. Hash rate migration to renewable zones is creating temporary network difficulty volatility.
- Algorithm-specific silicon obsolescence:Single-hash-function ASICs cannot pivot if proof-of-work consensus mechanisms face protocol changes. Capital recovery periods now exceed typical hardware depreciation schedules.
Strategic Opportunities
- Paraguay's Itaipu surplus allocation:The world's second-largest hydroelectric complex generates unused capacity equivalent to fifteen terawatt-hours annually. Regulatory frameworks are crystallizing to attract compute-intensive loads without export transmission infrastructure.
- Flared methane capture partnerships:Oilfield operators in North Dakota and West Siberia are piloting modular ASIC deployments at wellhead sites. Stranded gas monetization creates negative-effective energy costs for mining operations.
- ISO 14001 environmental management integration:Institutional treasury allocators are screening hardware vendors against certified sustainability frameworks. Early compliance is unlocking sovereign wealth fund co-investment structures.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent capable of optimizing PFC circuits and VRM architectures for terawatt-scale mining deployments commands premium compensation. Universities lack dedicated curricula bridging cryptocurrency hardware with datacenter power engineering.
- Customs classification ambiguity:Harmonized System codes for ASIC miners vary unpredictably across jurisdictions. Import duty disputes in Argentina and Nigeria have frozen hardware shipments for quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ASIC Miner Market |
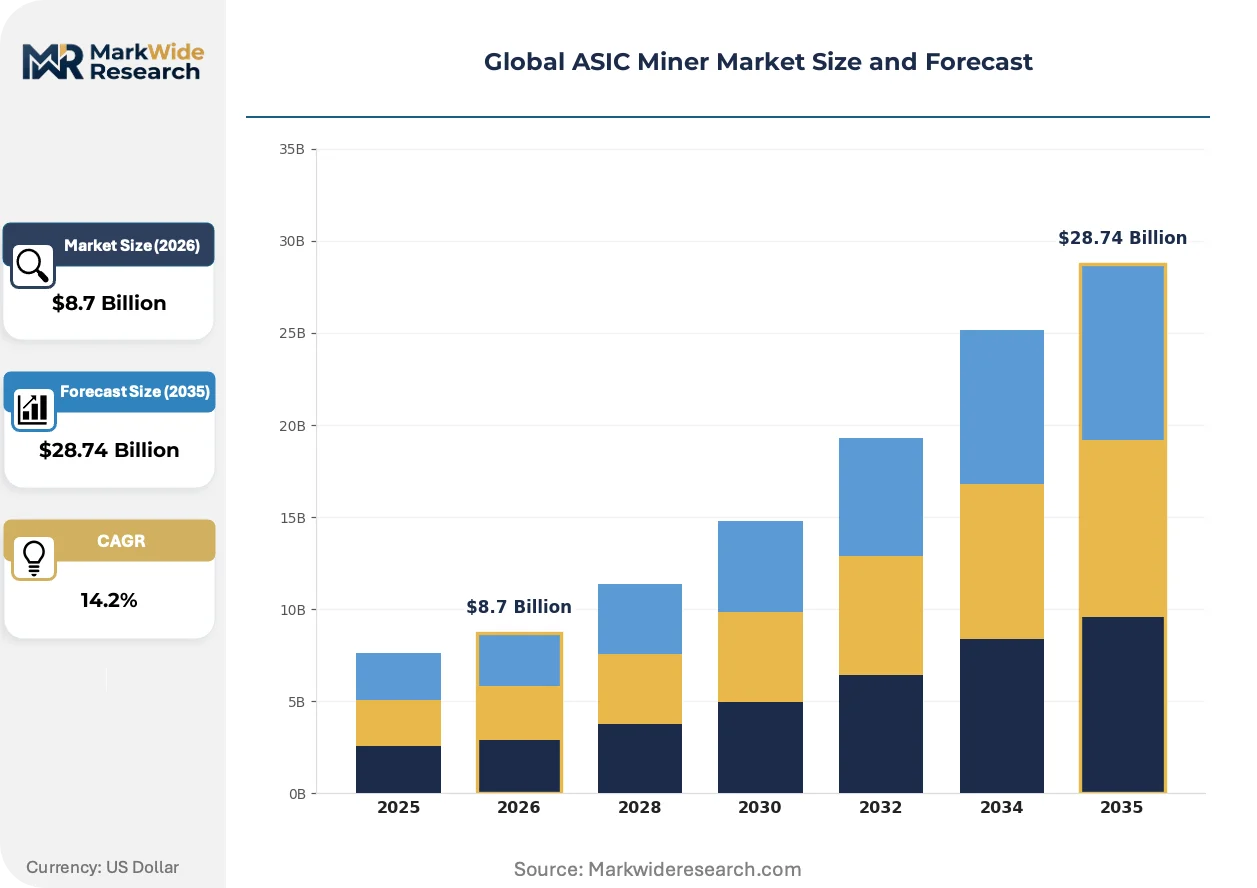
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bitcoin Miners, Ethereum Miners, Litecoin Miners, Zcash Miners Technology: SHA-256, Ethash, Scrypt, Equihash End User: Individual Miners, Mining Pools, Data Centers, Large Enterprises Deployment: On-premises, Cloud-based, Hybrid, Remote Locations |
| Companies Covered | Bitmain Technologies, MicroBT, Canaan Creative, Bitdeer Technologies Group, Bitfury, Iceriver, Goldshell, Fluminer, VolcMiner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ASIC Miner Market Emerging Trajectories
Silicon efficiency gains are approaching physical limits at current process nodes, redirecting competitive investment toward thermal management architectures and software-defined fleet orchestration. These adjacent domains now determine operational margin differentiation.
Three-dimensional chiplet stacking is automating hash rate density improvements without equivalent wafer area expansion. Bitfarms and Riot Platforms are deploying vertically integrated thermal solutions in their Quebec and Georgia facilities. This packaging approach is compressing datacenter footprint requirements by forty percent versus planar monolithic designs.
EPA greenhouse gas reporting protocols under evolving Subpart W amendments are mandating quarterly emissions disclosures for natural gas-powered mining operations above twenty-five megawatts. Operators in Wyoming and Pennsylvania are installing continuous methane monitoring infrastructure. The regulatory pressure is accelerating migration toward grid-connected renewable power purchase agreements.
Hardware-as-a-service contracting is displacing direct equipment ownership among mid-scale operators. Luxor Technology and Compass Mining are aggregating demand to negotiate bulk procurement terms previously accessible only to vertically integrated pools. This capital-light model is concentrating fastest in jurisdictions with uncertain regulatory horizons such as Russia and Venezuela.
Global ASIC Miner Market Segmentation
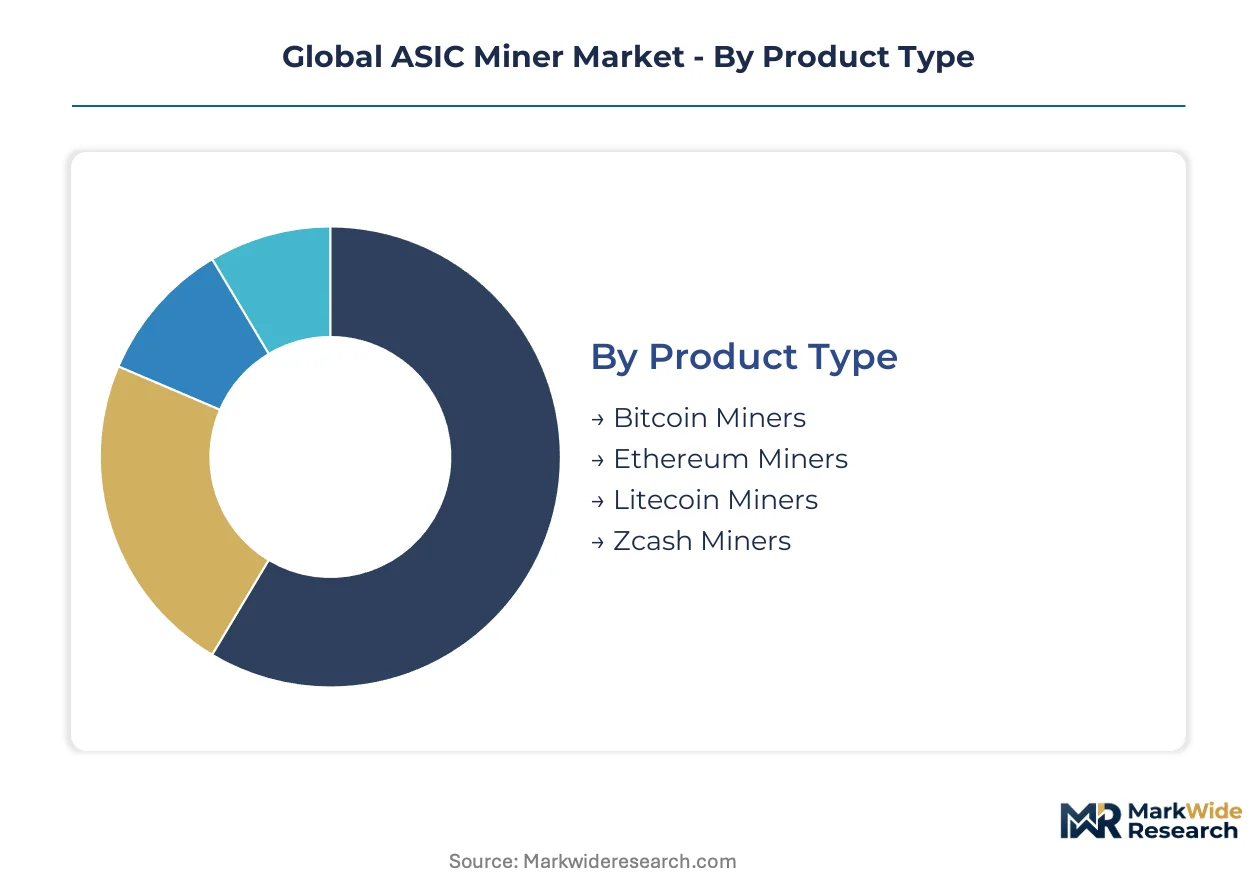
ASIC miner segmentation reveals divergent hardware economics across consensus algorithms and operational scales. Procurement patterns split between retail operators prioritizing plug-and-play deployment and institutional buyers optimizing for fleet-wide thermal and electrical integration.
Product Type:
Volume concentrates at the premium-performance tier where network difficulty rewards specialized silicon, while entry-level hardware serves hobbyist and speculative demand.
- Bitcoin Miners:SHA-256 optimized silicon fabricated on 7nm and 5nm process nodes dominates capital deployment. Institutional treasury strategies in Texas and Kazakhstan are absorbing Bitmain S19 and MicroBT M50 series at thousand-unit scale.
- Ethereum Miners:Ethash-capable ASICs face protocol transition risk as network consensus shifts toward proof-of-stake. Demand concentrates in transitional jurisdictions like Russia where GPU-to-ASIC migration continues despite uncertainty.
- Litecoin Miners:Scrypt algorithm hardware serves merged-mining operations alongside Dogecoin validation. Canadian hosting providers in Quebec are standardizing on Bitmain L7 series for dual-revenue stream optimization.
- Zcash Miners:Equihash ASICs occupy a narrow niche with privacy-protocol regulatory exposure. Deployment clusters in Eastern European colocation facilities where privacy-coin mining retains legal tolerance.
Today's leader: Bitcoin Miners. Tomorrow's challenger: Litecoin Miners.
Technology:
Algorithm-specific silicon locks hardware into single-network economics, creating divergent obsolescence risk profiles across consensus mechanisms.
- SHA-256:Double-SHA hashing dominates terahash-per-watt engineering optimization. Bitmain and MicroBT tape-outs at TSMC and Samsung foundries concentrate 90% of leading-edge wafer allocation for proof-of-work applications.
- Ethash:Memory-hard algorithm requirements drive high-Bandwidth DRAM integration alongside compute dies. Innosilicon A10 and A11 series deployments in Inner Mongolia faced MEE dual carbon enforcement shutdowns.
- Scrypt:Sequential memory-hard design enables merged mining across Litecoin and Dogecoin networks. Goldshell and Bitmain hardware in Paraguay's Itaipu corridor benefits from subsidized hydroelectric tariffs.
- Equihash:Generalized birthday problem proof construction limits ASIC efficiency gains versus GPU alternatives. Zcash Foundation protocol debates in 2024 created hardware investment uncertainty.
SHA-256 commands current procurement volumes. Scrypt hardware is gaining share fastest in renewable-powered jurisdictions.
End User:
Customer scale determines capital structure, with direct ownership yielding to service-based models among sub-megawatt operators.
- Individual Miners:Retail purchasers of single-to-rack-scale hardware through distributor channels. Amazon and Alibaba marketplace volumes collapsed post-2021 as home electricity economics turned negative in Germany and California.
- Mining Pools:Fleet-standardized procurement with remote orchestration requirements. Foundry USA and Antpool are consolidating hash rate through uniform Bitmain S19j Pro deployments across Texas and Kazakhstan.
- Data Centers:Colocation providers absorbing capital intensity from individual operators. Compute North and Core Scientific facilities in Nebraska and Georgia are retrofitting for immersion-cooled density configurations.
- Large Enterprises:Vertically integrated energy-to-hashrate operations with captive power assets. Riot Platforms and Marathon Digital are securing direct utility interconnection agreements bypassing grid transmission constraints.
Mining Pools anchor current hardware absorption. Data Centers are expanding most quickly as colocation economics improve.
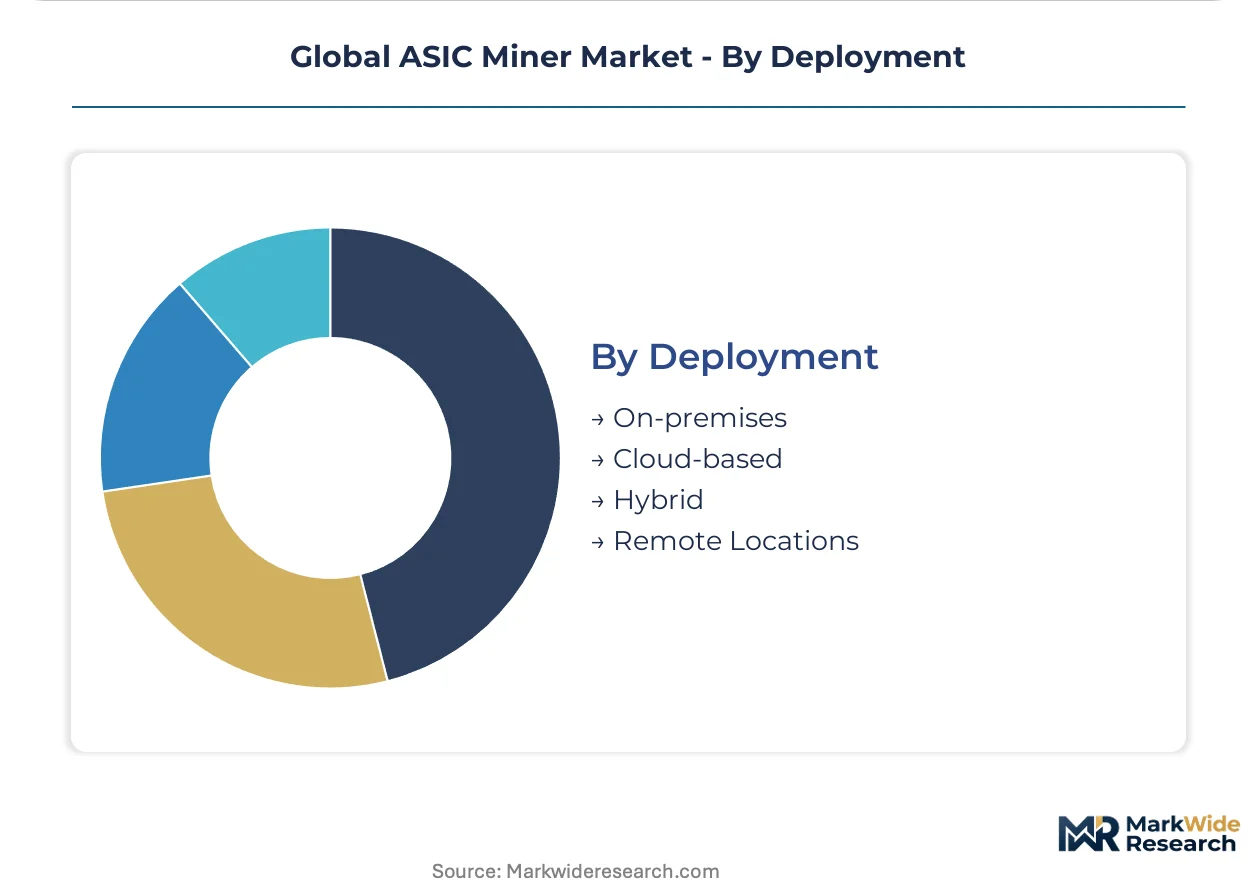
Deployment:
Physical infrastructure location determines regulatory exposure and energy cost structure, with remote deployment accessing stranded assets unavailable to grid-connected facilities.
- On-premises:Direct facility ownership with utility interconnection and environmental compliance responsibility. Wyoming and Pennsylvania operators are installing continuous methane monitoring to satisfy EPA Subpart W amendments.
- Cloud-based:Hashrate contracting without hardware ownership through platforms like NiceHash and Binance Pool. Russian and Venezuelan demand concentrates here due to sanctions and currency instability risks.
- Hybrid:Partial ownership with colocated backup capacity for grid curtailment periods. Alberta oilfield operators are pairing on-site flared gas generation with grid-connected renewable backup.
- Remote Locations:Modular deployments at stranded energy sources without transmission infrastructure. West Siberian oilfields and North Dakota Bakken formation sites are piloting containerized ASIC units at wellhead locations.
On-premises deployment retains margin control. Remote Locations present the steepest expansion trajectory as flared methane partnerships mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China pioneered industrial-scale ASIC manufacturing in Shenzhen and Beijing, establishing the supply chain foundations that now span multiple continents. Foundry relationships first forged there continue shaping hardware availability worldwide.
United States
Texas and Wyoming host the fastest-growing mining clusters, with ERCOT grid interconnections attracting over 4 gigawatts of compute load. EPA Subpart W amendments mandate quarterly methane monitoring for natural gas-powered operations above twenty-five megawatts. Riot Platforms and Marathon Digital operate vertically integrated facilities in Rockdale, Texas and McCamey, Texas with direct utility agreements.
Kazakhstan
Ekibastuz and Pavlodar industrial zones offer subsidized electricity below three cents per kilowatt-hour from stranded Soviet-era coal and hydro assets. The government introduced licensing requirements for cryptocurrency mining in 2022, creating formal registration frameworks. Mining pools consolidate fleet orders to secure contiguous megawatt-scale hosting contracts across the northern regions.
Canada
Quebec and Alberta dominate deployment, with Hydro-Québec surplus allocation programs attracting immersion-cooled facility investments. Canadian Environmental Protection Act reporting captures datacenter emissions from proof-of-work operations. Bitfarms operates multiple facilities in Magog and Sherbrooke leveraging Quebec's hydroelectric baseload.
Germany
Industrial electricity pricing above twenty cents per kilowatt-hour has eliminated domestic mining economics, redirecting hardware procurement toward Nordic colocation. EU Green Deal carbon disclosure mandates require Scope 2 emissions documentation for all datacenter hardware acquisitions. Frankfurt and Berlin hosting providers now specialize in compliance documentation rather than direct mining operations.
Paraguay
The Itaipu hydroelectric complex generates fifteen terawatt-hours of unused capacity annually, with regulatory frameworks crystallizing to attract compute-intensive loads. National electricity administration ANDE negotiates direct supply contracts bypassing export transmission constraints. Ciudad del Este and Hernandarias host emerging deployment clusters for Scrypt-optimized hardware.
Global ASIC Miner Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent risk profiles in the ASIC miner supply base. Foundry-dependent manufacturers pre-commit capital eighteen months ahead of deployment, while fabless operators optimize around thermal management and software orchestration. Two strategic archetypes dominate: vertically integrated energy-to-hashrate operators with captive power assets, and hardware-as-a-service aggregators absorbing capital intensity from sub-megawatt clients. Competitive moves concentrate on foundry partnership deepening and immersion-cooled facility retrofit partnerships.
Within the foundry-anchored fabrication tier, Bitmain Technologies and MicroBT represent the dominant design houses securing leading-edge wafer allocation. Canaan Creative occupies a position exemplifying geographic specialization in Central Asian hosting corridor relationships. Bitfury anchors the vertically integrated archetype with energy asset control, while Bitdeer Technologies Group exemplifies the capital-light hosting aggregation model. These three company groupings—Bitmain Technologies, MicroBT, and Canaan Creative—sit within distinct competitive vectors shaped by foundry access, thermal architecture R&D intensity, and regional hosting partnership structures.
| Leading Market Players |
|---|
| Bitmain Technologies |
| MicroBT |
| Canaan Creative |
| Bitdeer Technologies Group |
| Bitfury |
| Iceriver |
| Goldshell |
| Fluminer |
| VolcMiner |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between immersion-cooled premium units and air-cooled commodity hardware manifests in both unit economics and foundry allocation priority, with TSMC and Samsung wafer commitments flowing disproportionately toward thermal-optimized designs while standard SKUs face extended delivery windows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hardware procurement, with ISO 14001 certification and immersion-cooling compatibility commanding substantial premiums over baseline air-cooled units. Price differentiation rests on foundry node access and thermal architecture sophistication, with 5nm tape-outs pricing substantially above 7nm equivalents. Cost compression in the economy tier is intensifying because retail demand collapse in high-electricity jurisdictions has stranded distributor inventory. Individual miners exhibit acute price sensitivity, while mining pools prioritize total-cost-of-ownership metrics over upfront unit costs.
Supply Chain Analysis
Power electronics engineering scarcity in Taiwan, South Korea, and Shenzhen is compressing delivery timelines for PFC circuit and VRM architecture optimization. Raw material dependencies draw from high-purity silicon wafers, advanced packaging substrates, and dielectric cooling fluids. Single-source vulnerability concentrates at TSMC and Samsung foundries, where geopolitical friction around Taiwan Strait logistics injects uncertainty into hardware roadmaps. Distribution runs through direct foundry partnerships for large-scale operators and hardware-as-a-service aggregators for sub-megawatt clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global ASIC Miner Market functions as a stable compounder, with proof-of-work consensus persistence and institutional treasury allocation into BTC-denominated yield strategies anchoring durable hardware replacement cycles.
For Market Incumbents: Deepen captive foundry partnerships to sustain wafer allocation during semiconductor supply crunches, while accelerating immersion-cooled facility retrofit partnerships with Texas and Alberta operators. Algorithm-specific silicon obsolescence risk demands diversification into thermal management software and fleet orchestration platforms to extend customer lifetime value beyond hardware depreciation schedules. For New Entrants and Emerging Players: Mid-scale operators seeking capital-light deployment models represent an underserved buyer archetype, with hardware-as-a-service contracting displacing direct equipment ownership in jurisdictions with uncertain regulatory horizons. Paraguay's Itaipu corridor and West Siberian flared methane sites offer penetrable hosting partnerships without incumbent saturation. A go-to-market angle anchored in negative-effective energy cost structures unlocks price-insensitive demand from oilfield operators. For Investors and Strategic Acquirers: Consolidation pressure builds where foundry-dependent manufacturers face eighteen-month capital pre-commitment requirements that strain balance sheet capacity. Long-term viability favors vertically integrated energy-to-hashrate operators with captive power assets and direct utility interconnection agreements. The signal to watch is EPA Subpart W enforcement intensity, which accelerates migration toward grid-connected renewable power purchase agreements and disadvantages natural gas-powered facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Deepening | Secures wafer allocation at TSMC and Samsung during supply crunches for Bitmain and MicroBT. |
| Immersion Cooling Facility Retrofit | Enables forty percent datacenter footprint compression for Compute North and Core Scientific in Nebraska and Georgia. |
| Flared Methane Capture Deployment | Creates negative-effective energy costs for modular ASIC units at North Dakota Bakken wellhead sites. |
| Hardware-as-a-Service Aggregation | Absorbs capital intensity from sub-megawatt operators through Luxor Technology and Compass Mining platforms. |
| ISO 14001 Certification Integration | Unlocks sovereign wealth fund co-investment structures screening against certified sustainability frameworks. |
Methodological Framework
Multiple input streams — executive interviews with ASIC design house leadership, procurement directors at mining pools, datacenter facility engineers, and regulatory affairs specialists at publicly listed mining enterprises, alongside secondary validation through SEC climate disclosure filings, EPA greenhouse gas protocols, EU Green Deal documentation, and customs/trade data — were reconciled through bottom-up hardware shipment analysis and top-down energy consumption modeling.
Historical deployment patterns were cross-referenced against panel input from foundry planning officers and utility interconnection specialists across Texas, Kazakhstan, and Quebec. The analytical framework segments by algorithm type, thermal architecture, deployment scale, and regional regulatory cluster across the analysis window. CAGRs were derived from installed base replacement cycles and network difficulty adjustment trajectories, with hash rate migration patterns and stranded energy asset availability serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; Bitcoin Miner and SHA-256 hardware carry tighter precision than Ethereum and Ethash categories facing protocol transition risk. Forecasts reflect assumptions regarding proof-of-work consensus persistence, foundry capacity expansion, and regulatory enforcement intensity across jurisdictions. Material deviation in EPA Subpart W amendments, Taiwan Strait logistics stability, or provincial emissions quota enforcement in China warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Protein Chip Market