
 OLED Laptops Market | 2026-2036
OLED Laptops Market Size, Share, and Industry Trends Forecast 2026-2036
OLED Laptops Market Insights
South Korea's display infrastructure expansion is reshaping competitive dynamics in OLED laptop manufacturing. Samsung leverages its captive OLED panel supply to sustain pricing flexibility across premium tiers. ASUS differentiates through specialized gaming SKUs with high-refresh-rate OLED configurations. LG anchors the supply chain through its WOLED expertise, extending panel availability to multiple OEM partners.
An OLED laptop integrates organic light-emitting diode panels that achieve per-pixel illumination without backlighting, enabling contrast ratios exceeding 1,000,000:1 and response times below 1 millisecond. The technology serves professional color grading, competitive gaming, and mobile workstation applications where display fidelity directly impacts output quality. Gaming laptops command the strongest margin pools among product types, while ultrabooks represent the volume growth corridor as business travelers prioritize weight reduction. The 15-inch and 16-inch size bands concentrate OEM investment, with 14-inch formats gaining traction in creator-focused configurations.
REACH chemical restrictions in Europe govern organic compound disposal and manufacturing emissions, while EPA hazardous substance rules in the United States affect end-of-life processing obligations for imported devices. South Korea's Ministry of Trade, Industry and Energy (METI-equivalent industrial policy) channels domestic subsidies toward Gen 8.5+ OLED capacity, directly influencing which OEMs secure preferential panel allocation. Stakeholders must track how display substrate size transitions alter panel cost curves and which brands secure early supply commitments for next-generation IT OLED lines.
Market Dynamics
Gen 8.6 substrate manufacturing is redrawing cost curves and panel availability, concentrating supply leverage among Korean display makers while OEMs race to lock multi-year allocation agreements.
Growth Catalysts
- Content creator demand surge:Media and entertainment professionals now specify OLED color accuracy as a non-negotiable workstation requirement, pulling panel allocation toward creator-tier SKUs.
- REACH chemical framework:Europe's hazardous substance rules are accelerating closed-loop manufacturing investments, rewarding early-compliant Korean suppliers with preferential EU market access.
- Tandem OLED architecture:Dual-emission-layer stacks are extending panel lifetime and peak brightness, opening high-ambient-light applications previously closed to OLED laptops.
Market Restraints
- Input cost volatility:Iridium and platinum group metal prices in emitter materials create 15-20% panel cost swings that OEMs cannot fully pass through.
- Geographic supply concentration:Seoul-Incheon corridor and Shenzhen cluster control over 90% of IT OLED capacity, exposing buyers to single-point disruption risk.
- Technical burn-in limitation:Static UI elements in enterprise software accelerate pixel degradation, constraining warranty terms and corporate fleet adoption.
Strategic Opportunities
- India market underpenetration:Domestic laptop assembly under PLI scheme creates localized OLED SKUs at import-parity pricing for price-sensitive creator segments.
- High-refresh gaming convergence:240Hz+ OLED panels are capturing esports tournament specifications, displacing LCD in prize-pool hardware mandates.
- EPA hazardous substance rules:US end-of-life processing obligations favor modular designs with separable OLED assemblies, creating service-revenue streams for certified recyclers.
Industry Challenges
- Calibration skill scarcity:Factory-level color tuning for per-unit uniformity requires technicians trained on spectroradiometer protocols that take 18-24 months to develop.
- Gen 8.6 capex intensity:Single IT OLED line demands over $3 billion investment, freezing out mid-tier panel makers from next-generation supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OLED Laptops Market |
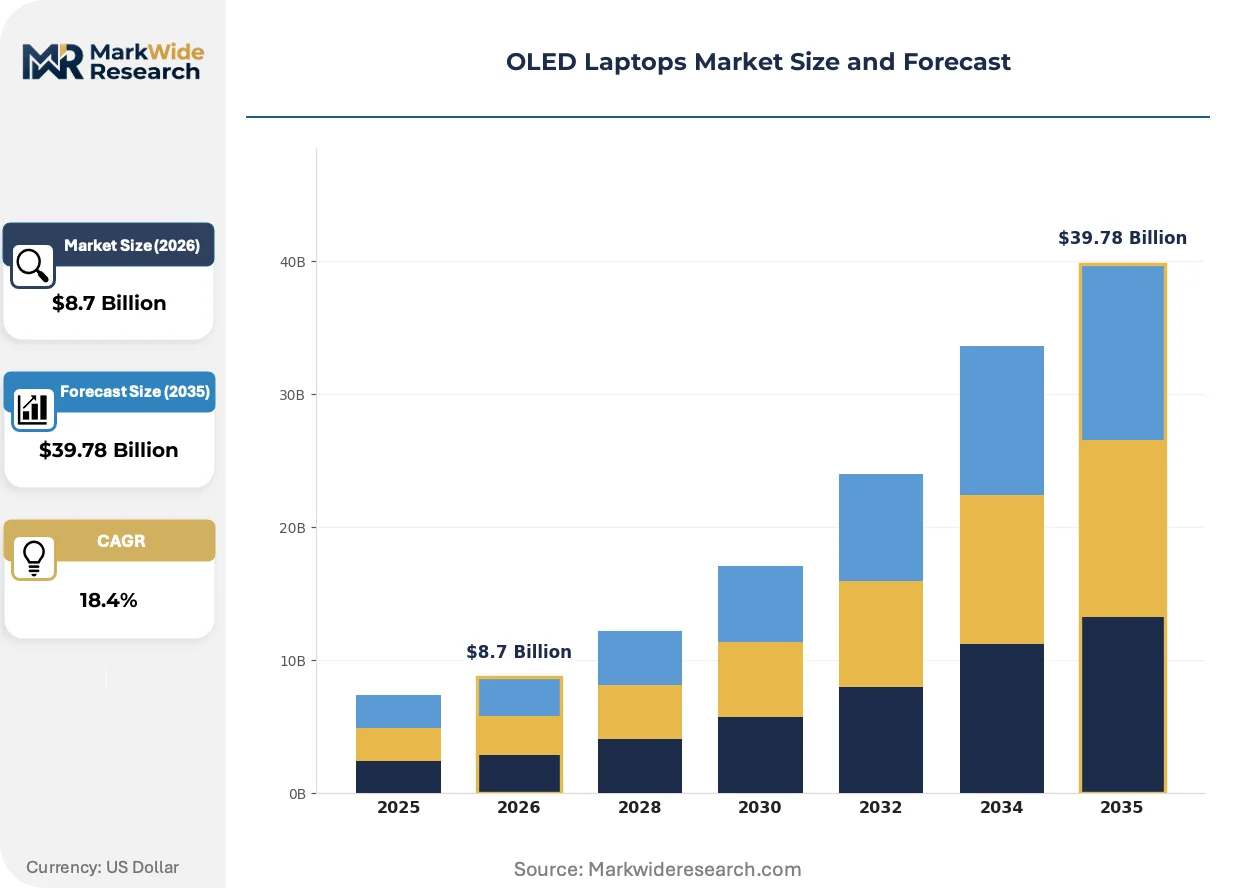
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-in-1, Ultrabook, Gaming Laptop, Business Laptop End User: Students, Professionals, Gamers, Creators Size: 13 inch, 15 inch, 17 inch, 14 inch Technology: Passive Matrix, Active Matrix, OLED, Flexible OLED |
| Companies Covered | Dell, MSI, ASUS, LG, HP, Samsung, Razer, Acer, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OLED Laptops Market Trends and Innovations
Display substrate scaling and regulatory chemistry compliance are converging to redefine how OLED laptop panels are manufactured, sourced, and specified across professional and consumer tiers.
Phosphorescent emitter chemistry is migrating from small-molecule fluorescent systems to heavy-metal phosphorescent dopants that harvest both singlet and triplet excitons for near-unity internal quantum efficiency. Professional color-grading workstations in Los Angeles and London post-production houses are specifying these panels for HDR mastering workflows. This transition is compressing power consumption budgets while maintaining brightness targets previously unattainable without thermal throttling.
REACH Annex XVII restrictions on organic solvent emissions are mandating dry-process vapor deposition equipment upgrades across Korean and Chinese panel fabs. The industrial consequence is a 12-18 month equipment qualification timeline that favors incumbent suppliers with existing capex reserves. Gaming laptop configurations with extended warranty terms are most affected, as manufacturers absorb compliance costs into premium tier pricing rather than mid-market SKUs.
Enterprise procurement departments are consolidating laptop refresh cycles from 48-month to 36-month intervals, treating display quality as a retention tool for creative talent rather than a cost center. Direct OEM relationships are displacing distributor-mediated purchasing for fleets above 5,000 units. This pattern is most visible in US and UK media agencies where creative director input overrides traditional IT procurement specifications.
OLED Laptops Market Segmentation
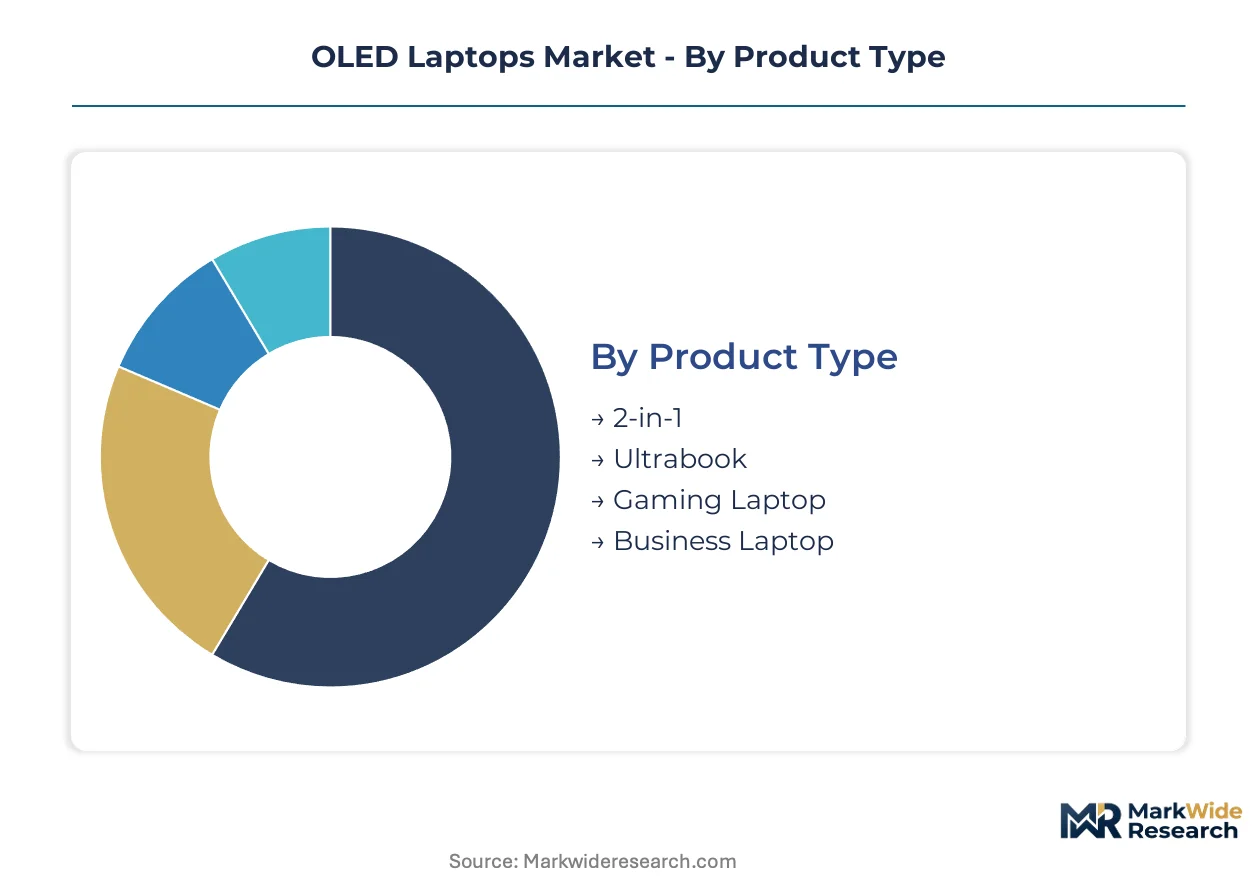
OLED laptop segmentation reveals how panel technology, form factor, and user workflow intersect to determine pricing architecture and supply allocation. Manufacturers configure substrate cuts and emitter chemistries differently across these dimensions, creating distinct margin profiles that reshape competitive positioning.
Product Type:
Use-case spectrum spans mobile productivity, immersive entertainment, and professional workstation applications, each demanding different thermal budgets and display specifications.
- Gaming Laptop:High-refresh-rate panels with sub-1ms response times dominate tournament-grade configurations. Seoul-based panel allocation prioritizes this tier for esports hardware mandates and premium pricing.
- Ultrabook:Thickness constraints below 15mm drive power-efficient phosphorescent emitter adoption. Business travelers in London and New York post-production corridors specify these for mobile color-grading workflows.
- 2-in-1:Convertible hinge mechanisms require flexible substrate handling during assembly. Korean fabs limit volume allocation due to yield complexity.
- Business Laptop:Enterprise procurement cycles favor 36-month refresh intervals with burn-in warranty limitations constraining fleet deployment scale.
The dominant share belongs to Gaming Laptop configurations, while Ultrabook is closing the gap fastest.
End User:
Customer archetypes differ sharply in specification sensitivity, with procurement authority residing in creative directors rather than IT departments for two segments.
- Creators:Media professionals specify HDR mastering panels with factory calibration certificates. Los Angeles post-production houses and London grading suites drive demand for phosphorescent emitter technology with near-unity quantum efficiency.
- Gamers:Competitive players prioritize 240Hz+ refresh rates and response time consistency. Shenzhen-based OEM assembly lines configure dedicated SKUs for APAC tournament circuits.
- Professionals:Corporate creative departments override standard IT procurement with display quality specifications. Direct OEM relationships displace distributor channels above 5,000-unit fleet thresholds.
- Students:Price sensitivity constrains penetration to education discount programs with reduced brightness specifications.
Creator segment commands premium tier concentration, while Gamer segment shows steepest expansion trajectory.
Size:
Substrate utilization efficiency and portability trade-offs determine which diagonal lengths attract manufacturing investment.
- 15 inch:Optimal substrate cut efficiency from Gen 8.6 lines concentrates OEM investment. Korean panel makers prioritize allocation to this format for volume scale.
- 16 inch:Emerging creator-focused aspect ratios near 16:10 displace legacy 16:9 configurations. ASUS and Dell secure early supply commitments for workstation-tier SKUs.
- 14 inch:Creator mobility requirements drive specification convergence with larger formats. Panel makers limit distinct SKU allocation due to substrate fragmentation.
- 13 inch:Ultrabook portability ceiling constrains thermal headroom for peak brightness targets. Reduced emitter drive currents extend operational lifetime.
- 17 inch:Desktop replacement configurations absorb yield fallout from larger substrate cuts. Limited volume due to mobility penalty in creator segments.
15 inch maintains installed base leadership, while 16 inch gains share fastest in professional tiers.
Technology:
Emitter architecture and matrix addressing schemes determine power efficiency, manufacturing cost, and application suitability across ambient light conditions.
- Active Matrix:Thin-film transistor backplanes enable per-pixel addressing for HDR content mastering. Korean and Chinese fabs concentrate capacity expansion on this architecture for IT applications.
- OLED:Standard RGB stripe configurations serve mainstream professional and gaming segments. Samsung Display and LG anchor supply through Seoul-Incheon corridor capacity.
- Flexible OLED:Polyimide substrate handling enables curved and foldable form factors. Yield complexity limits deployment to concept-tier products.
- Passive Matrix:Simpler drive electronics suit low-resolution status displays and secondary panels. Obsolete for primary laptop applications.
Active Matrix dominates production volume, while Flexible OLED remains constrained by manufacturing yield.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul-Incheon corridor and Shenzhen cluster control over 90% of IT OLED panel capacity, creating asymmetric supply leverage that shapes procurement patterns across consumer and professional tiers. Korean display makers anchor substrate manufacturing while Chinese assembly lines configure finished systems. This geographic concentration exposes downstream OEMs to single-point disruption risk.
South Korea
Content creator demand from Seoul-based post-production houses drives premium panel allocation toward HDR mastering configurations. METI-equivalent industrial policy channels domestic subsidies toward Gen 8.5+ OLED capacity expansion. Samsung Display's Gen 8.6 IT OLED line in Asan directly influences which OEMs secure preferential supply commitments.
China
Shenzhen-based OEM assembly lines configure dedicated gaming SKUs for APAC tournament circuits at volume scale. MIIT standards govern display energy efficiency certifications for domestic market entry. BOE and Visionox fabs in Chengdu and Hefei are qualifying phosphorescent emitter processes for professional-tier exports.
United States
Los Angeles post-production corridors specify factory-calibrated OLED panels for HDR color grading workflows. EPA hazardous substance rules affect end-of-life processing obligations for imported devices. Austin and Seattle tech corridors host enterprise procurement teams consolidating direct OEM relationships above 5,000-unit fleet thresholds.
Japan
Tokyo-Osaka creative agencies override standard IT procurement with display quality specifications for talent retention. JIS standards govern electromagnetic compatibility for professional workstation imports. Panasonic and Sharp maintain development partnerships with Korean panel makers for specialized mobile workstation configurations.
Germany
Berlin and Hamburg media agencies treat display quality as a retention tool for creative talent rather than a cost center. REACH chemical restrictions govern organic compound disposal and manufacturing emissions for EU market access. Bavaria-based automotive design studios specify OLED mobile workstations for real-time rendering applications.
OLED Laptops Market Competitive Landscape
Captive panel suppliers and assembly-integrated OEMs split the market into distinct competitive spheres. Korean display makers leverage upstream control over emitter chemistry and substrate manufacturing to sustain pricing flexibility across premium tiers. Three archetypes dominate: vertically integrated electronics conglomerates with captive OLED supply, specialized gaming hardware fabricators with high-refresh-rate configurations, and business-focused PC vendors with enterprise procurement relationships. Capacity expansion and strategic panel allocation agreements constitute the dominant competitive moves as Gen 8.6 substrate manufacturing redistributes supply leverage.
Among vertically integrated electronics conglomerates, Samsung and LG exemplify the captive-supply archetype through Seoul-based panel manufacturing and downstream system assembly. Dell and HP occupy positions within the enterprise-procurement tier, leveraging direct fleet relationships to secure preferential allocation for professional workstation SKUs. ASUS and MSI represent the gaming-specialist vector, differentiating through high-refresh-rate OLED configurations and esports tournament hardware mandates.
| Leading Market Players |
|---|
| Dell |
| MSI |
| ASUS |
| LG |
| HP |
| Samsung |
| Razer |
| Acer |
| Lenovo |
| Others |
Pricing and Supply Chain Analysis
Incheon-Seoul freight corridors carry iridium-doped emitter materials from Korean chemical processors to Asan panel fabs, with logistics costs feeding directly into premium-tier pricing while REACH compliance investments widen the gap between EU-certified and standard SKUs.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across OLED laptop configurations, separating factory-calibrated HDR mastering panels with phosphorescent emitter certification from standard RGB stripe alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects volume scale and calibration certificate inclusion. Cost compression in mid-market ultrabooks is intensifying because iridium price volatility in emitter materials cannot be fully passed through to enterprise procurement departments. Student segments exhibit highest price sensitivity, while Los Angeles post-production houses demonstrate lowest sensitivity due to talent retention imperatives.
Supply Chain Analysis
Iridium and platinum group metals from South African and Russian mining operations feed phosphorescent emitter synthesis, with organic compound precursors drawing from German and Japanese chemical specialists. Panel manufacturing concentrates in South Korea, China, and Taiwan, with substrate cutting and module assembly tethered to Seoul-Incheon and Shenzhen clusters. Single-source vulnerability in Gen 8.6 substrate equipment creates qualification bottlenecks that freeze out mid-tier panel makers. Distribution runs through direct OEM relationships for enterprise fleets above 5,000 units, with distributor channels serving education and small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED laptop procurement is shifting toward platform-centric ecosystem specifications where HDR mastering workflows, color calibration software, and hardware-optimized rendering engines interoperate as unified creative infrastructure rather than discrete component purchases.
For Market Incumbents: Entrench captive panel allocation through multi-year Gen 8.6 supply commitments before Chinese fabs complete phosphorescent emitter qualification. Secure preferential iridium supply contracts to buffer against substitute LCD mini-LED technology price aggression in gaming tiers. METI-equivalent subsidy channels in South Korea offer leverage for capacity expansion in Asan.
For New Entrants and Emerging Players: Pursue India PLI scheme assembly partnerships for localized creator-tier SKUs at import-parity pricing, where domestic laptop production remains underpenetrated for OLED specifications. Target education discount programs with reduced brightness configurations as the most penetrable volume corridor. Go-to-market through direct relationships with Mumbai and Bangalore media institutes bypasses entrenched distributor networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate display divisions seeking to monetize non-core OLED laptop panel operations amid Gen 8.6 capex intensity. Long-term viability hinges on emitter chemistry IP positions and locked OEM supply agreements rather than assembly scale. Watch for Samsung Display allocation announcements to ASUS and Dell as inflection indicators for competitive supply access.
| Strategic Initiative | Industry Significance |
|---|---|
| Gen 8.6 Substrate Line Investment | Samsung Display's Asan facility locks preferential supply for early-commitment OEM partners. |
| Phosphorescent Emitter Process Qualification | BOE and Visionox Chengdu fabs target professional-tier export certification under REACH Annex XVII. |
| Direct Enterprise Procurement Relationship | HP and Dell bypass distributor channels for fleet contracts above 5,000 units in US media corridors. |
| India PLI Scheme Assembly Partnership | Localized SKUs achieve import-parity pricing for price-sensitive creator segments in Mumbai. |
| Esports Tournament Hardware Mandate | ASUS secures 240Hz+ panel allocation through Shenzhen OEM lines for APAC circuit specifications. |
Research Methodology
Operator-level perspectives from display panel procurement directors, OEM product managers, post-production technical supervisors, and esports tournament organizers anchored the qualitative base. Primary interviews combined with secondary validation against SEC 10-K filings from Dell and HP, Korean Ministry of Trade customs data for emitter material imports, and ECHA REACH compliance registries. Bottom-up unit shipment estimates from Seoul-Incheon and Shenzhen assembly lines triangulated against top-down market value projections.
Scenario-bracketing framed the analytical approach across the analysis window, with CAGRs derived from substrate capacity expansion timelines and OEM allocation commitment patterns. Segmentation dimensions modeled include product type, end user archetype, diagonal size format, and emitter architecture technology tier. Forecast inputs incorporated Gen 8.6 line ramp schedules and phosphorescent emitter yield qualification progress from Korean and Chinese fabs.
Sensitivities concentrate around iridium price volatility, REACH enforcement intensity, and burn-in warranty limitation revisions that could accelerate or constrain enterprise fleet adoption. Cross-checking against IHS Markit panel shipment databases and OEM earnings call commentary is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Plasma Display Module Market
Display Technologies
North America Industrial Display Market
Display Technologies
Light Field Display Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Projector Screen Market
Display Technologies
Backlit Displays Market
Display Technologies
Touch Screen Module Market
Display Technologies
Computer Monitor Market
Display Technologies
Display Mask Market
Display Technologies
Portable Projector Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Large Industrial Displays Market
Display Technologies
E-Paper Display Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Global UHD Display Market