
 Cockpit Soc Chip Market | 2026-2036
Cockpit Soc Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Cockpit Soc Chip Market Insights
The EU Cyber Resilience Act is broadening the cost-of-entry calculus for cockpit SoC suppliers by mandating built-in security architectures and lifecycle update guarantees. Qualcomm leverages its Snapdragon Digital Chassis portfolio to sustain design wins across premium automotive platforms. NXP Semiconductors anchors its position through domain controller silicon purpose-built for functional safety requirements. Renesas Electronics competes via tight integration between its microcontroller heritage and newer infotainment-class processors.
A cockpit SoC is a system-on-chip that integrates CPU clusters, GPU cores, AI accelerators, and automotive networking interfaces onto a single die to process sensor data, render displays, and execute cabin intelligence workloads. These devices typically incorporate ISO 26262-certified safety islands alongside high-performance compute regions to satisfy mixed-criticality automotive architectures. Processor-class silicon captures the dominant value share as automakers spec multi-hundred-watt compute platforms for consolidated cockpit domains. Machine Learning-enabled SoCs represent the fastest-expanding technology segment as neural processing units become standard for occupant monitoring and natural language interfaces. Edge Computing deployment models are gaining preference among Tier-1 suppliers seeking deterministic latency for safety-critical display rendering.
The EU Cyber Resilience Act and UN R155 cybersecurity regulation are reshaping product qualification timelines by requiring hardware-rooted trust anchors and certified software supply chain documentation. The U.S. NHTSA and China's MIIT are advancing parallel mandates on data localization and crash-event recording that directly influence SoC memory architecture and encryption block design. Stakeholders must monitor divergence between regional certification regimes to avoid platform fragmentation that erodes silicon reuse economics.
Market Dynamics
The cockpit SoC market is being fundamentally restructured by the consolidation of discrete vehicle compute domains into unified zonal architectures, forcing silicon vendors to absorb safety-critical and infotainment-class workloads onto single die configurations.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory hardware security modules and over-the-air update capabilities at the silicon level are creating upgrade cycles across installed vehicle fleets.
- Electric vehicle platforms:Battery-electric architectures from automakers in China, Germany, and the United States require consolidated cockpit compute to reduce wiring harness complexity and vehicle weight.
- Neural processing unit integration:AI accelerators for occupant monitoring and natural language interfaces are becoming standard silicon blocks, expanding addressable die area per vehicle.
Market Restraints
- Advanced node wafer costs:Migration to 5nm and 3nm process geometries for high-performance cockpit clusters is inflating unit economics and constraining design win accessibility for mid-tier automakers.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification cycles for safety islands extend 18-24 months, compressing product refresh windows and locking architectural decisions early.
- Memory subsystem complexity:LPDDR5 and GDDR6 integration requirements for multi-display rendering are multiplying validation burden and defect escape risk at tape-out.
Strategic Opportunities
- Software-defined vehicle architectures:Over-the-air update mandates from the EU Cyber Resilience Act and UN R155 are enabling recurring revenue models for security patch and feature activation services.
- Edge computing deployment models:Tier-1 suppliers are adopting deterministic latency configurations for safety-critical display rendering, opening specialized silicon variants beyond standard merchant SoCs.
- India automotive production:Local content requirements and expanding domestic vehicle assembly are creating demand for cost-optimized cockpit silicon with reduced thermal envelopes.
Industry Challenges
- Functional safety engineering talent:Scarcity of ISO 26262-certified architects and verification engineers is extending development timelines and inflating compensation costs across design centers.
- Legacy vehicle integration:Backward compatibility with CAN and LIN bus architectures while supporting Ethernet-TSN for new zonal networks is multiplying interface IP complexity and silicon area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cockpit Soc Chip Market |
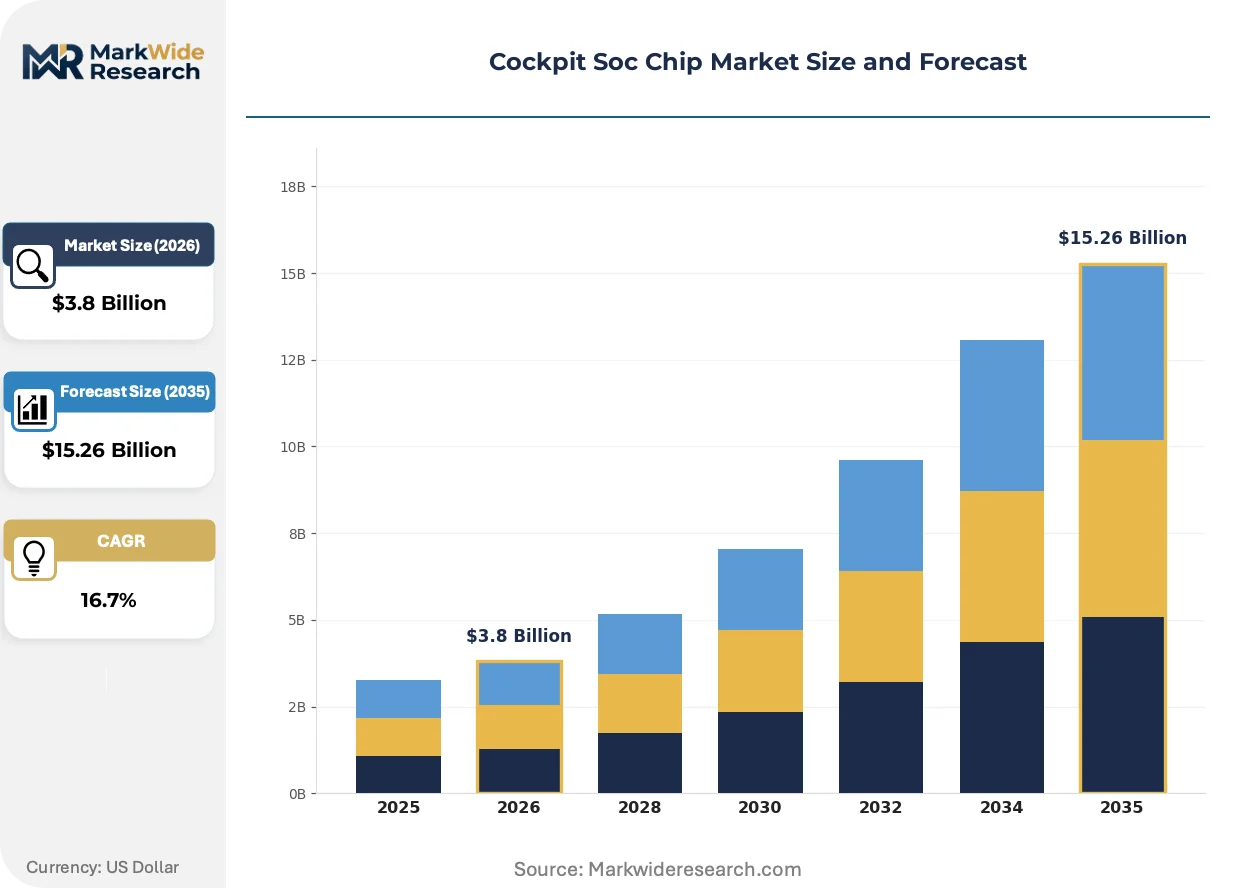
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuit, Microcontroller, Processor, FPGA Technology: Digital Signal Processing, Machine Learning, Data Fusion, Wireless Communication End User: Automakers, Tier-1 Suppliers, Aftermarket Providers, Fleet Management Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Qualcomm, NXP Semiconductors, Texas Instruments, Renesas Electronics, Infineon Technologies, STMicroelectronics, NVIDIA, Intel, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cockpit Soc Chip Market Trends and Innovations
Silicon architectures are converging around heterogeneous compute fabrics where neural processing units, safety islands, and graphics cores share unified memory subsystems, collapsing the traditional separation between infotainment and instrument cluster processors.
Chiplet-based designs are automating the integration of disaggregated compute, I/O, and memory die through standardized interconnects like UCIe. Automotive OEMs in Germany and the United States are qualifying these modular configurations for 2027 platform launches. This approach is automating the ability to mix process nodes—combining 3nm logic with mature-node I/O—without full reticle redesign, compressing non-recurring engineering costs by 40-60% versus monolithic alternatives.
The EU Cyber Resilience Act and UN R155 cybersecurity regulation are mandating hardware-rooted trust anchors and certified software supply chain documentation before type approval. Semiconductor vendors must embed physically unclonable functions and secure enclaves at the foundry level. Premium vehicle platforms in Germany face the steepest compliance burden, with certification timelines extending 8-12 months beyond historical baselines.
Fleet operators and mobility-as-a-service providers are consolidating procurement decisions at the group level rather than delegating to individual vehicle programs. This buyer concentration is forcing silicon vendors to commit to 7-10 year production guarantees and long-term pricing agreements. The shift is most pronounced in China, where domestic ride-hailing platforms and state-backed fleet electrification mandates are consolidating demand across multiple OEM brands under unified technical specifications.
Cockpit Soc Chip Market Segmentation
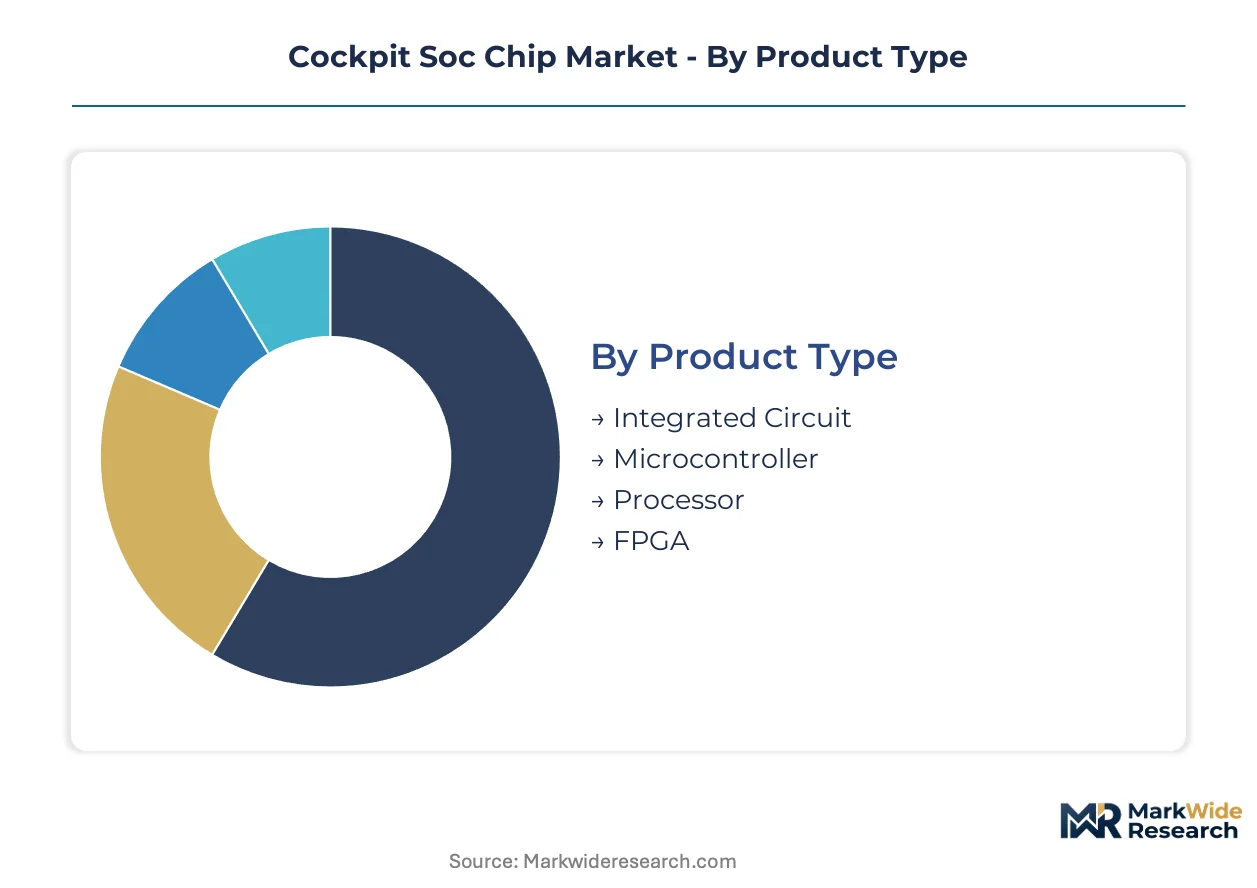
Cockpit SoC segmentation reveals how silicon vendors balance automotive-grade reliability against consumer-electronics performance. Each dimension—product architecture, compute paradigm, customer channel, and infrastructure model—carries distinct certification burdens and margin profiles that shape vendor portfolio strategy.
Product Type:
Standardization pressure intensifies downward from processors toward microcontrollers, yet automakers still demand customization for thermal envelopes and pin compatibility.
- Processor:Multi-core CPU clusters with integrated GPU and NPU blocks dominate consolidated cockpit domains. German premium automakers specify these for unified instrument cluster-infotainment compute, driven by EU Cyber Resilience Act mandates for hardware-rooted security enclaves.
- Microcontroller:Safety islands hosting ASIL-D certified real-time cores handle steering-column switches and warning lamps. Tier-1 suppliers in the United States integrate these alongside main processors to partition critical from non-critical workloads, constrained by ISO 26262 qualification timelines stretching 18-24 months.
- Integrated Circuit:Analog front-ends and power management die complete the cockpit silicon stack.
- FPGA:Reconfigurable logic accelerates prototyping for novel sensor fusion algorithms.
Leading the category by volume: Processor. Growing fastest: Microcontroller.
Technology:
Cost tier separation runs from commodity wireless stacks to premium neural accelerators requiring dedicated foundry capacity.
- Machine Learning:Neural processing units execute occupant monitoring and natural language interfaces at sub-50 millisecond latency. China domestic EV platforms mandate these blocks as standard equipment, expanding die area per vehicle and inflating wafer consumption at advanced nodes.
- Digital Signal Processing:Dedicated DSP cores handle audio beamforming and road-noise cancellation with deterministic throughput. United States pickup truck and SUV segments prioritize these for premium cabin acoustics, facing margin pressure from software-defined alternatives on general-purpose cores.
- Data Fusion:Sensor aggregation pipelines merge camera, radar, and lidar streams for augmented reality head-up displays.
- Wireless Communication:Cellular and Wi-Fi modems enable over-the-air updates and cloud-connected services.
Commanding the highest margins: Machine Learning. Expanding most quickly: Digital Signal Processing.
End User:
Procurement authority is shifting from dispersed vehicle programs toward consolidated fleet-level negotiations.
- Automakers:OEMs in Germany, China, and the United States define SoC specifications for entire vehicle architectures. Their platform consolidation strategies demand 7-10 year production guarantees from silicon vendors, compressing supplier margins through long-term pricing agreements.
- Tier-1 Suppliers:Continental, Bosch, and Denso intermediate between chip vendors and vehicle programs. These integrators in Europe and North America are adopting edge computing deployment models for deterministic latency, creating demand for specialized silicon variants beyond merchant catalog parts.
- Aftermarket Providers:Retrofit infotainment systems for legacy vehicle fleets.
- Fleet Management:Ride-hailing and logistics operators in China consolidate procurement across multiple OEM brands.
Driving the steepest volume concentration: Automakers. Gaining share fastest: Fleet Management.
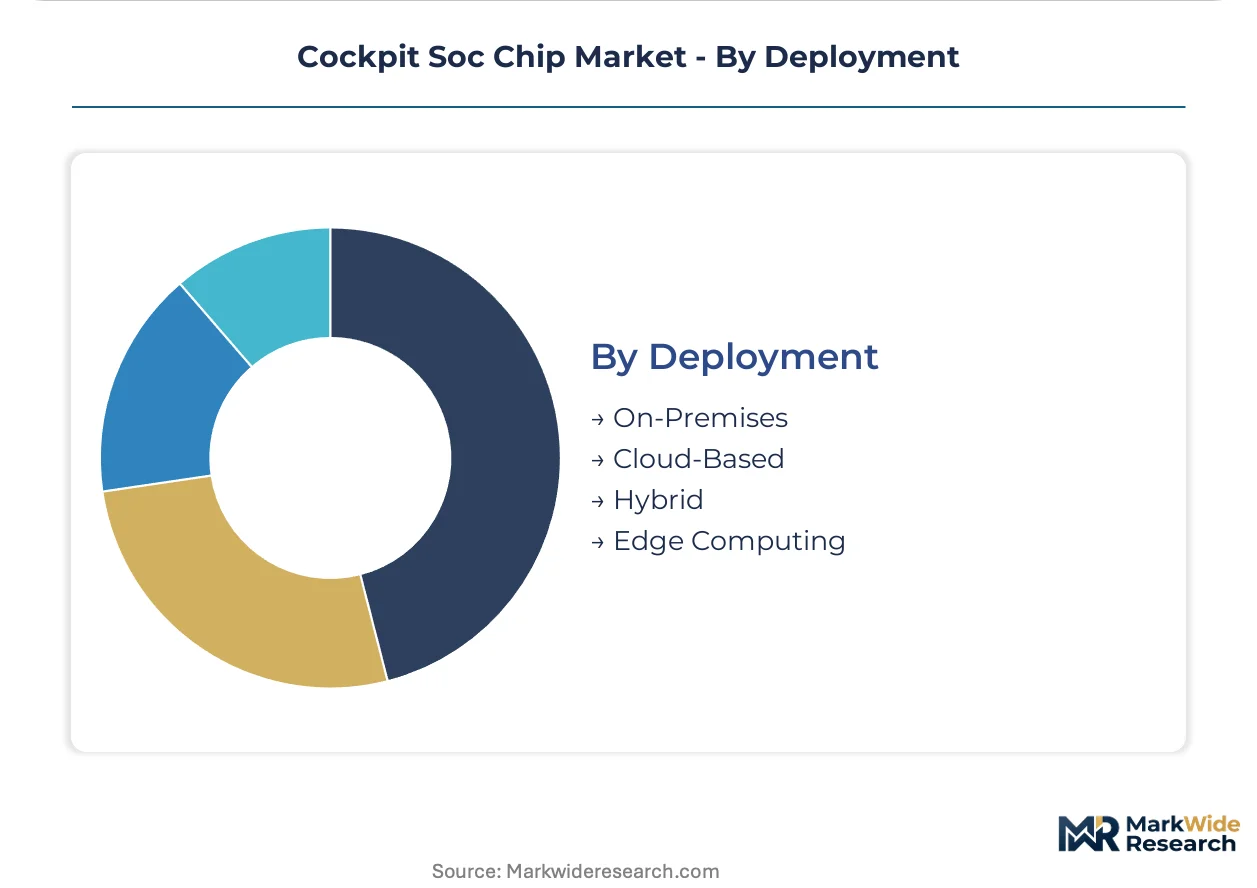
Deployment:
Maturity separation separates proven on-premises architectures from emerging cloud-hybrid models with unvalidated cybersecurity postures.
- Edge Computing:Deterministic latency configurations process safety-critical display rendering locally without cloud round-trips. Tier-1 suppliers in Germany and the United States qualify these for zonal E/E architectures, enabled by EU Cyber Resilience Act and UN R155 mandates for hardware-rooted trust anchors.
- On-Premises:Traditional cockpit compute remains fully contained within vehicle boundaries. Japanese automakers favor this model for cybersecurity risk containment, constrained by limited scalability for AI model updates compared to connected alternatives.
- Cloud-Based:Remote rendering and voice processing offload compute to data centers.
- Hybrid:Workload partitioning between vehicle and cloud based on connectivity and criticality.
Anchor deployment by installed base: On-Premises. Climbing the fastest: Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Lingang Special Area and Hsinchu Science Park concentrate foundry capacity for automotive-grade silicon. Tax incentives in these zones draw packaging and test houses into co-located clusters. Local content rules in major automotive markets are fragmenting procurement geography.
China
Domestic EV platforms from BYD and NIO mandate neural processing units as standard equipment. MIIT enforces data localization rules that dictate on-chip encryption block design. The Yangtze River Delta cluster around Shanghai houses wafer fabs and OSAT facilities serving local automakers.
Germany
Premium OEM platform consolidation demands 7-10 year silicon production guarantees. KBA enforces UN R155 cybersecurity mandates that extend qualification timelines 8-12 months. The Stuttgart-Munich corridor anchors infotainment system integration for Mercedes-Benz and BMW architectures.
United States
Pickup truck and SUV segments prioritize DSP cores for premium cabin acoustics. NHTSA advances crash-event recording mandates influencing SoC memory architecture. Michigan's automotive corridor and Austin's silicon design centers host Tier-1 supplier engineering operations.
South Korea
Hyundai-Kia Group's unified E/E architectures require consolidated cockpit compute. The national regulator enforces parallel cybersecurity standards to EU and UN frameworks. Seoul's Pangyo Techno Valley clusters fabless design houses specializing in automotive neural accelerators.
Japan
Conservative automakers favor on-premises compute models for cybersecurity containment. METI coordinates domestic semiconductor resilience programs with automotive procurement. Nagoya's Chubu region maintains Tier-1 supplier headquarters for Toyota and Honda platform integration.
Cockpit Soc Chip Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the cockpit SoC landscape. Qualcomm, NVIDIA, and Intel leverage consumer electronics scale against NXP and Renesas automotive heritage. Three archetypes dominate: mobile-chip transplants, automotive-born suppliers, and industrial-semiconductor diversifiers. M&A activity concentrates in AI accelerator IP and functional safety software assets, while strategic partnerships secure foundry capacity at advanced nodes.
Among mobile-processor transplants, Qualcomm and NVIDIA occupy positions exemplifying the premium-tier vector, leveraging GPU and AI heritage for infotainment consolidation. NXP Semiconductors and Renesas Electronics represent the automotive-native archetype, anchoring functional safety credibility through ISO 26262-certified product lines. Texas Instruments and Infineon Technologies sit within the industrial-diversification tier, extending power management and real-time control expertise into cockpit domains.
| Leading Market Players |
|---|
| Qualcomm |
| NXP Semiconductors |
| Texas Instruments |
| Renesas Electronics |
| Infineon Technologies |
| STMicroelectronics |
| NVIDIA |
| Intel |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
EU Cyber Resilience Act hardware security mandates gate qualified foundry access and compress premium-tier pricing power to vendors with certified silicon architectures. Automakers in Germany and China now pay scarcity premiums for SoCs embedding lifecycle update guarantees, while mid-tier buyers face exclusion from advanced-node supply.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with automakers paying 15-25% markups for 12-week delivery windows versus standard 26-week cycles. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and non-safety-qualified economy levels separates German premium OEMs from Chinese mass-market EV platforms and Indian cost-optimized variants. Cost compression in the economy tier intensifies because domestic Chinese foundries are expanding mature-node capacity. Fleet operators consolidating procurement across multiple OEM brands exhibit lowest price sensitivity, while Indian domestic assemblers face acute margin constraints.
Supply Chain Analysis
Freight costs for specialized automotive-grade packaging from Taiwan and South Korea add 8-12% to landed silicon costs for European and North American module assembly. Wafer supply concentrates in Taiwan, South Korea, and the United States, with advanced-node EUV capacity tethered to TSMC and Samsung foundry schedules. Raw material dependencies span silicon wafers, high-purity photoresists, and palladium-based sputtering targets. Single-source vulnerability around EUV lithography equipment exposes qualification timelines to ASML production backlogs. Distribution runs through Tier-1 integrators in Germany, Japan, and the United States who buffer inventory against automotive demand volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chiplet-based heterogeneous integration is displacing monolithic SoC architectures as the dominant cockpit compute paradigm. This technology transition compresses non-recurring engineering costs while fragmenting supplier ecosystems.
For Market Incumbents: Deploy functional safety certification moats by accelerating ISO 26262 ASIL-D qualification pipelines ahead of competitor tape-outs. Qualcomm and NXP should deepen backward integration into secure enclave IP to defend against NVIDIA's GPU-centric platform consolidation. Locking 7-10 year production guarantees with German premium OEMs secures volume commitments that emerging entrants cannot match.
For New Entrants and Emerging Players: Enter via India's expanding domestic vehicle assembly, where local content requirements and reduced thermal envelope specifications create white-space for cost-optimized microcontroller-class silicon. Target edge computing deployment models for Tier-1 suppliers in the United States seeking deterministic latency configurations beyond standard merchant catalogs. Partner with domestic Chinese foundries on mature-node processes to bypass advanced-node capacity constraints.
For Investors and Strategic Acquirers: KBA extending UN R155 cybersecurity qualification timelines by 8-12 months is the leading indicator that functional safety software assets will command acquisition premiums. The 5-10 year viability window favors vendors with automotive-native heritage over consumer-electronics transplants lacking ASIL certification track records. Acquire AI accelerator IP specialists with occupant monitoring algorithm portfolios before platform consolidation locks architectural standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Adoption | Automotive OEMs in Germany qualify UCIe-based modular configurations for zonal E/E platforms. |
| Hardware Security Module Integration | EU Cyber Resilience Act mandates embed physically unclonable functions at foundry level. |
| Edge Computing Deployment | Tier-1 suppliers adopt deterministic latency configurations for safety-critical display rendering. |
| Neural Processing Unit Standardization | China domestic EV platforms mandate NPU blocks as standard equipment across all trims. |
| Long-Term Production Guarantees | Fleet operators in China consolidate procurement under 7-10 year silicon supply agreements. |
Research Methodology
Document review covered SEC 10-K filings, automotive semiconductor trade databases, and regulatory submission records from KBA and MIIT, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, foundry account managers, and functional safety certification auditors. Secondary validation drew from vehicle production databases, IHS Markit registration data, and customs import records. Bottom-up unit shipment estimates triangulated against top-down semiconductor consumption models.
Output tables project value and volume trajectories across the analysis window by product type, technology paradigm, end-user channel, and deployment architecture. CAGRs derive from regression against historical silicon content per vehicle, foundry capacity expansion schedules, and regulatory mandate implementation timelines. Model inputs include neural processing unit penetration curves, ISO 26262 certification backlog estimates, and zonal E/E architecture adoption rates by OEM.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry equipment export restrictions or automotive demand shocks. Projections reflect assumptions about EU Cyber Resilience Act enforcement consistency and China-U.S. semiconductor trade policy stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Europe Digital Signal Processor Market