
 DNA Sequencing Chip Market | 2026-2036
DNA Sequencing Chip Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Sequencing Chip Market Insights
China's semiconductor foundry expansion is fragmenting the DNA sequencing chip supply base as domestic fabs add MEMS and biosensor capacity. Illumina sustains its position through captive reagent ecosystems and installed-base lock-in across clinical laboratories. Thermo Fisher Scientific anchors its presence through ion semiconductor chemistry and integrated workflow instrumentation. Pacific Biosciences differentiates via single-molecule real-time architecture for complex genomic regions.
A DNA sequencing chip integrates microfluidic channels, electrochemical sensors, or optical detectors onto a silicon or glass substrate to read nucleotide sequences in parallel. These devices achieve throughput from thousands to billions of reads per run, with read lengths spanning tens to millions of base pairs depending on architecture, enabling de novo assembly, variant calling, and epigenetic profiling. Next-generation sequencer chips now capture the dominant value pool as clinical-grade throughput requirements favor massively parallel designs, while long-read sequencer chips represent the fastest-expanding segment for structural variation and telomere analysis. Sequencing by synthesis technology leads in installed base and consumable recurrence, though nanopore sequencing chips gain traction in field-deployable and point-of-care configurations.
The FDA regulates sequencing chips as part of in vitro diagnostic systems under premarket notification or approval pathways, while the EMA's In Vitro Diagnostic Regulation imposes post-market surveillance and performance documentation requirements across European member states. ISO 13485 quality management standards govern manufacturing consistency for clinical-grade chips, and the Clinical Laboratory Improvement Amendments shape laboratory-developed test workflows that drive chip utilization. Stakeholders must monitor how regulatory convergence on analytical validation standards affects chip architecture choices and software companion requirements.
Market Dynamics
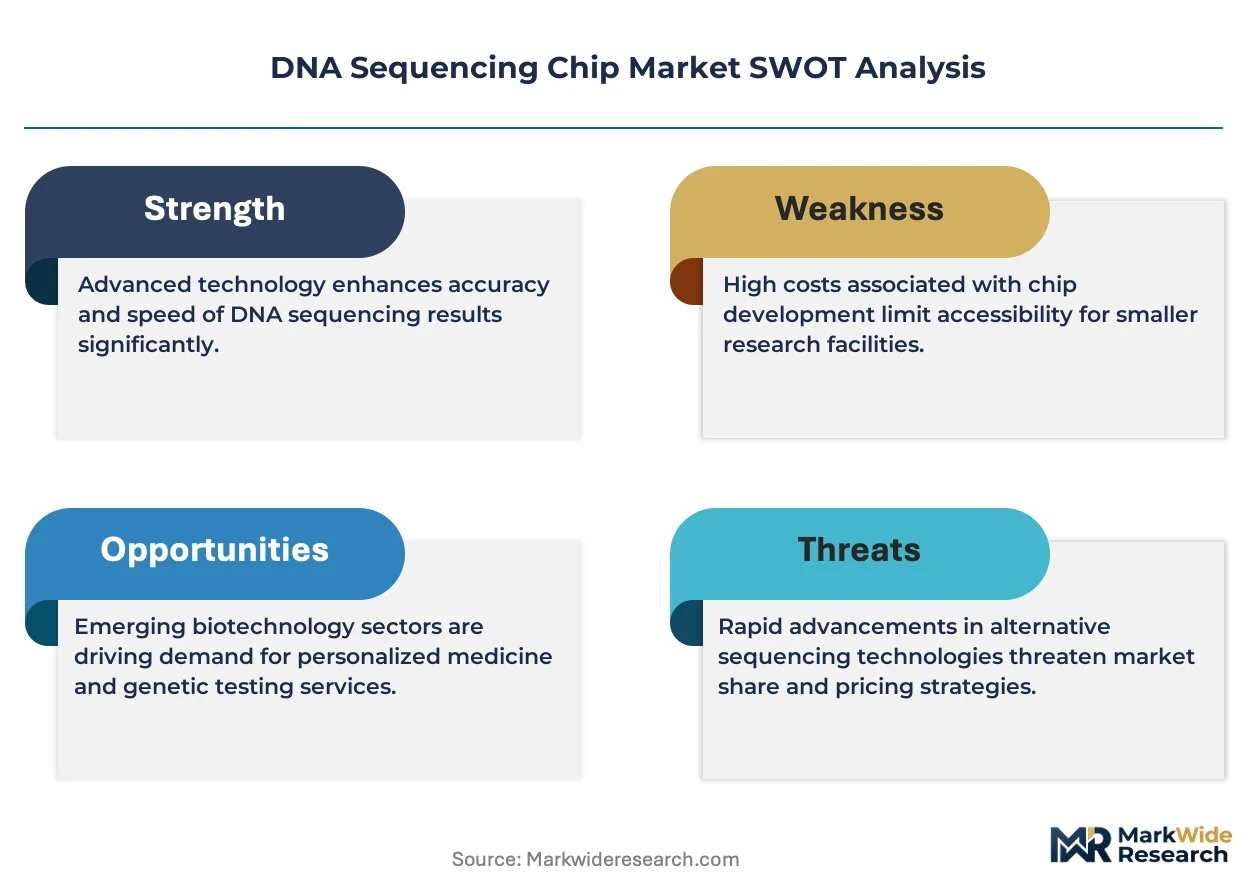
China's semiconductor foundry expansion is fragmenting the DNA sequencing chip supply base as domestic fabs add MEMS and biosensor capacity, eroding the historical concentration of fabrication in Taiwan and the United States.
Growth Catalysts
- Clinical Laboratory Improvement Amendments:The CLIA framework shapes laboratory-developed test workflows that drive chip utilization in hospital-based precision medicine programs across the United States.
- Next-generation sequencing oncology panels:The FDA's evolving guidance on NGS-based cancer diagnostics is reshaping product validation requirements and expanding addressable test menus.
- Academic medical centers:United States biotechnology clusters and research hospitals anchor instrument placement and consumable pull-through in translational genomics.
Market Restraints
- Silicon wafer cost volatility:Foundry pricing for 300mm silicon wafers creates margin pressure on chip fabricators serving sequencing instrument OEMs.
- Optical component supply concentration:Laser and filter suppliers in Germany and Japan represent single-source risks for fluorescence-based sequencing architectures.
- Read-length limitations in short-read chips:Sequencing-by-synthesis platforms cannot resolve complex structural variants or highly repetitive genomic regions without complementary long-read workflows.
Strategic Opportunities
- Point-of-care infectious disease testing:Nanopore sequencing chips enable field-deployable pathogen identification in rural health systems and outbreak response settings.
- Epigenetic profiling applications:Methylation-aware sequencing workflows open adjacent revenue streams in liquid biopsy and aging-related diagnostics.
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract semiconductor packaging and biosensor assembly capacity to serve South Asian diagnostic markets.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories struggle to hire computational biologists capable of interpreting variant calls from high-throughput sequencing outputs.
- ISO 13485 certification timelines:Quality management system audits for clinical-grade chip manufacturing extend product commercialization cycles by 12-18 months.
- Legacy instrument compatibility:Chip architecture refreshes must maintain backward compatibility with installed-base fluidics and thermal control subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Sequencing Chip Market |
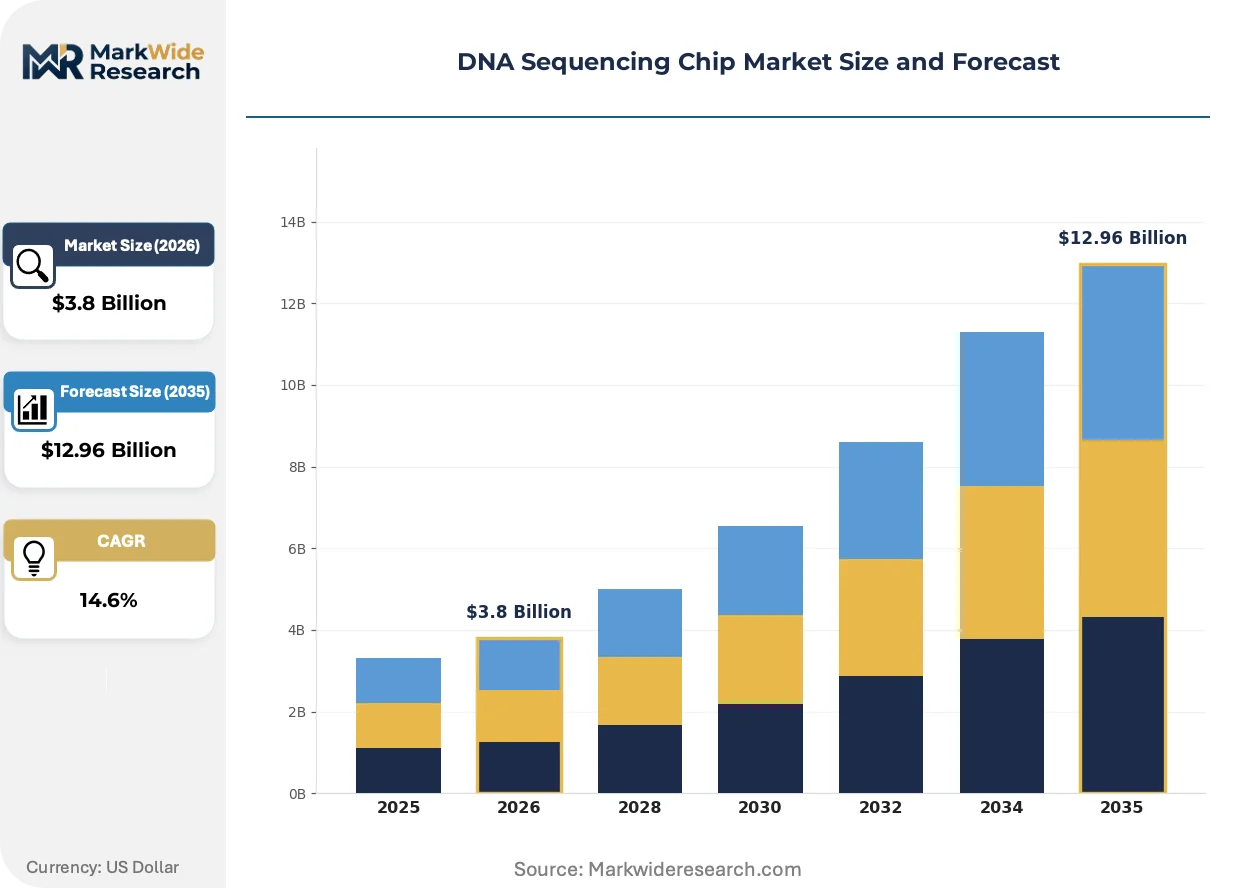
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarray, Next-Generation Sequencer, Sanger Sequencer, Long-Read Sequencer Application: Clinical Diagnostics, Environmental Testing, Agricultural Genomics, Research & Development End User: Hospitals, Academic Institutions, Biotechnology Companies, Pharmaceutical Firms Technology: Sequencing By Synthesis, Ion Torrent, Nanopore Sequencing, Optical Sequencing |
| Companies Covered | Illumina, Thermo Fisher Scientific, QIAGEN, Roche, Agilent Technologies, Pacific Biosciences, Oxford Nanopore Technologies, PerkinElmer, Macrogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Sequencing Chip Market Trends and Innovations
Sequencing architectures are converging around hybrid workflows that combine throughput and accuracy, while regulatory frameworks and procurement models adapt to clinical-grade deployment at scale.
Combinatorial probe-anchor synthesis technology is hybridizing with enzymatic base detection to enable real-time error correction during massively parallel sequencing runs. Academic medical centers in the United States are piloting these hybrid chips for somatic variant profiling in solid tumor biopsies. The approach compresses the gap between short-read accuracy and long-read contiguity without requiring separate instrument platforms.
The European Union's In Vitro Diagnostic Regulation imposes post-market surveillance and performance documentation requirements across member states. Chip manufacturers must now maintain technical files and clinical evidence packages for each sequencing chemistry variant. Medium-sized diagnostic companies are responding by consolidating product portfolios and exiting lower-volume assay categories to reduce compliance burden.
Hospital procurement departments are unbundling sequencing service contracts from instrument leases, creating separate negotiations for capital equipment, consumables, and bioinformatics support. Integrated delivery networks in the United States are driving this fragmentation to benchmark per-sample costs against reference laboratories. The shift pressures OEMs to disclose component-level pricing and accept shorter contract renewal cycles.
DNA Sequencing Chip Market Segmentation
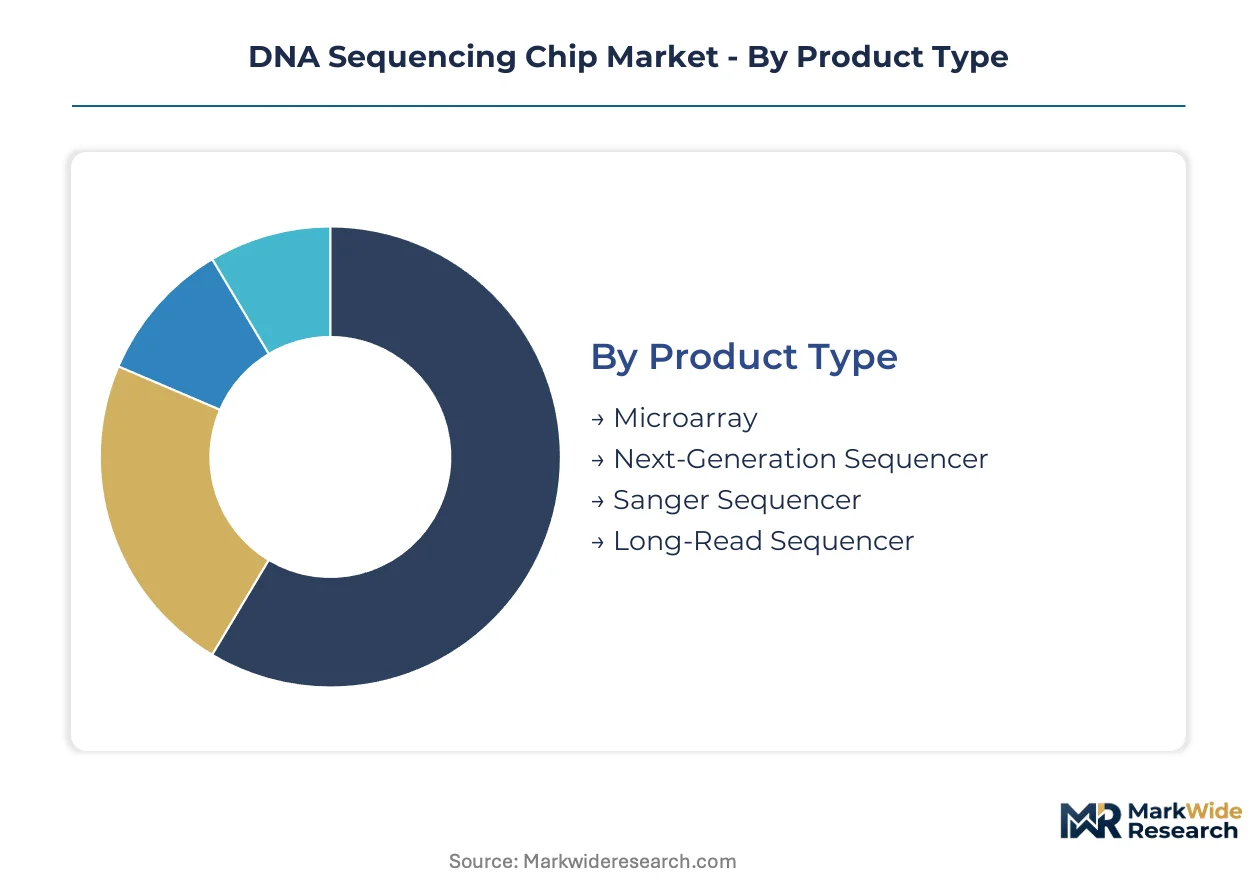
Segmentation in the DNA sequencing chip market reflects divergent technical requirements across throughput demands, read-length specifications, and regulatory compliance tiers. Each dimension shapes procurement patterns, consumable pull-through rates, and manufacturing quality standards.
Product Type:
Cost tier differentiation separates commodity microarray platforms from premium long-read architectures.
- Microarray:These chips immobilize oligonucleotide probes on glass or silicon substrates for targeted genotyping and expression profiling. Agricultural genomics programs in Brazil and research consortia in Germany drive replacement cycles for these lower-cost consumables.
- Next-Generation Sequencer:Massively parallel flow cells integrate cluster generation and sequencing chemistry for billions of reads per run. Clinical laboratories in the United States anchor demand as oncology panel volumes expand under CLIA-certified workflows.
- Sanger Sequencer:Capillary electrophoresis chips resolve fragments by size for targeted validation sequencing. Academic core facilities maintain installed bases for confirmatory testing.
- Long-Read Sequencer:Single-molecule real-time or nanopore architectures achieve contiguous reads spanning millions of base pairs. Structural variation analysis in rare disease diagnostics and telomere research commands premium pricing.
Next-Generation Sequencer commands the established base. The steepest expansion runs through Long-Read Sequencer.
Application:
Application focus determines regulatory pathway complexity and reimbursement eligibility.
- Clinical Diagnostics:FDA-cleared sequencing chips support hereditary cancer screening, pharmacogenomics, and infectious disease identification. Hospital laboratories in Texas and California scale precision medicine programs with validated assay menus.
- Environmental Testing:Portable nanopore chips enable field-based biodiversity monitoring and pathogen surveillance. Research stations in Australia and watershed management authorities in Canada deploy these for real-time microbial community analysis.
- Agricultural Genomics:Trait mapping and marker-assisted breeding programs utilize mid-density microarray panels. Seed companies in Iowa and livestock improvement cooperatives in the Netherlands drive seasonal consumable demand.
- Research & Development:Exploratory sequencing workflows in academic and biotechnology settings tolerate higher error rates for novel discovery. Flexible reagent configurations and custom probe designs characterize procurement.
Clinical Diagnostics captures the dominant revenue pool. Agricultural Genomics is climbing the fastest as food security investments accelerate.
End User:
Customer type dictates instrument capital allocation and service contract structures.
- Hospitals:Integrated delivery networks consolidate sequencing infrastructure under centralized laboratory medicine departments. CLIA high-complexity certification requirements shape vendor selection and validation timelines.
- Academic Institutions:Core sequencing facilities serve multi-investigator consortia with subsidized per-run pricing. National Institutes of Health funding cycles drive instrument refresh decisions.
- Biotechnology Companies:Contract research organizations and platform developers prioritize throughput scalability and automation compatibility. Cell therapy manufacturers adopt in-house sequencing for quality control release testing.
- Pharmaceutical Firms:Companion diagnostic development programs require GMP-compliant chip manufacturing and extensive analytical validation. Oncology and rare disease therapeutic pipelines anchor investment.
Hospitals represent the largest installed base. Biotechnology Companies are gaining share fastest as cell and gene therapy manufacturing scales.
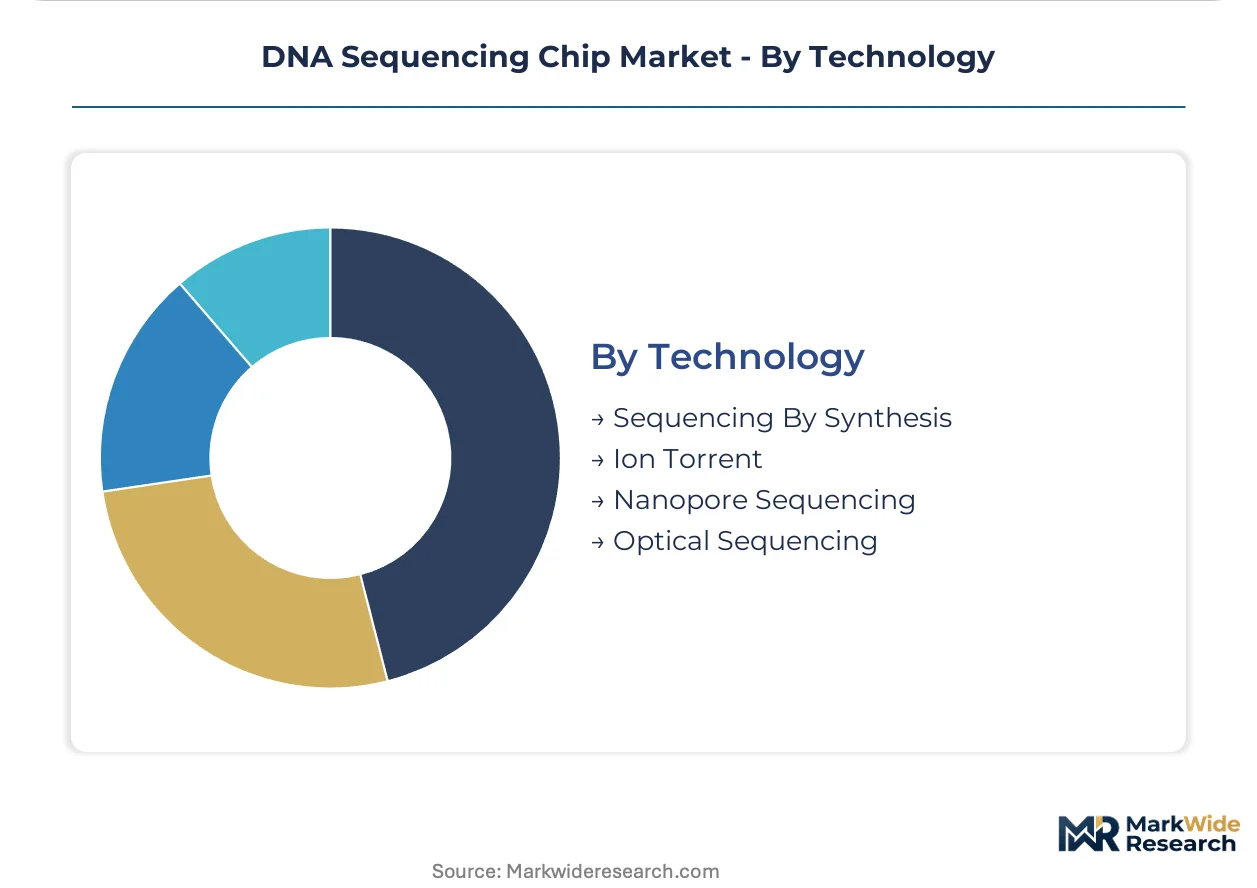
Technology:
Technical architecture determines read accuracy, length distributions, and capital intensity.
- Sequencing By Synthesis:Reversible terminator chemistry with fluorescence detection achieves industry-leading accuracy for single-nucleotide variant calling. Short-read limitations in repetitive regions necessitate complementary long-read workflows.
- Ion Torrent:Semiconductor-based detection of hydrogen ions during polymerization eliminates optical components. Thermo Fisher Scientific's installed base in clinical and research settings sustains consumable demand.
- Nanopore Sequencing:Protein nanopores embedded in synthetic membranes read nucleotides via ionic current disruption. Field-deployable configurations bypass centralized laboratory infrastructure for outbreak response.
- Optical Sequencing:Direct imaging of individual DNA molecules enables ultra-long read generation. PacBio's single-molecule real-time platform resolves complex structural variants and epigenetic modifications.
Sequencing By Synthesis dominates the installed base. Nanopore Sequencing shows the steepest expansion trajectory as point-of-care applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States laboratories prioritize clinical-grade throughput for oncology panels, while Chinese research institutes emphasize cost-engineered alternatives for agricultural genomics, and European facilities balance regulatory compliance with multi-omics integration.
United States
Academic medical centers in Boston and Houston anchor instrument placement for precision medicine programs. The FDA's evolving guidance on NGS-based oncology panels reshapes validation requirements for chip manufacturers. Texas and California hospital networks scale CLIA-certified workflows, driving consumable pull-through.
China
Domestic semiconductor foundries in Shanghai and Beijing add MEMS and biosensor capacity, fragmenting the historical supply base. The NMPA accelerates review pathways for innovative sequencing devices. Yangtze River Delta biotechnology parks cultivate local chip design capabilities.
Germany
Industrial genomics programs in Bavaria and North Rhine-Westphalia sustain demand for high-accuracy short-read platforms. The EMA's In Vitro Diagnostic Regulation imposes post-market surveillance documentation. Munich-area research consortia pilot hybrid sequencing workflows for rare disease diagnostics.
India
Agricultural biotechnology institutes in Maharashtra and Karnataka deploy mid-density microarrays for crop improvement. The PLI scheme for electronics manufacturing attracts semiconductor packaging capacity. Hyderabad's diagnostic corridor expands sequencing infrastructure for infectious disease surveillance.
Japan
Pharmaceutical firms in Kanto and Kansai regions adopt sequencing chips for companion diagnostic development. The PMDA maintains stringent analytical validation standards for clinical-grade devices. Osaka-based cell therapy manufacturers integrate in-house quality control sequencing.
DNA Sequencing Chip Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The DNA sequencing chip market structures around a consolidated core of integrated platform developers and a fragmented periphery of specialized component suppliers. Three archetypes dominate: captive ecosystem providers with installed-base lock-in, chemistry-agnostic instrument specialists, and emerging nanopore disruptors targeting point-of-care deployment. Competitive moves center on backward integration into foundry partnerships and portfolio consolidation to reduce regulatory compliance burden.
Among integrated platform developers, Illumina and Thermo Fisher Scientific exemplify the scale-driven archetype through captive reagent ecosystems, while Pacific Biosciences occupies a position within the long-read specialization tier. These three companies anchor distinct competitive vectors: fluorescence-based massively parallel sequencing, semiconductor ion detection, and single-molecule real-time architectures respectively.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| QIAGEN |
| Roche |
| Agilent Technologies |
| Pacific Biosciences |
| Oxford Nanopore Technologies |
| PerkinElmer |
| Macrogen |
| Others |
Pricing and Supply Chain Analysis
Shanghai's Yangtze River Delta foundry cluster is adding MEMS and biosensor capacity at pace, eroding Taiwan's historical dominance and compressing margin capture for sequencing chip fabricators serving instrument OEMs. This geographic redistribution fragments supplier pricing power while CLIA-certified hospital laboratories in Texas and California consolidate procurement volumes.
Pricing Analysis
Price spreads between US and Chinese supply origins now exceed 30% for equivalent process nodes, forcing OEMs to arbitrage quality-grade certifications against landed cost. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical-grade chips from research-use-only and unvalidated alternatives. Cost compression in the mid-tier is intensifying because domestic Chinese fabs are undercutting established suppliers on 300mm wafer processing. Academic core facilities show highest price sensitivity, while pharmaceutical companion diagnostic programs absorb premium pricing for GMP-compliant manufacturing.
Supply Chain Analysis
300mm silicon wafers from Taiwan, South Korea, and the United States anchor upstream feedstock, with photolithography equipment and specialty gases drawing from German and Japanese suppliers. Laser sources, optical filters, and nanopore membranes represent concentrated single-source vulnerabilities. Tariff exposure on semiconductor manufacturing equipment is rerouting some packaging steps to Malaysia and Vietnam. Distribution runs through instrument OEM captive channels and third-party laboratory distributors with regional cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation under integrated delivery networks is shifting negotiating leverage toward buyers, fragmenting vendor pricing power and shortening contract renewal cycles. This buyer-power concentration demands differentiated defensive positioning across the value chain.
For Market Incumbents: Harden installed-base lock-in through backward integration into reagent chemistry manufacturing and exclusive foundry partnerships in Taiwan or South Korea. Nanopore disruptors targeting point-of-care deployment threaten the clinical laboratory consumable stream; ISO 13485 certification investment creates switching-cost barriers against lower-cost Chinese entrants. For New Entrants and Emerging Players: Build out field-deployable infectious disease testing configurations for rural health systems in India and outbreak response settings in Southeast Asia. Agricultural genomics programs in Brazil and the Netherlands present the most penetrable volume tier. A reagent-rental pricing model with instrument placement subsidies bypasses capital-budget constraints at mid-sized diagnostic laboratories. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurrence play because clinical-grade sequencing generates predictable pull-through revenue streams under CLIA-certified workflows. Target acquisition profiles center on nanopore membrane engineering specialists and bioinformatics software companions with FDA 510(k) clearance pathways. The signal to watch is NMPA approval velocity for domestic Chinese sequencing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Diversification | Reduces single-source exposure to Taiwan semiconductor fabrication capacity. |
| Reagent Chemistry Backward Integration | Captures consumable margin pools and deepens installed-base switching costs. |
| Point-of-Care Regulatory Pathway | Positions nanopore architectures for CLIA-waived infectious disease testing expansion. |
| Bioinformatics Software Companion | Addresses clinical laboratory talent scarcity with automated variant interpretation. |
| Hybrid Sequencing Workflow Development | Combines short-read accuracy with long-read contiguity for solid tumor profiling. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings for this DNA sequencing chip market assessment. Conversations with clinical laboratory directors, biomedical engineers at academic medical centers, GPO contracts managers, and sequencing platform R&D heads combined with FDA 510(k) databases, EMA technical documentation, NMPA approval registries, and ISO 13485 audit records. Bottom-up instrument placement modeling and top-down consumable pull-through estimation triangulate market sizing.
Calibration against historical placement data from NIH funding cycles and hospital capital expenditure disclosures validates the projection framework across the analysis window. Segmentation dimensions include product architecture, application regulatory tier, end-user capital allocation pattern, and technology read-length specification. CAGRs derive from instrument refresh cycles, consumable recurrence rates, and panel test volume expansion under precision medicine programs. Epigenetic profiling adoption curves and structural variation diagnostic penetration serve as industry-specific forecast inputs.
Sensitivities concentrate around FDA guidance evolution for NGS-based oncology panels, NMPA approval timelines for domestic Chinese platforms, and silicon wafer pricing volatility from foundry capacity constraints. Cross-checking against CMS reimbursement rate adjustments for molecular diagnostics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Microserver Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Cockpit Soc Chip Market