
 South Korea Data Center Processor Market | 2026-2036
South Korea Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Processor Market Insights
Cloud computing is restructuring processor procurement patterns across South Korean data centers. NVIDIA Corporation dominates AI training workloads through its GPU architecture leadership. Samsung Electronics anchors memory-processor integration with its HBM supply chain. SK Hynix leverages advanced packaging capabilities to differentiate in high-bandwidth memory solutions.
A data center processor is a specialized integrated circuit fabricated on advanced process nodes, typically below 7 nanometers, designed to execute computational workloads in centralized server facilities with thermal design power ratings exceeding 150 watts. Its primary commercial purpose is enabling efficient parallel computation for enterprise and consumer digital services. GPU segments capture premium margins as machine learning training intensity escalates. CPU categories retain volume leadership in virtualization and general-purpose cloud instances. FPGA adoption concentrates in telecommunications edge deployments requiring programmable logic flexibility.
MFDS standards govern processor reliability in healthcare data center deployments, while K-Chips Act subsidies reshape domestic design house competitiveness against foreign suppliers. METI-aligned efficiency benchmarks from Japan influence regional supplier certification requirements for data center equipment exports. Stakeholders must monitor whether domestic foundry capacity expansion under national semiconductor programs alters procurement economics for fabless processor vendors serving Korean hyperscalers.
Market Dynamics
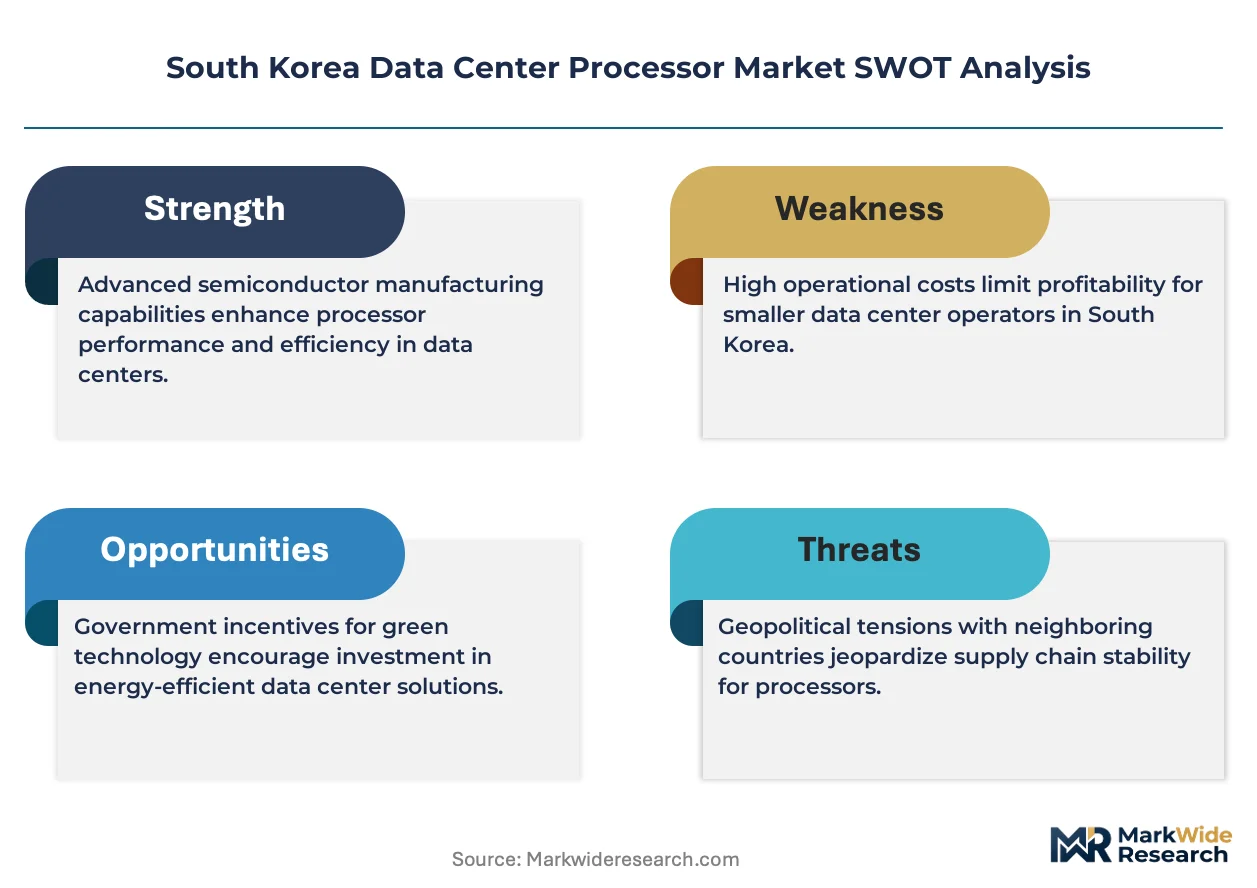
K-Chips Act subsidies are restructuring procurement economics for South Korean hyperscalers, tilting domestic data centers toward locally designed processors while advanced packaging investments by memory suppliers compress integration timelines for AI-optimized silicon.
Growth Catalysts
- Memory-Compute Convergence:HBM3E integration with logic dies is reducing data movement bottlenecks in Seoul training clusters. Korean foundries are expanding CoWoS-equivalent capacity to capture this packaging demand.
- Cloud Infrastructure Expansion:Naver and Kakao Enterprise are scaling GPU deployments for generative AI services. Pangyo Techno Valley hyperscalers account for concentrated procurement volume.
- K-Chips Act Incentives:Tax credits for fabless design houses are strengthening domestic semiconductor R&D. Foreign processor vendors face margin pressure from subsidized local competitors.
Market Restraints
- Advanced Node Concentration:Sub-3nm logic fabrication depends on a single non-Korean foundry source. Geopolitical export controls threaten supply continuity for leading-edge AI accelerators.
- HBM Supply Bottleneck:Memory-processor integration requires specialized TSV capacity concentrated among two domestic suppliers. Equipment lead times for advanced packaging tools exceed 18 months.
- Power Density Constraints:Thermal design power ratings above 700 watts are exceeding standard data center cooling infrastructure. Guro Digital Complex facilities require liquid cooling retrofits.
Strategic Opportunities
- Edge AI Deployment:Busan and Incheon smart city projects are creating demand for low-latency inference processors. Municipal data centers represent underpenetrated procurement channels.
- Chiplets Standardization:UCIe adoption is enabling heterogeneous integration of domestic memory with foreign logic dies. Korean packaging houses can capture value from disaggregated architectures.
- Carbon-Neutral Mandates:RE100 commitments by major cloud operators are prioritizing energy-efficient processor procurement. Domestic suppliers with advanced power management IP gain preferential positioning.
Industry Challenges
- Packaging Engineering Talent:CoWoS and 3D-IC design expertise is concentrated among a small cohort of senior engineers. Universities are struggling to scale advanced packaging curriculum output.
- Legacy x86 Migration Friction:Enterprise data centers in Gyeonggi Province face software stack recompilation costs when transitioning to ARM-based cloud instances. Compatibility testing timelines extend procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Processor Market |
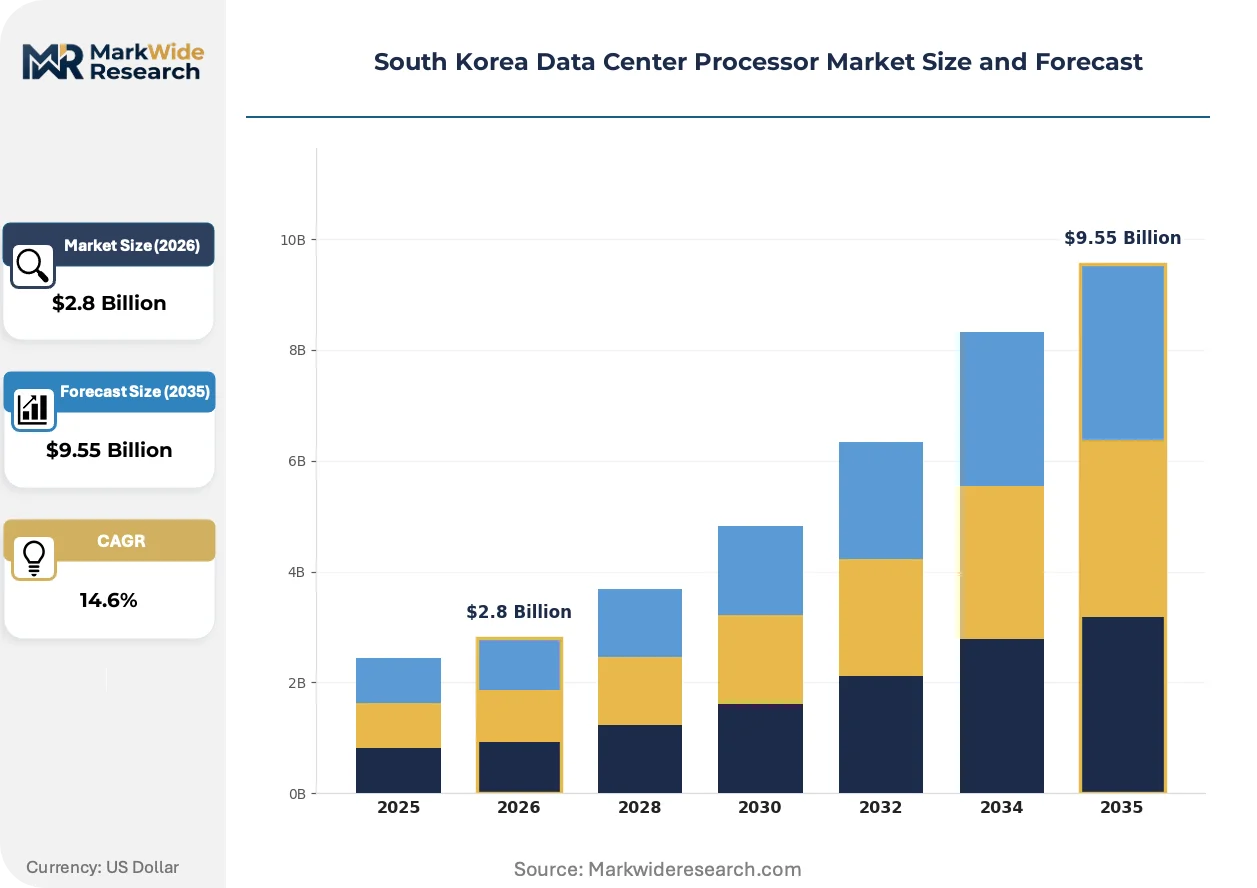
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPUs, GPUs, TPUs, FPGAs Application: Cloud Computing, Big Data Analytics, Machine Learning, Virtualization End User: Telecommunications, Financial Services, Healthcare, Education Form Factor: Blade, Rackmount, Microserver, Tower |
| Companies Covered | Ampere Computing, Rebellions, Intel Corporation, FuriosaAI, SAPEON, Advanced Micro Devices Inc., Samsung Electronics, SK Hynix, NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Processor Market Trends and Innovations
Silicon architecture is fragmenting into specialized accelerators as Korean hyperscalers optimize for workload-specific performance. Domestic suppliers are leveraging memory-process integration advantages to differentiate against foreign GPU incumbents.
Chiplet-based processor design is integrating heterogeneous dies through advanced packaging rather than monolithic integration. Naver's AI research division is adopting disaggregated architectures for training infrastructure. This approach is integrating domestic HBM supply with foreign logic dies while reducing dependency on single-foundry advanced nodes.
MFDS reliability standards for healthcare data center deployments are mandating extended burn-in testing for processors handling medical imaging workloads. Korean hospital systems are requiring supplier certification against these benchmarks. Medical AI startups in Seoul are selecting processors pre-qualified for clinical deployment to accelerate regulatory approval timelines.
Hyperscaler procurement is consolidating around direct foundry relationships rather than merchant silicon channels. Kakao Enterprise and Naver Cloud are negotiating wafer starts directly with TSMC and domestic foundries. This pattern is most visible in Pangyo Techno Valley, where vertical integration into upstream supply is compressing distributor margins and reshaping component vendor economics.
South Korea Data Center Processor Market Segmentation
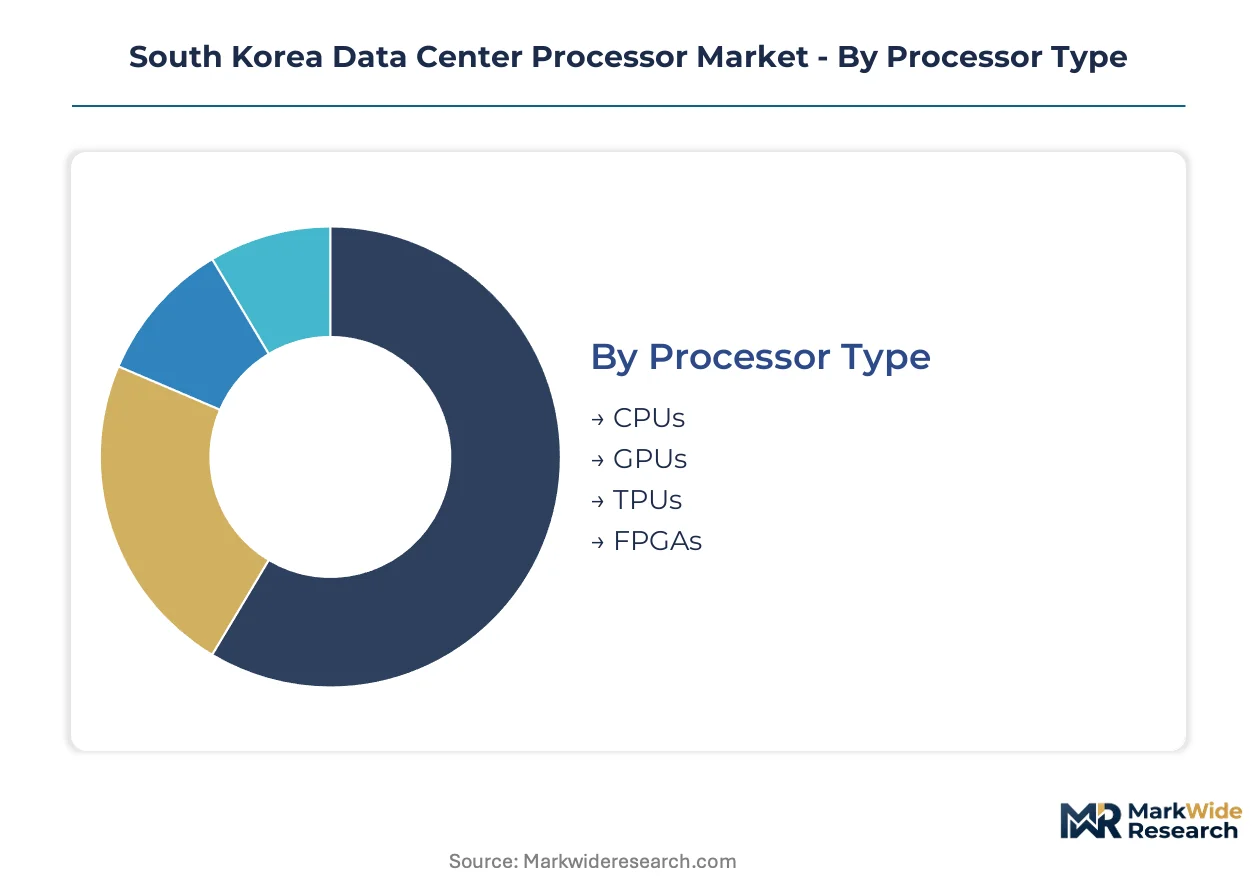
Processor segmentation in South Korean data centers reflects divergent workload optimization strategies. Cloud operators and enterprise facilities select architectures based on thermal constraints, software ecosystem compatibility, and memory bandwidth requirements specific to Seoul's Guro Digital Complex and Pangyo Techno Valley deployments.
Processor Type:
Upgrade cycles in Korean hyperscaler facilities are shortening as generative AI training intensity escalates, forcing procurement teams to balance backward compatibility against performance gains from novel architectures.
- CPUs:x86 and ARM-based general-purpose processors handle virtualization layers and control-plane operations in mixed-workload racks. Naver Cloud and Kakao Enterprise deploy these for legacy enterprise instance types across Gyeonggi Province facilities where software stack stability outweighs raw throughput.
- GPUs:Massively parallel tensor processors with HBM3E integration dominate AI training clusters. Demand concentrates in Pangyo Techno Valley where NVIDIA's architecture leadership meets domestic memory supplier packaging capabilities for reduced data movement latency.
- TPUs:Google's proprietary AI accelerators serve specific TensorFlow workloads through cloud rental models rather than direct procurement.
- FPGAs:Programmable logic devices enable telecommunications edge customization for 5G baseband processing in Busan municipal deployments.
CPUs sit at the top of the volume ranking, with GPUs climbing the fastest.
Application:
Cost tier differentiation separates premium AI training infrastructure from standardized virtualization deployments across Korean data center portfolios.
- Cloud Computing:General-purpose compute instances supporting SaaS and IaaS revenue models. Seoul-based operators prioritize energy efficiency metrics under RE100 commitments when selecting processors for multi-tenant racks.
- Big Data Analytics:High-memory-bandwidth processors executing distributed query engines across petabyte-scale datasets. Financial services clusters in Yeouido demand low-latency interconnects for real-time risk calculations.
- Machine Learning:Specialized training and inference silicon with mixed-precision arithmetic units. Korean AI startups in Pangyo favor domestic HBM-integrated solutions to reduce foundry dependency.
- Virtualization:Multi-core processors enabling server consolidation ratios that maximize facility utilization. Guro Digital Complex legacy facilities retain x86 dominance due to migration cost sensitivity.
Cloud Computing commands the largest installed base, while Machine Learning gains share fastest.
End User:
Customer type dictates certification requirements and procurement approval timelines, with regulated sectors imposing extended validation cycles.
- Telecommunications:KT and SK Telecom deploy edge-optimized processors for 5G network functions virtualization. Low-latency inference silicon in Busan and Incheon smart city nodes supports municipal AI services.
- Financial Services:Banking consortia in Yeouido mandate hardware security modules and deterministic execution for trading algorithms. Regulatory scrutiny from the Financial Supervisory Service extends procurement cycles for foreign-sourced accelerators.
- Healthcare:MFDS-certified processors handling medical imaging workloads require extended burn-in testing. Seoul hospital systems select pre-qualified silicon to accelerate clinical AI deployment approvals.
- Education:Research universities operate training clusters with subsidized domestic processors under K-Chips Act incentives. KAIST and POSTECH facilities serve as testbeds for novel memory-compute architectures.
Telecommunications leads by deployment volume, with Healthcare expanding most quickly on regulatory tailwinds.
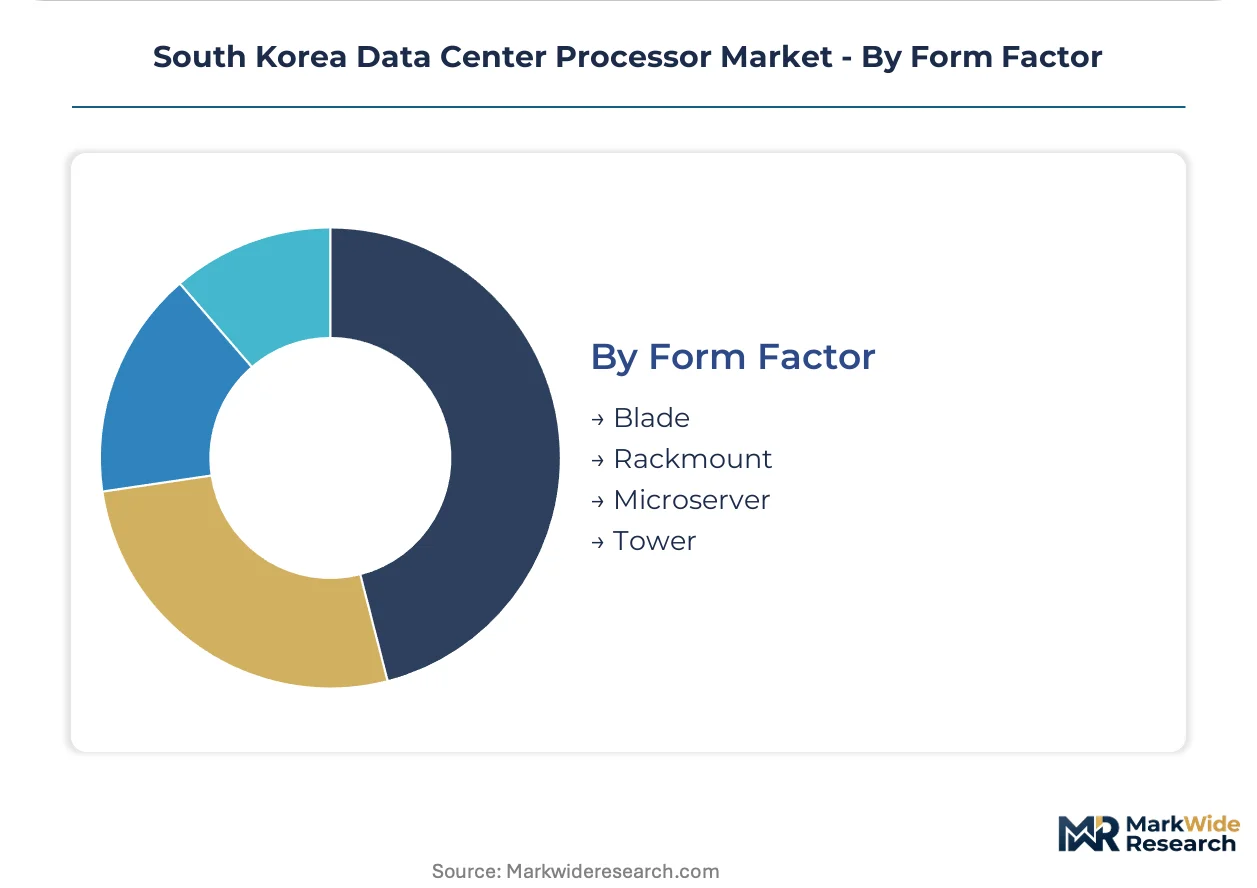
Form Factor:
Physical packaging constraints interact directly with Seoul's limited data center real estate and legacy facility cooling limitations.
- Blade:High-density modular servers maximizing rack-unit efficiency in premium Pangyo facilities. Liquid cooling integration becomes mandatory as thermal design power exceeds 700 watts per processor.
- Rackmount:Standard 19-inch enclosures dominating enterprise and mid-market deployments. Guro Digital Complex operators face retrofit costs when upgrading to liquid-cooled variants.
- Microserver:Compact single-socket designs for edge and distributed computing nodes. Incheon port logistics centers deploy these for localized inference with minimal footprint.
- Tower:Standalone configurations limited to development environments and small-scale on-premise installations.
Rackmount maintains volume leadership, with Blade showing the steepest expansion trajectory on density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping processor procurement across East Asian data center clusters, with compliance-cost differentials between jurisdictions accelerating facility location decisions and silicon sourcing patterns.
Seoul Capital Area
Pangyo Techno Valley hyperscalers Naver and Kakao Enterprise are scaling GPU deployments for generative AI training clusters. The K-Chips Act provides tax credits for fabless design houses locating R&D facilities in Gyeonggi Province. Guro Digital Complex legacy operators face liquid cooling retrofit costs as thermal design power ratings exceed 700 watts per processor.
Busan-Ulsan
Smart city infrastructure projects are generating demand for low-latency edge inference processors in municipal data centers. KT and SK Telecom deploy 5G network functions virtualization requiring programmable logic flexibility. The Busan Digital Innovation Park serves as a testbed for telecommunications-optimized silicon architectures.
Daejeon-Sejong
KAIST and POSTECH research facilities operate training clusters with subsidized domestic processors under national semiconductor programs. Government data center consolidation in Sejong City prioritizes energy-efficient procurement under public sector RE100 commitments. The Daedeok Innopolis cluster anchors advanced packaging R&D for memory-compute integration.
Daegu-Gyeongbuk
Industrial automation demand from manufacturing conglomerates drives edge processor deployment in private data centers. The region's textile and machinery sectors require deterministic execution for real-time quality control systems. Daegu Technopolis hosts specialized facilities for automotive AI inference workloads.
South Korea Data Center Processor Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic foundries race to capture advanced packaging demand from AI-optimized silicon. The vendor base separates into three tiers: foreign GPU incumbents with architecture leadership, domestic memory suppliers leveraging HBM integration advantages, and emerging fabless design houses benefiting from K-Chips Act subsidies. Strategic archetypes include vertically integrated memory-logic specialists, pure-play AI accelerator vendors, and legacy x86 ecosystem providers. Competitive moves concentrate on foundry partnership negotiations and CoWoS-equivalent capacity reservations.
Within the domestic accelerator tier, Rebellions and FuriosaAI exemplify the fabless design house model capitalizing on national subsidy programs. NVIDIA Corporation anchors the foreign incumbent position through GPU architecture dominance in training workloads. Samsung Electronics occupies the integrated memory-processor convergence space, leveraging HBM supply chain control to differentiate against merchant silicon competitors.
| Leading Market Players |
|---|
| Ampere Computing |
| Rebellions |
| Intel Corporation |
| FuriosaAI |
| SAPEON |
| Advanced Micro Devices Inc. |
| Samsung Electronics |
| SK Hynix |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Advanced photoresist formulations from Japanese specialty chemical producers flow through foundry procurement contracts into tiered processor pricing structures, with sub-3nm lithography material costs concentrating margin pressure on premium AI accelerator tiers while legacy node CPUs absorb volume discounts through long-term hyperscaler offtake agreements.
Pricing Analysis
Distributor margins compress as Pangyo Techno Valley hyperscalers negotiate direct foundry relationships, bypassing traditional component channels. Three-tier pricing structure across premium AI training accelerators, standard virtualization CPUs, and economy edge inference chips reflects HBM integration depth and thermal design power ratings. Pricing pressure stems from K-Chips Act subsidies enabling domestic fabless competitors to undercut foreign GPU incumbents on comparable performance tiers. Enterprise data centers in Gyeonggi Province exhibit highest price sensitivity due to legacy x86 migration friction, while Naver Cloud and Kakao Enterprise prioritize performance-per-watt over unit cost in training cluster procurement.
Supply Chain Analysis
EUV lithography equipment supply rests on Dutch and Japanese capital equipment producers, creating single-source vulnerability for sub-3nm logic fabrication. Silicon wafers draw from Japanese and German substrate specialists, while HBM3E memory supply centers on Samsung Electronics and SK Hynix domestic packaging capacity. Tariff exposure on advanced packaging tools with 18-month equipment lead times threatens CoWoS-equivalent capacity expansion timelines. Distribution runs through direct foundry negotiations rather than merchant silicon channels, compressing traditional semiconductor distributor economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
K-Chips Act tax credits create procurement cost arbitrage between domestic fabless design houses and foreign GPU incumbents, with Gyeonggi Province R&D facility location decisions offering 15-25% effective cost differentials against non-subsidized competitors.
For Market Incumbents: Cement architecture leadership through exclusive HBM3E supply agreements with Samsung Electronics and SK Hynix, locking in memory-processor integration advantages before domestic competitors scale CoWoS-equivalent capacity. Prioritize liquid cooling certification partnerships with Guro Digital Complex operators to defend positioning as thermal design power ratings exceed 700 watts. Counter K-Chips Act-subsidized entrants by accelerating software ecosystem lock-in through TensorFlow and PyTorch optimization layers. For New Entrants and Emerging Players: Enter via Busan and Incheon smart city edge AI deployments, where municipal procurement channels remain underpenetrated by foreign GPU incumbents and latency requirements favor low-power inference accelerators. Target telecommunications 5G network functions virtualization segments where programmable logic flexibility commands premium pricing. Pursue K-Chips Act certification early to unlock hyperscaler pilot programs with Naver Cloud and Kakao Enterprise. For Investors and Strategic Acquirers: Roll-up economics work for advanced packaging engineering specialists because CoWoS and 3D-IC design expertise concentrates among a small cohort of senior engineers with limited university pipeline replacement. Platform consolidation around memory-logic integration capabilities offers 5-10 year viability as chiplet architectures displace monolithic silicon. Watch for MFDS healthcare processor certification milestones as inflection indicators for medical AI startup procurement channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS-Equivalent Capacity Expansion | Domestic foundries capture advanced packaging demand from AI-optimized silicon architectures. |
| HBM3E Supply Agreement | Samsung Electronics and SK Hynix secure logic die partnerships through memory bandwidth differentiation. |
| Liquid Cooling Retrofit Partnership | Guro Digital Complex operators address 700-watt thermal design power infrastructure constraints. |
| K-Chips Act Certification | Fabless design houses unlock tax credits and hyperscaler pilot program access. |
| MFDS Pre-Qualification | Processor vendors accelerate Seoul hospital system clinical AI deployment approvals. |
Research Methodology
Coverage spans Seoul Capital Area, Busan-Ulsan, Daejeon-Sejong, and Daegu-Gyeongbuk clusters, with primary inputs from each combining hyperscaler procurement executives, foundry operations directors, fabless design house CTOs, and advanced packaging engineering leads with secondary validation against SEC filings, hyperscaler capex disclosures, and MFDS regulatory filings. Bottom-up processor shipment estimates triangulate against top-down data center infrastructure investment flows.
Rate-of-change decomposition separates volume expansion from value migration across the analysis window, modeling processor type, application workload, end-user vertical, and form factor density dimensions. CAGRs derive from segment-level growth rate blending weighted by installed base evolution. Forecast inputs incorporate K-Chips Act subsidy phase-in assumptions and CoWoS-equivalent capacity buildout timelines from domestic foundry disclosures.
Inputs from hyperscaler procurement executives and foundry operations directors were available through the study window; gaps in specific K-Chips Act implementation guidance introduce uncertainty bands around domestic fabless market share trajectories. Forecasts reflect assumptions on advanced node export control continuity and HBM supply bottleneck resolution. A small set of triggers—MFDS certification milestone acceleration, RE100 commitment tightening, and sub-3nm foundry diversification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market