
 X86 Architecture CPU Market | 2026-2036
X86 Architecture CPU Market Size, Share, and Industry Trends Forecast 2026-2036
X86 Architecture CPU Market Insights
Taiwan's advanced packaging capacity build-out is reshaping supply security for high-performance x86 processors. Intel Corporation sustains its foundry ambitions through aggressive process node transitions and U.S. fab commitments. AMD differentiates via chiplet architectures that optimize yield and cost across server and client segments. Shanghai Zhaoxin Semiconductor Co., Ltd. anchors China's sovereign compute agenda with indigenous x86-compatible designs.
The x86 architecture CPU is a complex instruction set computing (CISC) processor built on the x86 instruction set architecture originally developed by Intel, featuring 64-bit address spaces, out-of-order execution pipelines, and transistor counts exceeding tens of billions on advanced process nodes. Its primary purpose is to execute general-purpose computing workloads across personal computers, enterprise servers, and embedded systems with broad software compatibility. Server CPUs command the dominant value pool as cloud hyperscalers and enterprise data centers prioritize core density and memory bandwidth for virtualization and AI inference. Mobile CPUs face margin compression from ARM-based alternatives in thin-client devices, though integrated graphics and turbo boost technologies preserve relevance in premium laptops. Embedded CPUs occupy a specialized niche in industrial control and network appliances where legacy software ecosystems resist migration.
The U.S. Department of Commerce export controls restrict advanced x86 manufacturing equipment to certain Chinese fabs, compressing process node advancement for regionally focused vendors. China's MIIT mandates domestic x86 adoption in government procurement through security review catalogs and preferential tender scoring. The EU Chips Act and F-Gas Regulation collectively push for localized wafer fabrication while constraining fluorinated gas use in etching processes. Stakeholders must monitor how sovereign compute mandates and equipment access restrictions bifurcate the x86 supply chain into parallel technology tiers.
Market Dynamics
The x86 CPU market is bifurcating into parallel technology tiers as sovereign compute mandates and equipment access restrictions force divergent supply chain configurations across major economies.
Growth Catalysts
- Generative AI server buildouts:Cloud hyperscalers are expanding x86 deployments to support large language model inference workloads, driving core density requirements upward.
- CHIPS and Science Act incentives:U.S. domestic fab investments are redirecting capital toward onshore advanced node capacity for strategic processor supply security.
- MIIT procurement mandates:China's security review catalogs and preferential tender scoring accelerate domestic x86 adoption across government and state-owned enterprise compute infrastructure.
Market Restraints
- EUV lithography equipment access:U.S. Department of Commerce export controls restrict advanced manufacturing tools to certain Chinese fabs, compressing process node advancement for regional vendors.
- Fluorinated gas constraints:The EU F-Gas Regulation limits etching chemistry availability, raising production costs for European wafer fabrication.
- ARM-based substitution in thin clients:Power-efficient RISC architectures are capturing premium laptop volume, pressuring x86 mobile CPU margins.
Strategic Opportunities
- Advanced packaging capacity expansion:Taiwan's substrate and interposer build-out creates captive supply security for high-performance x86 processor assembly.
- Chiplet architecture adoption:Modular die designs enable yield optimization and cost reduction across heterogeneous server and client product stacks.
- Industrial embedded retention:Legacy software ecosystems in network appliances and control systems resist migration, preserving long-tail demand for established x86 embedded SKUs.
Industry Challenges
- Process node transition cadence:Aggressive roadmap execution demands sustained R&D intensity as transistor scaling economics tighten.
- Cross-border IP licensing complexity:x86 instruction set cross-licensing arrangements face renegotiation pressure amid geopolitical technology segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X86 Architecture CPU Market |
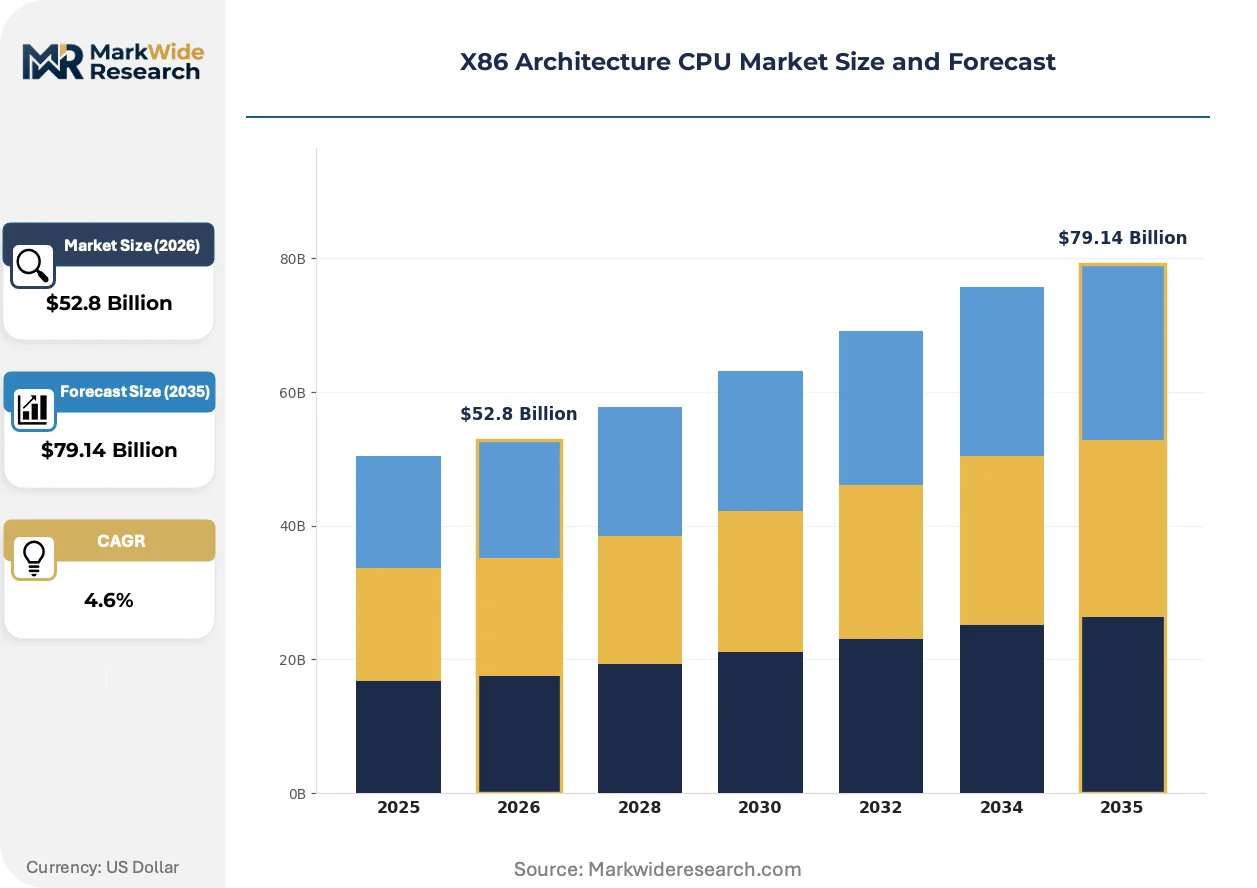
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop CPUs, Server CPUs, Mobile CPUs, Embedded CPUs End User: Gaming Enthusiasts, Data Centers, OEMs, Retail Consumers Technology: Multi-Core, Turbo Boost, Integrated Graphics, Hyper-Threading Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Shanghai Zhaoxin Semiconductor Co., Ltd., Nvidia Corporation, Intel Corporation, Qualcomm Technologies Incorporated, IBM Corporation, AMD, VIA Technologies, NXP Semiconductors, HYGON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X86 Architecture CPU Market Trends and Innovations
Three forces are actively restructuring how x86 processors are designed, manufactured, and procured: die disaggregation, environmental chemistry constraints, and hyperscaler vertical integration.
Chiplet-based multi-die integration is collapsing the traditional monolithic CPU design paradigm. AMD and Intel are disaggregating memory controllers, I/O, and compute cores onto separate tiles connected via high-bandwidth interconnects. Cloud hyperscalers are qualifying these architectures for AI training clusters, compressing time-to-market for new process nodes while enabling mix-and-match performance tiers.
REACH and the EU F-Gas Regulation are tightening chemistry availability for semiconductor etching and cleaning processes. The industrial consequence is accelerated process engineering for alternative chemistries and localized gas recycling infrastructure. European fabs are most affected, with capacity expansion timelines extending as suppliers qualify F-gas alternatives for critical EUV lithography steps.
Hyperscalers are internalizing CPU specification and validation workflows previously managed through OEM intermediaries. Microsoft, Amazon Web Services, and Google Cloud are issuing direct silicon requirements to foundries, compressing traditional server vendor design cycles. This pattern is most visible in North American cloud infrastructure procurement, where custom SKU volumes now rival commercial off-the-shelf server CPU shipments.
X86 Architecture CPU Market Segmentation
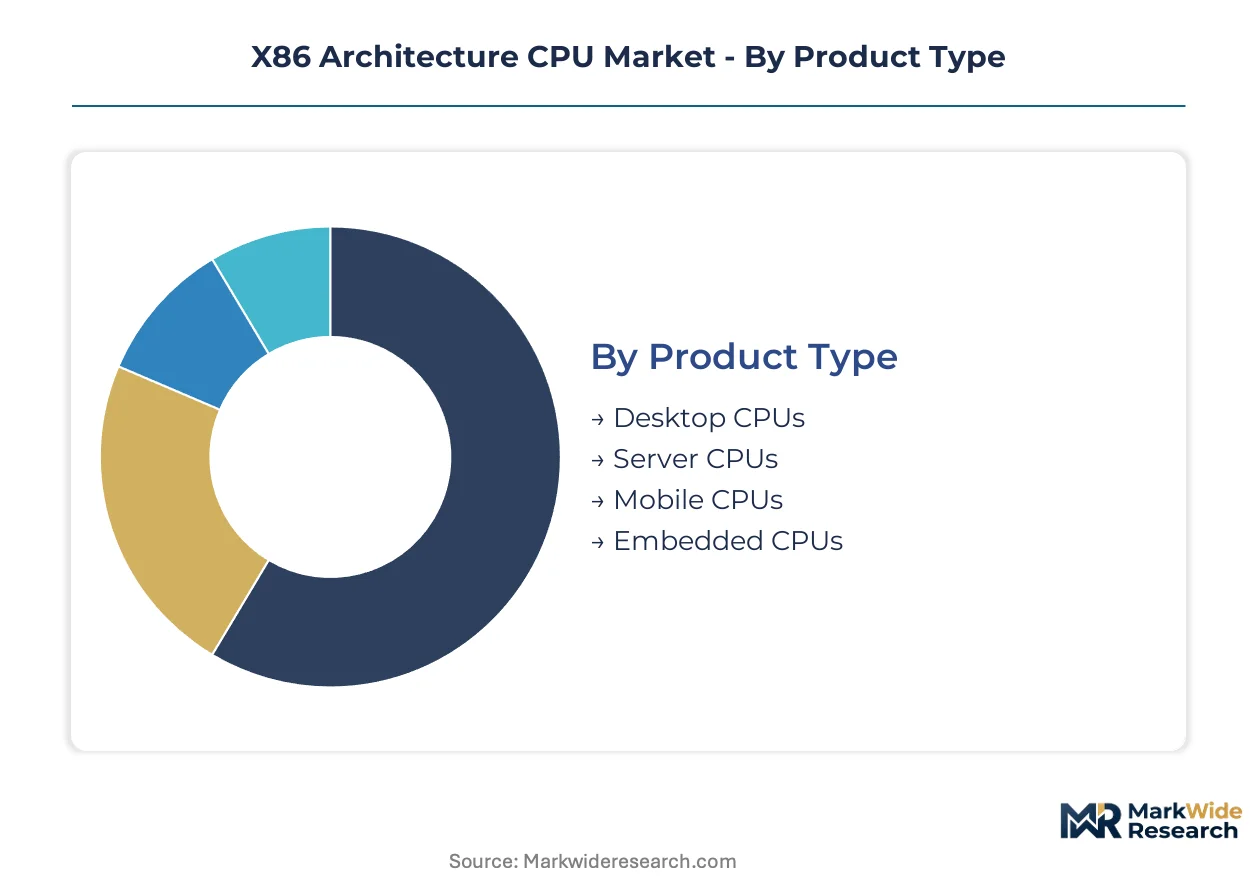
X86 CPU purchasing patterns diverge sharply across workload types and infrastructure ownership models. Cloud hyperscalers negotiate directly with foundries for custom silicon, while embedded buyers prioritize decade-long software compatibility over raw performance.
Product Type:
Cost tier separates these four processor categories, with server silicon commanding premium pricing and embedded units trading margin for longevity.
- Desktop CPUs:These processors emphasize single-threaded frequency headroom and unlocked multipliers for enthusiast overclocking. Gaming enthusiasts in the United States and Western Europe drive refresh cycles, with DDR5 memory adoption pushing platform upgrades.
- Server CPUs:High core densities and massive L3 caches dominate designs for virtualization and AI inference. Data centers in Virginia, Frankfurt, and Singapore absorb the majority of high-margin Xeon and EPYC shipments as generative AI workloads expand.
- Mobile CPUs:Thermal design power constraints below 28W govern these compact dies with integrated graphics. Thin-and-light laptop OEMs specify these for corporate fleet deployments where battery endurance outweighs absolute performance.
- Embedded CPUs:Industrial temperature ratings and guaranteed availability windows extending ten years define this category. Network appliance manufacturers and programmable logic controller vendors in Germany and Japan specify these for infrastructure with decades-long service horizons.
Server CPUs hold installed capacity. Embedded CPUs are rotating up the share rankings as industrial automation retrofits accelerate.
End User:
Customer type determines procurement channel and specification depth, from direct foundry relationships to retail box shipments.
- Gaming Enthusiasts:Individual buyers prioritize frame rates in AAA titles and streaming encode performance. Online retailers in South Korea and the United States move high-margin unlocked SKUs with bundled cooling solutions.
- Data Centers:Hyperscale operators validate custom stepping codes for their thermal and power envelopes. Microsoft, Amazon Web Services, and Google Cloud issue direct silicon requirements that bypass traditional server OEM design cycles.
- OEMs:System integrators balance bill-of-materials cost against performance segmentation for corporate and consumer product lines. Taiwanese and Chinese contract manufacturers negotiate quarterly pricing adjustments based on wafer allocation forecasts.
- Retail Consumers:Mainstream buyers respond to marketing frequency specifications and core count visibility. Big-box electronics chains in India and Brazil stock boxed processors with bundled stock coolers for DIY assembly markets.
Data centers dominate absolute volume. Gaming enthusiasts are expanding most quickly as livestreaming and esports participation broadens.
Technology:
Functional differentiation through silicon features creates pricing tiers and workload specialization.
- Multi-Core:Die area allocation toward parallel execution units enables throughput scaling for rendering and compilation. Cloud providers specify 64-core and 96-core configurations for container density in Frankfurt and Singapore facilities.
- Turbo Boost:Dynamic frequency elevation above base clocks responds to thermal headroom for bursty workloads. Financial trading floors in London and Chicago demand sustained turbo residency for latency-sensitive applications.
- Integrated Graphics:On-die GPU clusters eliminate discrete card requirements for office productivity and video playback. Corporate fleet buyers in Japan and Germany specify these for docked laptop configurations to simplify inventory.
- Hyper-Threading:Simultaneous multithreading exposes two logical cores per physical execution unit to the operating system. Virtualization hosts in Virginia data centers license software per-core and exploit this density for license optimization.
Multi-Core holds installed capacity. Turbo Boost is rotating up the share rankings as single-threaded performance becomes a competitive battleground.
Deployment:
Infrastructure ownership and physical location of compute create distinct procurement and operational patterns.
- On-Premises:Enterprise-owned facilities maintain direct control over hardware refresh timing and security boundaries. German automotive manufacturers and Japanese banks retain these for regulatory compliance with data residency mandates.
- Cloud-Based:Third-party operated hyperscale facilities deliver elastic capacity without capital expenditure. Software-as-a-service vendors in California and Washington state consume these for variable workload scaling.
- Hybrid:Orchestrated workloads span owned and rented infrastructure based on sensitivity and burst requirements. European pharmaceutical companies deploy these for clinical trial data processing with regulatory-controlled on-premise components.
- Edge Computing:Distributed micro-datacenters position compute within 10 milliseconds of endpoints for latency-critical applications. Telecommunications providers in South Korea and the United States install these for autonomous vehicle infrastructure and smart factory networks.
Cloud-Based holds installed capacity. Edge Computing is climbing the fastest as 5G network densification and industrial IoT deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT procurement mandates anchor the dominant geography. The U.S. CHIPS and Science Act redirects foundry investments toward domestic capacity. EU F-Gas Regulation constrains etching chemistry availability for regional fabrication.
United States
Cloud hyperscalers in Virginia and Washington state drive server CPU procurement for AI inference clusters. The CHIPS and Science Act channels subsidies toward onshore advanced node fabrication. Intel Corporation sustains foundry commitments in Arizona and Ohio for sovereign processor supply security.
China
State-owned enterprises and government data centers accelerate x86 adoption under security review catalogs. MIIT mandates domestic CPU preference through preferential tender scoring. Shanghai Zhaoxin Semiconductor anchors indigenous design capabilities in the Yangtze River Delta for import substitution.
Germany
Automotive manufacturers and industrial automation vendors demand embedded CPUs with decade-long availability guarantees. The EU F-Gas Regulation limits fluorinated gas use in etching processes. Bavaria's semiconductor cluster extends capacity timelines as suppliers qualify alternative chemistries for EUV lithography.
Taiwan
Advanced packaging capacity build-out secures substrate and interposer supply for high-performance processor assembly. The island's foundry ecosystem serves cloud hyperscaler custom silicon programs. Hsinchu Science Park concentrates die disaggregation and chiplet integration expertise for AMD and Intel roadmaps.
South Korea
Telecommunications providers deploy edge computing infrastructure for autonomous vehicle networks and smart factories. MFDS coordinates with industrial regulators on semiconductor manufacturing standards. Seoul Capital Area fabs expand advanced packaging capacity to capture x86 assembly demand from U.S. cloud customers.
X86 Architecture CPU Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The x86 CPU market consolidates around instruction set licensees with multi-decade software ecosystem entrenchment. Three archetypes dominate: sovereign compute specialists serving government procurement mandates, hyperscale foundry partners delivering custom silicon, and legacy embedded suppliers preserving industrial software compatibility. Competitive moves center on process node transition cadence and advanced packaging capacity capture.
Within the sovereign compute tier, Shanghai Zhaoxin Semiconductor Co., Ltd. represents China's indigenous x86-compatible design agenda. Among U.S.-based incumbents, Intel Corporation and AMD occupy positions spanning client, server, and custom silicon segments. These three entities exemplify how instruction set licensing, foundry access, and government procurement alignment determine competitive positioning.
| Leading Market Players |
|---|
| Shanghai Zhaoxin Semiconductor Co., Ltd. |
| Nvidia Corporation |
| Intel Corporation |
| Qualcomm Technologies Incorporated |
| IBM Corporation |
| AMD |
| VIA Technologies |
| NXP Semiconductors |
| HYGON |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Taiwan's advanced packaging substrate lines is driving foundry pricing power and hyperscaler procurement urgency simultaneously. This utilization squeeze concentrates margin capture with TSMC and ASE Holdings while forcing cloud buyers into multi-year offtake commitments.
Pricing Analysis
Geographic price spreads between U.S. and Chinese x86 procurement have widened as MIIT mandates compress import substitution premiums domestically. Pricing stratifies across premium server, standard client, and economy embedded tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in mobile CPUs is intensifying because ARM-based alternatives capture thin-client share. Data centers exhibit lowest price sensitivity due to performance-per-watt optimization priorities, while retail consumers remain most responsive to core-count marketing.
Supply Chain Analysis
Contract manufacturing concentration rests with TSMC, Samsung Foundry, and Intel's internal fabs for leading-edge x86 wafer production. Taiwan, South Korea, and the United States anchor geographic supply concentration for advanced node capacity. Raw material dependencies draw from high-purity silicon wafers, EUV photoresists, and fluorinated etching gases. Single-source vulnerability in EUV lithography equipment creates structural risk given ASML's monopoly position. Distribution runs through direct foundry relationships for hyperscalers and OEM-mediated channels for client and embedded segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as ARM-based server CPUs gain cloud qualification traction. The architecture threat demands ecosystem lock-in reinforcement and performance-per-watt acceleration.
For Market Incumbents: Harden instruction set ecosystem entrenchment through compiler optimization investments and legacy software compatibility guarantees. Accelerate chiplet architecture roadmaps to maintain yield advantages against monolithic ARM competitors. Foundry capacity addition in Arizona and Ohio reduces Taiwan concentration risk. For New Entrants and Emerging Players: China's government procurement whitespace offers the most penetrable entry vector under MIIT domestic preference scoring. Industrial embedded segments in Germany and Japan present second-tier targets with decade-long availability requirements. Direct tender participation with security certification pre-qualification represents the optimal go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced packaging sub-segments as substrate and interposer capacity becomes bottlenecked. Long-term viability centers on sovereign compute alignment and foundry access security. Acquisition targets should display captive packaging partnerships or government procurement channel entrenchment. The signal to watch is EUV equipment licensing scope expansion for China-focused vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Transition | AMD and Intel roadmaps disaggregate monolithic dies to optimize yield across process nodes. |
| Advanced Packaging Capacity Expansion | Taiwan's substrate build-out secures interposer supply for high-bandwidth x86 processor assembly. |
| Sovereign Compute Certification | MIIT security review catalogs create preferential procurement channels for indigenous x86 designs. |
| Direct Foundry Relationships | Hyperscalers bypass OEM intermediaries to specify custom silicon for AI inference clusters. |
| Process Node Transition Acceleration | Intel's Arizona and Ohio commitments advance domestic EUV capacity for strategic supply security. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and foundry utilization reports anchors the qualitative findings in this study. Primary interviews with cloud infrastructure procurement officers, semiconductor foundry account managers, OEM platform engineers, and government IT procurement directors combined with secondary validation from SEC 10-K filings, EIA power consumption data, and customs trade records. Bottom-up and top-down triangulation reconciles unit shipment estimates with revenue aggregation across the analysis window.
Calibration against historical capacity expansion cycles and process node transition timelines informs the projection framework. Segmentation dimensions modeled include product type, end user archetype, deployment model, and regional regulatory cluster throughout the forecast period. CAGRs derive from elasticity-adjusted demand curves and supply-side capacity constraints. EUV equipment licensing scope and CHIPS Act subsidy disbursement trajectories serve as industry-specific forecast inputs.
Practitioners should monitor EUV equipment export control scope revisions and MIIT procurement catalog updates for early signals of supply chain bifurcation acceleration. Forecasts reflect assumptions regarding foundry yield maturation and sovereign compute mandate enforcement intensity. Cross-checking against hyperscaler custom silicon disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Connecting Chiplets Market