
 Europe 8- Bit Microcontroller Market | 2026-2036
Europe 8- Bit Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 8- Bit Microcontroller Market Foresight
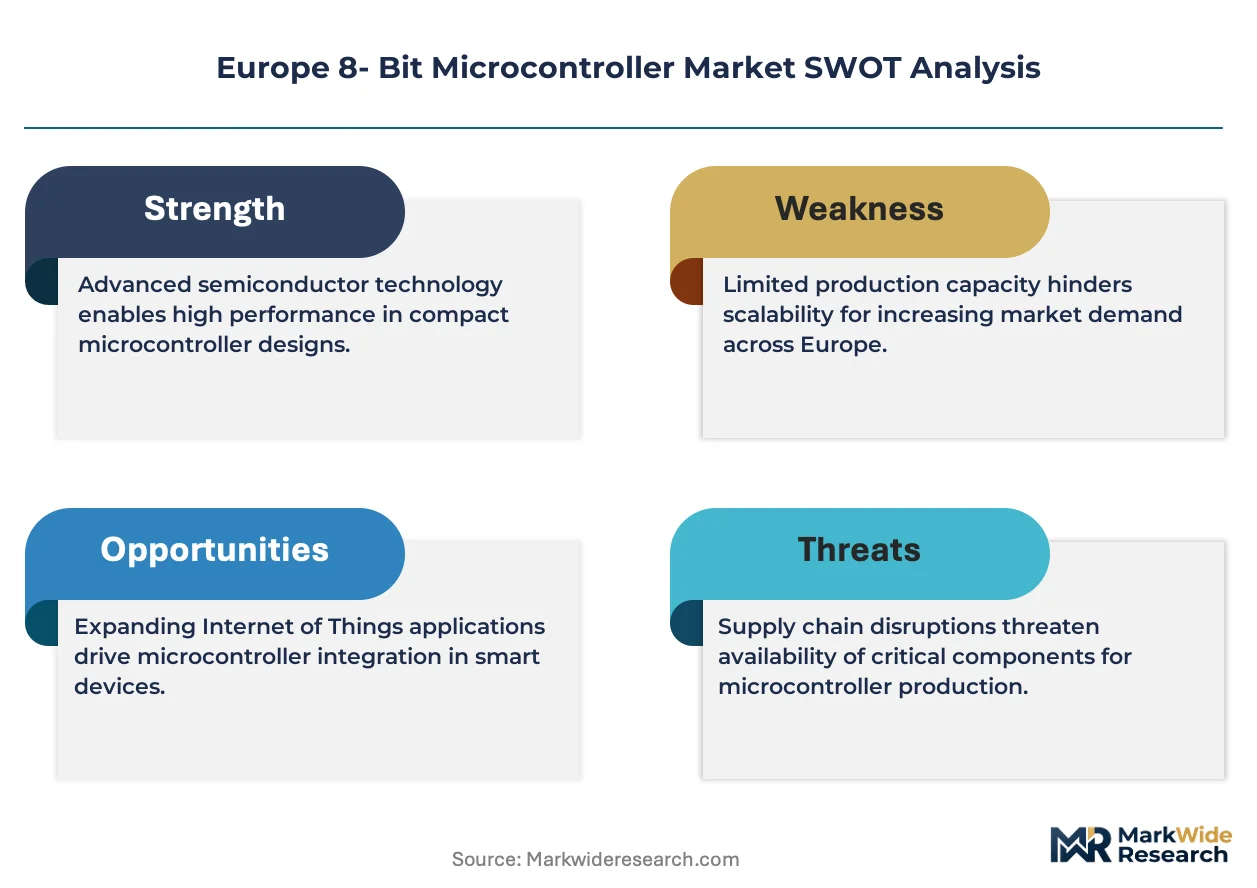
The EU Green Deal is rebalancing procurement criteria across European industrial supply chains. Infineon Technologies AG leverages its Dresden fabrication complex to sustain captive wafer supply for automotive-grade 8-bit units. STMicroelectronics N.V. dominates the mixed-signal segment through its Grenoble design center. NXP Semiconductors N.V. anchors its European operations with Eindhoven-based automotive microcontroller development.
An 8-bit microcontroller integrates an 8-bit central processing unit with embedded memory and programmable input-output peripherals on a single silicon die, typically operating at clock speeds below 40 MHz with flash memory capacities ranging from 2 KB to 256 KB. These devices execute real-time control tasks in cost-constrained applications where computational throughput requirements remain modest. The embedded product type category captures the largest volume share as appliance and automotive Tier-1 suppliers specify factory-programmed units for motor control and sensor interfacing. Mixed-signal technology commands the strongest margin pool by combining analog-to-digital converters with digital cores, eliminating discrete component counts in space-restricted designs. Industrial automation end users drive replacement cycles as legacy equipment retrofits demand pin-compatible 8-bit upgrades with extended temperature ratings.
REACH compliance and RoHS substance restrictions constrain material selections for European-bound microcontroller packaging and lead-free solder interfaces. The CE marking directive mandates electromagnetic compatibility testing for development boards and integrated modules sold into EU member states. ECHA substance-of-very-high-concern listings are expanding scrutiny of halogenated flame retardants in epoxy molding compounds. Stakeholders must monitor how the EU AI Act's risk-classification framework eventually propagates into embedded system documentation requirements for edge devices with deterministic control loops.

Market Dynamics
Automotive electrification is compressing development cycles across European Tier-1 supplier networks, forcing microcontroller vendors to synchronize roadmaps with powertrain integration timelines.
Growth Catalysts
- EU Green Deal energy mandates:Embedded efficiency requirements for industrial motor drives are expanding addressable unit volumes in German and Italian manufacturing clusters.
- Automotive sensor proliferation:Battery management systems and thermal monitoring nodes per vehicle are multiplying specified 8-bit unit counts.
- REACH substance compliance:Lead-free packaging mandates are accelerating replacement cycles for legacy equipment across European industrial automation corridors.
Market Restraints
- Wafer supply concentration:Dresden and Eindhoven fabrication complexes face input bottlenecks for automotive-qualified process nodes.
- 32-bit unit substitution:Cost-compressed ARM Cortex-M0 cores are encroaching on traditional 8-bit socket positions in appliance controllers.
- ECHA SVHC listings:Expanding scrutiny of halogenated flame retardants is constraining epoxy molding compound formulations for high-temperature automotive grades.
Strategic Opportunities
- Eastern European industrial retrofit:Polish and Czech automotive component plants are specifying pin-compatible 8-bit upgrades for legacy equipment modernization.
- EU AI Act documentation:Risk-classification frameworks for deterministic edge control loops will create premium documentation service revenue streams.
- Mixed-signal convergence:Integration of precision analog-to-digital converters with digital cores is eliminating discrete component counts in space-constrained medical device designs.
Industry Challenges
- Embedded firmware talent scarcity:Assembly-level optimization expertise for sub-40 MHz architectures is concentrating among aging specialist cohorts.
- CE marking timeline compression:Electromagnetic compatibility testing bottlenecks for development boards are extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 8- Bit Microcontroller Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.27 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Embedded, Development Board Technology: Analog, Digital, Mixed Signal, Microcontroller Unit End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Application: Home Appliances, Robotics, Wearable Devices, Medical Equipment |
| Companies Covered | Infineon Technologies AG, STMicroelectronics N.V., NXP Semiconductors N.V., Renesas Electronics Corporation, Microchip Technology Inc., Texas Instruments Incorporated, Silicon Laboratories Inc., Holtek Semiconductor Inc., Analog Devices Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 8- Bit Microcontroller Market Shifts & Advancements
Integration density and regulatory documentation requirements are restructuring how European microcontroller vendors allocate R&D resources across process nodes.
Smart analog peripherals are unifying sensor interface functions previously requiring discrete operational amplifiers and comparators. Automotive battery management system designers are adopting these integrated front-ends to reduce component counts. This unification is compressing bill-of-materials costs for Tier-1 suppliers while tightening vendor qualification timelines.
REACH substance restrictions are expanding documentation obligations for halogen-free epoxy molding compounds in automotive-grade packaging. European chemical agency listings are forcing reformulation of flame-retardant systems. German industrial automation OEMs are responding by consolidating supplier qualification pools to pre-certified packaging houses.
Factory-programmed procurement is displacing field-programmable unit purchases among large appliance manufacturers. Volume buyers are negotiating captive mask-ROM commitments to secure supply allocation. This pattern is most visible in Italian white-goods manufacturing clusters where single-source qualification reduces incoming inspection overhead.
Europe 8- Bit Microcontroller Market Segmentation
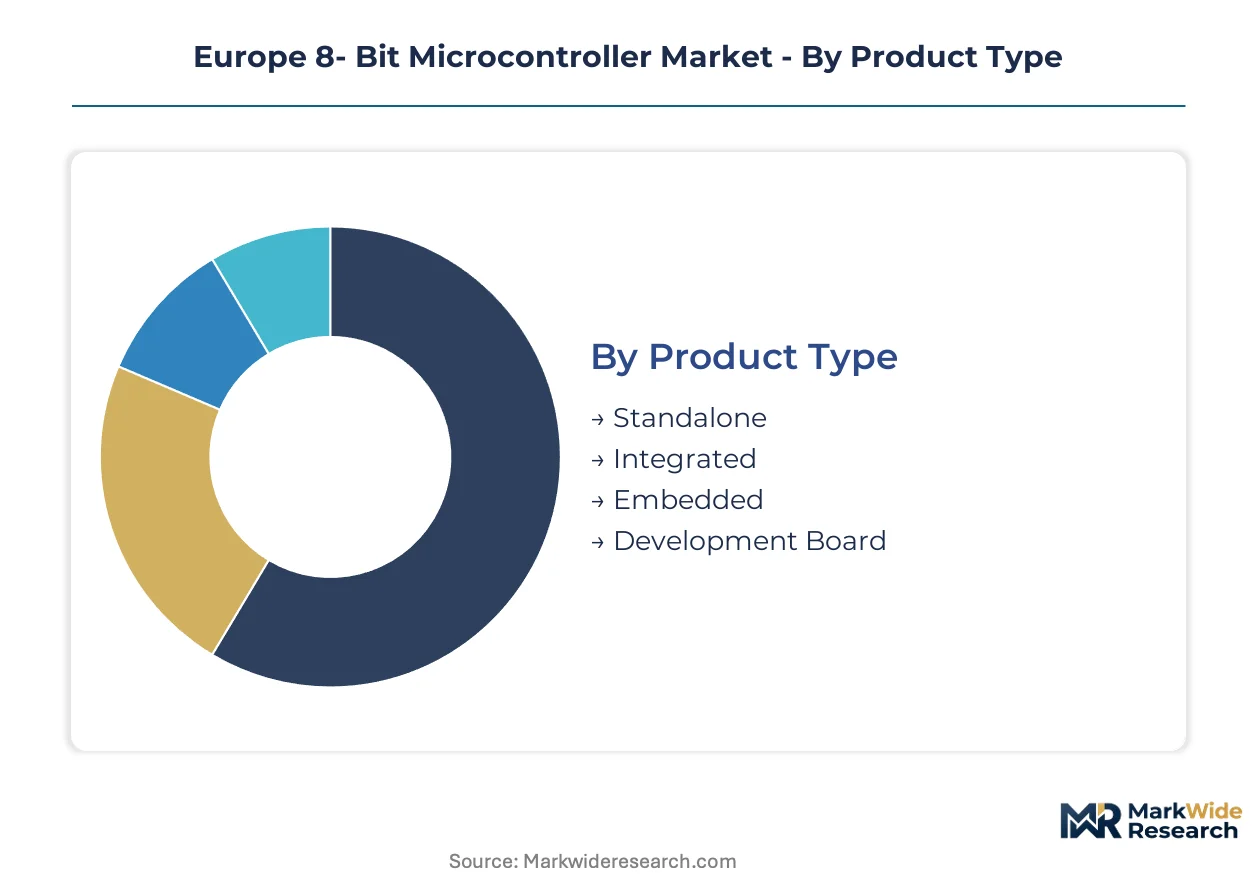
8-bit microcontroller procurement patterns in Europe diverge sharply between high-volume appliance contracts and premium automotive qualification programs. Segmentation reveals how packaging standards, analog integration levels, and temperature ratings partition addressable wallet across German industrial corridors and Italian manufacturing clusters.
Product Type:
Volume applications favor captive-programmed units while development flexibility sustains board-level purchases.
- Embedded:Factory-programmed units integrate flash memory below 256 KB with deterministic real-time kernels for motor control. German automotive Tier-1 suppliers specify these for battery management nodes to reduce field failure rates under extended temperature ratings.
- Standalone:Discrete 8-bit processors require external memory controllers and peripheral support chips. Polish and Czech industrial retrofit projects specify these for legacy equipment upgrades where pin compatibility overrides integration density.
- Integrated:System-on-chip architectures combine processing cores with power management and communication stacks. REACH-compliant packaging houses in Dresden supply these for medical device OEMs.
- Development Board:Evaluation platforms with debug interfaces and reference designs accelerate firmware prototyping. CE marking timelines for electromagnetic compatibility testing constrain launch windows for board vendors.
Today's leader: Embedded. Tomorrow's challenger: Integrated.
Technology:
Margin pools concentrate where analog precision eliminates discrete component counts.
- Mixed Signal:Precision analog-to-digital converters operate alongside 8-bit digital cores at sub-40 MHz clock speeds. Grenoble design centers dominate this segment for space-constrained sensor interfaces in Italian white-goods controllers.
- Analog:Continuous signal processing peripherals handle voltage reference and comparator functions without digital conversion. German industrial automation OEMs source these for legacy 4-20 mA loop interfaces.
- Digital:Pure logic implementations execute boolean operations and timing sequences without analog front-ends. Telecommunications equipment manufacturers in Eindhoven specify these for protocol state machines.
- Microcontroller Unit:Standardized core architectures with programmable GPIO and timer arrays. Consumer electronics assemblers negotiate volume commitments for mask-ROM variants.
Mixed Signal commands the steepest expansion trajectory as sensor proliferation multiplies analog channel counts per device.
End User:
Automotive qualification requirements create the steepest barriers to supplier entry.
- Automotive:AEC-Q100 stress testing and PPAP documentation govern powertrain and body electronics procurement. Eindhoven-based development centers synchronize roadmaps with electrification timelines.
- Industrial Automation:Extended temperature ratings and galvanic isolation specifications dominate programmable logic controller designs. German manufacturing clusters drive replacement cycles for lead-free solder compatibility.
- Consumer Electronics:Cost-optimized units with minimal peripheral counts serve appliance and personal device markets. Italian white-goods manufacturers consolidate supplier pools to reduce incoming inspection overhead.
- Telecommunications:Real-time protocol handling with deterministic latency bounds supports network infrastructure. CE marking mandates electromagnetic compatibility certification for base station subsystems.
Automotive absorbs the premium tier. Industrial Automation scales the volume base.
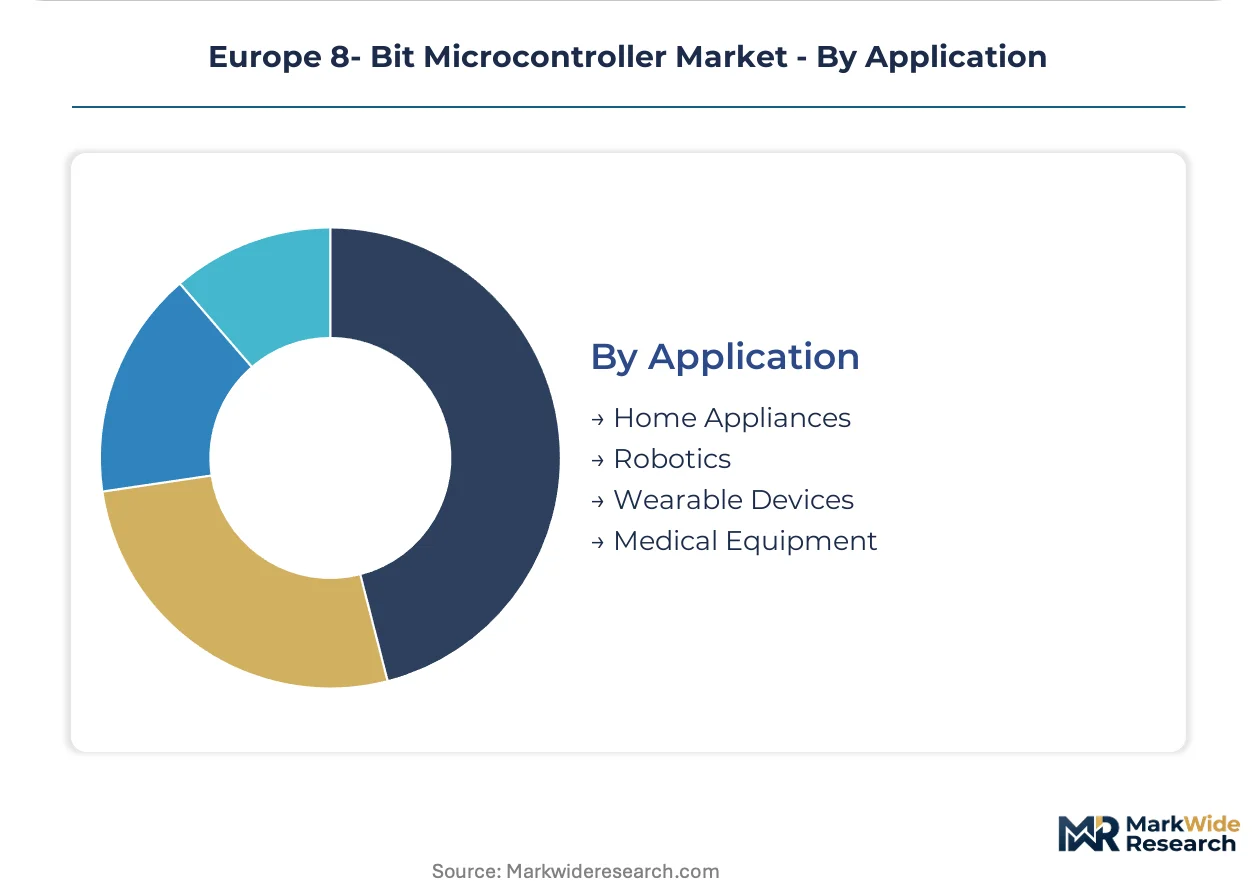
Application:
Medical and robotics segments demand documentation depth that factory-programmed supply can satisfy.
- Medical Equipment:IEC 60601 isolation requirements and biocompatibility standards constrain material selections for patient-contact devices. Swiss and German diagnostic equipment OEMs specify mixed-signal units for precision sensing front-ends.
- Robotics:Motor drive synchronization and encoder feedback loops require sub-millisecond interrupt response. Czech automotive component plants specify these for production line modernization.
- Home Appliances:Motor control algorithms and user interface scanning dominate washing machine and refrigerator controllers. Mask-ROM procurement from Italian manufacturing clusters reduces firmware update liability.
- Wearable Devices:Sub-1 mA sleep currents and compact wafer-level packaging enable battery-powered form factors. EU Green Deal efficiency mandates accelerate adoption for personal health monitors.
Medical Equipment claims the highest certification premiums. Home Appliances moves the largest unit volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European 8-bit microcontroller demand traces its industrial lineage to post-war precision engineering clusters in Germany and the Netherlands, where automotive and automation sectors first established captive semiconductor supply chains. These foundational manufacturing networks continue to anchor regional procurement patterns.
Germany
Automotive electrification and industrial automation corridors drive microcontroller consumption across Bavaria and Baden-Württemberg. The EU Green Deal mandates energy-efficiency standards for embedded motor control systems. Dresden fabrication complexes supply captive wafer output to automotive Tier-1 suppliers specifying extended temperature ratings.
Italy
White-goods manufacturing clusters in Lombardy and Veneto specify factory-programmed units for washing machine and refrigerator controllers. REACH compliance requirements constrain lead-free solder interface selections for appliance exports. Italian OEMs consolidate supplier qualification pools to reduce incoming inspection overhead.
Netherlands
Eindhoven-based development centers synchronize microcontroller roadmaps with powertrain integration timelines for European automotive programs. CE marking directives mandate electromagnetic compatibility testing for development boards. The Dutch semiconductor ecosystem anchors mixed-signal design expertise for sensor interface applications.
France
Grenoble design centers dominate precision analog-to-digital integration for space-constrained medical device controllers. The EU AI Act's risk-classification framework is propagating documentation requirements into embedded system specifications. French diagnostic equipment OEMs specify mixed-signal units for patient-contact sensing front-ends.
Poland
Automotive component plants in Silesia and Lower Silesia specify pin-compatible 8-bit upgrades for legacy equipment modernization. RoHS substance restrictions accelerate replacement cycles for industrial automation retrofits. Polish manufacturing clusters absorb technology transfer from German industrial corridors seeking cost-optimized production capacity.
Europe 8- Bit Microcontroller Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European 8-bit microcontroller landscape. The market structure concentrates around vertically integrated semiconductor houses with captive fabrication assets and fabless specialists licensing core architectures. Three archetypes dominate: automotive-qualified fabricators with AEC-Q100 certification pipelines, mixed-signal specialists integrating precision analog peripherals, and cost-optimized suppliers serving appliance volume contracts. Competitive dynamics center on strategic partnerships for advanced packaging capacity and geographic expansion into Eastern European industrial retrofit markets.
Within the automotive-qualified tier, Infineon Technologies AG and NXP Semiconductors N.V. occupy positions shaped by their European fabrication footprints. STMicroelectronics N.V. represents the mixed-signal convergence archetype through its Grenoble-based design operations. These three companies exemplify how regional production assets and regulatory compliance capabilities create defensive positioning against cost-compressed ARM-based alternatives.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Microchip Technology Inc. |
| Texas Instruments Incorporated |
| Silicon Laboratories Inc. |
| Holtek Semiconductor Inc. |
| Analog Devices Inc. |
| Others |
Supply & Pricing Matrix
Captive wafer fabrication at Dresden and Eindhoven complexes anchors supply security for automotive-grade 8-bit units while simultaneously constraining pricing flexibility for European microcontroller vendors serving cost-sensitive appliance markets.
Pricing Analysis
Three-tier pricing structure across automotive-qualified, industrial-grade, and economy appliance tiers dominates European procurement. Price differentiation separates AEC-Q100 certified units with PPAP documentation from standard-temperature commercial variants. Cost compression in the economy tier is intensifying because 32-bit ARM Cortex-M0 cores encroach on traditional 8-bit socket positions. Appliance manufacturers in Italian white-goods clusters exhibit the highest price sensitivity, while German automotive Tier-1 suppliers absorb premium pricing for extended temperature ratings and REACH-compliant packaging.
Supply Chain Analysis
AEC-Q100 qualification pipelines gate supplier entry and concentrate automotive-grade output among Dresden and Eindhoven fabrication complexes. Raw material dependencies span silicon wafers, halogen-free epoxy molding compounds, and lead-free solder alloys. Single-source vulnerability runs through REACH-compliant packaging houses certified for high-temperature automotive grades. Distribution runs through direct OEM contracts for volume appliance buyers and authorized distributors for development board sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe 8-bit microcontroller market represents a late-cycle quality story as automotive electrification shifts procurement criteria toward mixed-signal precision and extended temperature documentation.
For Market Incumbents: To counter 32-bit ARM encroachment in appliance controllers, deepen captive wafer supply at Dresden complexes while accelerating smart analog peripheral integration that eliminates discrete component counts. Prioritize AEC-Q100 certification pipeline investments to defend automotive socket positions against cost-compressed alternatives. For New Entrants and Emerging Players: Begin with Polish and Czech industrial retrofit corridors where pin-compatible 8-bit upgrades for legacy equipment modernization face limited qualified competition. Target medical device OEMs in Grenoble and Swiss diagnostic clusters requiring mixed-signal precision and IEC 60601 isolation documentation. Pursue factory-programmed mask-ROM supply agreements with Italian white-goods manufacturers consolidating supplier pools. For Investors and Strategic Acquirers: Roll-up economics work for mixed-signal design specialists because automotive sensor proliferation multiplies analog channel counts per device while aging assembly-level firmware talent concentrates defensible expertise. Five-to-ten year viability hinges on EU AI Act documentation service revenue streams materializing for deterministic edge control loops. Watch for ECHA SVHC listing expansions forcing halogenated flame retardant reformulation as inflection triggers for packaging house consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Analog Peripheral Integration | Unifying sensor interfaces eliminates discrete op-amps for Tier-1 battery management designs. |
| REACH-Compliant Packaging Certification | Pre-certified epoxy molding compound access secures automotive qualification timelines against ECHA restrictions. |
| Eastern European Geographic Expansion | Polish and Czech retrofit demand absorbs technology transfer from German industrial corridors. |
| Factory-Programmed Mask-ROM Commitments | Captive volume agreements with Italian appliance OEMs reduce incoming inspection overhead. |
| EU AI Act Documentation Services | Risk-classification frameworks for edge devices create premium service revenue beyond silicon sales. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from automotive Tier-1 procurement managers, industrial automation plant engineers, appliance OEM supply chain directors, and semiconductor packaging house technical leads. Secondary validation drew from SEC semiconductor filings, ECHA substance restriction updates, EU Green Deal implementation documents, and AEC-Q100 qualification registries. Bottom-up unit demand estimates triangulated against top-down fabrication capacity data.
Segment-weighting approaches distributed value across product type, technology, end user, and application dimensions. CAGRs were derived from regression analysis of historical procurement patterns projected across the modeling period. Forecast inputs incorporated automotive electrification roadmaps, REACH compliance timelines, and Eastern European industrial modernization trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruptions to wafer supply, abrupt shifts in EU AI Act implementation schedules, and unanticipated 32-bit cost compression breakthroughs. Forecasts reflect documented assumptions about sustained automotive sensor proliferation and stable REACH substance restriction trajectories. A model refresh is warranted upon material change in Eindhoven-Dresden fabrication complex output allocation or ECHA SVHC listing expansion pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Plasmonic Chip Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Wi-Fi Chipset Market