
 Power Architecture Market | 2026-2036
Power Architecture Market Size, Share, and Industry Trends Forecast 2026-2036
Power Architecture Market Analytics
Silicon carbide is displacing conventional silicon IGBTs in high-frequency power conversion, and this material transition is realigning cost structures across electric vehicle inverters and renewable energy inverters. NXP Semiconductors leverages its automotive-qualified SiC portfolio to anchor supply relationships with European EV platforms. Schneider Electric extends its dominance in three-phase power distribution through integrated microgrid software stacks.
Power architecture encompasses the systematic design of electrical energy conversion, distribution, and management subsystems operating at efficiencies typically exceeding 94% in modern switch-mode configurations, serving to ensure reliable power delivery across industrial, transportation, and digital infrastructure. Switch Mode Power technology leads volume deployment due to its density advantages in server racks and onboard chargers, while Digital Power controls capture expanding margin pools through firmware-defined optimization algorithms. Hybrid Power architectures are gaining traction in grid-tied storage systems where linear stages handle transient suppression before digital control loops manage steady-state operation.
EPA ENERGY STAR specifications and the EU Ecodesign Directive constrain standby losses and minimum load efficiencies for external power supplies sold across their respective jurisdictions, forcing redesigns of adapter and charger portfolios. IEC 62368-1 safety standards govern hazard-based engineering in audio-visual and information technology equipment, directly influencing isolation requirements and clearance rules in power stage layouts. Stakeholders must monitor how EPA rulemaking on data center PUE metrics and EU CSRD disclosure requirements reshape procurement criteria for hyperscale operators evaluating vendor qualification.
Market Dynamics
Silicon carbide substrate shortages are compressing inverter production timelines while EPA ENERGY STAR 8.0 specifications force 94%-plus efficiency floors across external power supply portfolios. This dual squeeze—material scarcity meeting regulatory ratcheting—determines which suppliers capture hyperscale qualification slots.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby loss limits below 0.5W for adapters sold across EU member states are forcing redesigns of legacy linear transformer portfolios, opening switch-mode replacement cycles.
- China domestic fab scale-up:Localized 200mm SiC wafer production in Hefei and Xiamen is reducing import dependency for domestic EV inverter manufacturers.
- Onboard charger power density:22kW bidirectional OBC architectures are proliferating across European EV platforms, pulling 650V SiC MOSFET demand.
Market Restraints
- Substrate cost volatility:6-inch SiC wafer prices remain elevated due to Wolfspeed and Coherent supply concentration, constraining margin expansion for mid-tier inverter vendors.
- Technical limitation:Gate oxide reliability in planar SiC MOSFETs under humid thermal cycling limits automotive qualification to AEC-Q101 Grade 0, excluding lower-tier suppliers.
- Regulatory friction:IEC 62368-1 third edition clearance requirements for reinforced isolation are extending power stage layout redesign cycles by 4-6 months.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor packaging are attracting module assembly investments for solar string inverters targeting Middle East and African export markets.
- Grid-tied storage hybridization:Convergence of silicon carbide power stages with lithium iron phosphate battery management systems is creating integrated microinverter form factors for residential solar-plus-storage.
- Digital power firmware licensing:ARM Cortex-M4 based control algorithms are enabling white-label power supply vendors to differentiate through adaptive dead-time optimization without silicon redesign.
Industry Challenges
- Magnetics design talent scarcity:Experienced planar transformer engineers capable of 500kHz+ LLC resonant design are concentrated among tenured specialists at Austrian and German magnetics houses.
- Multi-standard certification backlog:Simultaneous UL 62368-1, CE marking, and China CQC approval timelines are stretching product launch windows for universal adapter portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Architecture Market |
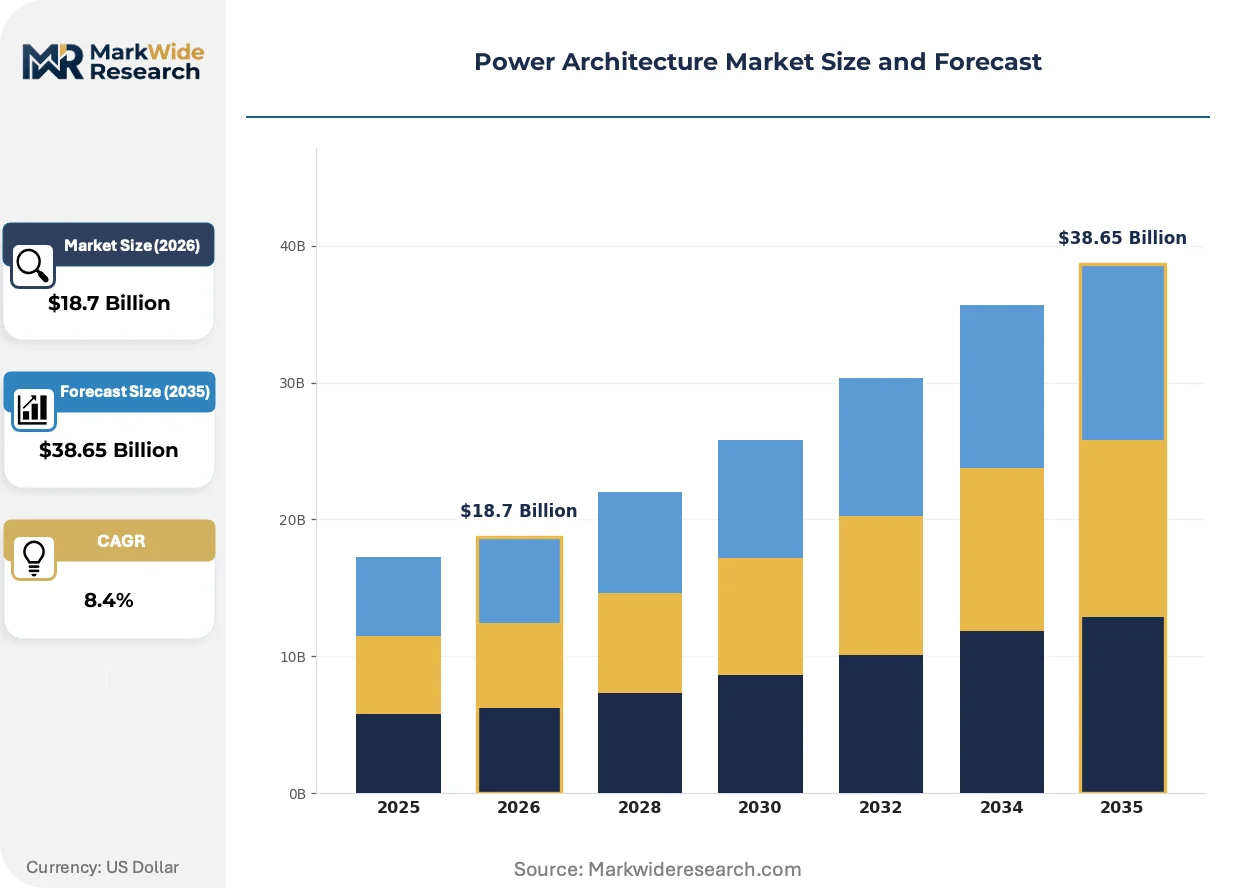
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Integrated Circuits, Power Modules, Power Management Systems, Gate Drivers Technology: Digital Power, Linear Power, Switch Mode Power, Hybrid Power End User: Automotive, Consumer Electronics, Industrial Automation, Telecommunications Application: Power Supply Units, Electric Vehicles, Renewable Energy Systems, Data Centers |
| Companies Covered | IBM, NXP Semiconductors, Applied Micro Circuits Corporation, Schneider Electric, Eaton, Vertiv, ABB, Delta Electronics, Huawei Digital Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Architecture Market Evolving Landscape
Power architecture is undergoing material-driven restructuring as wide-bandgap semiconductors compress switching losses and enable thermal management simplification. Regulatory efficiency floors and buyer procurement consolidation are simultaneously accelerating technology turnover.
Gallium nitride HEMTs are electrifying 48V direct-conversion server power architectures by eliminating intermediate bus stages. Hyperscale operators in Oregon and Virginia are qualifying 3kW+ single-stage 48V-to-point-of-load designs. This topology compression is collapsing the multi-vendor intermediate bus converter ecosystem into integrated power-stage monopolies.
EPA rulemaking on data center PUE metrics is mandating real-time power usage effectiveness disclosure for federal cloud procurement. Colocation operators in Northern Virginia and Frankfurt are retrofitting rack-level DCIM instrumentation to meet granular reporting thresholds. This transparency mandate is advantaging suppliers with embedded metering firmware over hardware-only competitors.
Buyer consolidation among tier-one EV platforms is compressing inverter supplier qualification cycles from 36 months to 18 months. Volkswagen Group and Stellantis are running parallel sourcing committees for 800V traction inverters, disqualifying vendors without AEC-Q100 full flow certification. This timeline compression favors incumbents with existing automotive process certifications over industrial power entrants.
Power Architecture Market Segmentation
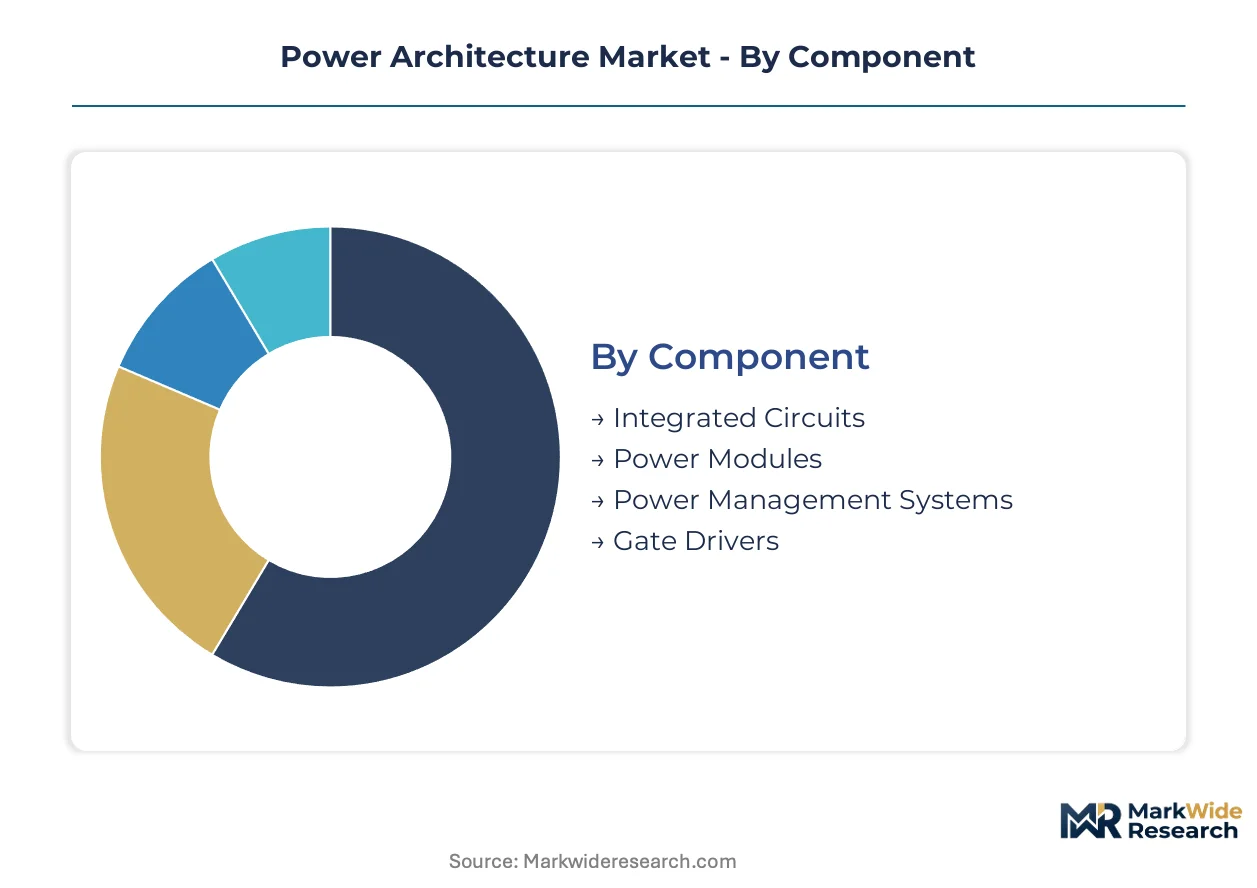
Power architecture segmentation reveals how certification requirements, material transitions, and end-use density demands reshape procurement patterns across component tiers and technology platforms. Buyers now qualify suppliers through combined efficiency benchmarks and automotive-grade reliability gates rather than discrete specification checks.
Component:
Certification burden concentrates heaviest on power modules and integrated circuits, where AEC-Q100 automotive flow and IEC 62368-1 safety isolation create 18-24 month qualification timelines that exclude fabless entrants.
- Integrated Circuits:Silicon carbide gate drivers and digital power controllers integrate adaptive dead-time algorithms in 40nm BCD processes. Demand clusters in Hefei and Shenzhen as domestic EV platforms localize inverter control electronics.
- Power Modules:Press-fit pin-fin baseplates and direct-bonded copper substrates handle 800V traction inverter thermal cycling. Volkswagen Group and Stellantis sourcing committees mandate AEC-Q101 Grade 0 gate oxide reliability, compressing supplier pools to Wolfspeed, Infineon, and STMicroelectronics qualified flows.
- Power Management Systems:Rack-level DCIM instrumentation with embedded metering firmware captures hyperscale procurement in Oregon and Virginia.
- Gate Drivers:Isolated gate drivers with reinforced isolation per IEC 62368-1 third edition clearance rules dominate 650V SiC MOSFET pairing.
Leading the category by volume: Power Modules. Growing fastest: Integrated Circuits.
Technology:
Cost tier stratification separates premium wide-bandgap implementations from legacy silicon, with firmware licensing models now capturing margin pools previously held by discrete semiconductor vendors.
- Switch Mode Power:LLC resonant and totem-pole PFC topologies achieve 94%-plus efficiency floors mandated by EPA ENERGY STAR 8.0. Server rack and onboard charger deployments in Frankfurt and Northern Virginia drive 500kHz+ magnetics demand.
- Digital Power:ARM Cortex-M4 based control loops enable adaptive optimization without silicon redesign. White-label vendors license firmware to differentiate against hardware-only competitors in external adapter markets.
- Linear Power:Remaining utility in audio and precision instrumentation where ripple suppression outweighs efficiency.
- Hybrid Power:Grid-tied storage systems pair linear transient suppression stages with digital steady-state control.
Highest margin capture: Digital Power. Steepest volume expansion: Switch Mode Power.
End User:
Application maturity varies sharply, with automotive qualification timelines now half their historical duration while industrial automation maintains 36-month certification stability.
- Automotive:800V traction inverters and 22kW bidirectional onboard chargers pull 650V SiC MOSFET demand. European EV platforms run parallel sourcing committees, disqualifying vendors without full AEC-Q100 flow certification.
- Industrial Automation:Three-phase motor drives and servo systems sustain demand for 1200V IGBT modules in mature replacement cycles.
- Telecommunications:48V direct-conversion server architectures eliminate intermediate bus stages in hyperscale facilities.
- Consumer Electronics:EU Ecodesign Directive standby loss limits below 0.5W force switch-mode redesigns of legacy transformer portfolios.
Deepest qualification barriers: Automotive. Fastest procurement cycle compression: Telecommunications.
Application:
Geographic deployment concentration shapes supplier selection, with data center operators in specific jurisdictions now mandating real-time PUE disclosure that advantages embedded metering capabilities.
- Data Centers:Rack-level DCIM instrumentation meets EPA federal cloud procurement thresholds for granular power usage effectiveness reporting. Colocation operators in Northern Virginia and Frankfurt retrofit telemetry infrastructure.
- Electric Vehicles:800V architectures proliferate across European platforms, pulling SiC inverter demand. Domestic fab scale-up in Hefei and Xiamen reduces import dependency for Chinese EV manufacturers.
- Power Supply Units:External adapters face simultaneous EPA ENERGY STAR efficiency ratcheting and IEC 62368-1 isolation redesigns.
- Renewable Energy Systems:Solar string inverters and grid-tied storage hybridize silicon carbide power stages with lithium iron phosphate battery management.
Most stringent reporting mandates: Data Centers. Fastest material transition: Electric Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the steepest demand acceleration as domestic semiconductor fabrication and electric vehicle manufacturing scale simultaneously. Germany and the United States anchor high-value procurement through automotive platform sourcing and hyperscale data center expansion. India, Japan, and South Korea complete the geographic spread through diverging specialization in assembly incentives, precision magnetics, and memory-adjacent power management.
China
Localized 200mm silicon carbide wafer production in Hefei and Xiamen reduces import dependency for domestic EV inverter manufacturers. The Ministry of Industry and Information Technology's dual carbon goals accelerate grid-tied storage deployments. Shenzhen and Shanghai clusters dominate digital power controller design for server and telecommunications applications.
Germany
Volkswagen Group and Stellantis sourcing committees mandate AEC-Q100 full flow certification for 800V traction inverter suppliers. The KBA enforces stringent automotive safety protocols that compress qualification timelines. Bavarian and Baden-Württemberg industrial corridors concentrate planar transformer engineering talent for 500kHz LLC resonant designs.
United States
Hyperscale operators in Oregon and Virginia qualify 3kW single-stage 48V-to-point-of-load architectures. EPA rulemaking on data center PUE metrics mandates real-time disclosure for federal cloud procurement. Northern Virginia colocation facilities retrofit rack-level DCIM instrumentation to meet granular reporting thresholds.
India
Production-linked incentives for semiconductor packaging attract module assembly investments targeting Middle East and African solar inverter export markets. The Bureau of Indian Standards and Central Electricity Authority regulate grid interconnection standards. Gujarat and Karnataka host emerging assembly clusters for string inverter power stages.
Japan
METI efficiency standards and JIS certification requirements sustain demand for precision linear power in audio and instrumentation segments. Tokyo and Osaka metropolitan areas retain concentrated expertise in high-frequency magnetics design. Domestic automotive platforms source locally qualified gate driver integrated circuits for hybrid vehicle powertrains.
Power Architecture Market Competitive Landscape
Capacity expansion dominates the current landscape as substrate-constrained suppliers race to capture automotive qualification slots before 18-month sourcing windows close. The vendor base stratifies across three tiers: integrated device manufacturers with captive SiC crystal growth, fabless digital power controller specialists licensing ARM-based firmware, and contract assemblers serving white-label adapter markets. Strategic archetypes include automotive-qualified incumbents defending AEC-Q100 certification moats, industrial power houses extending microgrid software stacks, and Asian electronics conglomerates leveraging vertical integration into magnetics and thermal management. M&A activity concentrates on SiC substrate assets and digital power algorithm portfolios, while geographic expansion targets Indian PLI scheme incentives and Middle East solar deployment corridors.
Within the automotive-qualified tier, NXP Semiconductors and Infineon occupy positions defined by AEC-Q101 gate oxide reliability certification. Schneider Electric exemplifies the industrial-microgrid convergence archetype through integrated three-phase distribution software. Huawei Digital Power represents the Asian conglomerate model with in-house capabilities spanning controller design to system integration. Delta Electronics sits within the contract manufacturing and ODM tier, serving hyperscale and telecommunications procurement channels. IBM and Applied Micro Circuits Corporation occupy legacy positions in enterprise computing power management, while Eaton, Vertiv, and ABB compete across data center infrastructure and industrial automation segments.
| Leading Market Players |
|---|
| IBM |
| NXP Semiconductors |
| Applied Micro Circuits Corporation |
| Schneider Electric |
| Eaton |
| Vertiv |
| ABB |
| Delta Electronics |
| Huawei Digital Power |
| Others |
Value Network & Pricing Analysis
EPA ENERGY STAR 8.0 efficiency mandates and EU Ecodesign Directive standby loss limits gate qualified supply access and premium-tier pricing power for external power supply vendors. Buyers without certified 94%-plus efficiency portfolios face disqualification from hyperscale and automotive procurement channels, compressing margin recovery for uncertified competitors.
Pricing Analysis
Volume deployment concentrates in switch-mode power supplies for server racks and onboard chargers, while margin capture clusters in digital power firmware licensing and AEC-Q100 qualified automotive modules. Pricing stratifies across AEC-Q101 Grade 0 certified premium tiers, EPA ENERGY STAR compliant standard tiers, and uncertified economy adapter tiers. Cost compression in mid-tier inverter segments intensifies because 6-inch SiC wafer prices remain elevated, squeezing vendors without captive substrate supply. Industrial automation buyers exhibit highest price sensitivity due to mature replacement cycles, while automotive platforms prioritize qualification speed over unit cost.
Supply Chain Analysis
Experienced planar transformer engineers capable of 500kHz+ LLC resonant design remain concentrated in Bavarian and Baden-Württemberg industrial corridors, constraining magnetics scaling. Substrate supply draws from Wolfspeed and Coherent concentration in the United States, with emerging 200mm SiC wafer production in Hefei and Xiamen reducing Chinese import dependency. Gate oxide reliability testing and AEC-Q101 Grade 0 qualification capacity create single-source vulnerability for automotive inverter vendors. Distribution runs through direct qualification relationships with Volkswagen Group and Stellantis sourcing committees, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as 18-month automotive qualification timelines and SiC substrate scarcity force weaker players without certification assets or captive supply into exit or acquisition.
For Market Incumbents: Deploy AEC-Q100 full flow certification as a defensive moat against industrial power entrants lacking automotive process qualifications. Add 200mm SiC wafer capacity in Hefei or Xiamen to reduce substrate cost volatility exposure. Capture hyperscale DCIM instrumentation procurement through embedded metering firmware differentiation. For New Entrants and Emerging Players: Direct-to-designer digital channels enable white-label power supply vendors to license ARM Cortex-M4 based control algorithms without silicon redesign investments. Target India's PLI scheme for semiconductor packaging incentives, serving Middle East and African solar inverter export markets. Pursue grid-tied storage hybridization opportunities where linear transient suppression stages pair with digital steady-state control. For Investors and Strategic Acquirers: Wolfspeed or Coherent capacity expansion announcements are the leading indicator that substrate scarcity is easing and margin compression will shift downstream to module assemblers. Over a multi-year horizon, vertically integrated SiC crystal growth assets command premium valuations. Monitor EPA rulemaking on data center PUE metrics as the signal for embedded metering firmware acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Full Flow Certification | Volkswagen Group and Stellantis sourcing committees mandate this gate for 800V traction inverter supply. |
| 200mm SiC Wafer Capacity Buildout | Hefei and Xiamen localization reduces import dependency for domestic Chinese EV manufacturers. |
| Digital Power Firmware Licensing | ARM Cortex-M4 based algorithms enable white-label differentiation without silicon redesign. |
| Rack-Level DCIM Instrumentation | Northern Virginia and Frankfurt colocation operators retrofit to meet EPA federal cloud procurement thresholds. |
| India PLI Scheme Module Assembly | Gujarat and Karnataka clusters target Middle East and African solar string inverter export markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with power module procurement leads at Tier 1 automotive suppliers, data center infrastructure planners in Oregon and Virginia, planar transformer engineering directors in Bavaria, and SiC substrate supply chain managers triangulated against EPA ENERGY STAR certification databases, IEC 62368-1 third edition safety filings, and AEC-Q100 qualification registries. Bottom-up segment sizing across component tiers and top-down market reconciliation validated volume estimates.
Granularity-level modeling distinguished switch-mode, digital, linear, and hybrid power technologies across automotive, industrial automation, telecommunications, and consumer electronics end uses. Component segmentation captured integrated circuits, power modules, power management systems, and gate drivers with distinct certification burdens. CAGRs derived from shipment volume trajectories and value-per-unit trends across the analysis window, incorporating SiC substrate supply constraints and regulatory efficiency floor ratcheting as structural parameters.
The model holds under sustained EPA and EU regulatory enforcement and stable SiC substrate supply concentration; deviation in Wolfspeed or Coherent capacity expansion timelines, IEC 62368-1 fourth edition rulemaking, or China domestic fab scale-up acceleration would shift competitive positioning and margin distribution. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
United Arab Emirates Data Center Processor Market