
 China Automotive Microcontroller Market | 2026-2036
China Automotive Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Microcontroller Market Outlook
Modular ECU bundling is restructuring procurement patterns across Chinese OEMs. STMicroelectronics leverages its Arm Cortex-M product depth to anchor premium safety system contracts. Texas Instruments sustains analog-digital integration leadership for powertrain modules. Infineon Technologies AG dominates automotive-grade 32-bit supply through its AURIX platform.
Automotive microcontrollers are integrated circuits engineered to operate across temperatures from minus forty to one hundred fifty degrees Celsius, managing real-time control functions in vehicle subsystems through embedded flash memory and deterministic processing cores. Their primary purpose is executing safety-critical and comfort functions under strict ISO 26262 functional safety constraints. The 32-bit segment leads unit shipments as advanced driver-assistance systems and domain controllers require higher compute throughput. Powertrain applications command concentrated R&D investment due to electrification mandates. Embedded technology occupies the largest revenue pool, though reprogrammable architectures gain traction for over-the-air update compatibility.
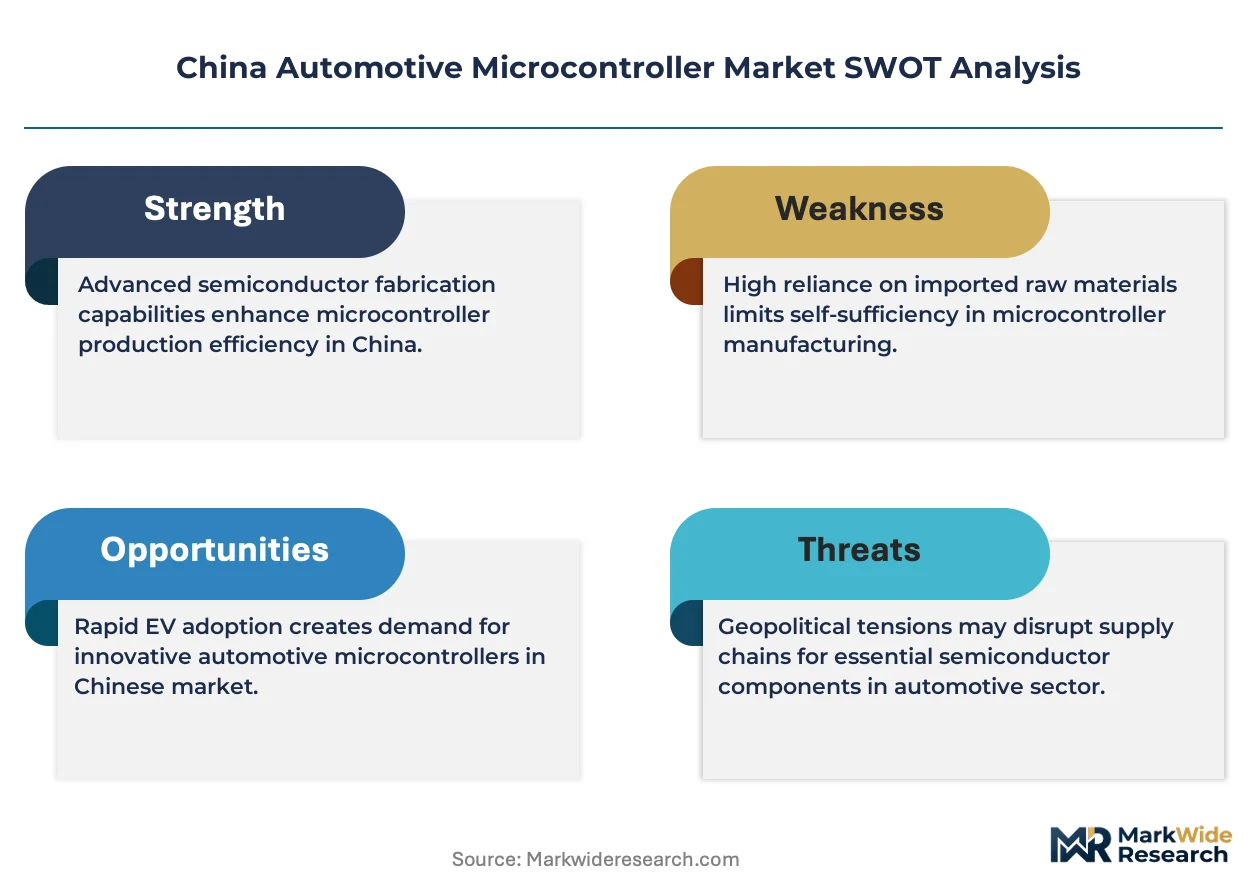
MIIT enforces GB/T standards for vehicle network security and software upgrades, compelling MCU vendors to integrate hardware security modules. SAMR oversees antitrust and quality certification, shaping market access for domestic and foreign suppliers. China's dual carbon goals from MEE tighten emissions monitoring requirements, expanding microcontroller penetration in battery thermal management. Stakeholders must monitor how GB/T compliance timelines and domestic substitution policies redistribute design wins between foreign and local chip vendors.
Market Dynamics
China's dual carbon mandate from MEE is compressing electrification timelines, forcing OEMs to consolidate ECU architectures and source higher-integration MCUs from clustered Yangtze River Delta suppliers.
Growth Catalysts
- GB/T cybersecurity mandates:MIIT's hardware security module requirements for vehicle network protection are pulling advanced 32-bit MCUs into every new platform.
- Battery thermal management proliferation:Electrification targets from MEE are expanding microcontroller deployment across motor control and cell monitoring subsystems.
- Yangtze River Delta clustering:Co-location of tier-1 suppliers and chip design houses around Shanghai and Suzhou is shortening development cycles for domestic OEMs.
Market Restraints
- Wafer supply concentration:Automotive-grade silicon dependency on Taiwan and South Korea foundries creates vulnerability to geopolitical friction and capacity allocation.
- ISO 26262 certification costs:Functional safety compliance for ASIL-D ratings demands multi-year validation investment that excludes smaller domestic MCU vendors.
- Legacy 8-bit substitution ceiling:Cost-sensitive entry vehicle segments retain 8-bit architectures where 32-bit performance exceeds subsystem requirements.
Strategic Opportunities
- Domain controller consolidation:Zonal E/E architectures are unifying multiple ECU functions into single high-performance MCUs, opening socket expansion at BYD and NIO.
- Over-the-air update infrastructure:Reprogrammable flash architectures are enabling subscription-feature monetization that rewards flexible MCU platforms.
- Western China inland penetration:Chengdu-Chongqing automotive manufacturing growth is dispersing demand beyond coastal supply clusters.
Industry Challenges
- Functional safety engineering scarcity:ASIL-certified firmware developers remain concentrated at foreign suppliers and select domestic tier-1s.
- GB/T compliance timeline compression:Accelerated cybersecurity certification deadlines are forcing redesign cycles that strain validation resources.
- Legacy powertrain integration friction:Internal combustion platforms require bridge solutions that complicate pure electrification MCU roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Microcontroller Market |
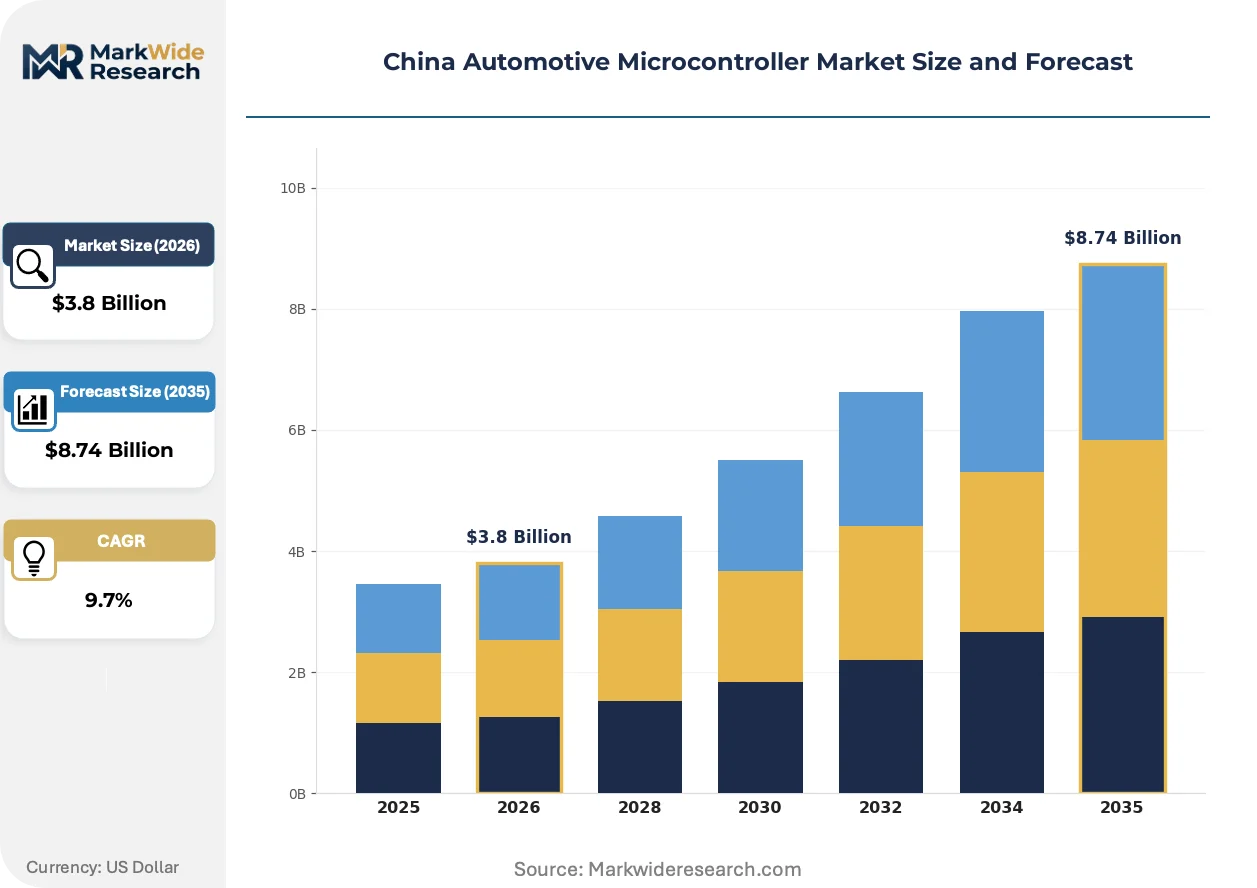
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 32-bit, 16-bit, 8-bit, ARM Cortex Application: Powertrain, Safety Systems, Infotainment, Body Control Technology: Embedded, Reprogrammable, Analog, Digital End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | STMicroelectronics, Texas Instruments, NXP Semiconductors N.V, GigaDevice, BYD Semiconductor, Infineon Technologies AG, Microchip Technology Inc., Nationz Technologies Inc., Renesas Electronics Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Microcontroller Market Strategic Shifts
Electrification is collapsing discrete ECU boundaries, merging powertrain, chassis, and body domain control into unified silicon platforms that demand deterministic real-time performance.
Multi-core lockstep architectures are unifying safety-critical and non-safety functions on single die, reducing component count and wiring mass. Tier-1 suppliers at SAIC and Geely are adopting these integrated solutions for domain controllers. This consolidation is compressing supplier tiers and favoring vendors with in-house ASIL-certified software stacks.
MIIT's GB/T vehicle cybersecurity standards are mandating hardware root-of-trust and encrypted firmware verification for all networked MCUs. Vendors must embed dedicated security modules that isolate cryptographic operations from application cores. Powertrain and ADAS modules face the steepest compliance ramps, with domestic substitution policies accelerating local HSM IP development.
Fleet operators and mobility service providers are consolidating procurement authority, displacing decentralized tier-2 sourcing with direct MCU specifications to chip vendors. This buyer concentration is compressing qualification cycles and demanding multi-year supply commitments. The shift is most visible in NIO and XPeng platform strategies, where in-house hardware teams bypass traditional module suppliers.
China Automotive Microcontroller Market Segmentation
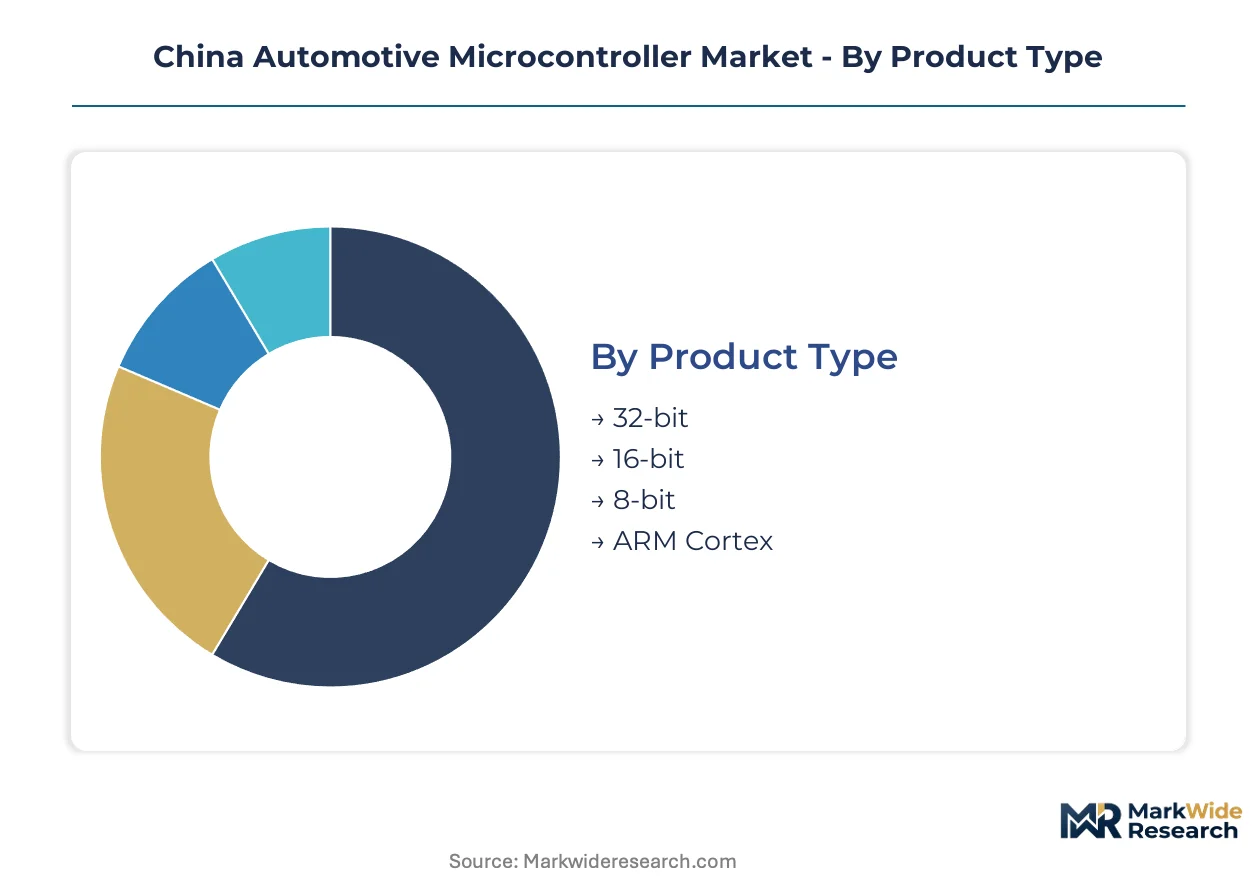
Automotive microcontroller segmentation in China reflects divergent capital requirements across bit-width architectures, application domains, and integration technologies. Procurement patterns cluster around electrification-driven powertrain modules and GB/T cybersecurity-compliant safety systems, while tier-1 supplier consolidation reshapes channel economics for each segment category.
Product Type:
Capital intensity escalates sharply with processing bit-width, as 32-bit designs demand multi-year ASIL-D validation cycles and advanced node wafer commitments that strain domestic vendor balance sheets.
- 32-bit:Multi-core lockstep architectures execute deterministic control for battery management and motor control subsystems in BYD and NIO electric platforms. Yangtze River Delta foundry partnerships concentrate supply for this segment, though ISO 26262 certification timelines extend qualification cycles beyond eighteen months.
- 8-bit:Legacy architectures retain cost-sensitive entry vehicle applications where subsystem complexity does not justify 32-bit overhead. Domestic substitution policies from MIIT favor local vendors in this mature tier, preserving 8-bit relevance in volume-focused OEM portfolios.
- 16-bit:Transitional architectures bridge legacy body control and emerging domain controller requirements with moderate silicon investment.
- ARM Cortex:Licensed IP cores from Arm Holdings enable rapid feature integration for tier-1 suppliers seeking software ecosystem compatibility without full custom design burden.
32-bit absorbs the bulk of installed capacity; ARM Cortex is expanding most quickly.
Application:
Application segmentation tracks electrification intensity, with powertrain modules commanding disproportionate R&D allocation versus comfort and convenience functions.
- Powertrain:Motor control inverters, battery management systems, and thermal regulation subsystems demand real-time deterministic processing under extreme temperature cycling. MEE dual carbon mandates are accelerating microcontroller penetration across cell monitoring and DC-DC conversion circuits in Shanghai and Suzhou manufacturing clusters.
- Safety Systems:Airbag deployment, anti-lock braking, and electronic stability control require ASIL-D functional safety certification that limits qualified vendor pools. GB/T cybersecurity standards from MIIT now mandate hardware security module integration for all networked safety controllers, compressing design win cycles.
- Infotainment:Human-machine interface and connectivity modules prioritize graphics throughput over hard real-time constraints, attracting consumer-grade silicon crossover.
- Body Control:Door modules, lighting, and climate management distribute lower-complexity processing across distributed ECU architectures.
Powertrain captures the steepest investment trajectory; Safety Systems face the tightest qualification bottlenecks.
Technology:
Technology segmentation distinguishes fixed-function versus field-updateable architectures, with reprogrammable flash commanding premium pricing for over-the-air compatibility.
- Embedded:Mask-ROM and one-time programmable architectures dominate cost-optimized body control and legacy powertrain applications where firmware stability outweighs update flexibility. Domestic OEMs at SAIC and Geely retain embedded preference for high-volume platform derivatives to minimize per-unit silicon overhead.
- Reprogrammable:Flash-based and EEPROM architectures enable subscription-feature monetization and cybersecurity patch deployment throughout vehicle lifecycle. NIO and XPeng in-house hardware teams specify reprogrammable MCUs exclusively, bypassing traditional tier-1 module suppliers for direct chip vendor procurement.
- Analog:Mixed-signal integration reduces discrete component count in powertrain sensing and battery monitoring subsystems.
- Digital:Pure logic implementations concentrate in gateway and domain controller applications requiring high-speed data routing.
Embedded retains volume dominance; Reprogrammable climbs fastest on electrification platform refresh cycles.
End User:
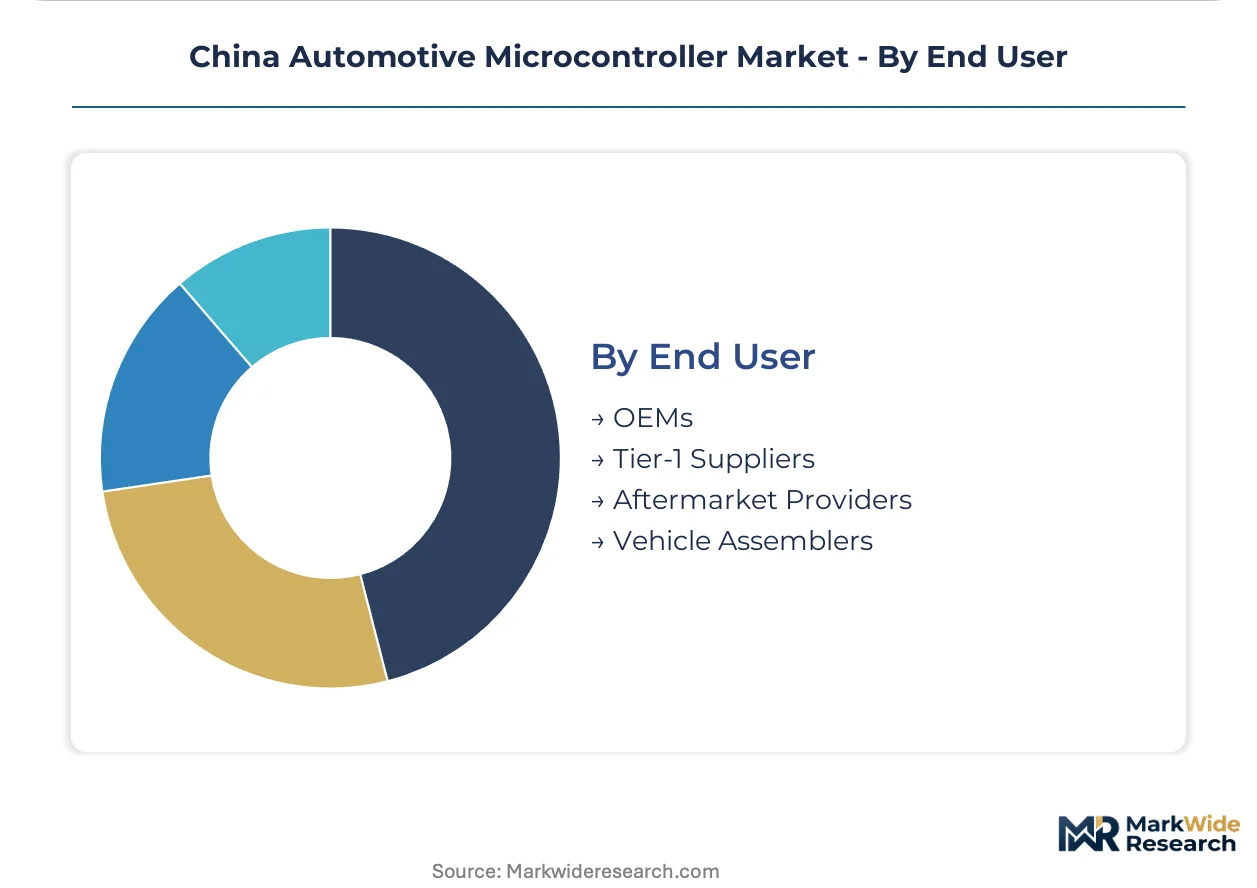
End user segmentation reveals procurement authority migration, with OEM direct sourcing displacing traditional tier-2 distribution for strategic microcontroller categories.
- OEMs:BYD, NIO, and XPeng maintain captive hardware engineering teams that specify MCUs directly, compressing supplier tiers and demanding multi-year supply commitments. This buyer concentration accelerates qualification timelines but concentrates volume risk on selected chip vendors.
- Tier-1 Suppliers:Bosch, Continental, and domestic counterparts around Shanghai and Suzhou co-locate with chip design houses to shorten development cycles for integrated domain controller modules. Their procurement authority persists in legacy platform derivatives where OEM hardware teams lack penetration.
- Aftermarket Providers:Diagnostic tool and retrofit module vendors source through distribution channels with less stringent qualification requirements.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities inherit MCU specifications from design-phase decisions.
OEMs absorb the bulk of strategic procurement volume; Tier-1 Suppliers retain execution leverage in legacy platform supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the bulk of automotive microcontrollers domestically while relying on Taiwan and South Korea foundries for wafer supply. This production-consumption gap shapes procurement risk and domestic substitution urgency across regional manufacturing clusters.
Yangtze River Delta
Shanghai and Suzhou anchor China's densest concentration of tier-1 suppliers and chip design houses. MIIT's GB/T cybersecurity standards compress development cycles here as co-located engineering teams iterate faster on hardware security module integration. BYD and NIO source 32-bit MCUs directly from clustered vendors for battery management systems.
Pearl River Delta
Guangzhou and Shenzhen drive demand through EV platform manufacturing and electronics supply chain depth. SAMR quality certification requirements filter market access for both foreign and domestic MCU suppliers. Tier-1 module suppliers co-locate with Shenzhen chip design houses to shorten qualification timelines for powertrain controllers.
Beijing-Tianjin-Hebei
State-owned OEMs and military-adjacent automotive programs concentrate procurement authority in captive hardware teams. MEE dual carbon goals tighten emissions monitoring mandates that expand microcontroller deployment across hybrid powertrain subsystems. Domestic substitution policies accelerate local vendor qualification for safety-critical applications.
Sichuan-Chongqing
Chengdu and Chongqing manufacturing growth disperses demand beyond coastal supply clusters. Western China inland expansion attracts tier-1 suppliers seeking lower operational costs and proximity to emerging EV assembly plants. Foundry partnerships remain thinner here, creating logistics premiums for wafer supply.
Shandong Peninsula
Qingdao and Jinan host heavy truck and commercial vehicle manufacturing that demands ruggedized MCUs for powertrain durability. MIIT mandates for commercial vehicle telematics pull networked microcontrollers into fleet management systems. Local industrial policy supports captive semiconductor packaging facilities to reduce import dependency.
China Automotive Microcontroller Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's automotive microcontroller supply base. European and American diversified semiconductor groups anchor premium safety system contracts through ASIL-certified product depth. Domestic pure-plays exploit substitution policies and co-location advantages in the Yangtze River Delta cluster. Competitive moves concentrate on multi-year supply commitments to OEMs with captive hardware teams and direct chip vendor procurement strategies.
Within the diversified tier, STMicroelectronics and Texas Instruments exemplify foreign suppliers leveraging analog-digital integration and Arm ecosystem depth to defend socket positions. Infineon Technologies AG anchors the automotive-grade 32-bit segment through its AURIX platform presence. Among domestic specialists, GigaDevice and BYD Semiconductor occupy positions accelerated by MIIT procurement preferences and vertical integration into captive EV platforms.
| Leading Market Players |
|---|
| STMicroelectronics |
| Texas Instruments |
| NXP Semiconductors N.V |
| GigaDevice |
| BYD Semiconductor |
| Infineon Technologies AG |
| Microchip Technology Inc. |
| Nationz Technologies Inc. |
| Renesas Electronics Corporation |
| Others |
Value Chain & Pricing Dynamics
300mm silicon wafer spot prices from Taiwan foundries cascade through automotive MCU supply chains into tiered pricing structures that separate ASIL-D certified safety controllers from commodity body electronics. Cost pass-through mechanics favor vendors with captive Yangtze River Delta packaging capacity, compressing margins for fabless domestic competitors.
Pricing Analysis
Margin tightening in 32-bit automotive segments reflects ISO 26262 validation cost amortization across lower unit volumes than consumer silicon. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and non-safety economy levels tracks certification investment depth. Pricing pressure accelerates in entry vehicle segments where domestic substitution policies favor local 8-bit vendors. Fleet operators at NIO and XPeng exhibit lowest price sensitivity due to direct procurement authority and lifecycle monetization strategies.
Supply Chain Analysis
Engineering talent scarcity in Shanghai and Suzhou is forcing wage premiums that concentrate advanced packaging investment in the Yangtze River Delta. Wafer fabrication draws from Taiwan and South Korea foundries, while back-end testing and packaging rests on domestic capacity expansion. Single-source vulnerability concentrates in automotive-grade 300mm wafer supply. Distribution runs through tier-1 module suppliers co-located with OEM engineering centers, though BYD and NIO are bypassing this layer for strategic MCU categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's automotive microcontroller market is consolidating around vendors with ASIL-certified software stacks and Yangtze River Delta manufacturing presence. MIIT's accelerated GB/T compliance timelines are forcing weaker domestic players toward module supplier partnerships or exit.
For Market Incumbents: Deploy multi-year supply commitments to OEMs with captive hardware teams, locking socket positions before qualification cycles compress further. Deepen in-house ASIL-D firmware development to defend against domestic pure-plays exploiting substitution policies. Threat vector: NIO and XPeng direct procurement strategies displace tier-1 supplier intermediation. For New Entrants and Emerging Players: Western China inland assemblers in Chengdu-Chongqing represent underserved procurement demand with thinner incumbent presence. Target commercial vehicle telematics modules where MIIT mandates are expanding microcontroller penetration but foreign certification requirements remain lighter. Go-to-market angle: foundry partnerships with domestic packaging houses to bypass Taiwan wafer supply concentration. For Investors and Strategic Acquirers: The window for entry favors domestic pure-plays with GB/T HSM IP development and Yangtze River Delta engineering co-location. Long-term viability hinges on vertical integration into automotive-grade packaging. Signal to watch: MIIT procurement preference shifts in state-owned OEM safety system tenders.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Software Stack Development | Captive firmware certification compresses supplier tiers at BYD and NIO platforms. |
| Yangtze River Delta Packaging Expansion | Co-located testing capacity shortens qualification cycles for domestic OEMs. |
| Hardware Security Module Integration | GB/T compliance mandates from MIIT pull advanced 32-bit MCUs into every new vehicle platform. |
| Direct OEM Procurement Partnerships | Bypassing tier-1 suppliers concentrates volume risk but accelerates design win capture. |
| Western China Inland Distribution | Chengdu-Chongqing manufacturing growth disperses demand beyond coastal supply clusters. |
Study Parameters
Document review covered MIIT regulatory filings, GB/T standard drafts, and vehicle production databases, complemented by interviews with tier-1 supplier procurement managers, OEM platform engineers, and Yangtze River Delta chip design house technical leads. Secondary validation drew from customs trade records, foundry capacity disclosures, and automotive semiconductor distributor channel data. Bottom-up segment sizing and top-down macro anchoring were triangulated to cross-check volume and value estimates.
Output metrics span unit shipments and revenue across the projection horizon, disaggregated by bit-width architecture, application domain, integration technology, and end-user procurement authority. CAGRs were derived from regression analysis against electrification penetration curves and GB/T compliance phase-in schedules. Key inputs include battery electric vehicle platform refresh cycles and domain controller consolidation roadmaps from BYD, NIO, and XPeng.
Revisions become necessary when MIIT accelerates cybersecurity certification timelines or when Taiwan foundry capacity allocation shifts materially. Forecasts reflect assumptions about domestic substitution policy continuity and ASIL-certified engineering labor supply elasticity. A small set of triggers—wafer supply disruption, GB/T standard revision, and state-owned OEM procurement preference shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Automotive Smart Chip Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Data Processing Neuromorphic Chip Market