
 Wheel Spindle Market | 2026-2036
Wheel Spindle Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Spindle Market Intelligence
Stricter vehicle safety mandates from regulators like the US National Highway Traffic Safety Administration (NHTSA) and through EU General Safety Regulations is expanding the requirement for higher-strength material integration. ZF Friedrichshafen AG leverages its expertise in drivetrain technology to offer integrated axle systems. Schaeffler Group specializes in precision components and advanced bearing technologies for spindle assemblies. Dana Incorporated sustains its market position through a focus on commercial vehicle and off-highway applications.
A wheel spindle is a critical suspension component, serving as the mounting point and rotation axis for the wheel hub assembly. These components are typically manufactured from high-strength forged steel or cast iron to withstand significant shear and torsional loads. Demand for aluminum alloy materials is increasing for passenger vehicle applications to reduce unsprung weight. In contrast, forged steel remains dominant in heavy-duty applications like commercial trucks and construction equipment due to durability requirements.
Product quality and performance are governed by international standards such as ISO 9001 for quality management and specific automotive OEM requirements. National regulations, including China's GB standards and federal motor vehicle safety standards in the United States, dictate material strength and testing protocols. Component suppliers must therefore navigate a complex matrix of regional compliance while investing in material science to meet evolving vehicle performance and efficiency targets.
Market Dynamics
The wheel spindle market is shaped by the fundamental tension between lightweighting mandates for passenger vehicles, driven by emissions standards from the US EPA and EU, and the uncompromised durability requirements of the heavy-duty commercial vehicle sector.
Growth Catalysts
- Stricter Safety Mandates:Regulations like the US NHTSA's federal motor vehicle safety standards and EU General Safety Regulations are compelling the use of higher-strength forged steel and advanced alloys to improve crashworthiness and component longevity.
- Lightweighting Initiatives:The automotive industry's focus on reducing vehicle mass to improve fuel efficiency and EV range drives the substitution of traditional cast iron with lighter aluminum alloys in passenger car spindle applications.
- Commercial Fleet Modernization:Economic expansion and e-commerce growth are fueling the modernization of commercial truck fleets, particularly in logistics-heavy economies, creating steady demand for durable forged steel spindles.
Market Restraints
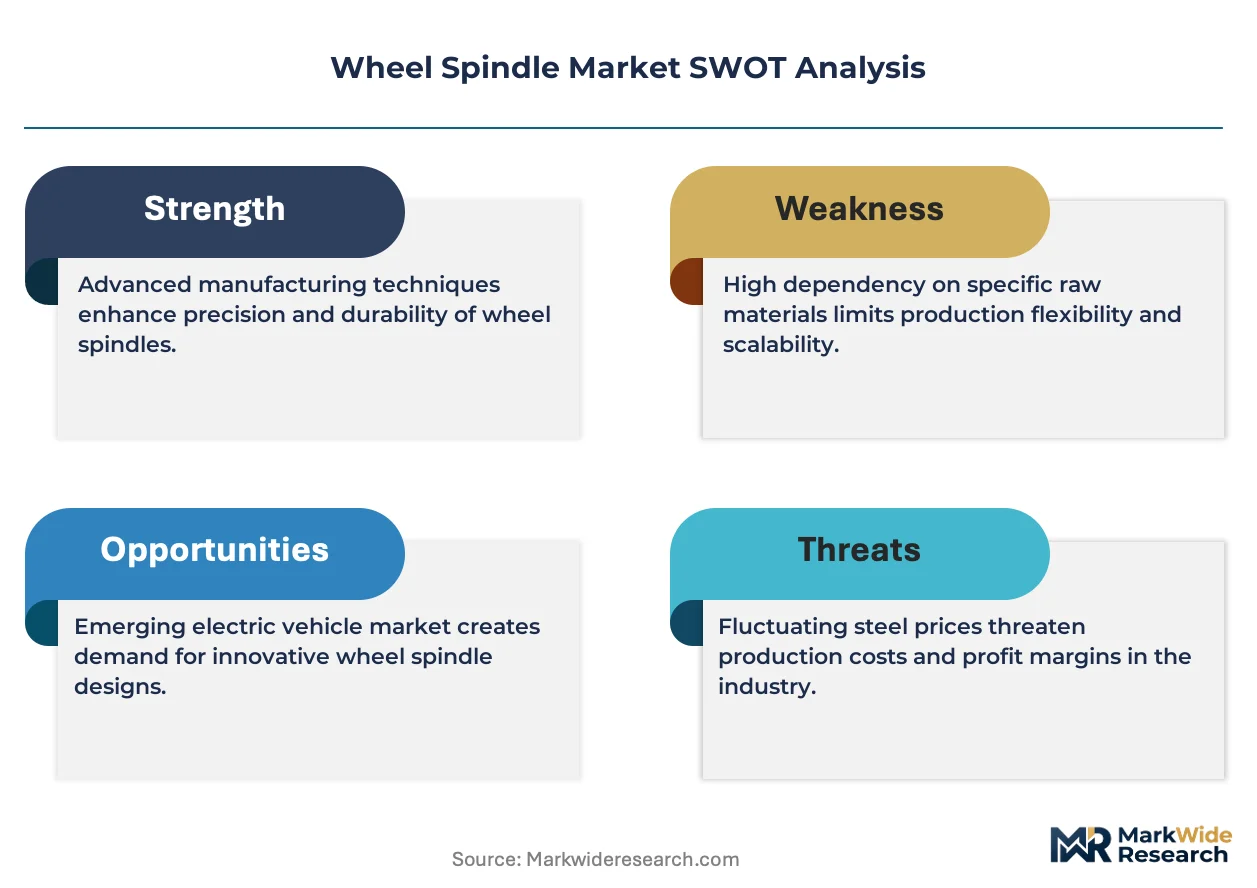
- Raw Material Price Volatility:Fluctuations in the cost of high-strength steel, specialty forging-grade aluminum, and other alloys create pricing instability and margin pressure for component manufacturers.
- Manufacturing Complexity:Forging aluminum alloys into complex spindle geometries that match the fatigue resistance of steel presents significant technical challenges and requires specialized, high-cost manufacturing processes.
- Supply Chain Concentration:The geographic concentration of heavy forging and casting facilities in regions like China creates potential risks for global supply chain disruptions and extended lead times for automakers.
Strategic Opportunities
- Electric Vehicle Architectures:The transition to EVs opens opportunities for developing novel, integrated spindle designs that accommodate in-wheel motors or are part of complete e-axle systems, requiring new material and engineering solutions.
- Aftermarket Expansion:A growing and aging global vehicle parc, especially in emerging economies across Southeast Asia and Latin America, creates a significant opportunity for aftermarket spindle replacement parts.
- Hybrid Material Components:Research into multi-material spindles, combining steel's strength in critical load-bearing areas with aluminum's light weight in others, offers a path to optimize performance for specific vehicle applications.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers must navigate a complex web of differing regional and national standards, including China's GB standards and various OEM-specific protocols, which complicates design, testing, and market access.
- High Capital Investment:The need for advanced precision forging presses and CNC machining centers to produce next-generation spindles requires substantial capital expenditure, creating a barrier to entry for smaller suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Spindle Market |
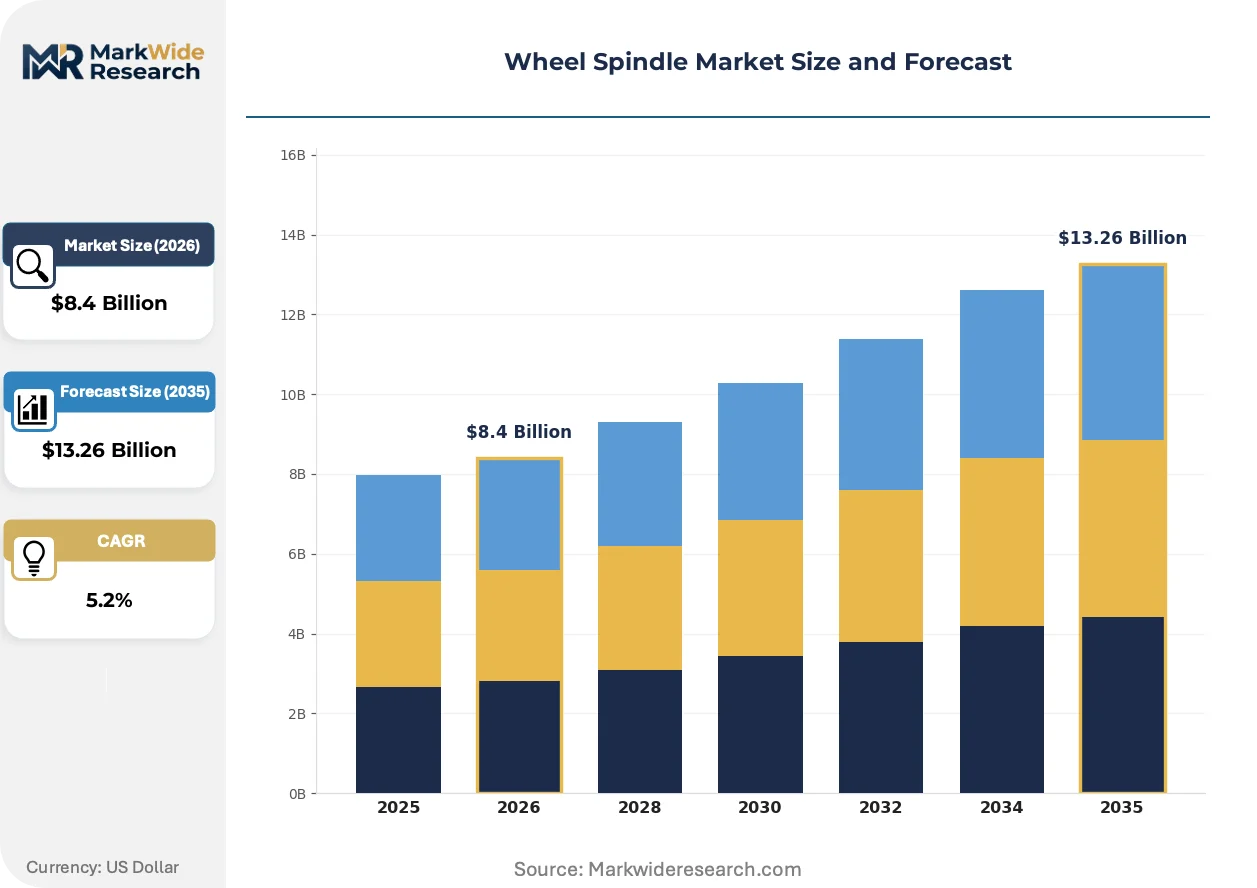
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Wheel Spindle, Rear Wheel Spindle, Heavy-Duty Spindle, Light-Duty Spindle, Precision Spindle Material: Forged Steel, Cast Iron, Aluminum Alloy, Carbon Steel, Composite Materials Application: Commercial Trucks, Passenger Vehicles, Off-Road Vehicles, Agricultural Machinery, Construction Equipment End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Suppliers, Specialty Vehicle Manufacturers |
| Companies Covered | ZF Friedrichshafen AG, Schaeffler Group, JTEKT Corporation, Dana Incorporated, GKN Automotive, Hyundai Mobis, NTN Corporation, American Axle & Manufacturing, ThyssenKrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Spindle Market Strategic Shifts & Innovations
Material science and component integration are at the forefront of change, as suppliers adapt spindle designs to meet the dual demands of vehicle electrification and more stringent global emissions regulations. This evolution is redefining the component's role within the larger vehicle chassis system.
Advanced integrated wheel hub assemblies now combine the spindle with bearings and sensors for anti-lock braking and stability control systems. This technology is seeing rapid adoption by automakers in new passenger vehicle platforms. This level of component fusion is electrifying the suspension corner module, enabling more sophisticated vehicle dynamics control and paving the way for autonomous driving features.
Stringent emissions targets, particularly those set by the US Environmental Protection Agency and within the European Union, are a powerful force for design change. This regulatory pressure compels automakers to pursue weight reduction across every vehicle system to improve overall efficiency. The passenger and light commercial vehicle segments are most affected, accelerating the material shift from traditional forged steel to lighter aluminum alloy spindles.
Fleet operators are altering procurement patterns for maintenance and repair, favoring complete, pre-assembled corner modules over individual replacement parts. This change disrupts the traditional aftermarket channel, which relied on selling discrete components like spindles, bearings, and hubs separately. This behavior is most prominent in the North American and European commercial trucking industries, where minimizing vehicle downtime is a critical operational priority.
Wheel Spindle Market Segmentation
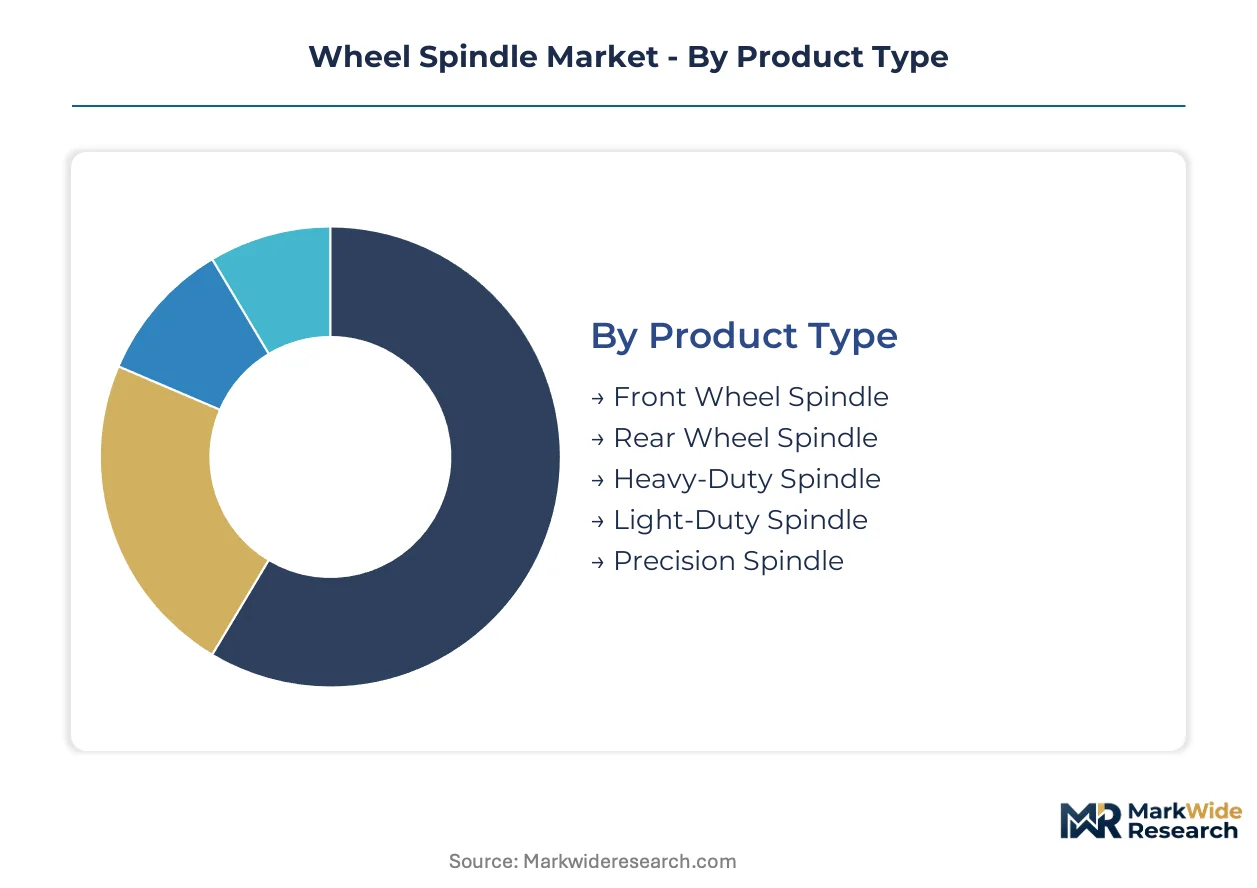
The wheel spindle market's intricate structure reflects diverse vehicle requirements and manufacturing processes. Understanding these segments clarifies the varying demands for material strength, precision engineering, and integration capabilities. This segmentation highlights the distinct challenges and opportunities across different vehicle types and operational contexts.
Product Type:
Supply concentration for specific product types is heavily influenced by the distinct manufacturing processes required for varying load capacities and material compositions.
- Heavy-Duty Spindle:Forged steel or high-strength cast iron forms these robust components, designed for extreme loads and continuous operation. Demand concentrates in commercial trucks and construction equipment, driven by uncompromised durability requirements.
- Light-Duty Spindle:These spindles often utilize aluminum alloys for weight reduction, critical for improving fuel efficiency and electric vehicle range. Passenger vehicles and light commercial vans drive demand, influenced by stringent emissions standards from the US EPA and EU.
- Front Wheel Spindle:This component integrates with steering systems, supporting the wheel and hub assembly at the vehicle's front.
- Rear Wheel Spindle:Designed for fixed or independent suspension setups, this spindle supports the rear wheel's rotation and load.
- Precision Spindle:Specialized manufacturing ensures minimal runout and high rotational accuracy for specific industrial or high-performance automotive applications.
Heavy-Duty Spindle absorbs the bulk of installed capacity; Light-Duty Spindle is expanding most quickly.
Material:
Application-specific demands dictate the choice of material, balancing performance characteristics with cost efficiency across the market.
- Forged Steel:This material provides exceptional strength and fatigue resistance, essential for components under high stress and impact. Commercial trucks, heavy-duty off-road vehicles, and construction equipment widely utilize forged steel due to its superior load-bearing capabilities.
- Aluminum Alloy:Offering significant weight reduction, aluminum alloy spindles contribute to improved vehicle efficiency and reduced unsprung mass. Passenger vehicles and electric vehicle platforms increasingly adopt aluminum alloys to meet stringent emissions targets and extend battery range.
- Cast Iron:A traditional material, cast iron spindles offer a cost-effective solution for certain light-duty and older vehicle applications.
- Carbon Steel:This material balances strength and cost, finding application in various standard automotive and industrial spindle designs.
- Composite Materials:Emerging composite materials aim for ultra-lightweight solutions, currently in research and niche high-performance applications.
Material innovations are largely bifurcated between Forged Steel for heavy-duty applications and Aluminum Alloy for lightweight passenger vehicles.
Application:
Volume requirements vary significantly across different vehicle applications, influencing production scale and design priorities for spindle manufacturers.
- Commercial Trucks:These vehicles demand robust and durable spindles capable of withstanding heavy loads and extensive mileage. Fleet modernization initiatives and growth in logistics sectors globally drive consistent demand for high-strength steel spindles.
- Passenger Vehicles:Spindles for passenger cars prioritize lightweighting and integration with advanced suspension systems for improved ride comfort and fuel economy. Global emissions regulations and the shift towards electric vehicles significantly influence material choices like aluminum alloys.
- Off-Road Vehicles:Spindles for off-road vehicles require enhanced durability and impact resistance to handle challenging terrains and harsh operating conditions.
- Agricultural Machinery:These applications demand robust spindles designed for heavy-duty, intermittent use in demanding farm environments.
- Construction Equipment:Spindles in construction equipment must endure extreme loads and abrasive conditions, necessitating maximum strength and wear resistance.
Demand across vehicle applications remains robust, with Passenger Vehicles representing the largest volume and Commercial Trucks showing dynamic growth.
End User:
Customer type defines distinct procurement channels and service requirements, from original equipment integration to aftermarket replacement parts.
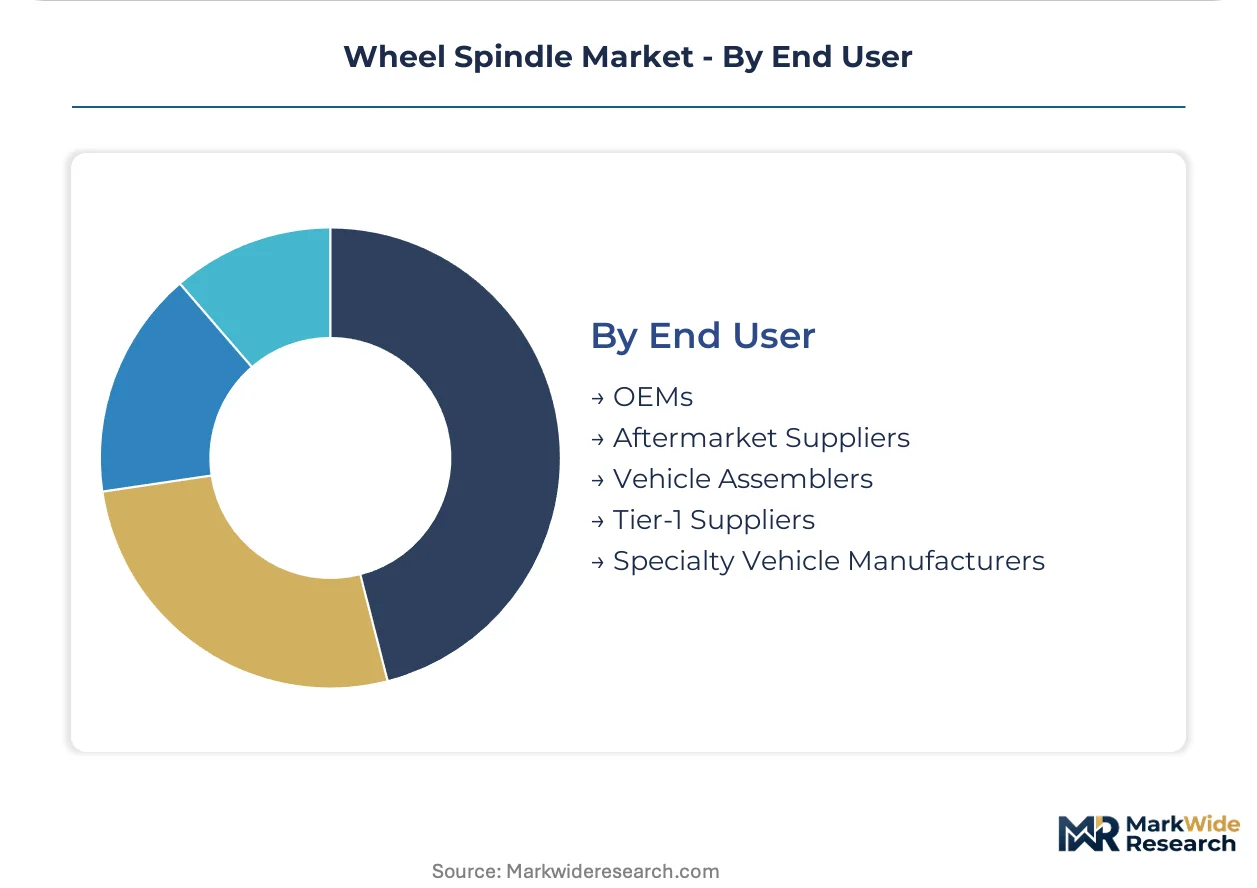
- OEMs:Original Equipment Manufacturers integrate spindles directly into new vehicle production lines, requiring high volume, specific design adherence, and rigorous quality control. Vehicle electrification and platform standardization dictate design and material specifications for OEM procurement.
- Aftermarket Suppliers:These suppliers provide replacement spindles for vehicle maintenance and repair, serving an aging global vehicle parc. Demand is influenced by vehicle longevity and the need for cost-effective, readily available components.
- Vehicle Assemblers:These entities integrate components from various suppliers to construct complete vehicles, often for niche or specialized markets.
- Tier-1 Suppliers:Tier-1 suppliers often design and manufacture complete axle systems or corner modules, integrating spindles into larger assemblies for OEMs.
- Specialty Vehicle Manufacturers:Companies producing custom or low-volume vehicles, such as recreational vehicles or defense vehicles, source specialized spindle solutions.
The shift towards integrated vehicle systems influences procurement patterns for both OEMs and Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's numerous special economic zones, including those in the Yangtze River Delta, drive significant manufacturing concentration for wheel spindles. These zones attract foreign investment and foster large-scale automotive production. This regional focus supports both domestic and export markets for critical vehicle components.
China
Demand for wheel spindles in China stems from massive automotive production and commercial truck fleet expansion. China's GB standards dictate material strength and testing protocols for automotive components. Manufacturing hubs like those in Shanghai and Guangzhou concentrate spindle production for domestic and international vehicle markets.
Germany
Germany's advanced automotive industry, including premium passenger vehicles and heavy commercial trucks, sustains demand for high-performance wheel spindles. EU General Safety Regulations require robust component integration for vehicle safety. The Bavaria region, home to major automotive OEMs and suppliers, drives innovation in spindle design and materials.
United States
Fleet modernization in the US commercial truck sector and lightweighting mandates for passenger vehicles fuel wheel spindle demand. The US National Highway Traffic Traffic Safety Administration (NHTSA) sets federal motor vehicle safety standards for component durability. Automotive clusters in Michigan and the Southeast focus on both original equipment and aftermarket spindle supply.
India
India's rapidly expanding automotive market and infrastructure development projects create substantial demand for wheel spindles. The Indian government's "Make in India" initiative encourages domestic manufacturing of auto components. Industrial corridors in Maharashtra and Tamil Nadu are emerging as key production centers for various spindle types.
Japan
Japan's precision engineering expertise and advanced vehicle manufacturing capabilities support demand for high-quality wheel spindles. Japanese Industrial Standards (JIS) ensure stringent quality control and performance benchmarks for automotive parts. The Aichi Prefecture, a major automotive production base, specializes in advanced spindle technology and integrated hub assemblies.
Wheel Spindle Market Key Industry Players
German and Japanese producers anchor one tier, emphasizing precision engineering and integrated systems; Chinese specialists hold significant positions in high-volume, cost-effective manufacturing. The wheel spindle market exhibits a tiered structure, with established Tier-1 suppliers focusing on advanced solutions and numerous regional players serving specific vehicle segments. Strategic archetypes include integrated system providers, precision component specialists, and heavy-duty application experts. Capacity expansion and strategic partnerships are dominant competitive moves.
Within the integrated system providers tier, ZF Friedrichshafen AG exemplifies expertise in drivetrain technology, often offering complete axle solutions. Schaeffler Group, a German-based company, sits within the precision component specialist archetype, focusing on advanced bearing technologies for spindle assemblies. Dana Incorporated represents a key player in heavy-duty applications, sustaining its market position through a focus on commercial vehicle and off-highway segments. These companies leverage their deep engineering capabilities to meet evolving OEM demands.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Schaeffler Group |
| JTEKT Corporation |
| Dana Incorporated |
| GKN Automotive |
| Hyundai Mobis |
| NTN Corporation |
| American Axle & Manufacturing |
| ThyssenKrupp AG |
| Others |
Cost & Logistics Intelligence
Captive supply arrangements and vertical integration choices anchor both the supply position and the pricing power for wheel spindle manufacturers. These strategic decisions directly influence cost structures and market responsiveness.
Pricing Analysis
Premium pricing for short lead times often dictates the market for specialized wheel spindles. The dominant pricing structure is contract-based long-term offtake for OEMs, with differentiation based on material composition like forged steel or aluminum alloy, and precision engineering. Pricing softness reflects raw material price volatility, impacting component manufacturers. Commercial truck OEMs are less price-sensitive due to durability requirements, while aftermarket suppliers face greater cost pressure.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for wheel spindles. Geographic supply concentration centers in China, Germany, and Japan, with significant raw material dependencies on high-strength steel and specialty aluminum alloys. Single-source vulnerability for advanced forging capabilities represents a structural risk. Distribution runs through a dual channel of direct OEM supply and an extensive aftermarket network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story, where stringent US NHTSA federal motor vehicle safety standards create a barrier-to-entry moat for compliant players. Meeting these rigorous requirements demands significant investment in material science and testing protocols.
For Market Incumbents:Extend material science research into hybrid components, combining steel's strength with aluminum's lightweight properties for specific applications. Invest in advanced manufacturing capabilities within key regions like Germany and the United States to mitigate supply chain risks. This proactive approach helps counter the threat from new material entrants and evolving regulatory demands. Strengthen relationships with Tier-1 suppliers to co-develop integrated e-axle systems.
For New Entrants and Emerging Players:EU General Safety Regulations in Europe opens a window for new entrants to offer specialized, high-strength aluminum alloy spindles for passenger vehicles. Target the light-duty segment, especially for electric vehicle platforms requiring optimized weight and performance. A go-to-market angle focusing on rapid prototyping and customizable solutions for smaller EV manufacturers can establish early market presence. Pursue certifications like ISO 9001 to ensure quality and compliance.
For Investors and Strategic Acquirers:Exit pathways concentrate in integrated system providers and precision component specialists, offering long-term viability within the evolving automotive sector. Target companies with patented material technologies or advanced manufacturing processes for next-generation EV architectures. The increasing adoption rate of complete e-axle systems serves as a critical inflection indicator. Focus on firms with strong OEM relationships in high-growth regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Material Development | Optimizes spindle performance by combining steel's strength with aluminum's light weight. |
| E-Axle System Integration | Positions firms to capitalize on the shift towards electric vehicle architectures. |
| Advanced Forging Capacity Expansion | Mitigates supply chain vulnerabilities and meets demand for complex geometries. |
| Aftermarket Channel Optimization | Captures value from an aging global vehicle parc requiring replacement parts. |
| Regional Manufacturing Diversification | Reduces geopolitical risks and strengthens localized supply for key automotive markets. |
Research Approach
Automotive production databases, trade association reports, and government transportation statistics formed the secondary backbone for this analysis. Primary research involved in-depth interviews with OEM procurement managers, Tier-1 engineers, aftermarket distributors, and material science experts across multiple regions. This approach ensured a robust bottom-up and top-down triangulation of market data.
Historical trendline analysis provided the foundation for projecting future market trajectories across the analysis window. The analytical framework modeled key segmentation dimensions including product type, material, application, end user, and vehicle propulsion architecture. Compound annual growth rates were derived from a synthesis of historical performance and anticipated technological shifts. Vehicle production forecasts and raw material price trends served as critical industry-specific inputs.
Caveats apply where raw material price volatility or geopolitical trade shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory stability and technological adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Sideloaders Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Latin America Two-Wheeler Components Market