
 Global Automotive Constant Vehicle Joint Boots Market | 2026-2036
Global Automotive Constant Vehicle Joint Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Constant Vehicle Joint Boots Market Intelligence
The shift from traditional rubber to advanced thermoplastic elastomers (TPEs) is tilting material science priorities within CV joint boot production. This change pressures incumbents to retool manufacturing processes away from vulcanization. GKN Automotive Limited leverages its extensive OEM relationships to introduce new TPE-based solutions across passenger car platforms. Trelleborg AB specializes in high-performance polymer engineering for demanding off-road vehicle applications, while SKF Group controls a significant portion of the aftermarket through its established global distribution network.
An automotive constant velocity (CV) joint boot is a flexible, bellows-like covering that protects the CV joint from contaminants like dirt and water. These components are engineered from materials like neoprene or TPE to withstand extreme temperatures and constant flexing while retaining grease. Their primary purpose is to ensure the longevity and proper function of the vehicle's drivetrain. While rubber boots remain a significant portion of the aftermarket, thermoplastic elastomer boots are seeing rapid adoption among OEMs for passenger cars.
Material composition and end-of-life vehicle requirements are influenced by regulations such as the EU's REACH and the US EPA's guidelines on polymer disposal. In China, GB standards dictate material performance and durability testing for all automotive components. These frameworks compel manufacturers to invest in compliant and sustainable material science. Supplier selection will increasingly depend on the ability to provide materials that meet a complex matrix of performance, cost, and environmental criteria.
Market Dynamics
The fundamental dynamic shaping the automotive CV joint boot market is the material science transition from traditional thermoset rubbers to recyclable thermoplastic elastomers. This shift is driven by a convergence of stringent environmental regulations and OEM demands for lighter, more durable components, forcing a complete re-evaluation of manufacturing processes, supply chains, and material sourcing priorities.
Growth Catalysts
- Advanced Material Adoption:The rapid adoption of thermoplastic elastomers (TPEs) in new passenger vehicle platforms offers superior temperature resistance, lower weight, and design flexibility compared to traditional neoprene, aligning with OEM efficiency goals.
- Commercial Vehicle Fleet Expansion:Sustained growth in logistics and construction is expanding the global fleet of commercial trucks, where the demand for highly durable, long-lasting CV joint boots to minimize downtime is a primary purchasing driver.
- Environmental Regulations:Mandates like the EU Green Deal and its focus on circular economy principles create a strong preference for recyclable TPEs over vulcanized rubber, which is difficult to process at its end of life.
Market Restraints
- High Retooling Costs:Shifting production from rubber vulcanization to TPE injection molding requires significant capital investment in new machinery and molds, creating a barrier for smaller, incumbent manufacturers.
- Aftermarket Price Sensitivity:The aftermarket segment remains dominated by low-cost neoprene rubber boots, whose price point creates a significant hurdle for the adoption of more expensive, higher-performance TPE alternatives in repair shops.
- Supply Chain Concentration:Heavy reliance on automotive manufacturing clusters in specific regions, particularly in China, exposes the supply chain to significant disruption risk from localized logistical, political, or economic events.
Strategic Opportunities
- High-Performance Niche Applications:There is a distinct opportunity to develop specialized, high-margin TPE and advanced polymer boots engineered specifically for the extreme torque and environmental demands of off-road, agricultural, and military vehicles.
- Recyclability as a Service:Suppliers can create value by establishing certified end-of-life collection and recycling programs for TPE boots, helping OEMs meet circular economy targets mandated by regulations like the EU's ELV Directive.
- Emerging Market OEM Integration:As new automotive production facilities are established in regions like Southeast Asia and Mexico, suppliers have a greenfield opportunity to specify TPE solutions from the outset, bypassing legacy rubber dependencies.
Industry Challenges
- Dual-Material Supply Management:Manufacturers face the operational complexity of managing two distinct supply chains, one for legacy rubber components for the aftermarket and another for advanced TPEs for OEM clients.
- Regulatory Standard Fragmentation:Compliance is complicated by the need to meet a patchwork of differing regional standards, such as China's GB standards for durability testing and Europe's REACH regulations on chemical composition.
- Component Integration and Validation:Ensuring that a new TPE boot design maintains a perfect seal and flexural endurance with dozens of existing CV joint models requires extensive and costly vehicle-specific testing and validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Constant Vehicle Joint Boots Market |
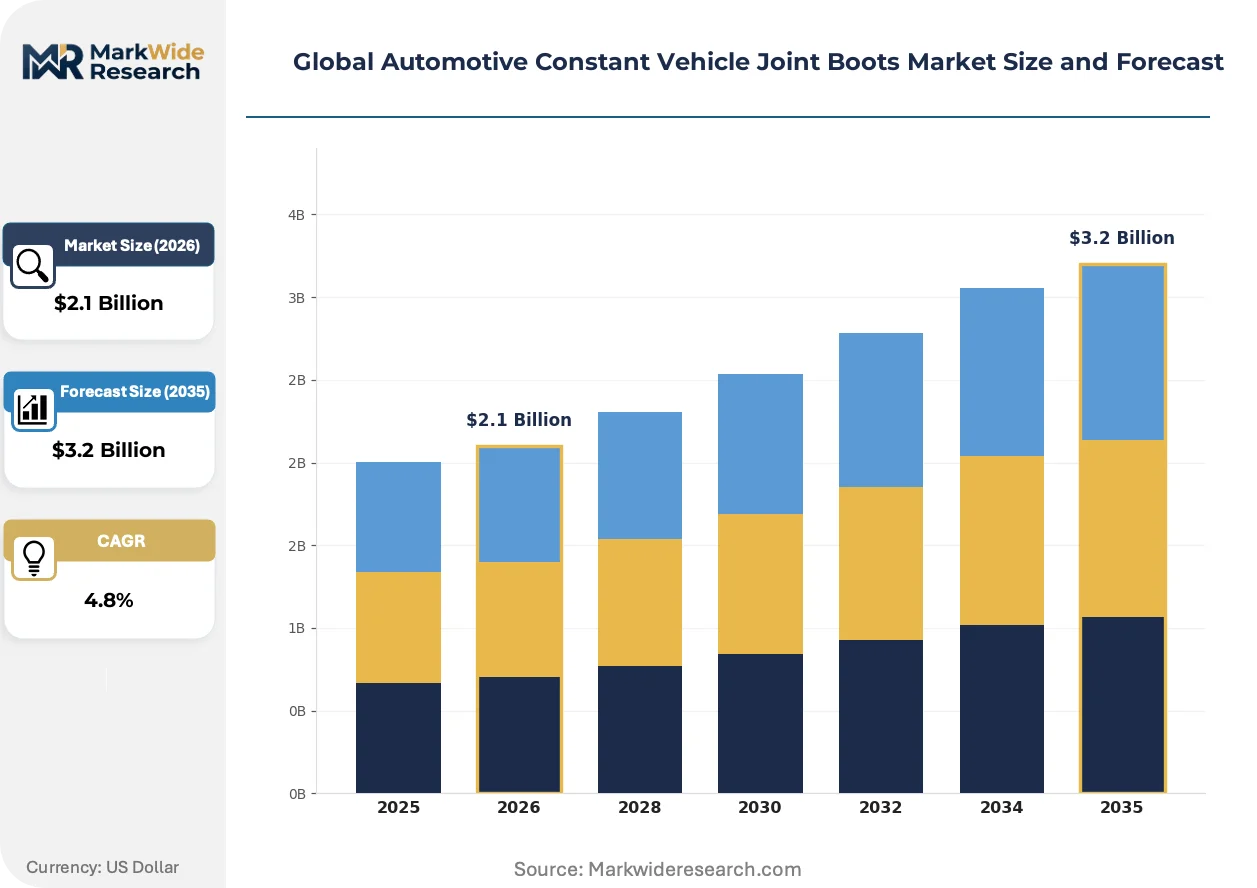
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Boots, Neoprene Boots, Thermoplastic Elastomer Boots, Silicone Boots, Polyurethane Boots Technology: Injection Molding, Compression Molding, Extrusion, Blow Molding, Vulcanization Application: Passenger Cars, Commercial Trucks, Off-road Vehicles, Recreational Vehicles, Agricultural Machinery End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Maintenance Workshops |
| Companies Covered | SKF Group, Trelleborg AB, GKN Automotive Limited, NOK Corporation, Federal-Mogul LLC, Freudenberg Group, Sumitomo Riko Company Limited, Hutchinson SA, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Constant Vehicle Joint Boots Market Strategic Shifts & Innovations
Material science advancements are at the core of market evolution, driven by the dual pressures of environmental compliance and enhanced vehicle performance. Innovations focus on creating lighter, more resilient components that contribute to overall drivetrain efficiency and sustainability. This pushes development beyond simple material substitution toward a holistic redesign of the component's life cycle.
Thermoplastic elastomers (TPEs) provide a recyclable, lightweight alternative to traditional rubber. Automakers are rapidly adopting TPEs for passenger car platforms to meet weight reduction and sustainability targets. Consequently, the market's material foundation is migrating from energy-intensive vulcanized rubber manufacturing to more efficient TPE injection molding processes, altering the industry's capital and chemical engineering requirements.
Regulations such as the EU's End-of-Life Vehicles (ELV) Directive and REACH framework exert significant influence. These rules compel manufacturers to increase the recyclability of components and restrict the use of certain hazardous substances common in rubber formulations. This directly impacts material selection, forcing suppliers targeting the European market to prioritize compliant TPEs and provide detailed substance documentation.
A notable shift in OEM sourcing behavior is the inclusion of life-cycle sustainability as a key procurement metric. This change moves supplier evaluation beyond the traditional criteria of cost and performance, creating an advantage for vendors who can provide verifiable data on a component's carbon footprint and recyclability. This demand-side evolution is most advanced among European automakers and global brands with strong corporate social responsibility mandates.
Global Automotive Constant Vehicle Joint Boots Market Segmentation
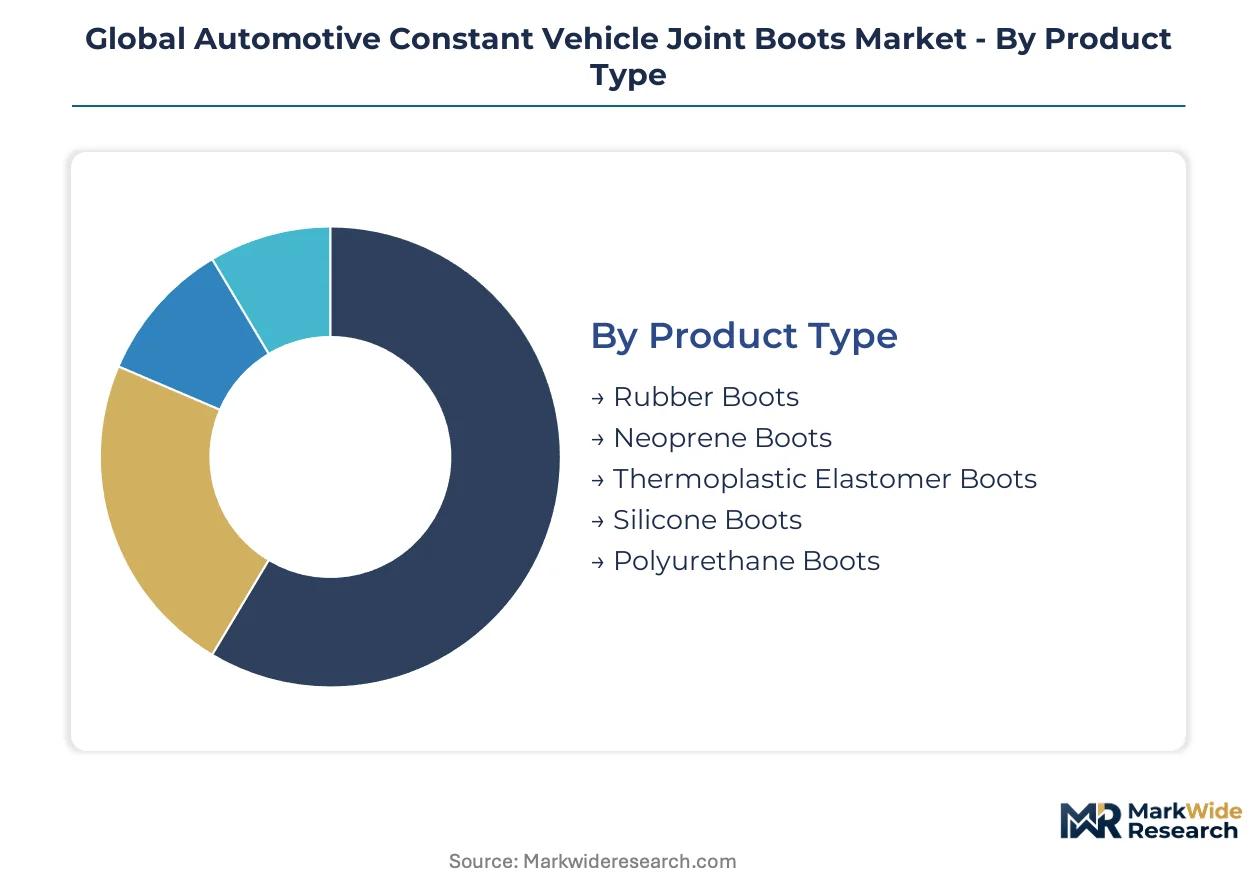
The automotive constant vehicle joint boots market segmentation reflects diverse material science, manufacturing processes, and end-use requirements. Understanding these distinct segments is crucial for manufacturers to tailor product development and market strategies. This segmentation highlights the varying demands across vehicle types and customer bases.
Product Type:
The intensity of after-sales service and replacement cycles significantly influences the demand for various CV joint boot product types. Material durability directly impacts service intervals and customer satisfaction.
- Thermoplastic Elastomer Boots:These components offer superior temperature resistance and flexibility, commonly used in modern passenger car platforms. Automakers prioritize TPE boots for their recyclability and contribution to vehicle weight reduction targets, aligning with environmental mandates like the EU Green Deal.
- Rubber Boots:Traditional rubber boots provide a cost-effective solution, widely used in the aftermarket for replacement parts due to their established manufacturing processes. Their vulcanized nature makes end-of-life recycling challenging, but their widespread availability supports repair networks globally.
- Neoprene Boots:Neoprene offers good resistance to oils and greases, finding application in various automotive and industrial settings.
- Silicone Boots:Silicone materials provide excellent high-temperature performance, suitable for specialized applications requiring extreme heat resistance.
- Polyurethane Boots:Polyurethane boots offer high abrasion resistance and tear strength, often chosen for heavy-duty or performance-oriented applications.
Rubber Boots holds the largest share; momentum sits with Thermoplastic Elastomer Boots.
Technology:
Supply chain concentration for manufacturing processes dictates the efficiency and scalability of CV joint boot production. Different technologies cater to specific material properties and volume requirements.
- Injection Molding:This high-volume manufacturing process is ideal for thermoplastic elastomers, allowing for complex geometries and efficient production cycles. It supports the rapid adoption of TPE boots in new vehicle production, particularly for OEMs seeking consistent quality.
- Vulcanization:A traditional process for thermoset rubbers, vulcanization involves chemical cross-linking to enhance material properties like elasticity and durability. This method remains prevalent for producing rubber and neoprene boots, primarily serving the aftermarket segment.
- Compression Molding:Compression molding is a versatile process for thermosetting materials, offering good material utilization and part integrity. This technology is suitable for medium-volume production runs of rubber-based boots.
- Extrusion:The extrusion process creates continuous profiles, which are then cut and formed into boot shapes. This method can be cost-effective for certain material types and simpler designs.
- Blow Molding:Blow molding is employed for hollow components, providing design flexibility for specific boot configurations. This technology is less common but offers benefits for intricate shapes.
Injection Molding is gaining traction as manufacturing shifts toward TPEs, while Vulcanization maintains a significant volume.
Application:
The diverse application landscape for CV joint boots highlights distinct performance requirements across various vehicle categories. Each application demands specific material properties and design considerations.
- Commercial Trucks:These vehicles require highly durable and robust CV joint boots capable of withstanding heavy loads, continuous operation, and harsh environmental conditions. The focus is on minimizing downtime and maximizing longevity, driving demand for premium materials.
- Passenger Cars:The largest segment by volume, passenger cars prioritize lightweight design, fuel efficiency, and long-term reliability for CV joint boots. OEMs increasingly adopt TPE solutions to meet stringent emissions standards and enhance vehicle performance.
- Off-road Vehicles:Off-road applications demand extreme resistance to punctures, abrasion, and environmental contaminants like mud and water.
- Recreational Vehicles:RVs require boots that can endure varied road conditions and extended periods of use, balancing durability with cost-effectiveness.
- Agricultural Machinery:Boots for agricultural equipment must withstand harsh outdoor environments, exposure to chemicals, and heavy operational stresses.
Passenger Cars command the largest share, with Commercial Trucks exhibiting a strong expansion trajectory.
End User:
The distinct purchasing behaviors and supply chain dynamics of various end-user segments shape the market's demand patterns. Each end-user group has unique priorities regarding cost, performance, and material specifications.
- OEMs:Original Equipment Manufacturers integrate CV joint boots into new vehicle production, driving demand for advanced materials like TPEs that support lightweighting and sustainability goals. OEMs require extensive testing and validation for component integration.
- Aftermarket Providers:This segment supplies replacement CV joint boots for vehicle repairs and maintenance, primarily focusing on cost-effective rubber and neoprene solutions. Distribution networks and product availability are critical for aftermarket success.
- Tier-1 Suppliers:These suppliers manufacture and assemble complex modules for OEMs, including CV joint assemblies, influencing material selection and technology adoption.
- Vehicle Assemblers:Vehicle assemblers integrate components from various suppliers into the final product, requiring reliable and readily available CV joint boot solutions.
- Maintenance Workshops:These workshops perform repairs and replacements, influencing demand for aftermarket parts based on customer needs and availability.
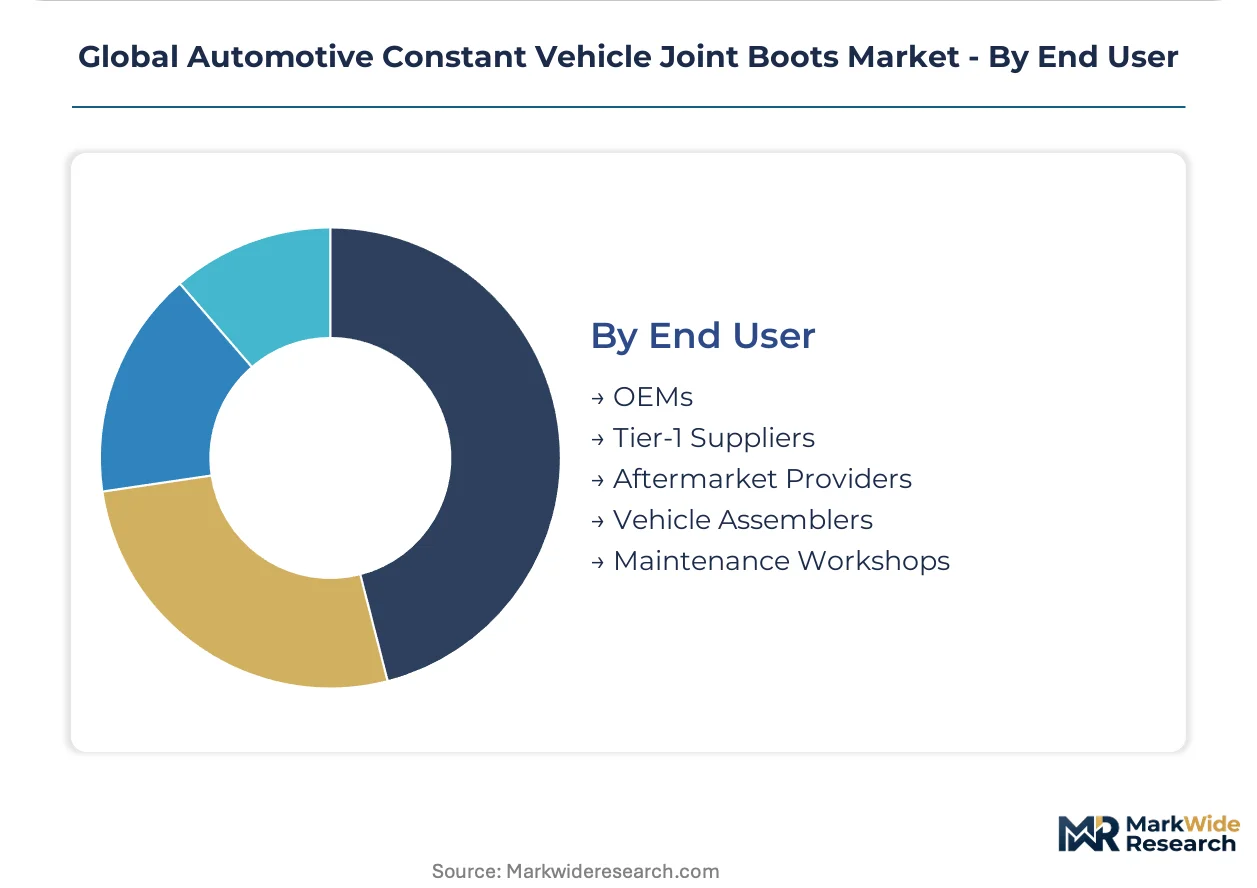
OEMs represent a significant portion of new component demand, while Aftermarket Providers contribute substantial volume through replacement sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEMs and aftermarket providers globally concentrate demand for automotive CV joint boots in key manufacturing hubs and mature vehicle markets. This dual-channel procurement strategy influences material adoption rates and technology preferences across regions. Consequently, suppliers must align their offerings with localized regulatory frameworks and customer requirements.
China
China's robust automotive manufacturing clusters drive significant demand for CV joint boots, particularly with its expanding commercial truck fleet. The country's GB standards dictate stringent material performance and durability testing for all automotive components. Manufacturing hubs like the Yangtze River Delta and Pearl River Delta are key production and consumption centers.
Germany
German automakers prioritize advanced TPE solutions for passenger cars, driven by stringent efficiency and sustainability targets. The EU Green Deal and REACH regulations compel manufacturers to adopt recyclable materials and restrict hazardous substances. Automotive production centers in Bavaria and Baden-Württemberg lead the integration of these compliant components.
United States
The United States represents a substantial market for both OEM and aftermarket CV joint boots, with a growing emphasis on TPE solutions. US EPA guidelines on polymer disposal influence material selection for automotive components. Detroit and other Michigan-based automotive clusters are pivotal for new vehicle integration and aftermarket distribution.
Japan
Japanese automotive manufacturers focus on high-performance CV joint boots to ensure long-term vehicle reliability and efficiency. JIS standards guide material performance and quality control for critical automotive parts. Aichi Prefecture, home to major automotive OEMs, remains a significant hub for innovative component development and integration.
Global Automotive Constant Vehicle Joint Boots Market Key Industry Players
Channel-controlling players compete with product-specialist players for dominance in the automotive CV joint boot market. The market structure exhibits a tiered consolidation, with large, diversified suppliers holding significant OEM contracts and smaller, agile firms serving niche aftermarket segments. Strategic archetypes include vertically integrated component manufacturers, material science innovators, and aftermarket distribution specialists. Competitive moves frequently involve strategic partnerships with OEMs and targeted capacity expansions to meet TPE demand.
Among the established suppliers, GKN Automotive Limited represents a key player with extensive OEM relationships, leveraging its global footprint to introduce new TPE-based solutions across passenger car platforms. Trelleborg AB, a Swedish-based engineering group, exemplifies high-performance polymer engineering for demanding applications like off-road vehicles, showcasing material innovation. SKF Group, another Swedish industrial giant, anchors a significant portion of the aftermarket through its established global distribution network, offering both traditional rubber and advanced TPE boot solutions to a broad customer base.
| Leading Market Players |
|---|
| SKF Group |
| Trelleborg AB |
| GKN Automotive Limited |
| NOK Corporation |
| Federal-Mogul LLC |
| Freudenberg Group |
| Sumitomo Riko Company Limited |
| Hutchinson SA |
| Dana Incorporated |
| Others |
Cost & Logistics Intelligence
Maritime shipping lanes, particularly from Asian manufacturing hubs, dictate the inbound cost dynamics for raw materials and components, influencing both supply concentration and downstream price differentiation for CV joint boots.
Pricing Analysis
Cost-plus contract patterns, often indexed to polymer and rubber commodity prices, govern OEM procurement of CV joint boots. Pricing differentiates primarily by material composition, with TPE boots commanding a premium over traditional rubber due to performance and recyclability. Volume scale also provides significant pricing leverage for large OEM orders. Pricing pressure from OEMs intensifies as they seek to meet aggressive cost reduction targets. The aftermarket segment remains highly price-sensitive, favoring cost-effective neoprene and rubber solutions for repairs.
Supply Chain Analysis
Contract manufacturing capacity for CV joint boots concentrates heavily in automotive manufacturing clusters across China, Germany, and Japan. The supply chain relies on a consistent flow of thermoplastic elastomers and specialized rubber compounds. Geopolitical tensions or localized logistical disruptions in these key regions pose a structural risk to global supply. Distribution runs through direct channels for OEMs and extensive independent aftermarket networks for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The increasing consolidation among OEMs is shifting buyer power, creating new strategic imperatives for suppliers in the automotive CV joint boot market.
For Market Incumbents: Pre-empt material science disruptions by accelerating investment in advanced TPE formulations and efficient injection molding capabilities. Leverage existing OEM relationships to co-develop next-generation solutions, mitigating the threat from new entrants specializing in sustainable materials. Expand TPE manufacturing capacity in strategic regions to address future demand and regulatory shifts.
For New Entrants and Emerging Players: High-performance niche applications for off-road, agricultural, and military vehicles represent the most penetrable entry point. Target specialized TPE solutions engineered for extreme torque and environmental demands. Offer certified end-of-life collection and recycling programs as a key go-to-market differentiator, aligning with circular economy mandates.
For Investors and Strategic Acquirers: Material science innovators specializing in advanced thermoplastic elastomers present compelling acquisition targets for long-term viability. These firms often possess critical intellectual property and R&D capabilities essential for future market leadership. Monitor OEM adoption rates of TPEs in new passenger car platforms as a key signal for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| TPE Manufacturing Capacity Expansion | Increases ability to meet growing OEM demand for sustainable and lightweight components. |
| Green Manufacturing Process Integration | Aligns production with stringent environmental regulations like the EU Green Deal. |
| Long-term OEM Supply Agreements | Secures stable revenue streams and reinforces market position with major automotive brands. |
| High-Performance Polymer R&D | Drives innovation for specialized applications like off-road and commercial truck segments. |
| Geographic Manufacturing Footprint Diversification | Mitigates supply chain disruption risks concentrated in specific automotive clusters. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, automotive manufacturing data, and regulatory filings. This included in-depth interviews with OEM procurement managers, Tier-1 suppliers, aftermarket distributors, and material scientists. Both bottom-up and top-down triangulation validated the market size and growth projections.
Forecast inputs considered vehicle production volumes, material adoption rates, and regulatory compliance timelines across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, and regional manufacturing clusters. Compound Annual Growth Rates were derived from historical trends and projected market shifts, incorporating TPE cost curves and end-of-life vehicle directives.
Practitioners should monitor geopolitical events, material science breakthroughs, and shifts in environmental policy for early signals of market revision. Forecasts reflect assumptions concerning supply chain stability and consistent regulatory enforcement. Monthly review of OEM material specifications and regional regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Snowplows Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Trailer Canopy Market