
 Germany Automotive Parts Zinc Die Casting Market | 2026-2036
Germany Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Parts Zinc Die Casting Market Foresight
Poland is fragmenting as a competitive production zone for German automotive zinc die casting, drawing sub-supply investment away from traditional Saxon and Bavarian strongholds. Druckguss Westfalen GmbH & Co KG anchors its position through captive finishing lines serving Rheinmetall AG. Rheinmetall AG leverages its defense-automation crossover to sustain dual-use casting expertise. Kalmbach GmbH differentiates via precision housing outputs for electric drivetrain architectures.
Zinc die casting for automotive parts involves injecting molten zinc alloy under high pressure into steel molds to produce complex, thin-walled components with dimensional tolerances reaching ±0.02 mm; the process yields parts with excellent corrosion resistance and surface finish suitable for direct coating or assembly. Engine components retain the largest volume share among product types due to persistent internal combustion production lines, though structural parts for battery enclosures and motor housings represent the fastest-expanding category as electrification penetrates German OEM portfolios. Tier-1 suppliers dominate the end-user channel, capturing margin pools through long-term program contracts while aftermarket providers occupy a narrower, price-sensitive niche.
KBA homologation requirements and REACH compliance obligations on zinc alloy composition shape material sourcing decisions and foundry qualification protocols across German supply chains. The EU Green Deal's embodied carbon tracking provisions pressure casters to document smelting energy sources and scrap recycling rates. Stakeholders must monitor how CSRD disclosure mandates alter OEM supplier scorecards and whether KBA updates alloy purity thresholds for safety-critical brake and steering castings.
Market Dynamics
KBA material traceability mandates are compressing supplier qualification timelines while OEM electrification roadmaps redirect die casting volumes toward battery and motor housing architectures. Tier-1 procurement teams now weight embodied carbon documentation as heavily as piece-price in source selection.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Casters documenting smelting energy sources and scrap recycling rates gain preferred supplier status with Stuttgart and Munich OEM program offices.
- Transmission case lightweighting:Fuel efficiency targets under WLTP protocols sustain demand for thin-walled zinc housings in hybrid powertrain production lines.
- Baden-Württemberg supplier clustering:Proximity to Porsche and Mercedes-Benz assembly plants reduces logistics costs and supports just-in-sequence delivery models.
Market Restraints
- Primary zinc price volatility:Smelter energy cost spikes in Nordrhein-Westfalen feed through to foundry margin compression on fixed-price program contracts.
- Polish production zone fragmentation:Sub-supply investment migration to Lower Silesia hollows out traditional Saxon casting employment bases.
- REACH alloy composition compliance:Cadmium and lead threshold restrictions limit secondary scrap feedstock pools and raise raw material certification costs.
Strategic Opportunities
- CSRD disclosure mandates:First-mover casters building Scope 3 data infrastructure capture OEM supplier scorecard premiums ahead of 2025 reporting deadlines.
- Electric drivetrain motor housings:Precision zinc architectures for 800V inverter enclosures represent uncontracted white space as EV platforms multiply.
- Dual-use defense crossover:Rheinmetall AG automation expertise creates transferable know-how for safety-critical brake and steering component production.
Industry Challenges
- CNC finishing skill scarcity:Captive machining lines require toolpath programmers with simultaneous five-axis experience that vocational pipelines in North Rhine-Westphalia undersupply.
- KBA homologation timeline compression:Safety-critical brake casting approvals now demand 18-month validation cycles that mismatch with 12-month OEM platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Parts Zinc Die Casting Market |
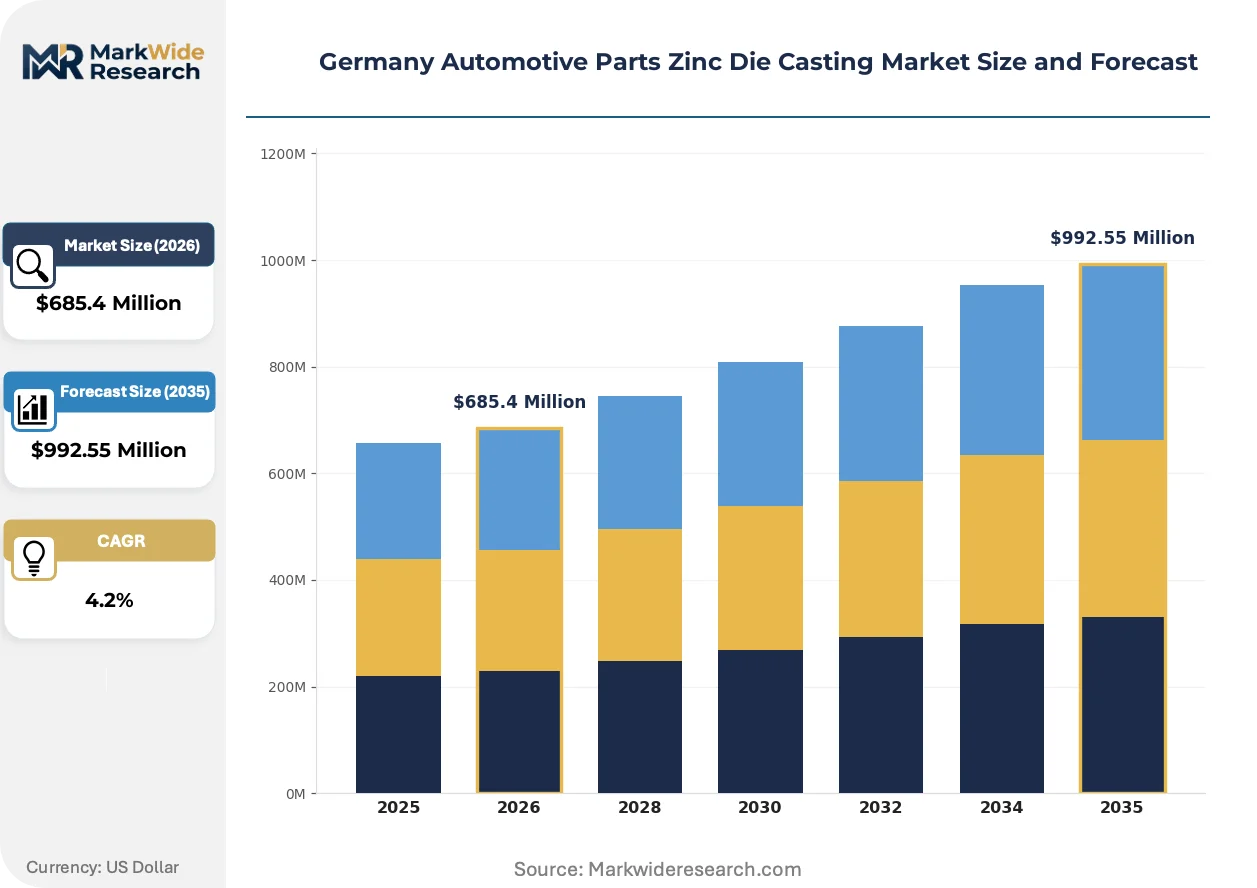
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Structural Parts, Housing End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Prototype, Production, Assembly, Finishing Material Grade: High Strength, Corrosion Resistant, Standard, Others |
| Companies Covered | GP Diecasting, Breuckmann GmbH & Co. KG, Druckguss Westfalen GmbH & Co KG, Brillcast Manufacturing LLC, Kalmbach GmbH, Druckguss Westfalen Behringer, Schweizer Group Global GmbH, Rheinmetall AG, Wolf Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Parts Zinc Die Casting Market Shifts & Advancements
Process intelligence and regulatory transparency are converging to reshape how German zinc die casters qualify for OEM programs. Digital thread technologies now trace alloy provenance from smelter to finished component.
Real-time melt monitoring via laser-induced breakdown spectroscopy is digitizing alloy chemistry verification at the ladle level. Druckguss Westfalen and comparable tier-1 suppliers deploy these sensors to eliminate batch-to-batch variation before injection. The technology compresses laboratory testing cycles from hours to seconds while generating the data trails KBA traceability rules require.
CSRD disclosure mandates are forcing foundries to install energy metering at cell level rather than plant level. German automotive suppliers now demand supplier-specific carbon intensity figures for each casting shipment. Tier-1 procurement teams in Stuttgart exclude vendors unable to provide smelter-origin certificates documenting renewable energy share.
Aftermarket channel consolidation is altering how replacement brake and transmission castings reach workshops. Independent distributors in Bavaria are losing shelf space to OEM-captive parts programs tied to service contracts. Procurement teams at large fleet operators now bypass traditional wholesale tiers, sourcing directly from certified foundries with VDA 6.3 process audits.
Germany Automotive Parts Zinc Die Casting Market Segmentation
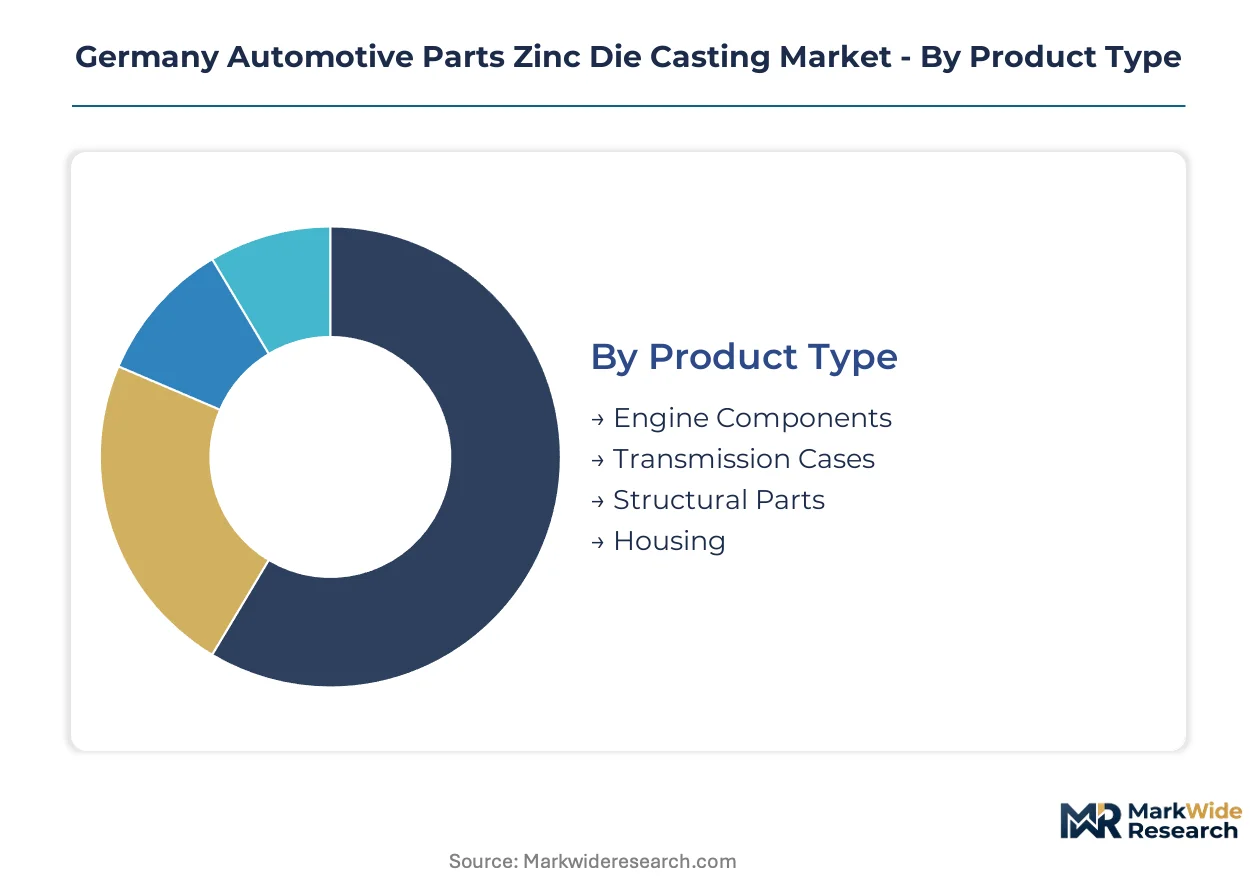
German zinc die casting supply chains fragment across product architectures, procurement channels, and material specifications. Each segmentation axis reveals distinct margin pools and qualification barriers that shape competitive positioning.
Product Type:
Component complexity spans precision-machined engine internals to single-cast structural enclosures, with each tier demanding different tooling investments and surface finish protocols.
- Engine Components:Cylinder head covers, timing chain housings, and oil pump bodies require high-pressure injection parameters to achieve porosity standards below 0.5 percent. Mercedes-Benz and Porsche powertrain programs in Stuttgart sustain volume concentration here despite electrification headwinds.
- Transmission Cases:Thin-walled housings for dual-clutch and automated manual gearboxes dominate Baden-Württemberg output. WLTP fuel efficiency mandates preserve demand as hybrid architectures retain multi-speed transmissions.
- Structural Parts:Battery tray brackets and motor mounting interfaces serve emerging EV platforms.
- Housing:Sensor enclosures and electronic control unit shells prioritize electromagnetic shielding properties.
The dominant share belongs to Engine Components, while Transmission Cases is closing the gap fastest.
End User:
Procurement authority concentrates with entities controlling program gate decisions and homologation timelines.
- OEMs:Direct sourcing relationships with Mercedes-Benz, BMW, and Volkswagen AG require VDA 6.3 process audits and KBA traceability documentation. These programs carry 36-48 month lifecycles with penalty clauses for delivery variance.
- Tier-1 Suppliers:ZF Friedrichshafen and Continental AG aggregate casting demand across multiple OEM platforms. Their supplier scorecards weight carbon intensity metrics equally with piece-price, reshaping foundry investment priorities.
- Aftermarket Providers:Independent distributors serve brake and transmission replacement demand through catalog-based procurement.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source limited volumes for niche production runs.
Tier-1 Suppliers command the largest procurement volume, yet OEM direct sourcing is expanding most quickly as CSRD disclosure mandates tighten supply chain visibility requirements.
Manufacturing Stage:
Value capture shifts dramatically across the process chain, from tool steel depreciation to CNC finishing labor premiums.
- Production:High-pressure die casting cells operating at 600-1,000 metric tons clamping force generate the bulk of sector revenue. Druckguss Westfalen and comparable operators run 24-hour cycles feeding just-in-sequence lines.
- Finishing:Deburring, shot blasting, and precision machining add 15-25 percent value uplift but require scarce five-axis programming talent that North Rhine-Westphalia vocational pipelines undersupply.
- Prototype:Soft tooling and gravity casting methods validate designs before hard die investment.
- Assembly:Sub-component integration and kitting operations cluster near Stuttgart assembly corridors.
Production retains the dominant revenue position, though Finishing is climbing fastest as OEMs outsource more value-added processing.
Material Grade:
Alloy specification directly determines KBA homologation eligibility and safety-critical application scope.
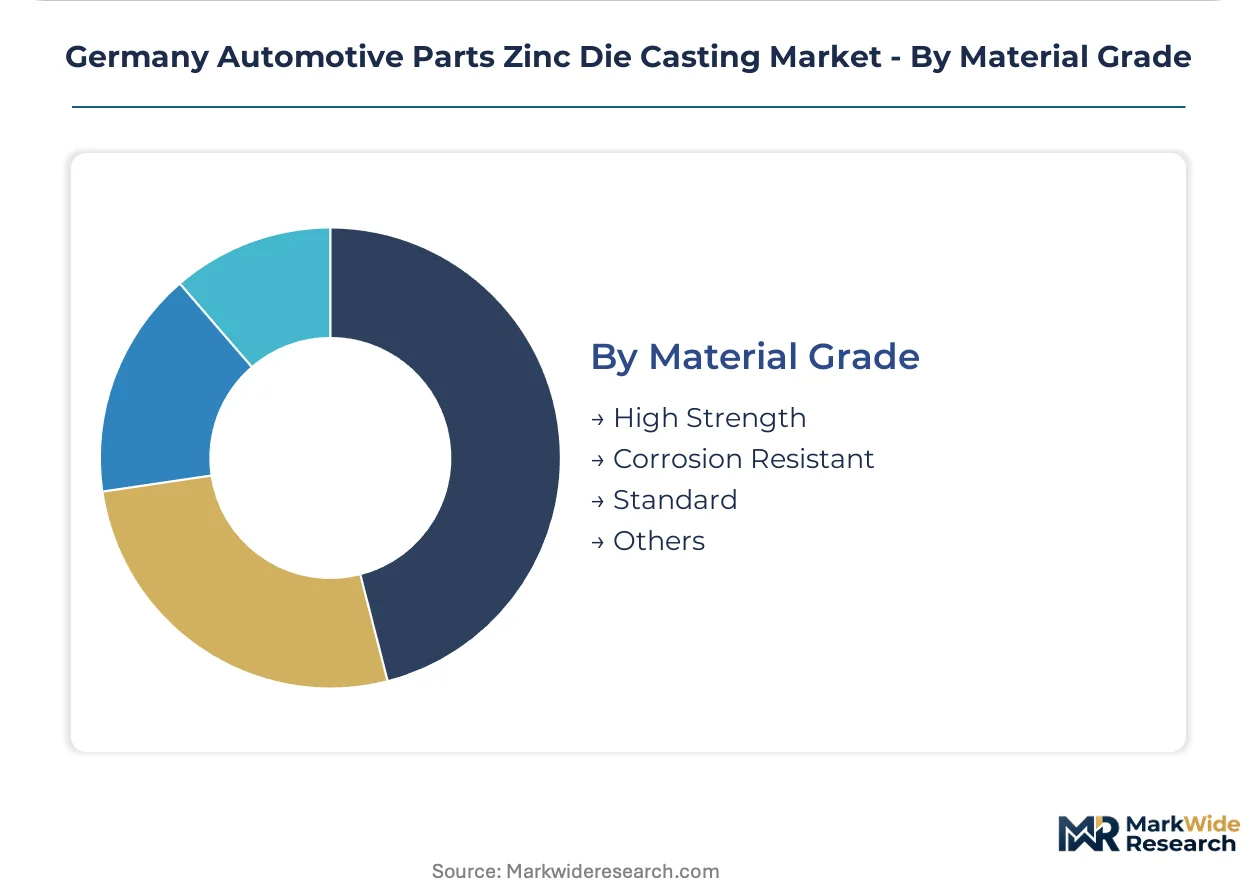
- High Strength:Zamak 5 and comparable alloys with 4 percent aluminum content deliver tensile properties exceeding 330 MPa. Brake caliper and steering knuckle applications in Munich-assembled vehicles mandate this grade exclusively.
- Corrosion Resistant:Specialized compositions with magnesium additions suit underbody and exposed architectural components. REACH compliance on cadmium and lead thresholds limits secondary scrap feedstock availability, raising certification costs.
- Standard:General-purpose Zamak 3 serves non-structural housings and decorative trim.
- Others:Experimental alloys for thermal management and electromagnetic applications remain developmental.
High Strength commands the dominant specification share, while Corrosion Resistant is gaining share fastest as OEMs extend warranty coverage on exposed components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Die casting capacity concentrates in Germany's southwestern and western industrial corridors, with supplier clusters aligning to Stuttgart and Munich assembly belts. KBA traceability mandates and REACH compliance obligations shape material sourcing decisions across these production zones.
Baden-Württemberg
Porsche and Mercedes-Benz powertrain programs sustain demand for thin-walled transmission housings and engine components. KBA homologation requirements enforce 18-month validation cycles for safety-critical brake castings. Stuttgart's tier-1 supplier density supports just-in-sequence delivery models to nearby assembly plants.
North Rhine-Westphalia
Druckguss Westfalen and comparable operators run 24-hour high-pressure die casting cycles feeding Rheinmetall AG defense-automation crossover programs. REACH alloy composition rules on cadmium and lead thresholds limit secondary scrap feedstock availability. Düsseldorf-Cologne corridor foundries face margin compression from smelter energy cost spikes.
Bavaria
BMW Group electrification roadmaps redirect die casting volumes toward battery tray brackets and motor mounting interfaces. The EU Green Deal's embodied carbon tracking provisions pressure Munich-area casters to document renewable energy shares. Nuremberg-Augsburg supplier clusters serve emerging 800V inverter enclosure architectures.
Lower Saxony
Volkswagen AG Wolfsburg operations anchor transmission case demand for hybrid powertrain production lines. WLTP fuel efficiency mandates preserve multi-speed gearbox casting volumes despite electrification headwinds. Hanover-Braunschweig logistics corridors enable consolidated shipment routes to northern European OEMs.
Hesse
Frankfurt-Rhine-Main financial and logistics infrastructure supports aftermarket distribution networks for replacement brake and transmission castings. Independent distributors face shelf space erosion from OEM-captive parts programs. Wiesbaden-area procurement teams at large fleet operators increasingly source directly from VDA 6.3-certified foundries.
Germany Automotive Parts Zinc Die Casting Market Competitive Landscape
Captive-finishing specialists and precision-housing developers split the market between volume-driven transmission programs and emerging EV architectures. Tier-1 procurement consolidation favors operators with in-house CNC machining capacity and KBA traceability documentation. Strategic differentiation centers on dual-use defense crossover expertise and CSRD-ready carbon accounting infrastructure. Competitive moves emphasize backward integration into smelter relationships and geographic proximity to Stuttgart-Munich assembly corridors.
Among German-based operators, Druckguss Westfalen GmbH & Co KG and Druckguss Westfalen Behringer occupy positions within the captive-finishing tier, while Rheinmetall AG exemplifies the defense-automation crossover archetype. Kalmbach GmbH represents precision-housing specialization for electric drivetrain applications. These entities anchor supplier scorecards that weight embodied carbon metrics equally with piece-price, reflecting how CSRD disclosure mandates reshape procurement priorities.
| Leading Market Players |
|---|
| GP Diecasting |
| Breuckmann GmbH & Co. KG |
| Druckguss Westfalen GmbH & Co KG |
| Brillcast Manufacturing LLC |
| Kalmbach GmbH |
| Druckguss Westfalen Behringer |
| Schweizer Group Global GmbH |
| Rheinmetall AG |
| Wolf Group |
| Others |
Supply & Pricing Matrix
Nordrhein-Westfalen smelter concentration feeds directly into margin compression dynamics for Baden-Württemberg foundries serving Stuttgart OEMs. Energy cost spikes at primary zinc producers transmit downstream through fixed-price program contracts, while KBA traceability mandates impose certification premiums that reshape where value accrues.
Pricing Analysis
REACH compliance obligations dictate the pricing tier structure across German zinc die casting supply chains. Three-tier pricing stratifies across KBA-certified high-grade alloys, standard Zamak compositions, and uncertified secondary feedstock, with carbon intensity documentation now weighted equally with piece-price in Tier-1 procurement scorecards. Cost compression in transmission case programs is intensifying because Polish production zones undercut Saxon labor rates. Aftermarket distributors exhibit highest price sensitivity, while OEM direct sourcing programs prioritize traceability premiums over unit economics.
Supply Chain Analysis
Extended payment terms from Stuttgart OEMs strain working capital for mid-tier foundries without supply-chain finance facilities. Primary zinc concentrates in Australia, Peru, and Kazakhstan, while German foundries draw from Nordrhein-Westfalen smelters and secondary scrap pools restricted by cadmium threshold rules. Single-source vulnerability runs through Rheinmetall AG defense-automation crossover capacity for safety-critical castings. Distribution runs through just-in-sequence lines feeding Porsche and Mercedes-Benz assembly corridors, with VDA 6.3 audit gates filtering channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric drivetrain housing demand represents early-cycle expansion as 800V inverter architectures penetrate German OEM portfolios. Platform standardization across BMW and Volkswagen AG programs accelerates zinc precision casting adoption for motor enclosures.
For Market Incumbents: Harden KBA traceability documentation systems ahead of alloy purity threshold updates for brake and steering castings. Secure captive finishing capacity through toolpath programmer apprenticeships in North Rhine-Westphalia vocational pipelines. Rheinmetall AG dual-use automation expertise creates defensible positioning against Polish cost competition. For New Entrants and Emerging Players: Uncontracted white space in 800V motor housing architectures for Nuremberg-Augsburg EV supplier clusters represents the most penetrable entry point. Precision zinc enclosures for battery tray brackets serve BMW Group electrification roadmaps with shorter qualification cycles than safety-critical brake programs. Lead with CSRD-ready carbon accounting infrastructure to bypass incumbent data gaps. For Investors and Strategic Acquirers: Capital is best deployed toward captive-finishing specialists with in-house five-axis machining and KBA-certified high-grade alloy capacity. Five-to-ten year viability hinges on backward integration into renewable-energy smelter relationships. Monitor CSRD disclosure mandate compliance rates as inflection signal for OEM supplier scorecard premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smelter Relationships | Renewable energy certificates from Nordrhein-Westfalen smelters satisfy Stuttgart OEM carbon scorecards. |
| CSRD-Ready Carbon Accounting Infrastructure | Scope 3 data capture at cell level enables preferred supplier status with Mercedes-Benz program offices. |
| Captive Five-Axis CNC Finishing Capacity | In-house machining lines command 15-25% value uplift on transmission case programs. |
| KBA Homologation Pre-Certification Investment | 18-month validation cycle compression aligns with 12-month OEM platform launch schedules. |
| Dual-Use Defense Crossover Capability | Rheinmetall AG automation expertise transfers to safety-critical brake and steering component production. |
Research Methodology
Operator-level perspectives from Tier-1 procurement managers, OEM platform engineers, foundry operations directors, and aftermarket distribution heads anchored the qualitative base. Primary fieldwork combined with secondary validation against KBA regulatory filings, REACH compliance databases, EU Green Deal embodied carbon tracking provisions, and vehicle production data from Stuttgart-Munich assembly corridors. Bottom-up segment sizing and top-down macro anchoring triangulated volume and value estimates.
Scenario-bracketing around electrification penetration rates and KBA homologation timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture complexity, procurement channel authority, manufacturing stage value capture, and material grade specification. CAGRs derived from production volume elasticities to WLTP fuel efficiency mandates and hybrid powertrain retention rates. Zinc alloy price volatility and smelter energy cost trajectories fed sensitivity bands.
Macroeconomic conditions sit as an overlay; deviation in primary zinc spot prices, Nordrhein-Westfalen energy costs, or Polish wage inflation would shift the trajectory. Forecasts reflect assumptions on CSRD disclosure adoption timelines and KBA alloy purity threshold stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Air Brake Market
Automotive Parts
South Korea Automotive Airfilters Market