
 Anti-Lock Braking System (ABS) Market | 2026-2036
Anti-Lock Braking System (ABS) Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Lock Braking System (ABS) Market Intelligence
The gap between premium integrated ABS platforms and commodity hydraulic units is shifting procurement patterns across automotive tiers. Robert Bosch GmbH leverages captive semiconductor supply to sustain margin on sensor-integrated modules. Continental AG anchors European OEM channels through embedded control software. ZF Friedrichshafen AG competes in heavy-duty commercial segments with actuator-dominant architectures.
An anti-lock braking system is an active safety mechanism that modulates brake pressure through wheel-speed sensors, electronic control modules, and hydraulic actuators to prevent wheel lockup during deceleration. The system operates by pulsing brake pressure at frequencies up to 15 Hz, maintaining directional stability and reducing stopping distances on low-friction surfaces. Electronic ABS now leads product type dynamics as automakers integrate brake-by-wire with autonomous emergency braking protocols. Passenger vehicles dominate end user demand, though motorcycle ABS shows the fastest regulatory-driven expansion across Southeast Asian markets. Sensor technology captures disproportionate value within the technology stack as LiDAR and radar convergence elevates wheel-speed precision requirements.
NHTSA mandates ABS on all new U.S. commercial vehicles above specified gross weight thresholds, while EU regulators enforce ECE R13 compliance across heavy-duty truck categories. India's Ministry of Road Transport mandates ABS on two-wheelers and commercial vehicles under CMVR amendments, tightening market access for non-compliant suppliers. Stakeholders must monitor divergence between brake-by-wire standardization timelines and legacy hydraulic retrofit obligations across emerging markets.
Market Dynamics
Electronic ABS architectures are absorbing sensor-integrated brake-by-wire protocols, compressing the value chain between semiconductor suppliers and Tier 1 module assemblers as hydraulic actuator content diminishes.
Growth Catalysts
- India's CMVR ABS mandate:The Ministry of Road Transport requires anti-lock systems on two-wheelers and commercial vehicles, forcing fleet operators to retrofit legacy trucks and accelerating aftermarket module demand.
- Sensor fusion convergence:LiDAR and radar integration with wheel-speed sensors elevates precision requirements, pulling advanced ABS platforms into autonomous emergency braking stacks.
- Brazil's heavy-duty fleet renewal:National regulators mandate ABS on new commercial vehicles, compelling domestic truck manufacturers to source compliant electronic control modules.
Market Restraints
- Semiconductor supply concentration:Captive silicon wafer capacity at Bosch and Continental limits second-tier module suppliers, creating allocation bottlenecks during demand spikes.
- Hydraulic actuator obsolescence risk:Brake-by-wire standardization threatens legacy hydraulic unit manufacturers with stranded inventory across emerging market retrofit channels.
- ECE R13 compliance friction:Divergent homologation timelines between EU member states delay heavy-duty truck platform launches, extending development cycles for pan-European OEMs.
Strategic Opportunities
- Motorcycle ABS underpenetration:Southeast Asian markets outside Thailand and Vietnam show minimal two-wheeler ABS fitment, creating white space for cost-optimized sensor-integrated modules.
- Software-defined braking:Embedded control algorithms enable over-the-air calibration updates, opening recurring revenue streams for Tier 1 suppliers previously dependent on hardware margins.
- China's dual carbon goals:MIIT incentives for energy-efficient commercial vehicles favor electronic ABS over hydraulic systems, aligning procurement with state industrial policy.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D validation for brake-by-wire modules extends 18-24 months, compressing product launch windows for platform-sharing OEMs.
- Legacy fleet retrofit complexity:Hydraulic-to-electronic ABS conversions on aging commercial vehicles require chassis-level electrical architecture upgrades, limiting addressable aftermarket volume.
- Cross-domain integration friction:ABS control modules must synchronize with autonomous driving compute stacks, demanding software competencies outside traditional braking supplier expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Lock Braking System (ABS) Market |
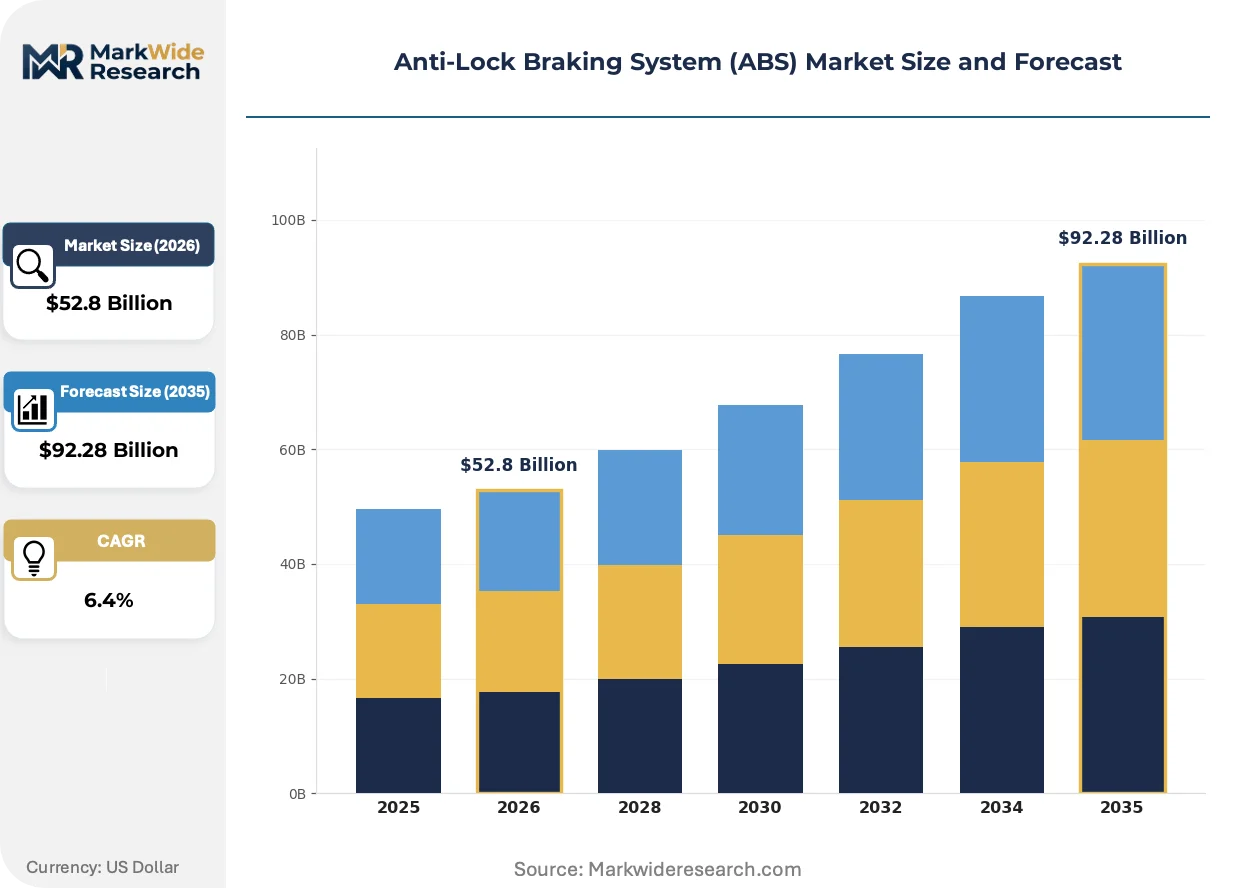
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional ABS, Electronic ABS, Hydraulic ABS, Integrated ABS End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Technology: Sensor Technology, Control Module, Hydraulic System, Actuator Installation Type: OEM Installation, Aftermarket Installation, Retrofitting, Upgrading |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, Hyundai Mobis, Autoliv Inc., Nissin Kogyo Co., Ltd., ADVICS Co., Ltd., Knorr-Bremse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Lock Braking System (ABS) Market Strategic Shifts & Innovations
Brake system electrification is collapsing the boundary between foundation braking and advanced driver assistance, forcing suppliers to restructure around software-integrated platforms rather than discrete hardware modules.
Electro-hydraulic brake (EHB) actuation is absorbing the core deceleration function previously handled by vacuum boosters and master cylinders. Passenger vehicle OEMs in Germany and China are adopting EHB for platform flexibility, enabling seamless integration with regenerative braking and autonomous emergency braking protocols. This absorption is compressing the supplier base as hydraulic component specialists lose share to integrated mechatronics providers.
REACH substance restrictions on hexavalent chromium plating are forcing corrosion-resistant coating transitions for ABS valve bodies and sensor housings. European suppliers face reformulation costs for surface treatments, with Tier 2 metal finishers absorbing compliance investment. Heavy-duty commercial segments show the steepest cost impact due to larger component masses and exposure duty cycles.
Fleet procurement departments are consolidating brake system sourcing under long-term platform contracts, displacing spot-market module purchases. Large commercial vehicle operators in India and Brazil now specify ABS performance benchmarks rather than supplier brands, compressing margins for branded component manufacturers. This concentration is most visible in long-haul trucking segments where total cost of ownership calculations dominate supplier selection.
Anti-Lock Braking System (ABS) Market Segmentation
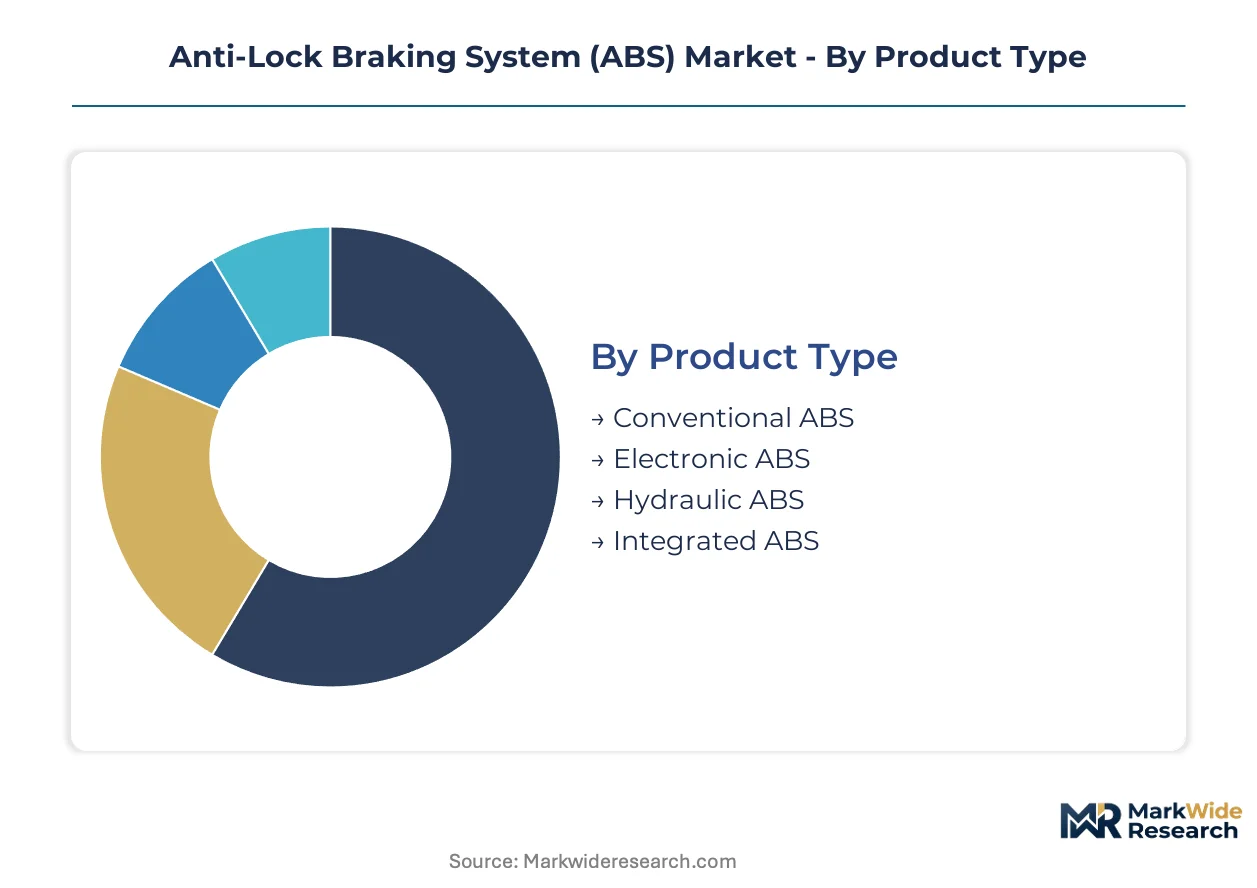
ABS market segmentation reveals how brake system architectures diverge across vehicle platforms and regulatory environments. Upgrade cycles and replacement demand vary sharply between electronic brake-by-wire platforms and legacy hydraulic retrofit markets.
Product Type:
Replacement cycles accelerate as electronic architectures displace hydraulic units across OEM platforms, compressing aftermarket windows for conventional component suppliers.
- Conventional ABS:Vacuum-boosted hydraulic systems with discrete wheel-speed sensors and standalone control modules. Demand concentrates in emerging market commercial vehicle retrofit channels where India's CMVR mandate forces fleet upgrades on aging truck platforms.
- Electronic ABS:Sensor-integrated brake-by-wire architectures with embedded control algorithms and electro-hydraulic actuation. China's passenger vehicle OEMs prioritize these systems for autonomous emergency braking integration, aligning procurement with MIIT energy-efficiency incentives.
- Hydraulic ABS:Pump-motor valve assemblies with pulsed pressure modulation. Brazil's heavy-duty truck manufacturers source these for cost-sensitive fleet specifications.
- Integrated ABS:Combined brake and stability control modules sharing sensor networks with ADAS compute stacks. German premium OEMs specify these for platform consolidation.
Electronic ABS sits at the top of the volume ranking, with Integrated ABS climbing the fastest as brake-by-wire standardization advances.
End User:
Cost tiers separate procurement patterns across vehicle categories, with premium sensor integration commanding price multiples over commodity hydraulic specifications.
- Passenger Vehicles:Four-channel electronic systems with individual wheel control. German and Chinese OEMs drive specification intensity for autonomous braking compatibility.
- Commercial Vehicles:Six-channel configurations for multi-axle truck stability. India's fleet operators absorb retrofit costs under CMVR compliance deadlines.
- Motorcycles:Compact single-channel or dual-channel units with reduced packaging envelopes. Southeast Asian markets outside Thailand show minimal fitment penetration.
- Heavy-Duty Trucks:High-cycle hydraulic actuators for severe-duty braking loads. Brazil's domestic manufacturers source these under national ABS mandates.
Passenger Vehicles capture the largest revenue share, with Motorcycles expanding most quickly on regulatory push across Asian markets.
Technology:
Supply concentration favors integrated module suppliers over discrete component specialists as system boundaries collapse.
- Sensor Technology:Hall-effect and magnetoresistive wheel-speed sensors with LiDAR fusion capability. Precision requirements escalate with autonomous emergency braking integration.
- Control Module:ASIL-D certified electronic units with embedded brake-by-wire algorithms. Bosch and Continental maintain captive semiconductor supply for these modules.
- Hydraulic System:Solenoid valve blocks and pump-motor assemblies. REACH substance restrictions force coating reformulations for European suppliers.
- Actuator:Electro-hydraulic brake calipers and foundation brake interfaces. Heavy-duty commercial applications specify these for actuator-dominant architectures.
Sensor Technology commands the highest value per unit, with Control Module assembly gaining share fastest through software-defined braking trends.
Installation Type:
Customer type stratification separates fleet procurement departments from individual vehicle owner upgrade decisions.
- OEM Installation:Factory-integrated systems with platform-matched calibration. Passenger vehicle platforms in Germany and China specify these exclusively.
- Aftermarket Installation:Dealer-fitted modules for vehicle-in-service compliance. India's commercial fleet operators drive volume under CMVR retrofit obligations.
- Retrofitting:Chassis-level electrical architecture upgrades for legacy hydraulic conversions. Complexity limits addressable volume on aging commercial vehicles.
- Upgrading:Sensor and control module replacements for performance enhancement. Motorcycle owners in Southeast Asia rarely pursue these given cost sensitivity.
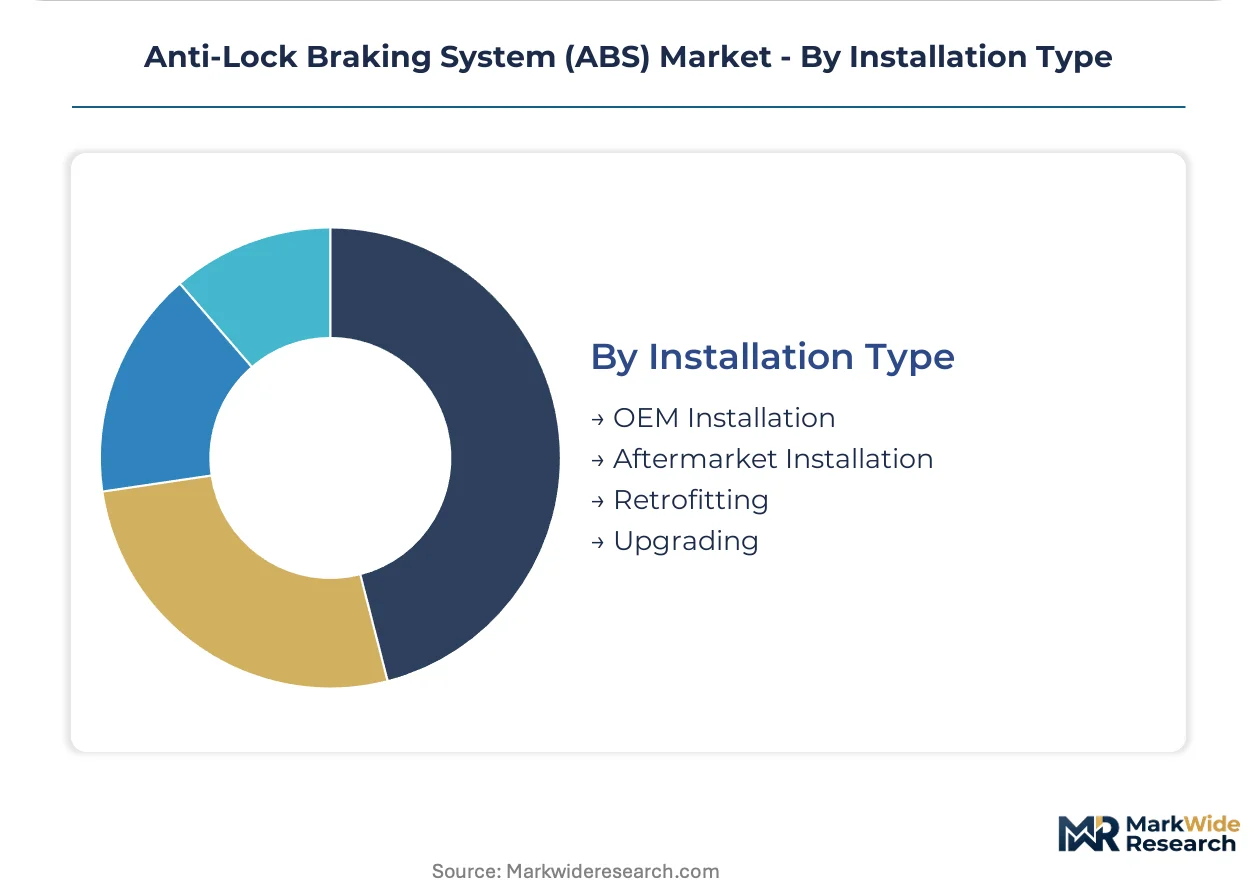
OEM Installation dominates absolute volume, with Aftermarket Installation rising fastest on regulatory retrofit mandates in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's passenger vehicle OEMs specify integrated ABS platforms at higher rates than Brazil's heavy-duty truck manufacturers, yet both markets face tightening regulatory mandates that compress supplier lead times.
Germany
Premium OEMs in Stuttgart and Munich drive specification intensity for brake-by-wire integration with autonomous emergency braking stacks. KBA enforces UN ECE R13 homologation standards across heavy-duty truck categories, extending validation timelines for pan-European platform launches. The Baden-Württemberg automotive cluster concentrates Tier 1 module assembly operations serving Mercedes-Benz and Porsche development centers.
China
Passenger vehicle electrification in Shanghai and Shenzhen accelerates electronic ABS procurement for regenerative braking compatibility. MIIT dual carbon incentives favor energy-efficient commercial vehicle specifications, aligning state industrial policy with brake system procurement decisions. The Yangtze River Delta manufacturing belt hosts integrated module production serving BYD and NIO platform requirements.
India
Commercial fleet operators in Maharashtra absorb retrofit costs under CMVR ABS compliance deadlines for two-wheelers and heavy-duty trucks. The Ministry of Road Transport mandates anti-lock systems through amended motor vehicle rules, forcing chassis-level electrical upgrades on aging platforms. The Tamil Nadu automotive corridor concentrates aftermarket module distribution serving Chennai-based commercial vehicle manufacturers.
Brazil
Domestic truck manufacturers in São Paulo source electronic control modules under national ABS mandates for new commercial vehicle registrations. ANVISA coordinates with transport regulators on heavy-duty fleet safety standards, though homologation timelines lag European benchmarks. The Minas Gerais industrial belt hosts hydraulic actuator production for cost-sensitive fleet specifications serving Scania and Volvo assembly plants.
United States
Commercial vehicle fleets in Michigan and Texas face NHTSA mandates requiring ABS on new trucks above gross weight thresholds. The Detroit automotive cluster anchors OEM installation volume for integrated brake and stability control modules. California's advanced driver assistance ecosystem pulls sensor-fusion ABS platforms into autonomous vehicle development programs.
Anti-Lock Braking System (ABS) Market Key Industry Players
Top-tier vendors anchor integrated module supply, while commodity hydraulic specialists face margin compression from brake-by-wire standardization. The supplier base concentrates around three strategic archetypes: captive semiconductor producers controlling sensor-integrated control modules, actuator-dominant heavy-duty specialists, and software-embedded platform providers. Consolidation pressures favor backward integration into silicon wafer capacity and embedded algorithm development.
Among Germany-based automotive suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated module archetype through captive semiconductor supply chains and embedded control software competencies. ZF Friedrichshafen AG occupies a position within actuator-dominant architectures for commercial vehicle applications. Japanese fabricators including Denso Corporation and Nissin Kogyo Co., Ltd. represent precision sensor and hydraulic component specialization. These named entities anchor industry-level commentary on competitive positioning without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Hyundai Mobis |
| Autoliv Inc. |
| Nissin Kogyo Co., Ltd. |
| ADVICS Co., Ltd. |
| Knorr-Bremse AG |
| Others |
Cost & Logistics Intelligence
REACH substance restrictions on hexavalent chromium plating gate qualified supply for ABS valve bodies and sensor housings, reserving premium-tier pricing access for European suppliers that absorbed coating reformulation costs. Fleet procurement departments in India and Brazil now specify performance benchmarks rather than brands, compressing margins for commodity hydraulic module manufacturers while sensor-integrated electronic architectures command price multiples.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing belt are reshaping price floors for electronic ABS modules as domestic suppliers scale brake-by-wire production. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified integrated platforms from hydraulic retrofit units, with certification grade and volume scale as primary price differentiation drivers. Pricing pressure stems from semiconductor allocation bottlenecks during demand spikes, squeezing second-tier module suppliers without captive silicon capacity. Commercial fleet operators in emerging markets show highest price sensitivity, while German premium OEMs prioritize autonomous braking compatibility over unit cost.
Supply Chain Analysis
Freight cost volatility from Asia-Europe routes feeds into landed cost calculations for semiconductor-dependent control modules, amplifying margin exposure for non-integrated suppliers. Supply concentrates in Germany, China, and Japan for Tier 1 module assembly, with Taiwan and South Korea anchoring sensor wafer fabrication. Raw material dependencies span silicon wafers, rare-earth magnetic components for Hall-effect sensors, and specialty steel alloys for valve bodies. Single-source vulnerability around automotive-grade microcontroller supply creates allocation risk during demand surges. Distribution runs through OEM direct channels for passenger vehicle platforms and aftermarket dealer networks for commercial fleet retrofit obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ABS market functions as a geographic-arbitrage play where India's CMVR retrofit deadlines impose cost absorption requirements on fleet operators that Brazilian heavy-duty manufacturers avoid through new-vehicle mandate timing differentials.
For Market Incumbents: Cement captive semiconductor supply through backward integration into silicon wafer capacity or long-term foundry offtake agreements, defending against allocation bottlenecks that strand competitor module production. Lock in multi-year platform contracts with pan-European OEMs before ECE R13 homologation timelines extend development cycles, using embedded control software as a switching-cost moat.
For New Entrants and Emerging Players: Begin with cost-optimized single-channel motorcycle ABS modules for Indonesian and Philippine two-wheeler markets where regulatory fitment penetration remains minimal. Pursue white-label aftermarket distribution through Chennai-based commercial vehicle service networks serving India's CMVR retrofit channel, bypassing OEM direct procurement concentration.
For Investors and Strategic Acquirers: Roll-up economics work for hydraulic-to-electronic conversion specialists because legacy fleet retrofit complexity creates regional service moats that resist platform commoditization. Target mid-cap module assemblers with captive coating compliance for REACH substance restrictions and established KBA validation relationships. Monitor brake-by-wire standardization timeline convergence as the inflection signal for stranded hydraulic inventory risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Agreement | Captive silicon wafer access sustains margin on sensor-integrated modules during allocation spikes. |
| Software-Defined Braking Investment | Embedded algorithm development enables over-the-air calibration revenue streams beyond hardware margins. |
| Geographic Manufacturing Footprint | Yangtze River Delta production aligns with MIIT dual carbon incentives for Chinese OEM procurement. |
| Platform Standardization | Brake-by-wire integration with autonomous emergency braking stacks consolidates Tier 1 supplier position. |
| Aftermarket Distribution Partnership | Chennai-based dealer networks capture India's CMVR retrofit volume on aging commercial vehicle fleets. |
Research Approach
Multiple input streams — OEM platform engineering disclosures, Tier 1 supplier procurement data, and national vehicle registration databases — were reconciled against regulatory mandate timelines across India, Brazil, Germany, China, and the United States. Primary interviews with ABS module procurement managers, commercial fleet operations directors, and automotive semiconductor supply planners were validated through secondary sources including NHTSA rulemaking dockets, EU ECE R13 homologation records, and MIIT policy circulars. Bottom-up unit economics for sensor, control module, and actuator content were triangulated with top-down OEM platform production forecasts.
Data-stream reconciliation across product type, vehicle class, propulsion architecture, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by content-per-vehicle assumptions for electronic versus hydraulic architectures. Industry-specific forecast inputs included CMVR compliance deadline phasing for Indian commercial fleets and MIIT dual carbon incentive alignment for Chinese passenger vehicle electrification.
Several conditions sit outside the modeled scope, including potential brake-by-wire standardization acceleration, unanticipated REACH substance restriction expansions, and autonomous vehicle regulatory framework shifts that could compress ABS control module boundaries into centralized compute stacks. Forecasts reflect assumptions about semiconductor supply normalization and fleet replacement cycle stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Europe Adaptive Steering Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
India Airbag Systems Market