
 Automotive Wheel Market | 2026-2036
Automotive Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Market Analysis
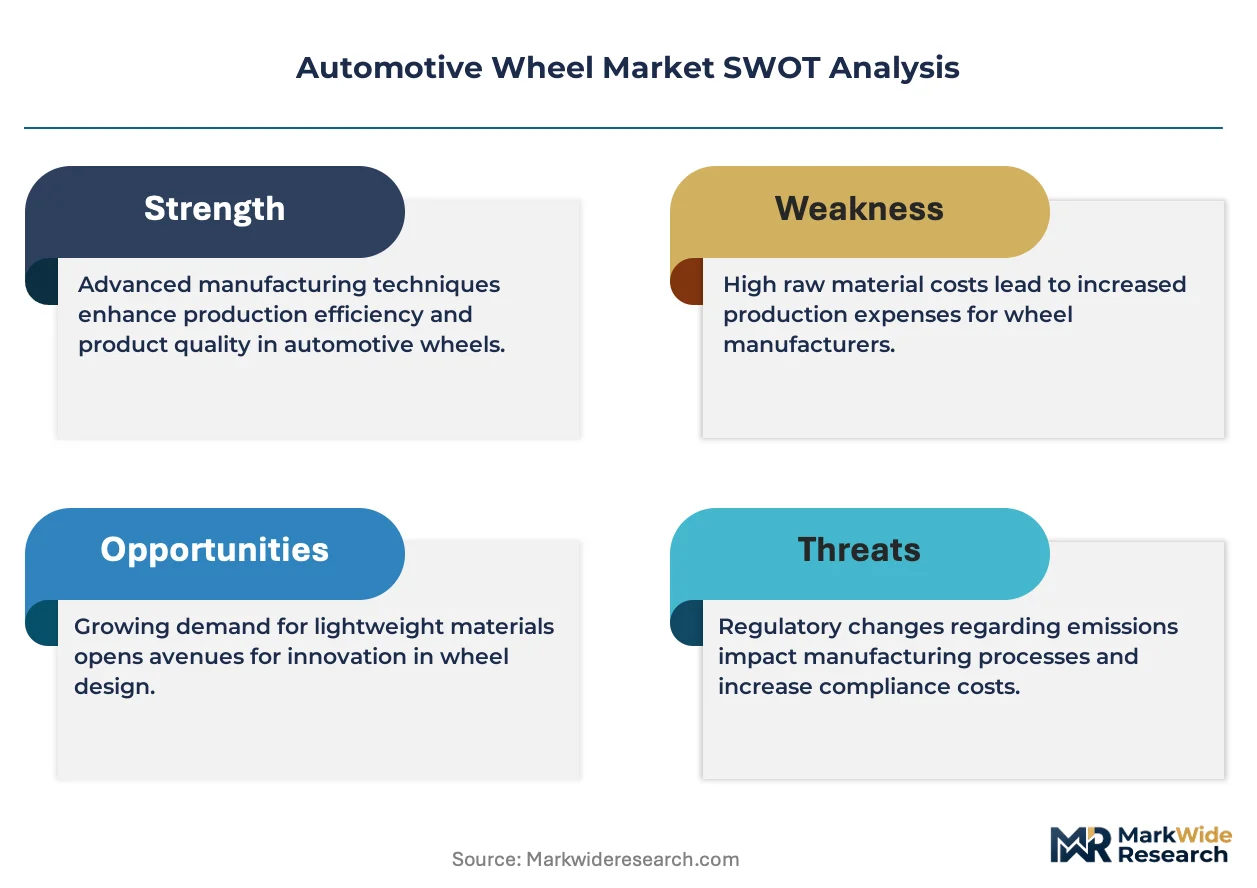
EPA tailpipe standards and the EU Green Deal's embedded carbon requirements are decoupling wheel procurement from pure unit-cost metrics toward lifecycle emissions accounting. CITIC Dicastal leverages captive aluminum smelting and forging capacity to dominate OEM supply contracts for electric vehicle platforms. Ronal Group sustains engineering leadership through proprietary flow-forming technology that reduces rotating mass without sacrificing structural integrity. Borbet competes on design flexibility, occupying the premium original equipment segment where styling differentiation commands sustained pricing power.
An automotive wheel is a structural rotating component, typically comprising aluminum alloy, steel, or magnesium, manufactured through forging, casting, or stamping processes to transmit vehicle load, absorb road shock, and maintain tire contact patch geometry under dynamic cornering and braking forces. Aluminum wheels now lead value contribution due to their strength-to-weight ratio and compatibility with regenerative braking thermal profiles, while carbon fiber remains confined to ultra-performance applications where unit economics tolerate extreme material costs. The forged manufacturing process captures the fastest growth trajectory as OEMs specify higher-strength alloys to accommodate heavier battery electric vehicle platforms without proportional mass penalties.
NHTSA's Federal Motor Vehicle Safety Standards govern wheel fatigue and impact resistance in the United States, while ECE R124 in Europe mandates radial fatigue, cornering fatigue, and impact testing protocols that directly shape product development timelines and tooling investments. China's GB/T standards, administered by SAMR, impose additional dimensional and metallurgical specifications that foreign suppliers must navigate for market access. Stakeholders must monitor how proliferating regional carbon-border mechanisms reshape sourcing economics between domestic forging capacity and imported cast wheel supply.
Market Dynamics
Electric vehicle platform weights are forcing wheel suppliers to re-engineer load-bearing architectures without sacrificing durability, compressing development cycles and elevating forged aluminum specifications across OEM portfolios.
Growth Catalysts
- EU F-Gas Regulation:Embedded carbon mandates in Europe are accelerating material substitution from conventional steel toward aluminum and magnesium alloys with lower production-phase emissions.
- China's integrated aluminum supply chains:Domestic foundry capacity and captive smelting operations enable cost-competitive forged wheel production for export programs and local EV brands.
- Regenerative braking thermal profiles:Battery electric vehicle platforms require wheels that dissipate heat from frictionless braking systems, favoring aluminum's thermal conductivity over steel alternatives.
Market Restraints
- Aluminum ingot price volatility:Primary aluminum input costs fluctuate with energy pricing, compressing margin predictability for casting and forging operations.
- Concentrated forging capacity:High-strength alloy wheel production clusters in China and Germany, creating geographic supply risk for OEMs with diversified assembly footprints.
- Magnesium corrosion limitations:Salt-spray durability constraints restrict magnesium wheel adoption to dry-climate markets despite its superior strength-to-weight ratio.
Strategic Opportunities
- India's EV subsidy schemes:PLI scheme incentives for electric vehicle component localization create entry pathways for forged wheel suppliers establishing domestic forging operations.
- Carbon fiber hybrid architectures:Convergence of forged aluminum centers with carbon fiber rim sections enables mass reduction for performance EV platforms without full composite cost burdens.
- Direct-to-fleet digital channels:Commercial vehicle fleet operators are procuring replacement wheels through B2B platforms, bypassing traditional tiered distribution.
Industry Challenges
- Multi-jurisdiction fatigue certification:NHTSA FMVSS, ECE R124, and China's GB/T standards impose divergent testing protocols, extending product validation timelines by 8-14 months.
- Tooling amortization pressure:Forged wheel dies require 6-figure capital investments per SKU, straining mid-volume suppliers managing proliferating EV platform variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Market |
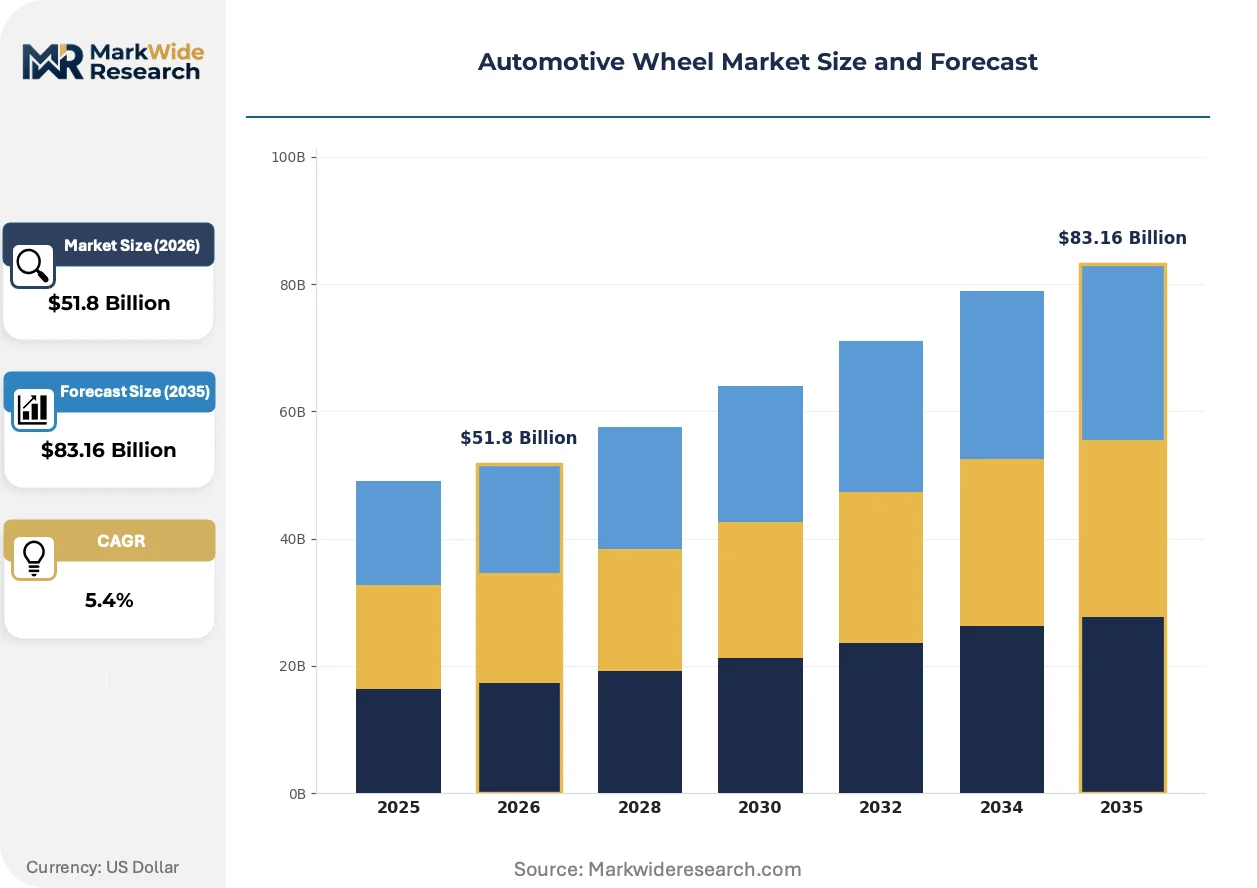
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $83.16 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Magnesium, Carbon Fiber Wheel Size: 15 Inch, 16 Inch, 17 Inch, 18 Inch End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Performance Tuners Manufacturing Process: Forged, Cast, Stamped, Machined |
| Companies Covered | CITIC Dicastal, Ronal Group, Iochpe-Maxion, Borbet, Enkei Corporation, Zhejiang Wanfeng Auto Wheel, Superior Industries International, Steel Strips Wheels, Accuride Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Market Emerging Trajectories
Wheel manufacturing is bifurcating between commodity casting for internal combustion fleets and precision forging for electric platforms, with process technology becoming the primary competitive differentiator.
Flow-forming technology is electrifying wheel production by stretching cast preforms into final rim profiles that reduce rotating mass 15-20% versus conventional casting. Tier-1 suppliers are adopting this hybrid process for mid-range EV platforms where full forging economics remain prohibitive. The technology is electrifying supplier competition by collapsing the historical cost gap between cast and forged architectures.
Europe's F-Gas Regulation and the EU Green Deal's embedded carbon requirements are decoupling wheel procurement from pure unit-cost metrics toward lifecycle emissions accounting. OEMs now request Environmental Product Declarations documenting smelting-phase carbon intensity. Battery electric vehicle programs in Germany, France, and the Netherlands are most affected, with procurement teams rejecting Chinese cast wheels lacking renewable energy certificates.
Fleet operators are consolidating wheel purchasing through outcome-based contracts that bundle supply, mounting, balancing, and damage replacement into per-kilometer fees. This displaces traditional spot-market transactions for commercial vehicle aftermarket demand. The model is most visible in Germany's long-haul trucking sector, where logistics firms outsource entire wheel lifecycle management to Tier-1 suppliers.
Automotive Wheel Market Segmentation
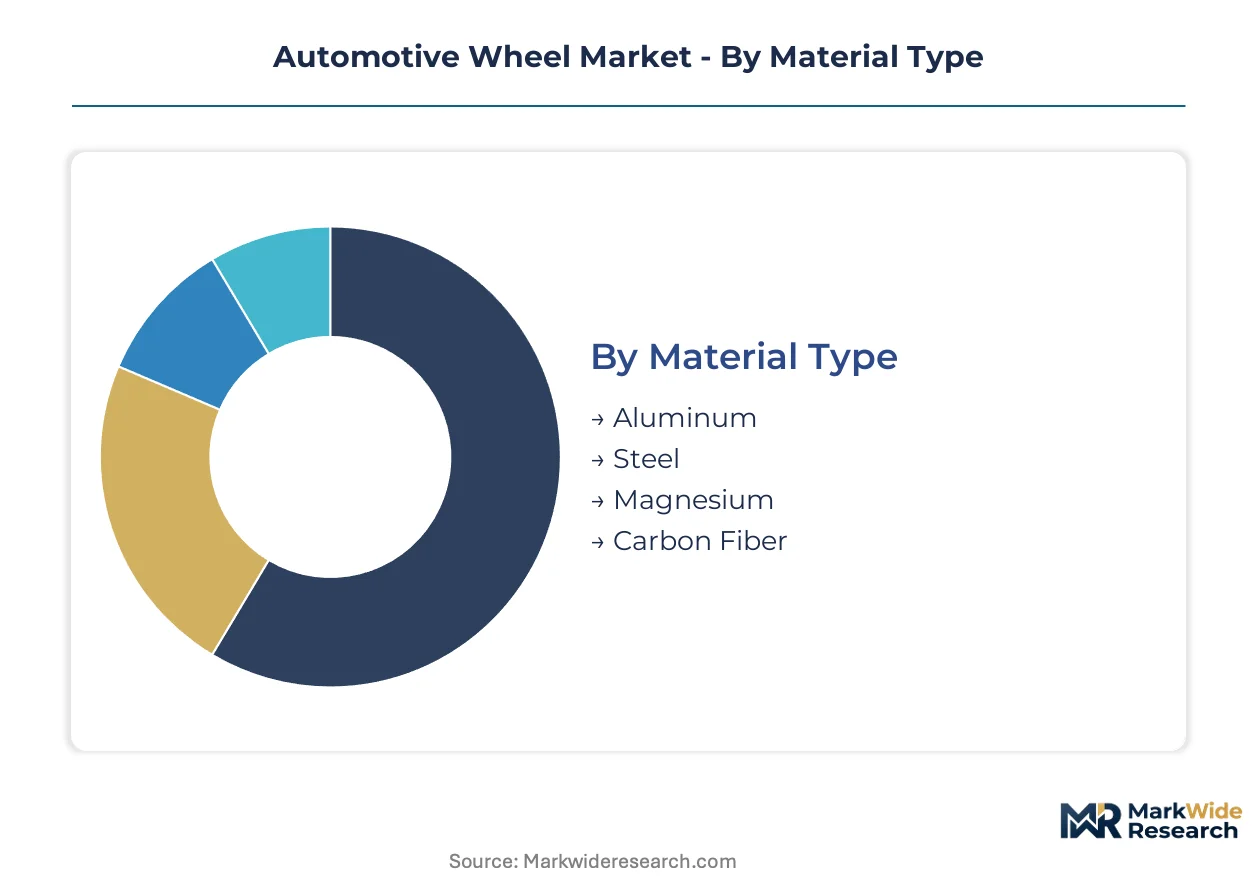
Wheel procurement specifications diverge sharply between mass-market electric vehicle platforms seeking weight reduction and commercial fleets prioritizing damage tolerance. Segmentation reveals how material selection and manufacturing process choices cascade through pricing, certification requirements, and supplier qualification timelines.
Material Type:
Customization intensity spans from commodity steel specifications to engineered carbon fiber layups, with aluminum alloys occupying the scalable middle ground where OEM volume concentrates.
- Aluminum:Aluminum alloys deliver optimal strength-to-weight ratios for battery electric vehicle thermal management, with demand concentrating in Germany and China where OEMs specify forged variants for premium EV platforms. The metal's thermal conductivity supports regenerative braking heat dissipation requirements.
- Steel:Conventional steel wheels retain dominance in commercial vehicle and emerging market applications where unit cost sensitivity overrides mass reduction targets. Stamped steel construction sustains margin viability for high-volume internal combustion fleet programs.
- Magnesium:Magnesium alloys offer superior strength-to-weight performance but face salt-spray corrosion constraints limiting deployment to dry-climate passenger segments.
- Carbon Fiber:Carbon fiber composite wheels serve ultra-performance applications where extreme material costs are absorbed within six-figure vehicle price points.
Most installed capacity flows through aluminum. Expansion is steepest in magnesium alloys as coating technologies address corrosion limitations.
Wheel Size:
Size specification tracks vehicle platform architecture, with larger diameters correlating to battery electric vehicle mass distribution requirements and brake rotor packaging needs.
- 18 Inch:Eighteen-inch wheels dominate premium electric SUV and sedan platforms where larger brake systems and aesthetic proportion requirements converge. OEMs in the Netherlands and Norway specify this diameter for flagship EV programs.
- 17 Inch:Seventeen-inch specifications balance ride comfort and unsprung mass for mid-range battery electric vehicles and hybrid architectures. This diameter captures the highest unit volumes across European C-segment platforms.
- 16 Inch:Sixteen-inch wheels sustain presence in compact internal combustion vehicles and fleet-oriented electric models where tire replacement cost minimization drives specification.
- 15 Inch:Fifteen-inch diameters concentrate in emerging market entry vehicles and commercial van segments where steel construction maintains cost competitiveness.
Production gravity centers on 17-inch and 18-inch formats. Steepest expansion occurs in 18-inch as EV platform weights escalate.
End User:
Customer type determines contract structure, with OEMs demanding multi-year supply commitments and aftermarket channels requiring inventory breadth across fragmented vehicle parc.
- OEMs:Original equipment manufacturers specify wheels through platform-development programs with 5-7 year contract horizons, embedding lifecycle emissions accounting into supplier scorecards. German and French OEMs lead in mandating Environmental Product Declarations.
- Aftermarket Providers:Aftermarket channels serve replacement demand and styling upgrades through distributor networks, with inventory carrying costs dictating SKU concentration in high-volume fitments.
- Vehicle Assemblers:Contract assemblers procure wheels on shorter lead times for limited-production or regional assembly operations.
- Performance Tuners:Performance specialists source forged and flow-formed variants for motorsport and enthusiast applications where margin structures tolerate premium pricing.
OEM contracts absorb the majority of forging capacity. Aftermarket channels are expanding fastest as EV parc ages into replacement cycles.
Manufacturing Process:
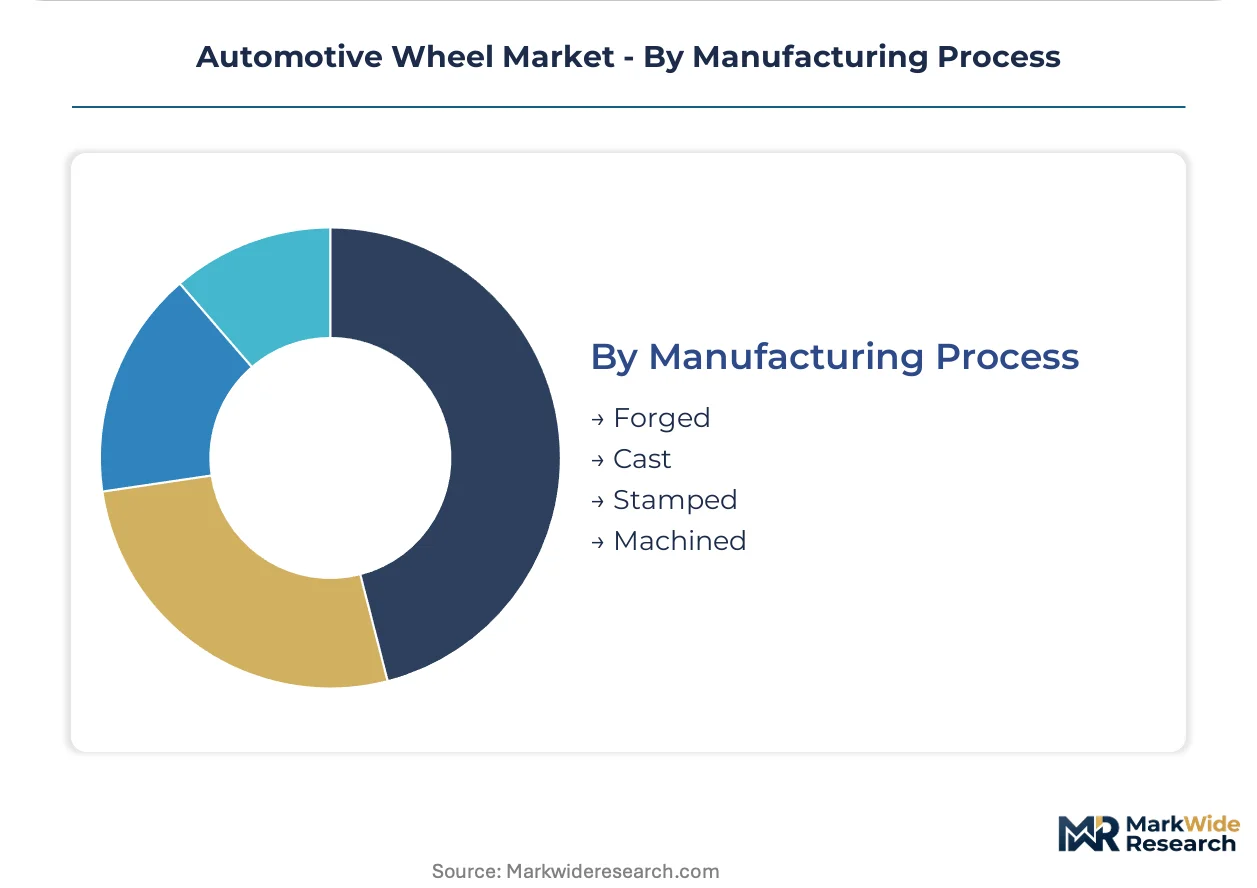
Process selection divides the market between capital-intensive forging for structural performance and casting economies for cost-sensitive applications.
- Forged:Forged manufacturing compresses aluminum alloy grain structure to yield 25-30% higher strength than casting, enabling thinner wall sections without durability compromise. Battery electric vehicle platforms in China and Germany specify forged wheels to offset battery mass penalties.
- Cast:Cast production achieves lowest unit costs for high-volume programs, with flow-forming hybrids narrowing the performance gap to forged alternatives. Gravity and low-pressure casting dominate mass-market internal combustion vehicle supply.
- Stamped:Stamped steel construction serves commercial vehicle and economy passenger segments where rotational inertia tolerance permits higher mass.
- Machined:Machined-from-billet production addresses ultra-low volume specialty and prototype requirements where tooling amortization is prohibitive.
Casting maintains the broadest installed base. Forged output is climbing the fastest as EV platform specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheel manufacturing originated in Germany's industrial heartland during the early automotive era, with forging expertise later migrating to China's Yangtze River Delta as aluminum supply chains consolidated. Today's production geography reflects this dual heritage.
China
Domestic EV brands BYD and NIO specify forged aluminum wheels for extended-range platforms, consuming capacity from Zhejiang and Shandong foundries. SAMR's GB/T standards impose metallurgical testing protocols that foreign suppliers must satisfy for market access. CITIC Dicastal anchors production in Qinhuangdao with captive smelting and forging operations serving export programs.
Germany
BMW and Mercedes-Benz procurement teams mandate Environmental Product Declarations documenting smelting-phase carbon intensity under EU Green Deal frameworks. KBA enforces ECE R124 fatigue testing protocols that extend validation timelines. Borbet operates forging facilities in Hallenberg while Ronal Group maintains engineering centers in Härkingen.
United States
Detroit Three OEMs specify larger-diameter wheels for electric truck platforms, sourcing from domestic forging capacity and Mexican maquiladora operations. NHTSA's FMVSS standards govern impact resistance and fatigue performance for highway safety certification. Superior Industries International maintains production in Arkansas and California to serve regional assembly footprints.
Japan
Toyota and Honda integrate wheel specifications into platform-development programs with 5-7 year contract horizons, emphasizing lightweight architectures for hybrid efficiency. METI administers JIS standards for dimensional tolerances and material grades. Enkei Corporation operates forging and flow-forming facilities in Shizuoka Prefecture for domestic and export supply.
India
Maruti Suzuki and Tata Motors procurement teams are localizing forged wheel supply under PLI scheme incentives for EV component manufacturing. BIS imposes additional testing protocols beyond international baselines for market access. Steel Strips Wheels and emerging domestic fabricators are establishing forging capacity in Haryana and Tamil Nadu.
Automotive Wheel Market Vendor Landscape
The competitive structure tilts toward scale-driven aluminum specialists with captive smelting capacity. Three player tiers operate: integrated foundry-to-forge operators with upstream aluminum control, precision engineering houses specializing in flow-forming and design differentiation, and regional stamping specialists serving commercial vehicle cost sensitivities. Dominant competitive moves include backward integration into primary aluminum and strategic partnerships with EV platform architects for co-development programs.
Among Chinese integrated operators, CITIC Dicastal and Zhejiang Wanfeng Auto Wheel exemplify the foundry-to-forge archetype with captive supply chains. Ronal Group occupies a position within the European precision engineering tier. Iochpe-Maxion represents the diversified multinational structure spanning multiple regional markets.
| Leading Market Players |
|---|
| CITIC Dicastal |
| Ronal Group |
| Iochpe-Maxion |
| Borbet |
| Enkei Corporation |
| Zhejiang Wanfeng Auto Wheel |
| Superior Industries International |
| Steel Strips Wheels |
| Accuride Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers and family-owned mid-caps anchor automotive wheel supply, with Chinese state-linked foundries and German family engineering houses wielding divergent pricing power. Their ownership structures shape inventory discipline and contract tenacity, insulating premium forged output from commodity aluminum volatility while compressing margins in cast wheel tiers.
Pricing Analysis
Contract-based long-term offtake dominates OEM procurement, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in standard cast segments is intensifying because Chinese integrated producers absorb aluminum ingot volatility through captive smelting. Fleet buyers exhibit highest price sensitivity, while German luxury OEMs prioritize lifecycle emissions accounting over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with primary aluminum smelting concentrated in China, Russia, and the Gulf states. Forged wheel production draws from bauxite, alumina, and high-strength alloy feedstock, with logistics chokepoints at Shanghai port and Rotterdam hub threatening just-in-time OEM sequences. Distribution runs through Tier 1 supplier consolidation centers co-located with vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive wheel market compounds steadily as electric vehicle platform proliferation forces structural weight reduction across every vehicle class. This durable demand driver sustains premium pricing for forged architectures through successive technology cycles.
For Market Incumbents: Hedge aluminum price exposure through backward integration into scrap recycling and long-term alumina offtake agreements. CITIC Dicastal's captive Qinhuangdao smelting demonstrates how upstream control defends margin position against LME volatility. Prioritize EPD certification investment to meet EU Green Deal procurement gates.
For New Entrants and Emerging Players: The mid-tier price gap between flow-formed and forged specifications creates white-space opportunity in India's PLI-subsidized EV component sector. Target commercial fleet outcome-based contracts in Germany's long-haul trucking segment, where per-kilometer wheel lifecycle management displaces spot purchasing. Lead with digital B2B platforms bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional stamping specialists lacking EV platform access. The 5-10 year viability window favors targets with flow-forming capability bridging cast and forged economics. Monitor Chinese GB/T standard enforcement as the inflection signal for foreign supplier market access contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | CITIC Dicastal's captive smelting insulates margins from energy-price-driven ingot volatility. |
| Flow-Forming Technology Deployment | Ronal Group's proprietary rim-stretching process collapses cost gaps to forged alternatives. |
| Environmental Product Declaration Certification | Borbet's EPD documentation secures BMW and Mercedes-Benz procurement scorecard compliance. |
| Carbon Fiber Hybrid Architecture Development | Enkei's forged-center carbon-rim prototypes target performance EV mass reduction specifications. |
| Direct-to-Fleet Digital Channel Launch | Superior Industries' B2B platform captures commercial vehicle replacement demand outside distributor networks. |
Methodological Framework
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market's stakeholder ecosystem. The research combines interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and foundry operations managers with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs trade records. Bottom-up volume builds and top-down market sizing triangulate to segment-level outputs.
Rate-of-change decomposition separates volume growth from value expansion across material type, manufacturing process, wheel size, and propulsion architecture dimensions over the projection horizon. CAGRs derive from modeled vehicle production trajectories, content-per-vehicle assumptions for electric platforms, and alloy substitution elasticities under regulatory carbon pricing. Forecast inputs include SAMR enforcement intensity for GB/T standards and EU Green Deal embedded carbon threshold implementation.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook by compressing EV platform weight penalties and reducing forged wheel specification intensity. Forecasts reflect assumptions about aluminum smelting decarbonization timelines and regional carbon border mechanism coverage. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market