
 Train Suspension System Market | 2026-2036
Train Suspension System Market Size, Share, and Industry Trends Forecast 2026-2036
Train Suspension System Market Analytics
Buyer concentration among state-backed rail operators is shifting toward fewer, larger procurement consortia with multi-year fleet renewal mandates. Knorr-Bremse leverages its pneumatic braking heritage to anchor high-speed train contracts across European networks. Wabtec Corporation sustains manufacturing scale through captive foundry capacity and backward integration into cast steel components. Amsted Rail Company specializes in heavy-haul freight suspension systems that dominate North American Class I railroad specifications.
A train suspension system integrates dampers, springs, linkages, and bushings to isolate wheel-rail forces from the car body, maintaining ride comfort within ISO 2631 vibration limits and stabilizing dynamic loads up to 250 km/h. The assembly serves the essential commercial purpose of extending rail asset life while permitting higher operational speeds without track damage. Active suspension platforms command premium positioning as operators prioritize real-time damping adjustment for high-speed and light-rail deployments. Pneumatic systems retain volume leadership in heavy rail and freight segments where cost-per-axle metrics dominate procurement criteria. Hydraulic systems face margin compression from composite material alternatives that reduce unsprung mass in electromagnetic configurations.
EU REACH restrictions on aromatic oils in rubber bushings are forcing compound reformulation across Trelleborg's European supply base. China's GB/T rail standards and NMPA-equivalent rail safety certification tighten market access for imported suspension modules. Japan's METI energy-efficiency benchmarks for rolling stock indirectly shape damper specifications through whole-train consumption targets. Stakeholders must monitor how F-Gas Regulation phase-down timelines alter pneumatic system refrigerant choices before committing to platform designs.
Market Dynamics
Active suspension platforms are compressing procurement timelines as Asian high-speed rail operators demand real-time damping adjustment, forcing suppliers to reconfigure pneumatic heritage systems for digital integration.
Growth Catalysts
- EU Green Deal modal-shift mandates:Freight rail tonnage targets in Germany and France are accelerating fleet renewal programs that specify upgraded suspension systems for heavier axle loads.
- Electromagnetic damper adoption:Japanese Shinkansen operators are retrofitting legacy hydraulic configurations with magnetorheological units that adjust stiffness within milliseconds.
- China's CRRC supply chain concentration:Domestic procurement rules for the Fuxing Hao platform series are pulling component sourcing toward certified local suspension module producers.
Market Restraints
- Specialty steel input volatility:Foundry-grade cast steel prices fluctuate with scrap metal arbitrage between Turkish and Indian suppliers, compressing margin predictability for axle box housing producers.
- REACH aromatic oil restrictions:ECHA compliance deadlines for rubber bushing reformulation are extending qualification cycles for European elastomer compounders by eight to fourteen months.
- Pneumatic refrigerant phase-down:F-Gas Regulation timelines are forcing premature platform redesigns before amortization of existing air suspension architectures.
Strategic Opportunities
- India's dedicated freight corridors:The Dedicated Freight Corridor Corporation's electrified heavy-haul lines specify active lateral suspension for 32.5-ton axle loads, opening a ten-year procurement window.
- Light-rail electromagnetic convergence:Streetcar operators in Spain and Italy are combining composite leaf springs with eddy-current dampers to reduce unsprung mass below 1,200 kilograms per bogie.
- Outcome-based maintenance contracts:British and Dutch infrastructure managers are unbundling suspension component replacement from rolling stock leases, creating service revenue pools for condition-monitoring providers.
Industry Challenges
- Magnetorheological fluid certification gaps:Absence of unified ISO test protocols for smart damper fluids is delaying homologation across European notified bodies.
- Legacy pneumatic integration friction:Active suspension retrofits onto 1990s-era trainsets require custom bracketry that extends engineering lead times by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Suspension System Market |
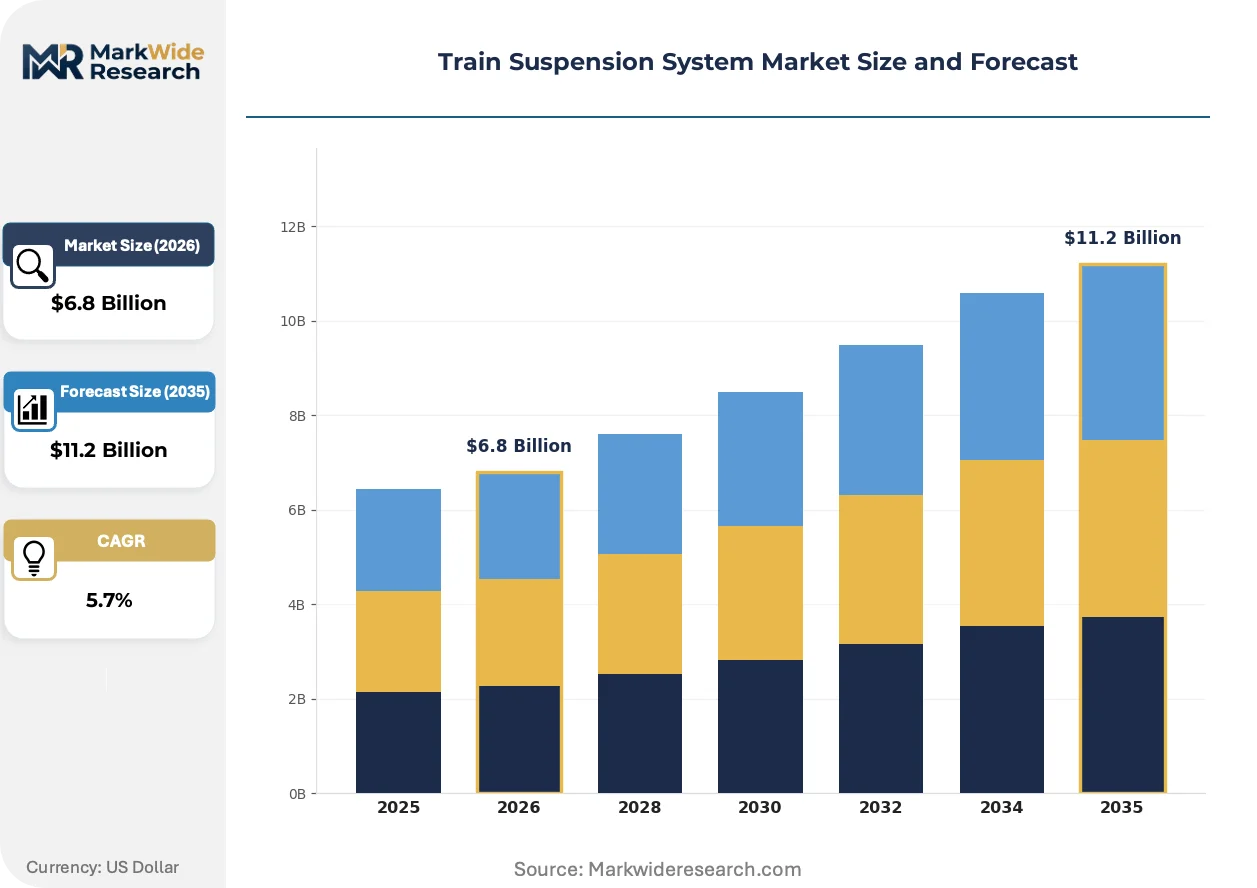
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Suspension, Passive Suspension, Semi-Active Suspension, Magnetic Suspension Installation Type: Original Equipment Manufacturer, Aftermarket, Retrofitting, Custom Installations End User: Heavy Rail, Light Rail, Freight Trains, High-Speed Trains Technology: Hydraulic Systems, Pneumatic Systems, Composite Materials, Electromagnetic Systems |
| Companies Covered | Mando Corporation, Trelleborg, Knorr-Bremse, Norgren, KONI, Amsted Rail Company, Wabtec Corporation, DTR VMS, Bombardier Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Suspension System Market Evolving Landscape
Digital twin architectures are displacing physical prototyping in suspension validation, compressing development cycles while regulators tighten material traceability requirements across multiple jurisdictions.
Magnetorheological damper technology is decentralizing control authority from centralized pneumatic valves to axle-mounted electromagnetic actuators. High-speed operators in South Korea and Taiwan are specifying these units for 300 km/h services that demand sub-50-millisecond response times. The shift is compressing incumbent hydraulic supplier margins while elevating semiconductor and sensor vendors in the value chain.
REACH authorization requirements for aromatic process oils in rubber bushings are forcing compound reformulation across European supply bases. Trelleborg and Continental must qualify bio-based plasticizers by 2026 to maintain access to German and French rolling stock programs. The regulation most acutely affects secondary suspension components where elastomer fatigue resistance governs maintenance intervals.
Buyer concentration among state-backed procurement consortia is consolidating specification authority into fewer technical committees. China's National Railway Administration and Japan's JR Central now issue ten-year framework agreements that lock in suspension suppliers for entire fleet generations. The pattern is most visible in high-speed segments where interoperability certification costs deter mid-tier competitors from bidding.
Train Suspension System Market Segmentation
Train suspension procurement patterns diverge sharply across operating speeds, regulatory jurisdictions, and fleet ownership structures. Each segmentation axis reveals distinct margin profiles and supplier qualification barriers that shape competitive positioning.
Product Type:
Supply concentration tilts toward platforms capable of real-time damping adjustment as Asian high-speed networks accelerate procurement.
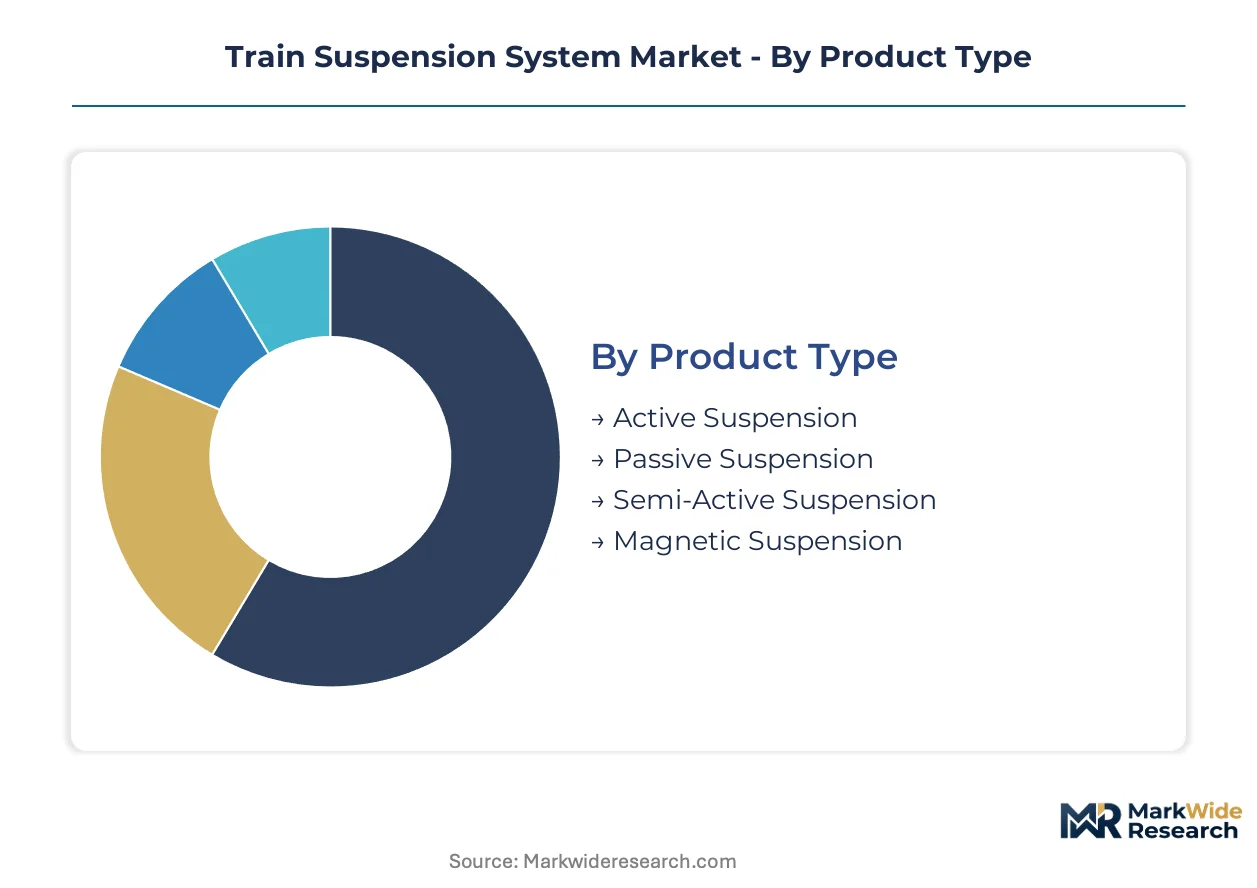
- Active Suspension:Microprocessor-controlled actuators adjust damping parameters within milliseconds based on track condition sensors. China's Fuxing Hao and Japan's N700S Shinkansen specify these systems for 300 km/h-plus services where ISO 2631 comfort thresholds demand continuous optimization.
- Semi-Active Suspension:Magnetorheological dampers modulate fluid viscosity through electromagnetic fields without external power supply. South Korean KTX and Taiwanese THSR operators are retrofitting legacy hydraulic bogies with these units to extend fleet life without full platform replacement.
- Passive Suspension:Coil springs and hydraulic dampers with fixed damping rates dominate freight and regional passenger fleets where capital constraints outweigh ride quality premiums.
- Magnetic Suspension:Electrodynamic levitation systems eliminate mechanical contact for maglev deployments in Shanghai and Japan's Chuo Shinkansen test corridor.
Passive systems absorb the bulk of installed capacity; semi-active configurations are expanding most quickly.
Installation Type:
Procurement patterns split between OEM line-fit programs and lifecycle extension projects driven by regulatory compliance deadlines.
- Original Equipment Manufacturer:Factory integration during bogie assembly allows suspension calibration against specific rail profiles. CRRC's Changchun and Qingdao plants specify supplier lock-in for entire Fuxing platform generations.
- Retrofitting:Active suspension upgrades onto 1990s-era trainsets require custom bracketry and control system integration. German ICE 1 and French TGV Réseau fleets face REACH-driven bushing replacements that trigger broader suspension modernization.
- Aftermarket:Component replacement cycles for dampers and bushings follow distance-based maintenance regimes in North American Class I railroads.
- Custom Installations:Specialized gauge conversions and heritage railway preservation projects demand non-standard suspension geometries.
OEM line-fit commands dominant revenue share; retrofitting activity is climbing the fastest as European fleets age.
End User:
Operating speed requirements and axle load specifications create divergent procurement criteria across rail modes.
- High-Speed Trains:Active lateral suspension and anti-yaw dampers stabilize bogies above 250 km/h. Operators in France, Germany, and Spain mandate multi-system compatibility for cross-border services.
- Freight Trains:Heavy-haul specifications prioritize durability under 32.5-ton axle loads. India's Dedicated Freight Corridor and Australian Pilbara iron ore lines specify maintenance intervals exceeding one million kilometers.
- Heavy Rail:Commuter and intercity services balance passenger comfort against infrastructure access charges in British and Dutch concession frameworks.
- Light Rail:Streetcar and tram systems emphasize low-floor designs with compact suspension envelopes for urban clearance constraints.
Freight applications anchor volume demand; high-speed deployments are gaining share fastest.
Technology:
Material substitution and control system digitization are fragmenting legacy supplier positions across technology categories.
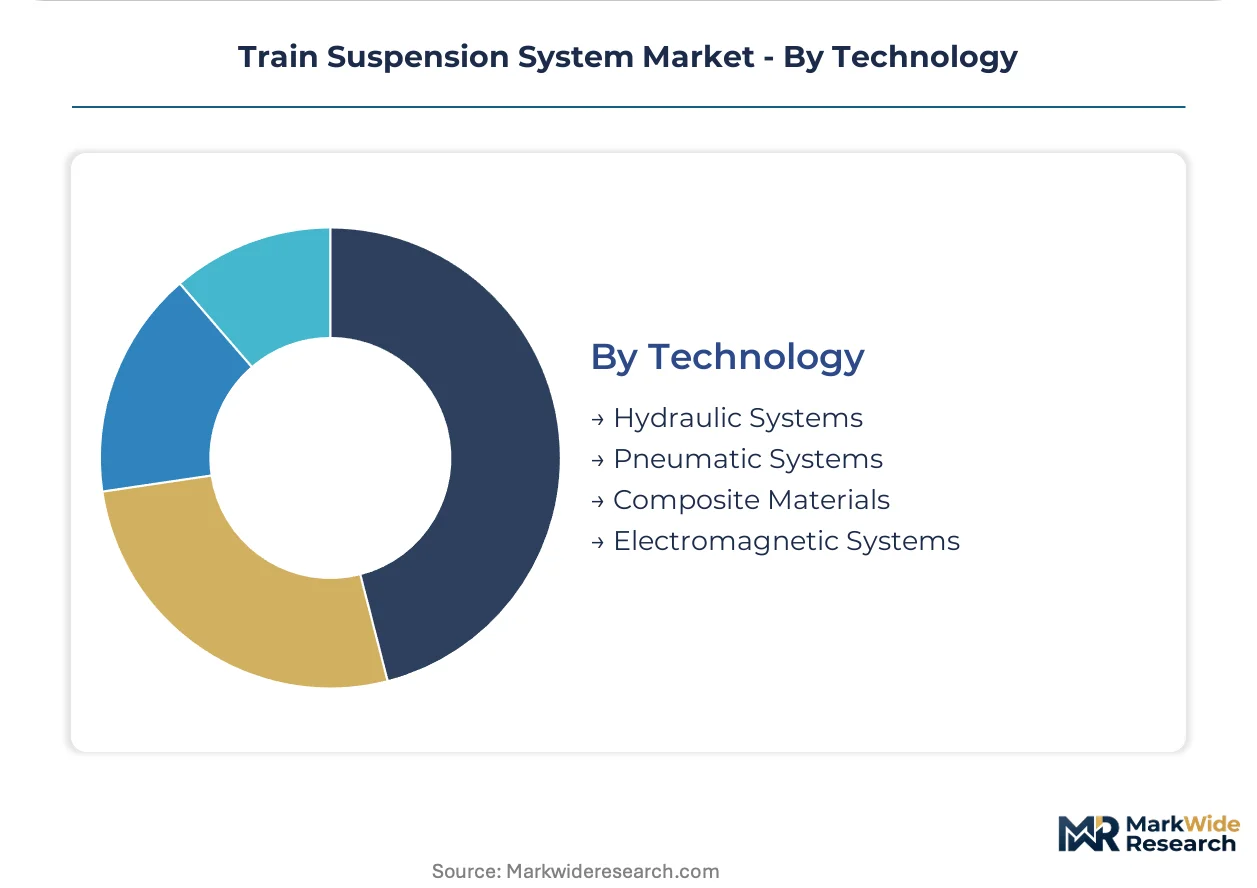
- Electromagnetic Systems:Eddy-current and magnetorheological dampers eliminate hydraulic fluid maintenance. Japanese suppliers dominate through METI-funded R&D consortia targeting next-generation Shinkansen specifications.
- Pneumatic Systems:Air springs and levelling valves retain cost advantages in heavy rail where F-Gas Regulation refrigerant phase-downs now force architectural redesigns.
- Hydraulic Systems:Conventional telescopic dampers face margin compression from composite alternatives in weight-sensitive applications.
- Composite Materials:Carbon fiber leaf springs and glass-reinforced bushings reduce unsprung mass below 1,200 kilograms per bogie in Spanish and Italian light-rail programs.
Pneumatic architectures retain dominant installed base; electromagnetic alternatives are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail procurement concentrates in state-backed operators with multi-year fleet mandates. China, Japan, Germany, the United States, and India anchor suspension demand through high-speed expansion and freight corridor investments.
China
CRRC's Fuxing Hao platform drives active suspension procurement for 350 km/h services. GB/T rail standards tighten certification requirements for imported modules. Changchun and Qingdao manufacturing clusters pull component sourcing toward certified domestic producers.
Japan
Shinkansen renewal programs specify magnetorheological dampers for N700S and next-generation rolling stock. METI energy-efficiency benchmarks shape damper specifications through whole-train consumption targets. Nagoya-based suppliers anchor electromagnetic R&D consortia.
Germany
ICE fleet modernization and freight rail tonnage targets under the EU Green Deal accelerate suspension upgrades. ECHA REACH deadlines force rubber bushing reformulation by 2026. Berlin and Munich technical committees consolidate specification authority for cross-border procurement.
United States
North American Class I railroads prioritize heavy-haul durability under 32.5-ton axle loads for maintenance intervals exceeding one million kilometers. FRA safety standards govern component qualification timelines. Chicago and Pittsburgh industrial corridors concentrate freight suspension manufacturing.
India
The Dedicated Freight Corridor Corporation specifies active lateral suspension for electrified heavy-haul lines, opening a ten-year procurement window. BIS rail standards align with GB/T frameworks for technology transfer. Gujarat and Maharashtra manufacturing zones attract joint ventures for localization.
Train Suspension System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electromagnetic and composite material specializations. Market structure tilts toward consolidation as state procurement consortia reduce vendor counts through ten-year framework agreements. Three archetypes dominate: pneumatic heritage suppliers defending freight positions, electromagnetic specialists capturing high-speed retrofits, and composite material innovators reducing unsprung mass. Competitive moves center on backward integration into cast steel foundries and strategic partnerships for digital twin validation platforms.
Within the pneumatic heritage tier, Knorr-Bremse and Wabtec Corporation exemplify scale-driven positions anchored in braking and foundry integration. Amsted Rail Company occupies the heavy-haul specialization vector. Among electromagnetic innovators, Mando Corporation represents the Korean contingent pursuing magnetorheological damper certification. Trelleborg and KONI sit within the elastomer and hydraulic component layers facing REACH-driven reformulation cycles. Norgren, DTR VMS, and Bombardier Transportation span control system and rolling stock integration roles.
| Leading Market Players |
|---|
| Mando Corporation |
| Trelleborg |
| Knorr-Bremse |
| Norgren |
| KONI |
| Amsted Rail Company |
| Wabtec Corporation |
| DTR VMS |
| Bombardier Transportation |
| Others |
Value Network & Pricing Analysis
EU REACH aromatic oil restrictions gate qualified supply for rubber bushing compounds and premium-tier pricing access for European rolling stock programs. ECHA compliance deadlines extend qualification cycles, forcing buyers into long-term contracts with certified compounders while excluding reformulation-lagged competitors from framework agreements.
Pricing Analysis
Volume leadership in passive pneumatic systems trades at thinner margins than premium active suspension platforms commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 2631 certification grade and F-Gas Regulation refrigerant compliance status. Cost compression in hydraulic tiers is intensifying because composite material substitution erodes incumbent damper positions. Freight rail operators exhibit highest price sensitivity; high-speed consortia prioritize performance thresholds over unit economics.
Supply Chain Analysis
Regional distribution centers in Changchun, Qingdao, and Nagoya anchor hub-and-spoke patterns for active suspension module delivery. Manufacturing gravity draws from China, Japan, and Germany for foundry-grade cast steel, magnetorheological fluids, and elastomer compounds. Single-source vulnerability concentrates in Turkish-Indian scrap metal arbitrage for axle box housings. Distribution runs through CRRC-certified domestic channels in China and JR Central-approved logistics networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
State-backed procurement consolidation is compressing vendor counts, forcing mid-tier suspension suppliers into acquisition targets or exit.
For Market Incumbents: Deploy backward integration into captive foundry capacity to defend against cast steel price volatility and emerging electromagnetic specialists. Lock in ten-year framework agreements with China's National Railway Administration and Japan's JR Central before qualification barriers harden. Anchor pneumatic heritage positions through F-Gas Regulation-compliant refrigerant architectures. For New Entrants and Emerging Players: Digital condition-monitoring platforms offer the fastest route to attach retrofit service revenue on European ICE and TGV fleets facing REACH-driven modernization. Target India's Dedicated Freight Corridor Corporation procurement windows before local joint ventures saturate certification pathways. Lead with outcome-based maintenance contracts rather than component sales. For Investors and Strategic Acquirers: Magnetorheological damper homologation across European notified bodies is the leading indicator that electromagnetic tier margins will stabilize above hydraulic legacy positions. Five-to-ten-year viability favors composite material innovators with sub-1,200 kilogram unsprung mass proofs in Spanish and Italian light-rail programs. Watch for BIS-GB/T alignment completion as the signal for India's localization threshold crossing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Wabtec Corporation's captive steel production insulates margin predictability from scrap metal arbitrage volatility. |
| Magnetorheological Damper Certification Investment | Mando Corporation's METI-funded R&D consortia secure N700S Shinkansen specification lock-in against hydraulic incumbents. |
| REACH-Compliant Elastomer Reformulation | Trelleborg's bio-based plasticizer qualification by ECHA deadlines preserves German and French rolling stock access. |
| Outcome-Based Maintenance Contract Unbundling | British and Dutch infrastructure managers' suspension replacement separation creates recurring service revenue pools. |
| Digital Twin Validation Platform Partnership | Knorr-Bremse's virtual prototyping compression accelerates active suspension procurement timelines for Asian high-speed operators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this train suspension system assessment. Primary interviews with rolling stock procurement directors, foundry operations managers, elastomer compound technical leads, and infrastructure maintenance contract officers combined with ECHA REACH documentation, GB/T rail standard publications, and METI energy-efficiency benchmark disclosures. Bottom-up unit economics triangulated against top-down fleet renewal mandate aggregation.
Granularity-level modeling captured active, semi-active, passive, and magnetic suspension product types; OEM line-fit, retrofitting, aftermarket, and custom installation channels; high-speed, freight, heavy rail, and light rail end users; and electromagnetic, pneumatic, hydraulic, and composite material technologies across the analysis window. CAGRs derived from bogie-level content per vehicle trajectories and axle load specification evolution. Forecast inputs incorporated F-Gas Regulation phase-down timelines and CRRC domestic procurement rule changes.
The model holds under steady regulatory enforcement timelines; deviation in ECHA deadline extensions or BIS-GB/T harmonization acceleration would shift supplier qualification windows. Forecasts reflect documented assumptions around state-backed procurement consolidation and material substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rail Damper Market
Railway
Locomotive Maintenance Market
Railway
Railway Track Market
Railway
Railroad Brake Shoe Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Connected Rail Market
Railway
Railway Bearing Market
Railway
Tugger Trains Market
Railway
South Africa Rail Freight Transport Market
Railway
Rail Brake Frame Market
Railway
40-Foot Platform Wagons Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
South Korea Connected Rail Market
Railway
Railway Axle Market
Railway
Railcar Vehicle Toilet Market
Railway
Asia Pacific Rail Freight Transport Market