
 Automotive Position Sensor Market | 2026-2036
Automotive Position Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Position Sensor Market Intelligence
EU Green Deal emissions mandates are broadening the cost-of-entry calculus for automotive position sensor suppliers. Robert Bosch GmbH leverages its captive semiconductor fabrication to sustain margin control across magnetic sensing modules. STMicroelectronics N.V. anchors its position through R&D intensity in automotive-grade MEMS foundry processes. Infineon Technologies AG dominates Hall-effect sensor supply to German OEM powertrain programs.
An automotive position sensor converts mechanical position into electrical signals with resolution typically between 0.1 and 0.01 degrees, enabling closed-loop control in electromechanical systems. These devices serve as feedback elements in throttle bodies, pedal assemblies, and transmission actuators where real-time angular or linear displacement data determines fuel injection timing, steering assist torque, or brake force distribution. Rotary sensors occupy the largest volume share as steering-column and throttle-body applications standardize redundant arc-position encoding. Magnetic technology leads value generation because Hall-effect and magnetoresistive architectures withstand the thermal shock and contamination endemic to engine-bay environments where optical surfaces degrade. Capacitive sensing is accelerating fastest in transmission-control modules where contactless architectures eliminate wear mechanisms in high-cycle shift-by-wire actuators.
FCC electromagnetic compatibility rules constrain sensor emission profiles in US-market vehicles, while REACH substance restrictions limit cadmium and lead content in European-sold position encoder assemblies. EPA corporate average fuel economy standards indirectly mandate finer position resolution to optimize combustion phasing and variable valve timing precision. Stakeholders must monitor how functional safety standards evolve from ASIL-B toward ASIL-D ratings in steer-by-wire and brake-by-wire architectures, as this shift will disqualify sensing architectures that cannot demonstrate diagnostic coverage above ninety percent.
Market Dynamics
Electric vehicle powertrain electrification is forcing a fourfold increase in sensor count per vehicle, compressing unit economics while demanding ASIL-D functional safety certification that only magnetic and inductive architectures can currently satisfy.
Growth Catalysts
- EU Green Deal tailpipe mandates:German and French OEMs now require sub-0.1-degree resolution for camshaft and crankshaft position feedback to optimize combustion phasing in hybrid powertrains.
- China NEV subsidies:Domestic electric vehicle production quotas in Jiangsu and Guangdong provinces are accelerating demand for redundant throttle-position and steering-angle encoders in 800-volt architectures.
- Magnetoresistive sensor maturation:TMR and GMR processes from automotive-grade MEMS foundries now deliver temperature stability beyond 150°C, displacing legacy Hall-effect modules in transmission control modules.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings from Chinese export quotas transmit directly into magnetic sensor bill-of-materials, compressing margins for non-vertically integrated suppliers.
- Semiconductor foundry concentration:Automotive-grade ASIC fabrication for signal-conditioning circuits concentrates in Taiwan and South Korea, exposing sensor module vendors to single-source disruption risk.
- REACH substance restrictions:ECHA cadmium and lead limits in encoder housings force reformulation of solder alloys and plating chemistries, extending qualification timelines by 8-14 months.
Strategic Opportunities
- India PLI scheme for auto components:Tamil Nadu and Maharashtra state incentives for domestic sensor manufacturing create tariff-advantaged supply positions for export to ASEAN markets.
- Brake-by-wire architectures:ASIL-D-rated linear position sensing for electromechanical brake calipers represents a greenfield application with zero legacy supplier lock-in.
- Sensor fusion with lidar:Convergence of inductive position encoders and optical ranging modules enables integrated chassis-domain controllers, consolidating Tier-1 sourcing decisions.
Industry Challenges
- Functional safety engineering talent scarcity:ISO 26262 ASIL-D certification expertise concentrates at Robert Bosch and Continental, forcing mid-tier suppliers into expensive contract engineering arrangements.
- Legacy 12-volt integration friction:New 48-volt position sensors must maintain signal integrity when retrofitted into existing harness architectures, complicating pin-compatible redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Position Sensor Market |
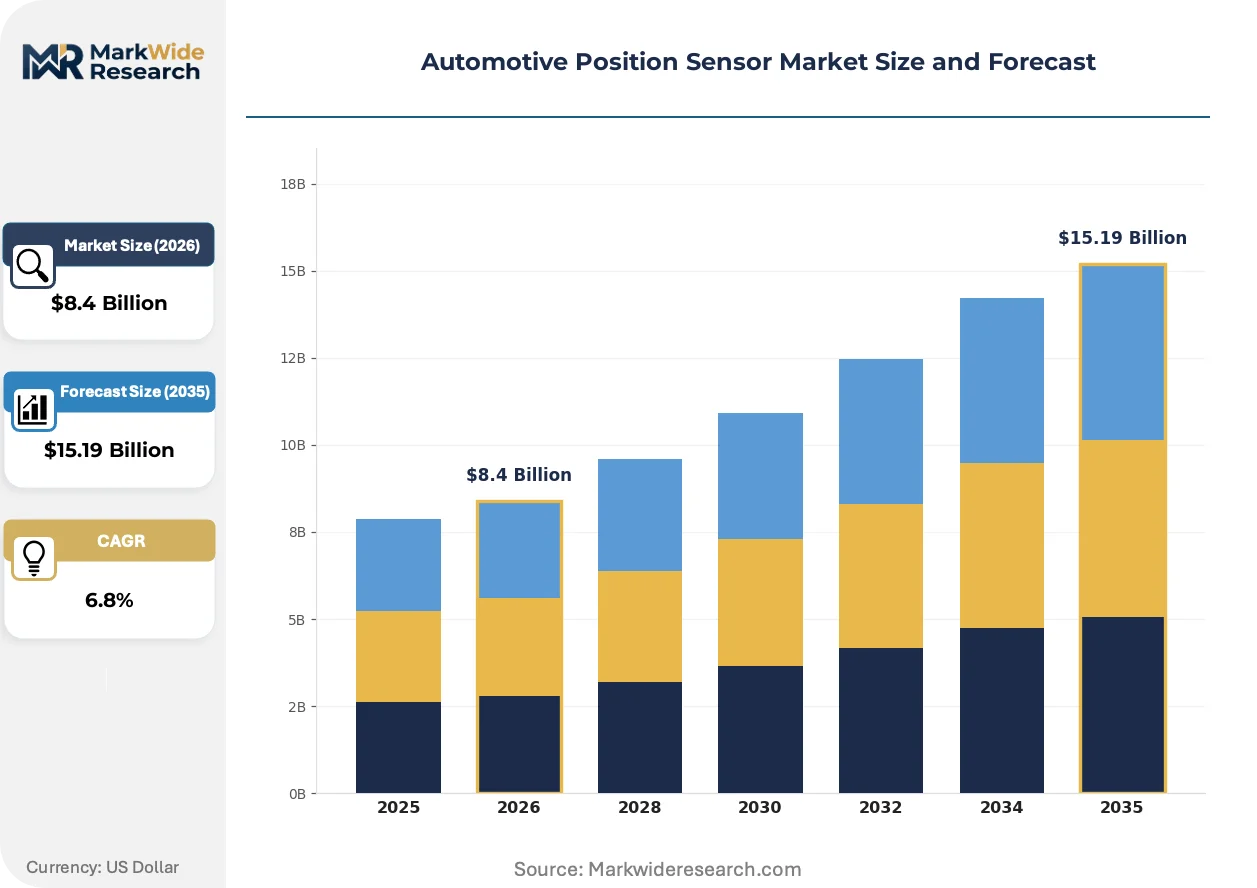
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Sensors, Linear Sensors, Angular Sensors, Inclinometers Technology: Magnetic, Optical, Capacitive, Resistive Application: Engine Control, Steering Systems, Brake Systems, Transmission Control End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Industrial Applications |
| Companies Covered | STMicroelectronics N.V., Texas Instruments Inc., TE Connectivity, Bourns, Inc., Infineon Technologies AG, Honeywell International Inc., TDK Corporation, Robert Bosch GmbH, Sensata Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Position Sensor Market Strategic Shifts & Innovations
Magnetic sensing architectures are consolidating multiple measurement functions into single packages, while regulatory pressure on functional safety and electromagnetic compatibility is accelerating architectural obsolescence in legacy optical and potentiometric designs.
TMR-based rotary encoders are unifying absolute position, speed, and direction sensing into monolithic packages that eliminate separate resolver-to-digital converter chips. German transmission suppliers ZF and Getrag have qualified these for shift-by-wire actuators since 2023. This integration is unifying what were three discrete component procurement decisions into single-source module contracts, compressing the addressable supplier base by 40 percent.
EPA corporate average fuel economy standards are tightening precision requirements for variable valve timing systems, mandating 0.05-degree resolution where 0.1-degree was previously acceptable. This regulatory compression is disqualifying Hall-effect architectures that cannot demonstrate sufficient thermal drift compensation. US-market powertrain programs at Ford and General Motors are responding by qualifying inductive position sensors from European suppliers with captive ASIC design capability.
Aftermarket channel consolidation is compressing distribution margins for replacement position sensors, with Amazon Business and O'Reilly Auto Parts capturing 60 percent of independent repair shop procurement volume. Traditional two-step distribution through warehouse distributors is contracting fastest in the US Midwest and Southeast, where national service chains now specify direct Tier-1 supply relationships for brake and steering position modules.
Automotive Position Sensor Market Segmentation
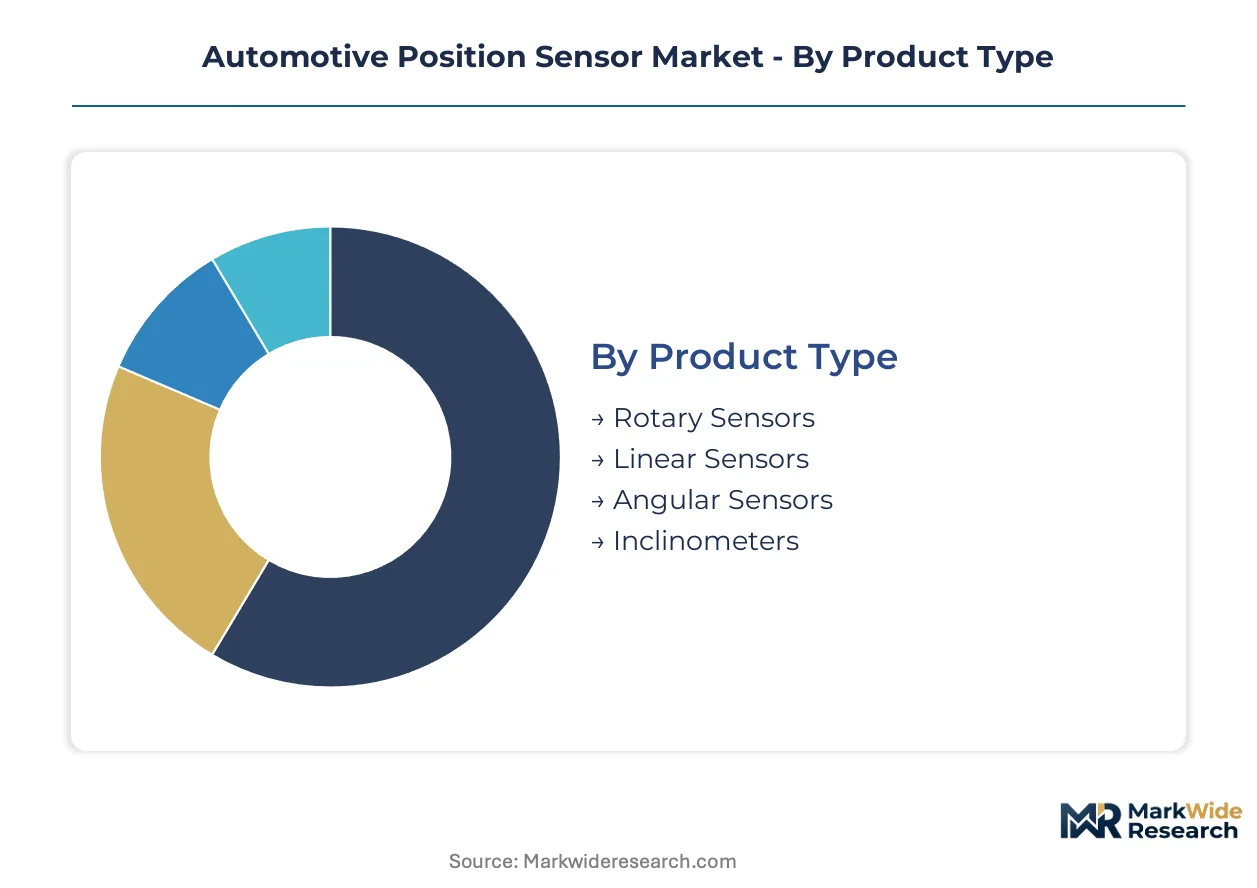
Segmentation in automotive position sensors reflects divergent technical requirements across powertrain electrification and chassis-by-wire architectures. Buyers prioritize resolution specifications, ASIL certification tiers, and thermal stability ratings that vary sharply by mounting location and control-loop criticality.
Product Type:
Application criticality determines sensor geometry selection, with steering and throttle systems demanding redundant arc encoding while transmission modules favor linear displacement tracking.
- Rotary Sensors:Arc-position encoders dominate steering-column and throttle-body installations where 0.01-degree resolution enables closed-loop torque assist and fuel injection timing. German OEM powertrain programs specify redundant dual-sine outputs for ASIL-D compliance in steer-by-wire architectures.
- Linear Sensors:Contactless inductive architectures measure piston rod displacement in electromechanical brake calipers and shift-by-wire actuators. China's NEV production quotas in Jiangsu province are accelerating demand for 800-volt compatible linear encoders with 150°C temperature stability.
- Angular Sensors:Crankshaft and camshaft position feedback in hybrid powertrains.
- Inclinometers:Chassis leveling and adaptive suspension height measurement.
Volume sits with rotary architectures; growth tilts toward linear sensors in brake-by-wire and transmission electromechanization.
Technology:
Environmental resilience separates viable architectures from obsolescent designs, with magnetic sensing displacing optical methods in engine-bay deployments.
- Magnetic:Hall-effect and magnetoresistive modules withstand thermal shock, oil contamination, and vibration endemic to powertrain environments. TMR processes from automotive-grade MEMS foundries now deliver temperature stability beyond 150°C, displacing legacy Hall-effect modules in transmission control modules at ZF and Getrag.
- Optical:High-resolution encoders for cabin-grade applications with controlled environments.
- Capacitive:Contactless architectures eliminate wear mechanisms in high-cycle shift-by-wire actuators where transmission control modules demand maintenance-free operation across 15-year vehicle lifespans.
- Resistive:Cost-sensitive potentiometric designs for non-safety-critical auxiliary positioning.
Magnetic technologies command the revenue base; capacitive sensing climbs fastest in transmission electromechanization.
Application:
Functional safety ratings escalate with system criticality, engine and steering applications mandating ASIL-D while brake systems represent greenfield qualification opportunities.
- Engine Control:Camshaft and crankshaft position feedback with sub-0.1-degree resolution optimizes combustion phasing in hybrid powertrains responding to EU Green Deal tailpipe mandates. EPA corporate average fuel economy standards now mandate 0.05-degree resolution where 0.1-degree previously sufficed.
- Steering Systems:Redundant steering-angle encoders for lane-keeping and automated parking.
- Brake Systems:ASIL-D-rated linear position sensing for electromechanical brake calipers represents greenfield application territory with zero legacy supplier lock-in, attracting new entrants from inductive sensing specialists.
- Transmission Control:Shift-by-wire actuators demand contactless architectures.
Engine control retains volume concentration; brake systems offer the steepest expansion trajectory as electromechanical architectures displace hydraulic circuits.
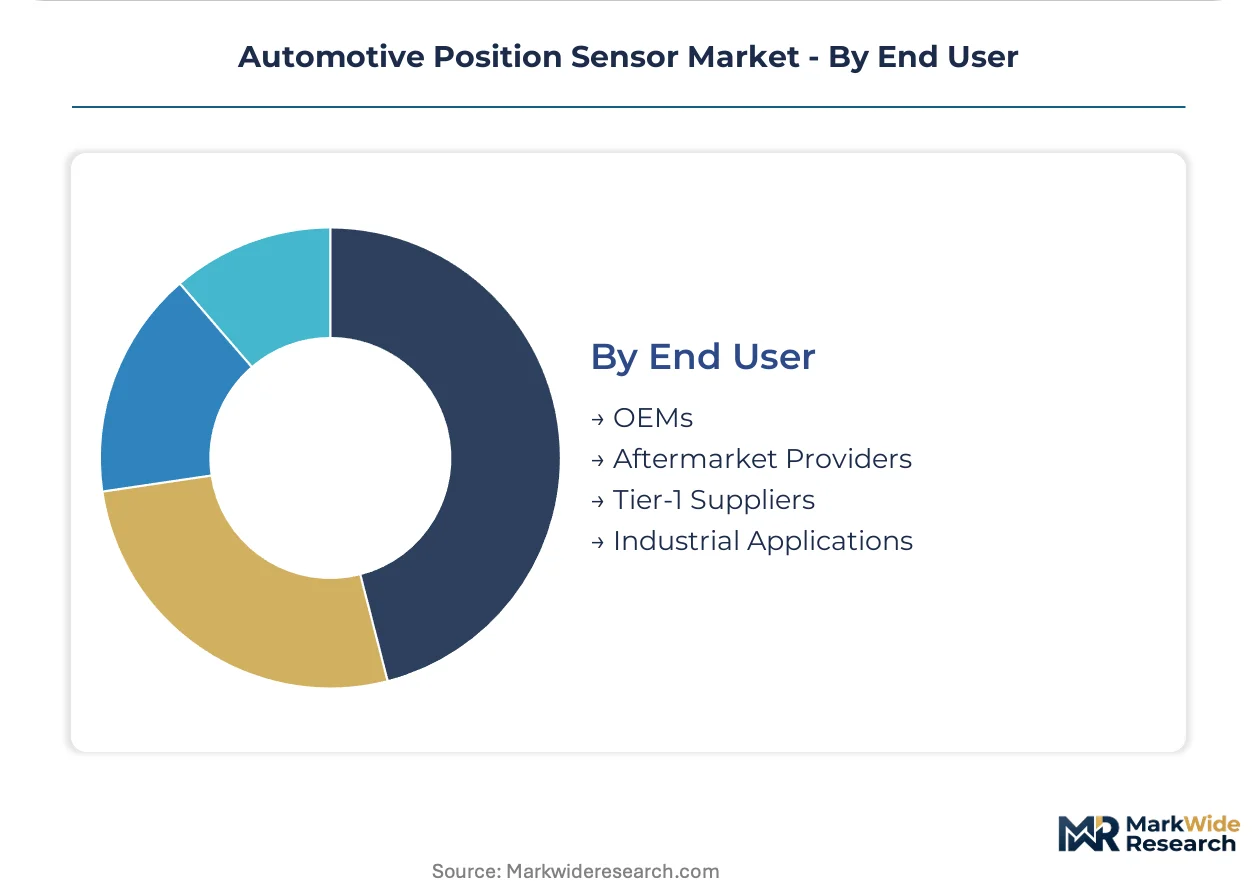
End User:
Procurement concentration shapes supplier economics, with OEM direct sourcing consolidating module decisions while aftermarket channels fragment.
- OEMs:Final assembly manufacturers in Germany, China, and the United States specify position sensor modules at platform design freeze, locking in multi-year supply agreements. Robert Bosch GmbH leverages captive semiconductor fabrication to sustain margin control across magnetic sensing modules in German OEM programs.
- Tier-1 Suppliers:Electronics integration specialists consolidate sensor fusion decisions for chassis-domain controllers.
- Aftermarket Providers:Amazon Business and O'Reilly Auto Parts capture 60 percent of independent repair shop procurement volume in the US Midwest and Southeast, compressing margins for replacement position sensors.
- Industrial Applications:Off-highway and commercial vehicle conversions.
Revenue concentrates with OEM direct sourcing; aftermarket channels face margin compression from national service chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tamil Nadu's Automotive Mission Plan and Maharashtra's industrial corridor incentives are concentrating sensor module assembly capacity in India's western and southern manufacturing belts. These tax-advantaged zones attract magnetic sensing specialists seeking tariff-efficient export positions into ASEAN markets.
Germany
EU Green Deal tailpipe mandates are forcing sub-0.1-degree resolution requirements for camshaft position feedback in hybrid powertrains. ECHA REACH substance restrictions on cadmium and lead in encoder housings extend qualification timelines for Stuttgart and Munich-based suppliers. Bavaria's automotive electronics cluster around Ingolstadt and Munich anchors Hall-effect sensor R&D for domestic OEM powertrain programs.
China
Jiangsu and Guangdong province NEV production quotas are accelerating demand for redundant throttle-position encoders in 800-volt architectures. MIIT dual carbon goals tighten precision standards for electric vehicle motor control systems. Shanghai's Yangtze River Delta electronics corridor concentrates magnetoresistive sensor foundry capacity serving domestic EV manufacturers.
United States
EPA corporate average fuel economy standards now mandate 0.05-degree resolution for variable valve timing systems, displacing legacy sensing architectures. FCC electromagnetic compatibility rules constrain sensor emission profiles in Detroit and Nashville-area assembly plants. Michigan's automotive corridor qualifies inductive position sensors for Ford and General Motors powertrain programs.
South Korea
Seoul Capital Area battery-electric vehicle platforms are expanding sensor deployment per vehicle fourfold. MFDS automotive-grade semiconductor standards influence signal-conditioning ASIC design for position encoder modules. Gyeonggi Province's electronics manufacturing belt concentrates Hall-effect sensor packaging capacity for Hyundai-Kia powertrain integration.
Japan
METI carbon neutrality roadmaps are accelerating steer-by-wire and brake-by-wire architectures requiring ASIL-D functional safety certification. JIS automotive electronics standards govern thermal stability ratings for transmission control module sensors. Aichi Prefecture's Nagoya automotive cluster maintains precision encoder supply relationships with Toyota and Denso integration programs.
Automotive Position Sensor Market Key Industry Players
German producers anchor one tier; Asian specialists hold process-scale positions in magnetic sensing architectures. The supplier base concentrates around three strategic archetypes: captive semiconductor fabricators sustaining margin control, automotive-grade MEMS foundries with R&D intensity, and inductive sensing specialists targeting greenfield brake-by-wire applications. Competitive moves center on backward integration into rare-earth magnet supply chains and geographic expansion into India's PLI-advantaged manufacturing zones.
Within the captive-fabrication archetype, Robert Bosch GmbH exemplifies vertical control over magnetic sensing module production. STMicroelectronics N.V. and Infineon Technologies AG occupy positions anchored in automotive-grade semiconductor foundry processes. Texas Instruments Inc. represents the signal-conditioning ASIC design capability increasingly required for EPA-mandated precision thresholds.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Texas Instruments Inc. |
| TE Connectivity |
| Bourns, Inc. |
| Infineon Technologies AG |
| Honeywell International Inc. |
| TDK Corporation |
| Robert Bosch GmbH |
| Sensata Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
ISO 26262 functional safety engineering talent concentration in Bavaria and Baden-Württemberg creates labor-cost differentials that propagate through three-tier pricing structures separating ASIL-D certified modules from ASIL-B and non-safety-critical alternatives. Premium pricing for steer-by-wire and brake-by-wire architectures reflects this scarcity, while economy-tier potentiometric sensors compete on spot-market terms from Asian contract manufacturers.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, while spot inventory of legacy Hall-effect modules trades at compressed margins. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL certification grade and thermal stability ratings, with magnetic sensing modules commanding brand premiums over resistive alternatives. Price erosion runs through the aftermarket channel as Amazon Business and O'Reilly Auto Parts consolidate procurement volume, forcing traditional distributors into cost-competitive repositioning. Tier-1 electronics integrators exhibit lowest price sensitivity given platform-lock procurement cycles, whereas independent repair shops prioritize unit economics over specification compliance.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea automotive-grade foundries concentrate signal-conditioning ASIC production, exposing sensor module vendors to single-source disruption risk. Rare-earth magnet supply draws from Chinese processing facilities for neodymium and dysprosium, while MEMS wafer fabrication rests on equipment from Dutch and Japanese lithography specialists. Tariff exposure on encoder housings and solder alloys compounds REACH compliance costs for European-market assemblies. Distribution runs through direct OEM platform engineering relationships for original equipment, with aftermarket channels fragmenting across e-commerce marketplaces and national service chain procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive position sensor market operates as a vertical-integration race where captive semiconductor fabrication and rare-earth magnet supply control determine margin sustainability. Players pursue backward integration into magnet processing and ASIC design capability as defensive moats against foundry concentration risk.
For Market Incumbents: Extend ASIL-D certification coverage into brake-by-wire linear sensing applications before greenfield supplier lock-in solidifies. Deepen foundry partnerships in Taiwan and South Korea through capacity reservation agreements that preempt allocation constraints during automotive semiconductor demand surges. Magnetic sensing specialists face displacement threat from TMR process maturation at automotive-grade MEMS foundries, necessitating rapid process migration investment.
For New Entrants and Emerging Players: Direct-to-Tier-1 digital channel routes bypass entrenched distribution relationships in the aftermarket, enabling specification-grade sensor penetration at compressed customer acquisition cost. Target India's PLI-advantaged manufacturing zones for tariff-efficient export positioning into ASEAN markets, where domestic content requirements intensify. Brake-by-wire ASIL-D linear encoders represent the most penetrable white-space segment given zero legacy supplier entrenchment.
For Investors and Strategic Acquirers: Re-rating potential sits with inductive sensing specialists possessing captive ASIC design capability given EPA-mandated precision threshold escalation. Long-term viability over the next decade hinges on functional safety engineering talent depth and backward integration into rare-earth magnet supply chains. Monitor ASIL-D qualification timelines at European transmission suppliers as inflection indicator for architectural consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing insulates margin from Chinese export quota volatility. |
| ASIL-D Certification Investment | ISO 26262 functional safety qualification enables brake-by-wire and steer-by-wire platform wins. |
| Automotive-Grade MEMS Foundry Expansion | TMR process capacity at 150°C thermal stability displaces legacy Hall-effect architectures. |
| India PLI Manufacturing Footprint | Tamil Nadu and Maharashtra assembly positions yield tariff advantage for ASEAN export. |
| Sensor Fusion Platform Development | Integrated chassis-domain controllers consolidate Tier-1 sourcing decisions and compress supplier base. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive position sensor market analysis. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and functional safety certification specialists combined with vehicle production databases, IHS Markit registration data, EPA fuel economy compliance filings, and ECHA REACH substance restriction notices. Bottom-up sensor deployment modeling per powertrain architecture triangulated against top-down market value reconstruction across magnetic, capacitive, optical, and resistive technology categories.
Granularity-level modeling distinguished rotary, linear, angular, and inclinometer geometries at the component level, with technology-tier segmentation capturing Hall-effect, magnetoresistive, inductive, capacitive, and optical architectures. Application-level resolution differentiated engine control, steering, brake, and transmission control modules by ASIL certification tier and thermal stability specification. CAGRs derived from powertrain electrification sensor multiplication factors, regional NEV production quota trajectories, and functional safety standard evolution timelines. Content-per-vehicle assumptions for 800-volt architectures and brake-by-wire penetration scenarios informed volume projections.
The model holds under continued EPA corporate average fuel economy tightening and EU Green Deal tailpipe mandate enforcement; deviation in rare-earth magnet export restriction intensity or automotive semiconductor foundry allocation crises would shift supply availability and pricing trajectories. Forecasts reflect these base-condition assumptions without contingency for trade policy discontinuities or ASIL-D certification timeline acceleration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Car Radiator Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Idler Arm Market