

Bicycle Chain Device Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Chain Device Market Insights
The EU Green Deal is restructuring procurement criteria across European bicycle OEMs, compelling suppliers to demonstrate lifecycle emissions reductions and recyclability in chain device production. Shimano leverages its integrated drivetrain ecosystem to control specification-setting power with major frame builders. SRAM competes through aggressive R&D intensity in wireless electronic shifting systems that demand proprietary chain interfaces. KMC Chains anchors the aftermarket replacement channel with broad compatibility across competing drivetrain standards.
A bicycle chain device is a precision-engineered linkage assembly of inner and outer plates, pins, bushings, and rollers, typically manufactured through multi-stage cold forging, heat treatment to HRC 50-60 hardness, and precision riveting, designed to transmit pedaling torque from chainrings to rear cassettes under varying load and contamination conditions. Multi-speed chains dominate value generation due to narrow-width engineering complexity and compatibility demands across 10- to 13-speed cassettes, while rust-resistant chains represent the fastest-expanding material segment as wet-climate commuters and fleet operators prioritize service-interval extension. Mountain bicycle applications sustain premium pricing through reinforced plate designs that withstand high-torque, high-impact loading regimes.
The EU's REACH regulation governs chemical substance restrictions in surface coatings and lubricants, while CE marking requirements enforce mechanical safety standards for bicycle components sold within the single market; Japan's JIS standards additionally shape export quality benchmarks for manufacturers serving Asian OEM supply chains. The US Consumer Product Safety Commission maintains recall authority over component failures, creating liability exposure that drives investment in fatigue-testing protocols. Stakeholders must monitor evolving battery-electric bicycle torque specifications that exceed traditional human-power loading and demand reinforced chain architectures.
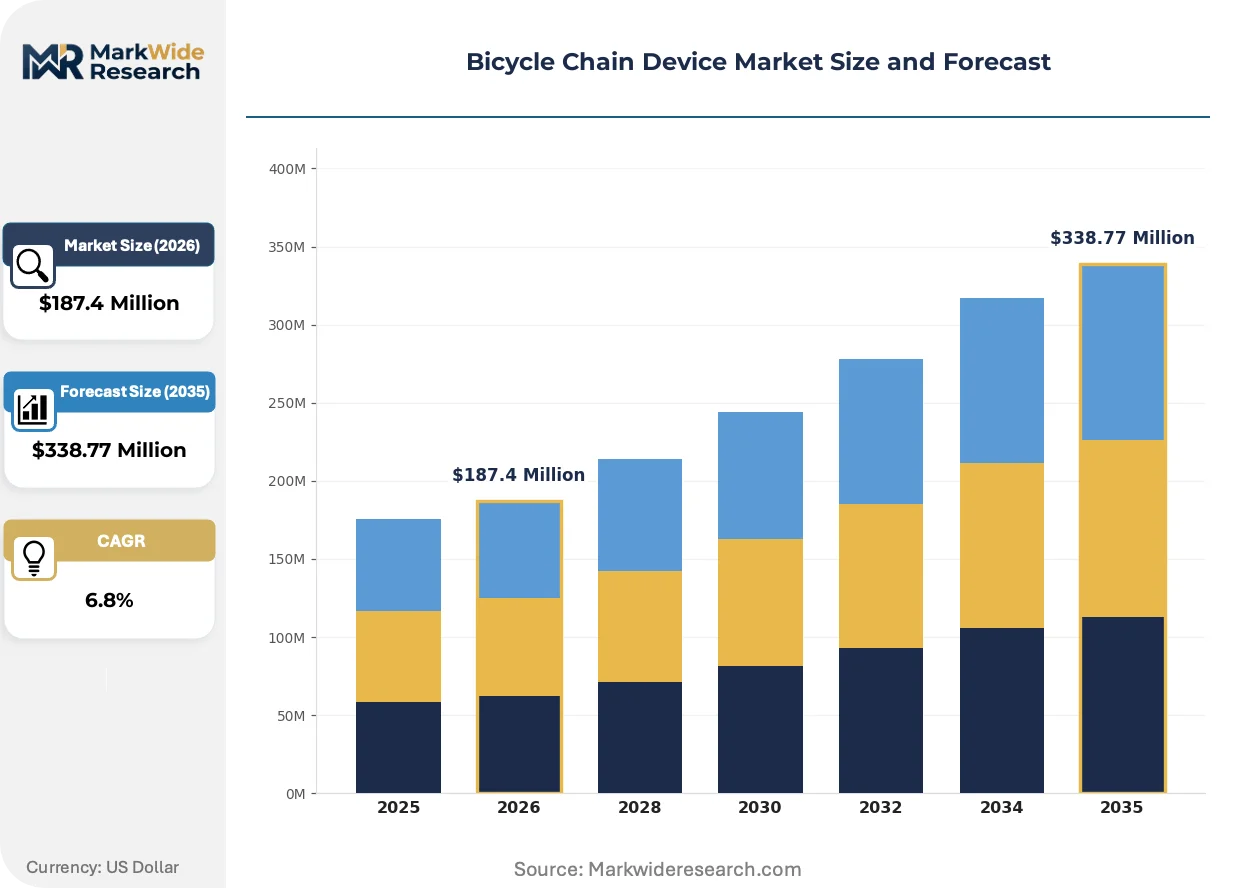
Market Dynamics
The EU Green Deal's transport decarbonization mandate is restructuring procurement criteria across European bicycle OEMs, compelling drivetrain suppliers to demonstrate lifecycle emissions reductions and recyclability in chain device production.
Growth Catalysts
- Urban cycling infrastructure expansion:Copenhagen and Amsterdam are extending dedicated cycling corridors, creating sustained fleet replacement demand for rust-resistant chain architectures in high-utilization municipal bike-share systems.
- REACH regulation compliance:Chemical substance restrictions in surface coatings are accelerating R&D investment in water-based lubricants and chrome-free plating processes that extend service intervals.
- E-bike torque specifications:Battery-electric bicycle motor outputs exceeding traditional human-power loading are forcing reinforced plate designs and hardened pin architectures into mainstream specification sheets.
Market Restraints
- Alloy steel price volatility:Cold-forging grade steel input costs fluctuate with energy-intensive European smelter output, compressing margin buffers for precision component suppliers in Germany's Ruhr industrial cluster.
- Specification lock-in:Integrated drivetrain ecosystems from dominant OEMs create proprietary chain interfaces that fragment aftermarket compatibility and raise switching costs for independent component manufacturers.
- JIS standard compliance costs:Japanese industrial standards for export quality benchmarks impose additional fatigue-testing and documentation burdens on suppliers serving Asian OEM supply chains.
Strategic Opportunities
- Fleet operator channel penetration:Last-mile delivery aggregators in wet-climate Northern European cities represent underpenetrated volume demand for corrosion-resistant, extended-service-interval chain architectures.
- CSRD disclosure alignment:Corporate Sustainability Reporting Directive requirements are creating procurement preference for suppliers with verified carbon footprint data across Scope 1-3 emissions.
- Wireless electronic shifting convergence:Integration of electronic derailleur systems with reinforced chain interfaces opens specification-setting opportunities for component suppliers outside traditional mechanical drivetrain hierarchies.
Industry Challenges
- Heat treatment technician scarcity:Multi-stage hardening processes requiring HRC 50-60 precision control face talent pipeline gaps as experienced metallurgists retire from European forging operations.
- CE marking timeline compression:Mechanical safety certification for bicycle components sold within the single market demands extended validation cycles that delay product launch windows.
- Legacy inventory reconciliation:Rapid 10- to 13-speed cassette transitions strand obsolete narrow-width chain stock in distribution channels, requiring write-down absorption.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Chain Device Market Trends and Innovations
Electrification of bicycle propulsion systems is fundamentally altering load profiles and durability requirements across drivetrain component engineering. Material science advances and regulatory disclosure mandates are simultaneously reshaping supplier qualification protocols.
Reinforced plate architectures with optimized pin-bushing geometries are electrifying category segmentation as e-bike torque loads exceed 85 Nm sustained outputs. Fleet operators in German and Dutch urban delivery networks are specifying these hardened configurations for 15,000+ kilometer service intervals. The technology is electrifying specification-setting power away from traditional road-racing performance metrics toward durability-under-load engineering benchmarks.
REACH chemical substance restrictions are eliminating hexavalent chromium surface treatments from European supply chains by 2026. Component manufacturers are pivoting to trivalent chrome and ceramic-based coating alternatives that maintain corrosion resistance without restricted substances. Wet-climate commuter applications in Belgium and the Netherlands are driving fastest adoption of these compliant surface treatments.
Direct procurement relationships between municipal fleet operators and component manufacturers are disintermediating traditional aftermarket distributors. Large-volume buyers in Scandinavian cities are negotiating multi-year supply agreements with specified mean-time-between-failure metrics. This pattern is most visible in Denmark's regional transport authority consolidation of bike-share maintenance contracts.
Bicycle Chain Device Market Segmentation
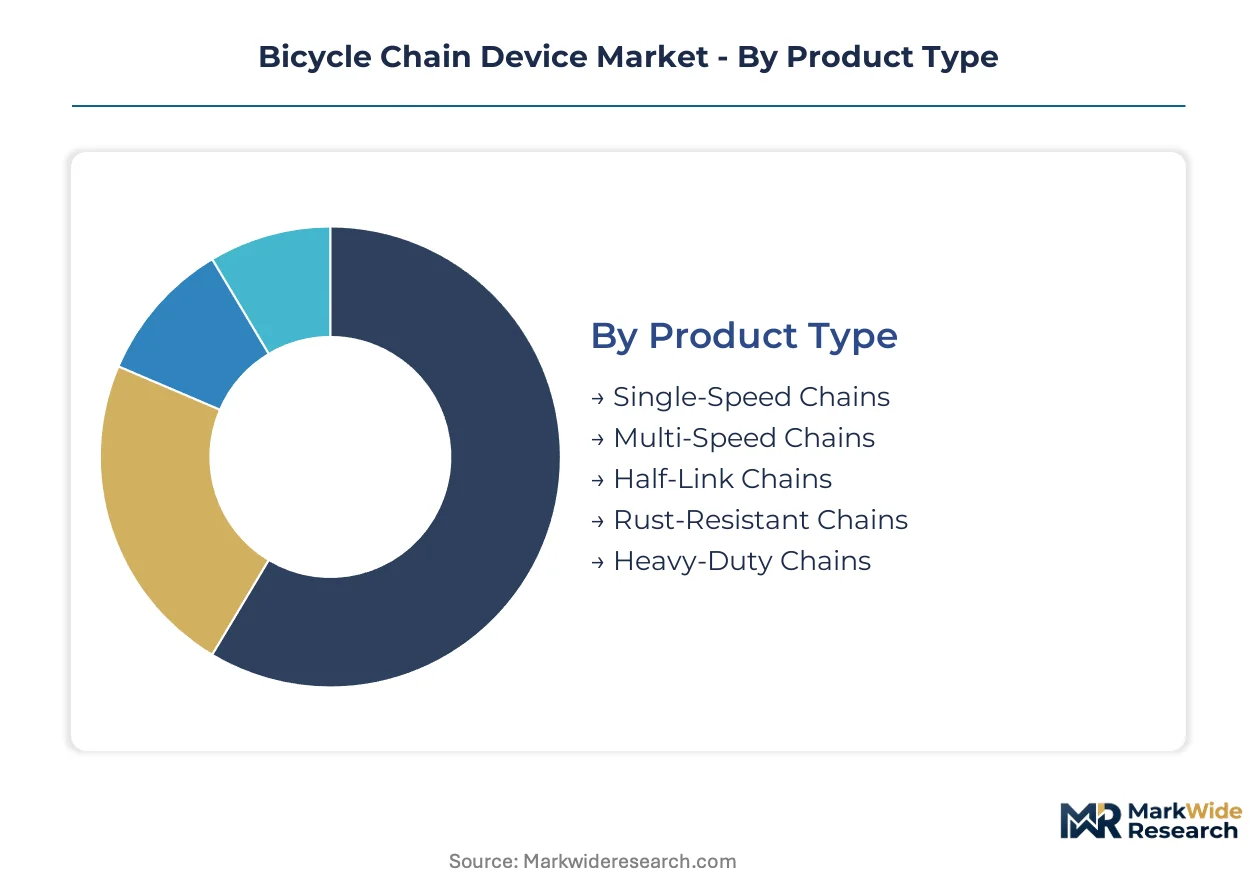
Segmentation in bicycle chain devices reveals how capital deployment, torque specifications, and climate exposure concentrate purchasing power across divergent engineering requirements. Each dimension exposes different margin structures and specification-setting hierarchies among OEMs and aftermarket channels.
Product Type:
Capital intensity concentrates in narrow-width precision forging lines and multi-stage heat treatment infrastructure, with equipment utilization rates varying dramatically across speed compatibility tiers.
- Multi-Speed Chains:Narrow-width link plates manufactured to 5.3-5.6mm outer dimensions require precision grinding and riveting tolerances within 0.02mm. OEM procurement from Germany's Ruhr cluster concentrates on 11- to 13-speed compatibility for road racing and gravel segments, with specification lock-in from integrated drivetrain ecosystems driving volume concentration.
- Rust-Resistant Chains:Ceramic-based and trivalent chrome surface treatments replace REACH-restricted hexavalent chromium processes, extending service intervals in wet-climate municipal fleets. Copenhagen and Amsterdam cycling corridors generate sustained replacement demand for corrosion-protected architectures.
- Single-Speed Chains:Wider 8-9mm link plates with relaxed tolerances serve fixed-gear urban commuters and track cycling applications.
- Half-Link Chains:Adjustable pitch configurations enable precise chain tensioning on BMX and fixed-gear bicycles with horizontal dropouts.
- Heavy-Duty Chains:Reinforced plate thickness and hardened pin architectures address e-bike torque loads exceeding 85 Nm sustained outputs.
Multi-speed chains absorb the bulk of installed capacity; rust-resistant chains are expanding most quickly.
Material:
Raw material selection governs heat treatment response, surface coating adhesion, and unit economics across European forging operations facing energy-intensive smelter cost volatility.
- Carbon Steel:Cold-forging grade 40Cr or 45# steel delivers HRC 50-60 hardness through multi-stage austempering, dominating OEM volume procurement for standard-duty applications where cost optimization outweighs corrosion resistance.
- Nickel-Plated Steel:Electroless nickel deposition provides sacrificial corrosion protection without REACH-restricted hexavalent chromium, gaining specification share in Belgian and Dutch wet-climate commuter segments.
- Stainless Steel:304 and 316L grades eliminate surface coating requirements entirely for premium marine and all-weather touring applications.
- Titanium Alloy:Ti-6Al-4V offers 40% weight reduction with comparable fatigue strength for ultralight racing configurations.
- Zinc-Coated Steel:Hot-dip and electrogalvanized finishes provide entry-level corrosion protection for price-sensitive replacement markets.
Carbon steel commands the greatest forging tonnage; nickel-plated alternatives are climbing the fastest on regulatory compliance tailwinds.
Application:
Load profile severity and contamination exposure create divergent durability specifications across cycling disciplines, with torque demands from electrified propulsion systems rewriting engineering priorities.
- Mountain Bicycles:Reinforced outer plates with chamfered leading edges withstand high-impact, high-torque loading regimes on technical terrain. OEM specification from German and Austrian frame builders prioritizes fatigue life over weight minimization.
- Commuter Bicycles:Rust-resistant architectures with extended service intervals align with fleet operator procurement in Scandinavian municipal bike-share systems, where mean-time-between-failure metrics dominate supplier selection.
- Road Bicycles:Narrow-width, lightweight chains prioritize shifting precision and efficiency under human-power loading conditions.
- Touring Bicycles:Balance of durability and repairability favors wider, field-serviceable link configurations.
- BMX Bikes:Half-link compatibility and extreme impact resistance govern specification for stunt and racing disciplines.
Mountain bicycle applications anchor premium pricing power; commuter bicycle specifications are gaining share fastest on fleet electrification and urban infrastructure investment.
End User:
Purchasing consolidation and technical specification authority vary sharply across direct OEM procurement, fragmented aftermarket channels, and emerging fleet operator verticals.
- Bicycle Manufacturers:Integrated drivetrain ecosystems from Shimano and SRAM lock in proprietary chain interfaces at frame assembly stage, capturing specification-setting power with multi-year supply agreements.
- Rental Services:Municipal and private fleet operators in Denmark and the Netherlands negotiate direct procurement relationships with corrosion-resistant specifications and 15,000+ kilometer service interval guarantees.
- Repair Shops:Broad compatibility requirements favor KMC Chains and other aftermarket specialists serving fragmented replacement demand.
- Cycling Enthusiasts:Premium component upgrades drive demand for titanium and ceramic-coated performance tiers.
- Sports Clubs:Volume purchasing for team equipment concentrates on durability-under-load for training and competition fleets.
Bicycle manufacturers retain the greatest procurement volume concentration; rental services are expanding most quickly through direct supplier disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial cluster generates the bulk of precision-forged chain components, while consumption concentrates in Northern European cycling corridors and Asian OEM assembly networks. This production-consumption divide shapes logistics costs, specification authority, and regulatory compliance burdens across supplier portfolios.
Germany
The Ruhr industrial cluster anchors continental supply through cold-forging operations serving bicycle OEM assembly networks across Europe. REACH chemical substance restrictions in surface coatings accelerate R&D investment in chrome-free plating processes among precision component suppliers. Dortmund-based heat treatment facilities face technician scarcity as experienced metallurgists retire from multi-stage hardening operations.
Netherlands
Amsterdam's expanded cycling corridors generate sustained fleet replacement demand for rust-resistant chain architectures in high-utilization municipal bike-share systems. The EU Green Deal's transport decarbonization targets accelerate procurement of durable drivetrain components with verified lifecycle emissions data. Utrecht's regional transport authority consolidates maintenance contracts through direct supplier relationships, disintermediating traditional aftermarket distributors.
Denmark
Copenhagen's urban mobility planners extend dedicated cycling infrastructure, creating volume demand for corrosion-protected chain specifications in wet-climate commuter applications. Corporate Sustainability Reporting Directive requirements create procurement preference for suppliers with Scope 1-3 carbon footprint verification. Regional transport authorities negotiate multi-year supply agreements with specified mean-time-between-failure metrics for fleet operations.
Japan
JIS standards shape export quality benchmarks for manufacturers serving Asian OEM supply chains, imposing additional fatigue-testing and documentation burdens on precision component suppliers. METI industrial policy supports advanced materials R&D in titanium alloy and surface coating technologies. Osaka-based frame builders specify narrow-width precision chains for domestic road racing and gravel segments.
United States
The Consumer Product Safety Commission maintains recall authority over component failures, creating liability exposure that drives investment in fatigue-testing protocols among suppliers serving North American distributors. E-bike torque specifications exceeding traditional human-power loading force reinforced plate designs into aftermarket specification sheets. California's municipal fleet operators pilot extended-service-interval chain architectures for last-mile delivery networks.
Bicycle Chain Device Market Competitive Landscape
The competitive structure tilts toward integrated drivetrain ecosystems that lock in proprietary chain interfaces at frame assembly stage. Specification-setting power concentrates with multi-component suppliers controlling derailleur, cassette, and chain interoperability standards. Two strategic archetypes dominate: vertically integrated drivetrain architects and aftermarket compatibility specialists. Capacity expansion in precision forging lines and strategic partnerships for electronic shifting integration represent the dominant competitive moves.
Among drivetrain architects, Shimano and SRAM occupy positions that exemplify specification-lock-in strategies through integrated ecosystem control. KMC Chains anchors the aftermarket replacement channel with broad compatibility positioning across competing standards. These three represent the archetypal tension between proprietary interface capture and open-standard accessibility that defines supplier selection dynamics for frame builders and fleet operators.
| Leading Market Players |
|---|
| Shimano |
| SRAM |
| Campagnolo |
| KMC Chains |
| Wippermann |
| FSA |
| Taya Chain |
| SunRace |
| Izumi Chain Mfg |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's lifecycle emissions disclosure mandate gates qualified supply access and premium-tier pricing power, forcing suppliers to bear certification costs that stratify market participation between verified carbon-footprint providers and commodity-grade competitors.
Pricing Analysis
Service-interval guarantees anchor value-based pricing for fleet procurement contracts, with mean-time-between-failure metrics replacing unit-cost benchmarks in municipal bike-share negotiations. Price differentiation rests on corrosion-resistance certification tiers and heat-treatment hardness specifications, with HRC 55-60 precision commands from German OEMs. Cost compression in standard-grade carbon steel chains is intensifying because alloy input volatility from European smelter output erodes margin buffers. Fleet operators in Scandinavian cities demonstrate lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while independent repair shops in Southern Europe remain most price-sensitive.
Supply Chain Analysis
Reverse-logistics flows for end-of-life chain collection and material recovery remain underdeveloped, though REACH compliance is accelerating pilot programs for chrome-free plating waste reclamation in Germany's Ruhr cluster. Cold-forging capacity concentrates in Germany, Japan, and Taiwan, with precision heat-treatment infrastructure drawing from specialized metallurgical labor pools in Dortmund and Osaka. Raw material dependencies center on cold-forging grade alloy steel, nickel plating chemistries, and ceramic coating substrates. Single-source vulnerability runs through European smelter output for specialty steel grades. Distribution runs through integrated drivetrain OEMs for frame-assembly supply, direct procurement for fleet operators, and aftermarket distributors for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around specification-setting power, with REACH compliance costs and e-bike torque engineering requirements forcing weaker forging operations into acquisition or exit.
For Market Incumbents: Anticipate electronic shifting convergence by securing reinforced chain interface patents before wireless derailleur standards solidify. Deepen backward integration into heat-treatment facilities to capture scarce metallurgical technician capacity in Germany's Ruhr industrial cluster. Defend against specification lock-in erosion by broadening compatibility certification across competing drivetrain ecosystems.
For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the lowest friction entry path, bypassing distributor markups and OEM specification gatekeepers. Target last-mile delivery aggregators in wet-climate Northern European cities with corrosion-resistant architectures and guaranteed service-interval contracts. Lead with sustainability disclosure alignment to capture Corporate Sustainability Reporting Directive procurement preferences.
For Investors and Strategic Acquirers: Municipal fleet contract announcements with specified mean-time-between-failure metrics are the leading indicator that durability-under-load engineering is displacing racing-performance metrics as the value anchor. The five-to-ten-year viability window favors acquisition of mid-cap forging operations with verified Scope 1-3 carbon footprint data and existing REACH-compliant surface treatment lines. Monitor e-bike torque specification revisions from major frame builders as the inflection signal for reinforced plate architecture demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Treatment Facility Acquisition | Captures scarce metallurgical technician capacity in Germany's Ruhr cluster. |
| Chrome-Free Plating Process R&D | Secures REACH compliance ahead of hexavalent chromium elimination deadlines. |
| Fleet Operator Direct Contracting | Disintermediates aftermarket distributors in high-volume municipal procurement. |
| Electronic Shifting Interface Patenting | Establishes specification-setting power before wireless derailleur standards converge. |
| Carbon Footprint Verification Investment | Unlocks Corporate Sustainability Reporting Directive procurement preferences. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with drivetrain procurement managers at frame builders, fleet maintenance directors at municipal transport authorities, heat-treatment facility operators in Germany's Ruhr cluster, and aftermarket distribution channel heads. Secondary sources included ECHA REACH substance restriction databases, EU Green Deal transport decarbonization impact assessments, JIS standard documentation from METI, and bicycle OEM supply chain disclosures. Bottom-up forging capacity estimates and top-down consumption triangulation validated volume figures.
Data-stream reconciliation across production capacity surveys, import-export trade flows, and end-use procurement patterns shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include speed compatibility tiers, surface treatment material categories, application load profiles, and end-user purchasing consolidation levels. CAGRs were derived from trend extrapolation of fleet electrification penetration and urban infrastructure investment pipelines, with e-bike torque specification trajectories and REACH compliance cost curves as industry-specific forecast inputs.
The model holds under sustained EU Green Deal implementation and stable alloy steel input costs; deviation in smelter energy pricing or accelerated electronic shifting standardization would shift competitive positioning. Forecasts reflect documented assumptions on technician pipeline recovery and fleet procurement consolidation velocity. Practitioners should monitor municipal contract award announcements and frame-builder specification sheet revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.