
 Sideloaders Market | 2026-2036
Sideloaders Market Size, Share, and Industry Trends Forecast 2026-2036
Sideloaders Market Analytics
Dealer networks and direct-to-fleet channels is reconfiguring how sideloaders reach end-users across North America and Europe. The Raymond Corporation leverages its captive dealer network to sustain aftermarket parts revenue in warehousing corridors. Combilift competes through product specialization in multi-directional handling, while BULMOR industries GmbH anchors its position in heavy-lift diesel configurations for steel and timber yards.
Sideloaders are lateral-load material handling vehicles engineered with multi-directional steering and extended load platforms, typically rated from 2 to 5 tons capacity, designed to transport long or bulky items through narrow aisles without turning radius penalties. Electric sideloaders now dominate new order books as battery energy density improvements extend shift durations beyond eight hours. The 3-ton and 4-ton capacity bands capture the bulk of margin pools, while telematics integration represents the fastest-growing technology attachment as fleet managers demand real-time utilization data.
The EPA enforces Tier 4 Final emissions standards on diesel sideloaders sold in the United States, pushing rental fleets toward electric substitutions. The EU Green Deal and REACH frameworks constrain hydraulic fluid chemistry and battery disposal pathways across European manufacturing and logistics operations. Stakeholders must monitor how OSHA's evolving powered industrial truck standards and the EU AI Act's risk classifications reshape automation roadmaps for autonomous sideloader deployment.
Market Dynamics
Battery energy density improvements and Tier 4 Final emissions enforcement are compressing diesel sideloader replacement cycles while electric configurations capture procurement preference in warehousing and timber yard operations.
Growth Catalysts
- EU Green Deal emissions mandates:Warehouse operators in Germany are electrifying fleets to meet binding carbon reduction targets, accelerating electric sideloader procurement through 2035.
- E-commerce fulfillment center expansion:China's manufacturing corridors are driving heavy-capacity unit demand as logistics operators optimize narrow-aisle storage density for bulky goods.
- Telematics integration:Fleet managers are mandating real-time utilization tracking, attaching IoT sensors to sideloader platforms to optimize shift scheduling and maintenance intervals.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing clusters in limited geographies create input cost volatility and procurement risk for electric sideloader manufacturers.
- Tier 4 Final compliance costs:EPA diesel emissions standards impose exhaust after-treatment systems that inflate diesel unit pricing and compress margins for rental fleet operators.
- Autonomous navigation technical limitations:Narrow-aisle maneuvering algorithms struggle with dynamic obstacle detection in steel and timber yards, delaying full automation deployment.
Strategic Opportunities
- Underpenetrated Indian logistics infrastructure:Cold chain expansion and organized retail growth create first-mover positioning for electric sideloader suppliers in temperature-controlled warehousing.
- EU AI Act regulatory tailwind:Risk classification frameworks for autonomous industrial vehicles are clarifying liability pathways, enabling pilot deployments of self-navigating sideloaders in German distribution hubs.
- Battery-as-a-service channel innovation:Leasing models for powertrains separate asset ownership from energy infrastructure, reducing capex barriers for mid-size timber processors.
Industry Challenges
- Certification timeline compression:CE marking and OSHA powered industrial truck standard updates require parallel compliance documentation, straining engineering resources.
- Legacy warehouse management system integration:Telematics data protocols from newer sideloader fleets conflict with established ERP architectures in mature logistics operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sideloaders Market |
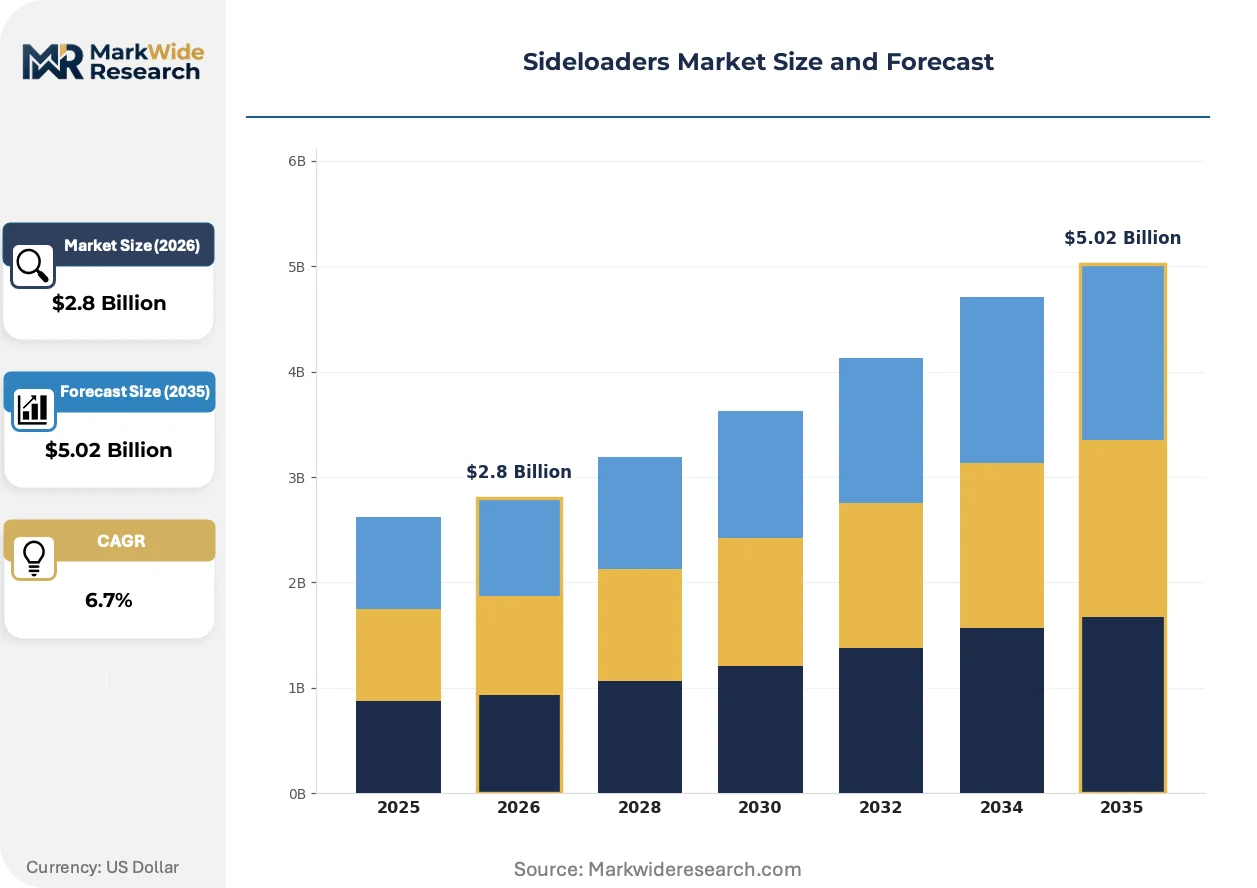
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Sideloaders, Diesel Sideloaders, Hybrid Sideloaders, Manual Sideloaders End User: Warehousing, Manufacturing, Retail, Logistics Capacity: 2 Ton, 3 Ton, 4 Ton, 5 Ton Technology: Telematics, Automation, GPS Tracking, Load Sensing |
| Companies Covered | The Raymond Corporation, BULMOR industries GmbH, Godrej Material Handling, Combilift, Italcarrelli, Labrie Group, Autocar, LLC, Mack Trucks, Dennis Eagle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sideloaders Market Evolving Landscape
Lithium-iron-phosphate battery chemistry and autonomous navigation stacks are restructuring competitive advantage in material handling equipment procurement, with warranty terms and software subscription revenue displacing traditional hardware margins.
High-voltage lithium-iron-phosphate battery packs are extending electric sideloader shift durations past eight hours without opportunity charging. Food and pharmaceutical cold storage operators in the Netherlands and Denmark are specifying these configurations for temperature-controlled environments. Conventional lead-acid battery maintenance contracts and mid-shift battery swap infrastructure are rendering obsolete across premium fleet segments.
REACH framework constraints on hydraulic fluid chemistry are forcing reformulation of mineral oil-based systems used in sideloader mast assemblies. Equipment lessors in France and Belgium face extended compliance documentation requirements for cross-border fleet deployment. Diesel-powered units in timber and steel applications are absorbing the highest compliance costs as biodegradable alternatives struggle with high-pressure performance specifications.
Outcome-based fleet availability contracts are replacing unit purchase models among third-party logistics operators. Sideloader suppliers in the United Kingdom are unbundling maintenance from capital leases, charging per pallet-move rates instead. This restructuring concentrates most visibly in grocery retail distribution networks where seasonal volume spikes demand flexible capacity scaling without asset ownership risk.
Sideloaders Market Segmentation
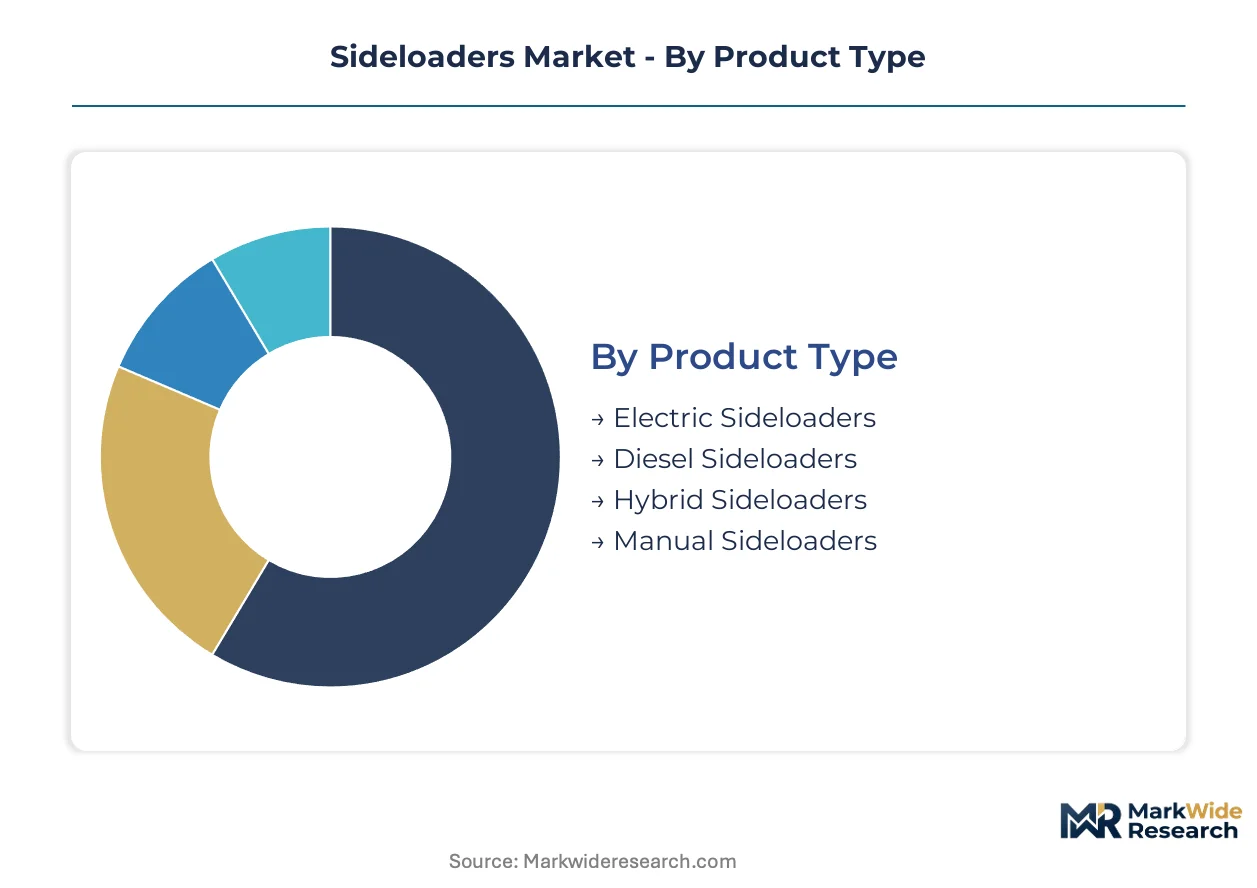
Sideloader procurement patterns diverge sharply across powertrain configurations and operational environments. Fleet replacement cycles and technology attachment rates vary by segment, creating distinct margin profiles for equipment suppliers and service providers.
Product Type:
Electric configurations turn over fastest as battery chemistry improvements accelerate obsolescence, while diesel units linger longest in heavy-lift timber and steel yards where electrification remains technically constrained.
- Electric Sideloaders:Lithium-iron-phosphate battery packs now deliver shift durations exceeding eight hours without opportunity charging. Warehouse operators in Germany and the Netherlands are specifying these units to satisfy EU Green Deal emissions mandates while eliminating exhaust contamination in food and pharmaceutical cold storage.
- Diesel Sideloaders:Tier 4 Final after-treatment systems inflate unit costs and compress rental fleet margins, yet remain essential for outdoor timber yards and steel processing facilities where battery energy density cannot match sustained heavy-lift duty cycles. EPA enforcement maintains pressure on US fleet composition.
- Hybrid Sideloaders:Dual-powertrain architectures serve transitional applications in mixed indoor-outdoor logistics corridors.
- Manual Sideloaders:Human-powered units persist in small-scale retail backrooms and maintenance workshops with minimal throughput requirements.
Diesel dominates installed base. Electric is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive warehousing automation from price-sensitive retail procurement, with manufacturing and logistics occupying intermediate positions on the technology adoption curve.
- Warehousing:Third-party logistics operators in China's manufacturing corridors are driving heavy-capacity unit procurement to optimize narrow-aisle storage density for e-commerce fulfillment. Telematics integration is now standard specification in premium fleet segments.
- Manufacturing:Steel and timber processors absorb the highest compliance costs as REACH framework constraints force hydraulic fluid reformulation. Biodegradable alternatives struggle with high-pressure mast assembly specifications.
- Retail:Grocery distribution networks in the United Kingdom are unbundling maintenance from capital leases, charging per pallet-move rates instead of unit ownership.
- Logistics:Cold chain expansion in India creates first-mover positioning for electric sideloader suppliers in temperature-controlled warehousing.
Warehousing commands the largest equipment installed base. Logistics is climbing the fastest.
Capacity:
Volume concentration pools in mid-range bands where application versatility intersects with fleet standardization economics, while specialty ratings serve narrow operational niches.
- 3 Ton:The most versatile rating across warehousing and light manufacturing applications, capturing procurement preference where single-fleet flexibility must accommodate variable load profiles. Margin pools concentrate here due to production scale and parts commonality.
- 4 Ton:Heavy-duty warehousing and timber yard operations specify this band for sustained lifting of packaged lumber and structural steel. Battery configurations in this class are gaining share fastest as energy density improvements extend shift durations.
- 2 Ton:Compact retail and light logistics applications favor this rating for maneuverability in constrained spaces.
- 5 Ton:Specialized steel processing and heavy timber applications require this capacity for raw material handling.
3 Ton anchors fleet standardization. 4 Ton is gaining share fastest.
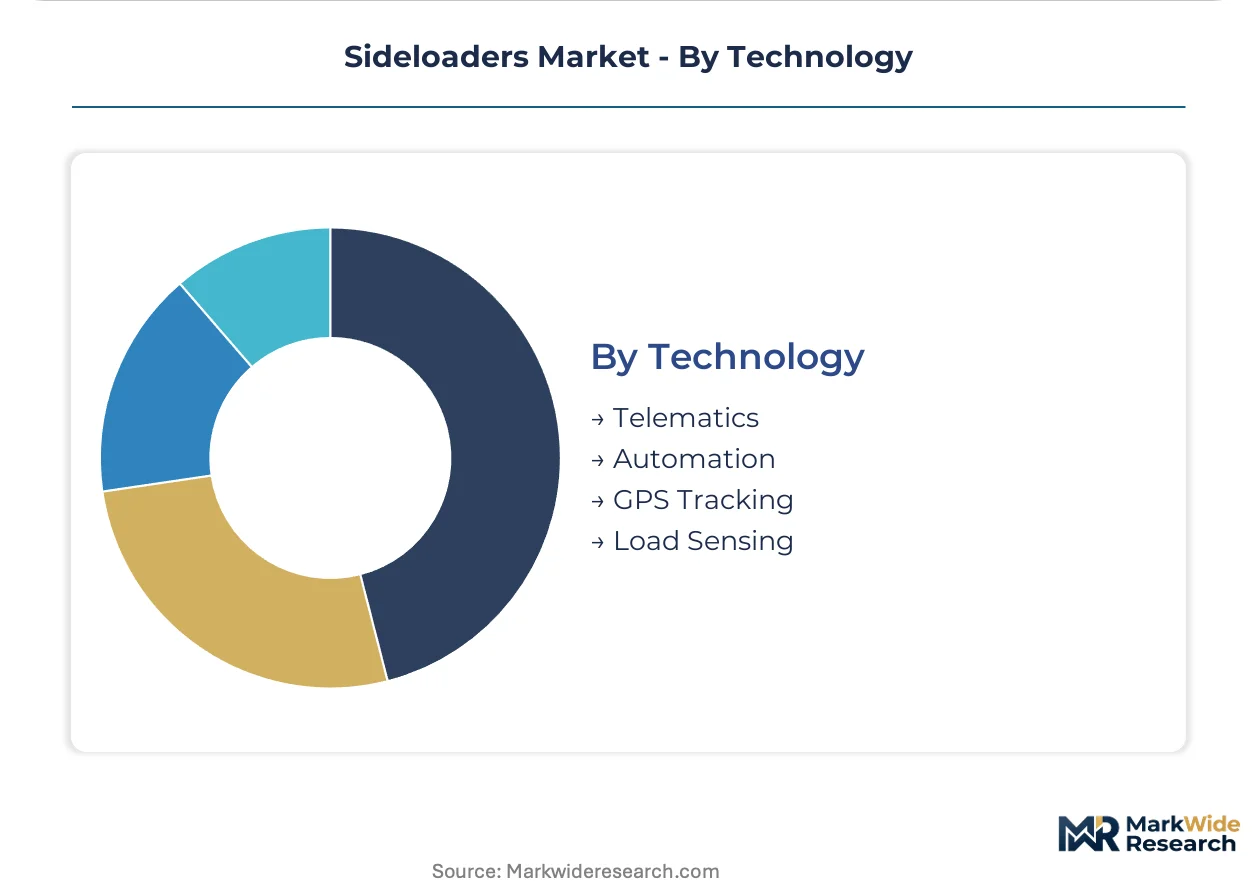
Technology:
Customer type segmentation separates fleet-scale telematics mandates from single-unit GPS tracking, with automation representing the steepest adoption trajectory despite technical limitations in dynamic obstacle environments.
- Telematics:IoT sensor platforms delivering real-time utilization data are now mandatory specification among third-party logistics operators optimizing shift scheduling and predictive maintenance intervals. Subscription revenue is displacing traditional hardware margins.
- Automation:EU AI Act risk classification frameworks are clarifying liability pathways for autonomous industrial vehicles, enabling pilot deployments of self-navigating sideloaders in German distribution hubs. Narrow-aisle maneuvering algorithms remain constrained by dynamic obstacle detection in steel and timber yards.
- GPS Tracking:Basic location monitoring serves rental fleet operators managing dispersed asset deployment across multi-site contracts.
- Load Sensing:Weight verification systems integrate with warehouse management software for inventory accuracy in high-velocity fulfillment centers.
Telematics dominates technology attachment rates. Automation represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German warehouse operators command pricing premiums for EU Green Deal-compliant electric configurations, while Indian logistics corridors absorb cost-sensitive diesel units as cold chain infrastructure scales.
United States
Third-party logistics operators in the Chicago-Milwaukee warehousing corridor are electrifying sideloader fleets to satisfy corporate ESG mandates. OSHA powered industrial truck standards are tightening inspection protocols for lithium-ion battery installations. The EPA's Tier 4 Final enforcement is compressing diesel replacement cycles in California's Central Valley timber processing clusters.
Germany
Distribution hubs in the Ruhr industrial belt are procuring heavy-capacity electric sideloaders with integrated telematics for narrow-aisle optimization. The EU AI Act's risk classification framework is enabling pilot autonomous deployments in Bavarian fulfillment centers. KBA certification timelines are accelerating for battery-as-a-service configurations among mid-size timber processors.
China
E-commerce fulfillment centers in the Yangtze River Delta are driving 4-ton capacity procurement to maximize storage density for bulky goods. SAMR quality standards are tightening on imported battery management systems. Manufacturing clusters in Guangdong province are absorbing the highest telematics attachment rates for real-time fleet optimization.
India
Cold chain expansion in Maharashtra and Gujarat is creating first-mover positioning for electric sideloader suppliers in temperature-controlled warehousing. BIS certification requirements are extending lead times for imported battery packs. Organized retail growth in the Delhi-NCR corridor is driving demand for 3-ton standardization across fragmented logistics networks.
Netherlands
Food and pharmaceutical cold storage operators in Rotterdam's port logistics zone are specifying lithium-iron-phosphate configurations to eliminate exhaust contamination. REACH framework constraints are forcing hydraulic fluid reformulation in mast assemblies. Equipment lessors face extended compliance documentation for cross-border fleet deployment into Belgium.
Sideloaders Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on battery and telematics modules. The vendor base organizes around three strategic archetypes: captive dealer networks sustaining aftermarket revenue, multi-directional handling specialists, and heavy-lift diesel configurators for timber and steel yards. M&A activity concentrates on telematics software assets, while geographic expansion targets underpenetrated Indian cold chain corridors.
Among North American platform integrators, The Raymond Corporation occupies a position within captive distribution architectures. European fabricators include Germany-based BULMOR industries GmbH and Ireland-registered Combilift, both exemplifying specialization archetypes—heavy-lift configurations and multi-directional engineering respectively.
| Leading Market Players |
|---|
| The Raymond Corporation |
| BULMOR industries GmbH |
| Godrej Material Handling |
| Combilift |
| Italcarrelli |
| Labrie Group |
| Autocar, LLC |
| Mack Trucks |
| Dennis Eagle |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container handling costs are transmitting upward pressure through sideloader supply chains, concentrating pricing power among battery pack integrators while forcing downstream differentiation between configured-to-order and standard fleet procurement.
Pricing Analysis
The customization-premium spread separates standard 3-ton electric configurations from heavy-lift diesel units with Tier 4 Final after-treatment systems. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and telematics bundling, with EU Green Deal compliance commanding material premiums in German warehousing corridors. Cost compression in mid-range electric segments is intensifying because cathode material processing clusters concentrate pricing volatility. Third-party logistics operators exhibit highest price sensitivity, while timber yard operators absorbing heavy-lift diesel units show lowest elasticity due to technical constraints on electrification.
Supply Chain Analysis
Contract manufacturing concentration for lithium-iron-phosphate battery packs centers on foundry partnerships in China, South Korea, and Japan, with cathode material processing drawing from nickel and cobalt supply chains anchored in Indonesia and the Democratic Republic of Congo. Sideloader mast assemblies rest on high-pressure hydraulic systems whose mineral oil formulations face REACH-driven reformulation costs. Single-source vulnerability concentrates in battery management system semiconductor supply. Distribution runs through captive dealer networks for aftermarket parts revenue, with direct-to-fleet channels gaining share in premium warehousing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated third-party logistics operators running multi-site fleet contracts, fragmenting price-setting autonomy among equipment suppliers as volume concentration accelerates in Chinese e-commerce fulfillment and German distribution hubs.
For Market Incumbents: Build aftermarket service moats by unbundling maintenance from capital leases and charging per pallet-move rates, mirroring outcome-based contracts emerging in UK grocery retail networks. Deepen backward integration into battery pack assembly to offset cathode material volatility. Prioritize KBA certification investment for battery-as-a-service configurations to defend against emerging platform integrators targeting mid-size timber processors with reduced capex barriers.
For New Entrants and Emerging Players: Pursue white-space positioning in Indian cold chain expansion across Maharashtra and Gujarat temperature-controlled warehousing, where BIS certification requirements extend lead times for incumbents but create first-mover windows for agile suppliers. Target 3-ton standardization opportunities in Delhi-NCR organized retail corridors. Anchor go-to-market strategy through telematics-native fleet optimization platforms rather than hardware-centric sales motions.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with sideloader divisions generating sub-scale aftermarket revenue against captive dealer network competitors. Long-term viability hinges on software subscription revenue displacement of hardware margins and battery-as-a-service channel innovation. Monitor EU AI Act autonomous vehicle risk classification clarifications as inflection signal for automation deployment capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Channel Launch | Separates asset ownership from energy infrastructure, reducing capex barriers for mid-size timber processors in Germany. |
| Telematics Platform Integration | Attaches IoT sensors to sideloader fleets, enabling per pallet-move pricing models in UK grocery distribution. |
| Backward Integration into Battery Assembly | Captures margin pools from lithium-iron-phosphate pack production, offsetting cathode material cost volatility. |
| EU AI Act Compliance Pathway | Clarifies liability frameworks for autonomous navigation, enabling pilot deployments in Bavarian fulfillment centers. |
| Indian Cold Chain Geographic Expansion | Positions electric configurations in Maharashtra temperature-controlled warehousing ahead of organized retail scaling. |
Research Methodology
A spread of perspectives from fleet maintenance directors, OEM procurement teams, aftermarket service heads, and plant engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs records, SEC filings from listed material handling equipment suppliers, and trade data from manufacturing corridors. Bottom-up unit economics triangulated against top-down market sizing across powertrain configurations and capacity bands.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with segmentation modeling spanning powertrain type, end-use environment, capacity rating, and technology attachment level. CAGRs derived from replacement cycle compression in diesel fleets and electrification penetration curves in warehousing applications. Battery energy density improvement trajectories and telematics adoption rates served as industry-specific forecast inputs.
Sensitivities concentrate around lithium-ion battery supply concentration, Tier 4 Final compliance cost inflation, and autonomous navigation technical limitations in dynamic obstacle environments. Forecasts reflect documented assumptions on fleet electrification timelines and regulatory enforcement intensity. Quarterly review of EU AI Act implementation progress and Indian BIS certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Grille Guard Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Headlight Market
Vehicle Components
RV Battery Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
EV Connectors Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Italy Automotive Composites Market