
 United States Ceramic Ball Bearings Market | 2026-2036
United States Ceramic Ball Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ceramic Ball Bearings Market Intelligence
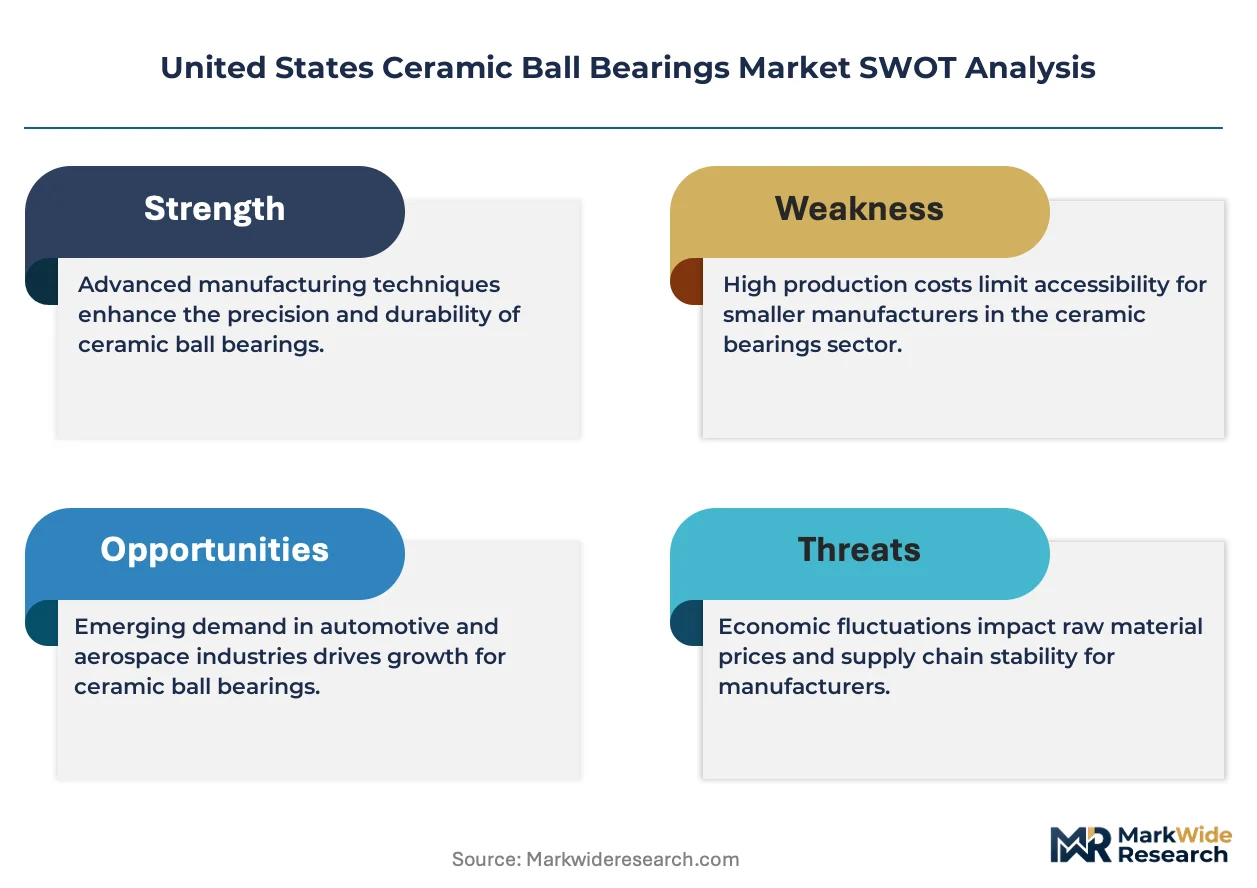
AS9100 certification is reorganizing competitive access for aerospace-grade suppliers in the United States ceramic ball bearings space. SKF USA Inc. leverages its vertically integrated ceramic powder-to-bearing production network across multiple states. Timken Company anchors its position through intensive R&D spending on silicon nitride formulations for extreme-temperature environments. CoorsTek, Inc. specializes in technical ceramic substrates that feed into precision bearing assemblies for medical and semiconductor equipment.
Ceramic ball bearings are rolling-element bearings manufactured from engineering ceramics such as silicon nitride, zirconia, or alumina, typically featuring density below 40% of equivalent steel bearings and operating temperatures exceeding 1,000 degrees Fahrenheit in full-ceramic configurations. Their primary purpose is to eliminate electrical conductivity, reduce centrifugal loading, and extend service life in corrosive or vacuum environments where steel bearings degrade prematurely. Hybrid ceramic bearings dominate current volume shipments across aerospace and automotive applications, while full-ceramic designs command premium positioning in medical devices and semiconductor wafer handling where magnetic interference and chemical inertness prove critical. Standard-size bearings maintain mature margin pools through OEM supply agreements, though custom and miniature segments attract faster growth from precision robotics and miniature motor manufacturers seeking application-specific geometries.
FAA airworthiness directives and NHTSA safety standards shape material qualification timelines and testing protocols for bearings entering transportation applications. EPA hazardous substance regulations govern the disposal and recycling of ceramic bearing waste streams, particularly those containing stabilized zirconia compounds. Stakeholders must monitor evolving FDA device classification pathways as ceramic bearings penetrate surgical robot and imaging equipment supply chains, since reclassification could trigger premarket submission requirements that reshape vendor qualification timelines.
Market Dynamics
NHTSA Corporate Average Fuel Economy standards are compressing automaker timelines for component lightweighting, forcing accelerated validation of silicon nitride bearings in powertrain and chassis systems across Detroit and Tennessee manufacturing corridors.
Growth Catalysts
- Fuel Economy Mandates:NHTSA CAFE standards compel automakers to substitute ceramic bearings for steel units in transmissions and auxiliary systems, cutting rotating mass by up to 60 percent in hybrid drivetrain applications.
- Aerospace Procurement Expansion:FAA airworthiness directives for next-generation turbine designs are expanding ceramic bearing specifications in flight-control actuators and engine accessory gearboxes across Boeing and Gulfstream supply chains.
- Silicon Nitride Powder Advances:Gas-pressure sintering improvements at Tennessee and Colorado ceramic foundries are reducing fracture toughness variability, enabling thinner raceway designs that extend fatigue life in high-speed spindle applications.
Market Restraints
- Yttria-Stabilized Zirconia Cost Volatility:Rare earth oxide supply concentration in Mountain Pass, California and Chinese processing facilities generates 18-24 month price swings that destabilize full-ceramic bearing quoting for medical device OEMs.
- AS9100 Certification Bottlenecks:FAA-recognized third-party auditors maintain 14-18 month backlogs for aerospace-grade ceramic bearing qualifications, freezing new supplier entry into Gulfstream and Lockheed Martin approved vendor lists.
- Hybrid Bearing Substitution:Steel-race ceramic-ball configurations deliver 80 percent of full-ceramic performance at 40 percent lower unit cost, capturing volume in automotive climate-control compressors where electrical insulation requirements remain secondary.
Strategic Opportunities
- Surgical Robotics Penetration:FDA 510(k) pathway acceleration for minimally invasive instruments is opening ceramic bearing specifications in da Vinci-compatible articulating wrists, where magnetic transparency enables real-time MRI guidance.
- Semiconductor Wafer Handling:Extreme ultraviolet lithography tool builders in Oregon and Arizona are specifying full-ceramic vacuum bearings to eliminate particle generation from steel lubricants in cleanroom environments.
- IRA Clean Manufacturing Credits:Inflation Reduction Act Section 45X advanced manufacturing tax credits are offsetting capital equipment costs for domestic silicon nitride powder synthesis, reshoring ceramic feedstock production from Asian suppliers.
Industry Challenges
- Ceramic Metallurgist Talent Scarcity:Universities in Ohio and Pennsylvania graduated fewer than 120 specialized ceramic engineers in 2023, constraining R&D expansion at precision bearing houses seeking to develop next-generation thermal barrier coatings.
- Legacy CNC Retrofit Complexity:Grinding machine fleets across Michigan and Illinois require $2-4 million per line upgrades to achieve the 0.1-micron sphericity tolerances demanded by miniature ceramic bearing geometries for drone motor applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ceramic Ball Bearings Market |
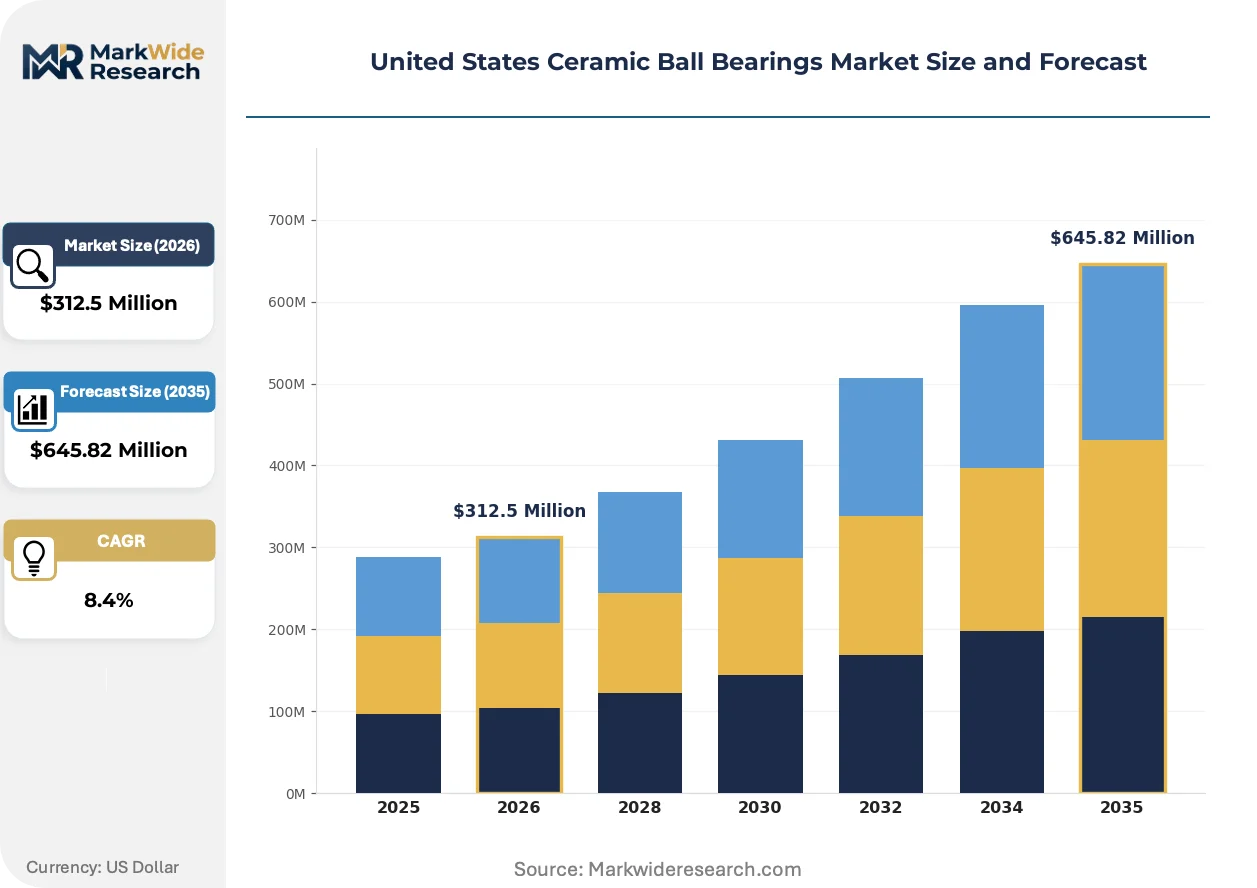
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Full Ceramic, Stainless Steel, Plastic Application: Aerospace, Automotive, Medical Devices, Industrial Machinery End User: Manufacturers, OEMs, Distributors, Aftermarket Suppliers Size: Miniature, Standard, Custom, Large |
| Companies Covered | SKF USA Inc., Timken Company, Schaeffler Technologies AG & Co. KG, NTN Corporation, NSK Americas, JTEKT North America Corporation, MinebeaMitsumi Inc., CoorsTek, Inc., Boca Bearing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ceramic Ball Bearings Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on vehicle efficiency are fragmenting traditional bearing procurement patterns, creating parallel development tracks for aerospace-grade precision and automotive cost-optimized volumes.
Silicon nitride bearing-grade powder production is bifurcating between aerospace-qualified lots requiring full traceability documentation and automotive commodity streams optimized for throughput. Gas-pressure sintering furnace operators in Tennessee and Colorado are installing separate production lines to serve these divergent specification tiers. The resulting capacity segmentation is compressing margin pools for mid-grade ceramic bearings that lack either premium certification or commodity scale.
NHTSA safety standards for autonomous vehicle steering systems are mandating redundant bearing architectures with documented failure-mode probabilities. Tier-1 suppliers in the Great Lakes automotive belt are responding by dual-sourcing ceramic and hybrid configurations from separate qualified vendors. The regulatory friction is extending validation timelines by 8-12 months for new bearing geometries entering electric power steering platforms.
Medical device OEMs in Minnesota and Massachusetts are consolidating procurement around single-source ceramic bearing partnerships with embedded quality engineering support. Long-term supply agreements now bundle bearing supply with application-specific lubricant selection and sterilization protocol validation. The service unbundling is most visible in surgical robot joint actuators, where OEMs trade unit price premiums for reduced FDA submission risk.
United States Ceramic Ball Bearings Market Segmentation
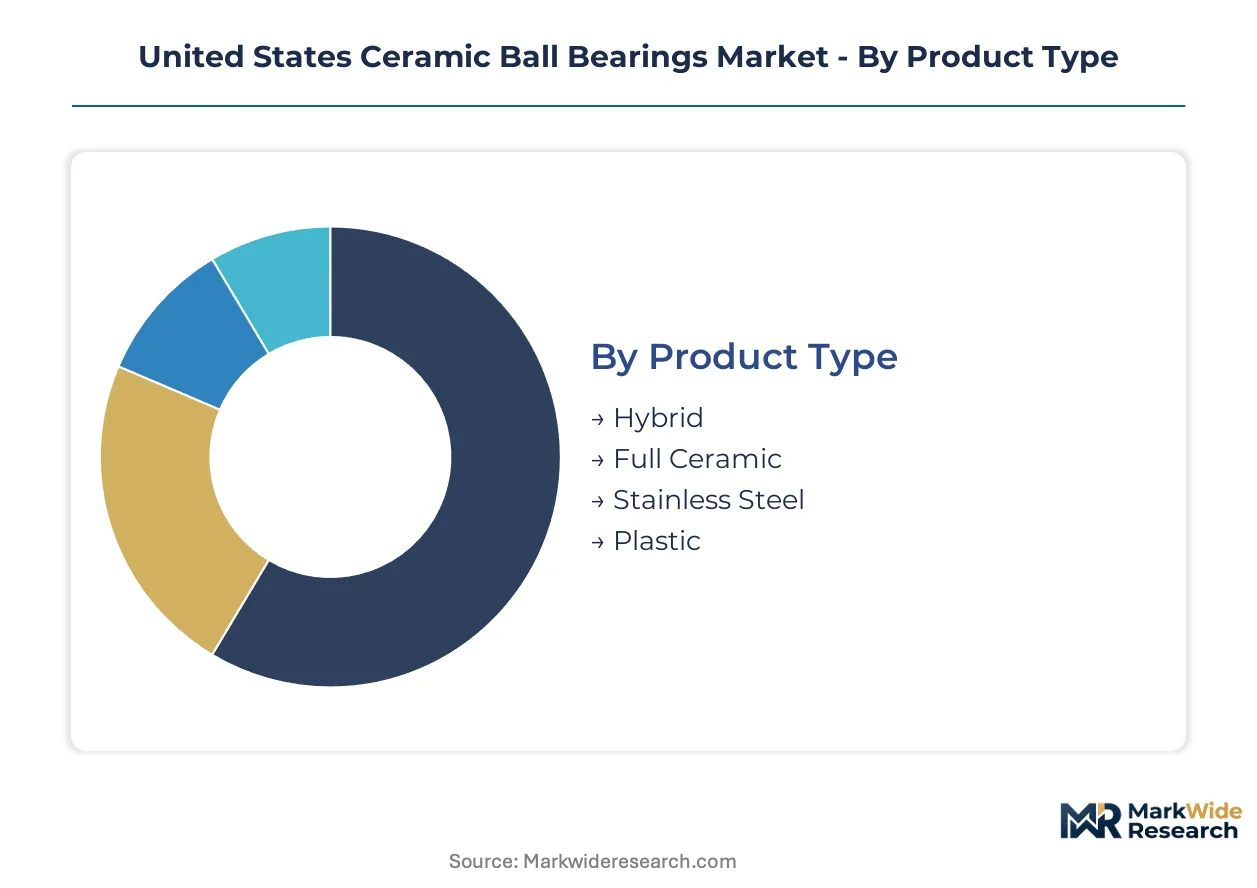
Ceramic ball bearings flow through distinct commercial channels depending on specification tier and end-use criticality. Aerospace-grade full-ceramic units move through AS9100-certified OEM direct contracts, while automotive hybrid configurations reach Detroit and Tennessee assembly plants via Tier-1 distributor networks.
Product Type:
Channel mix varies sharply by ceramic content: hybrid bearings dominate automotive aftermarket and industrial distributor shelves, while full-ceramic units bypass distribution entirely through medical device OEM captive supply agreements.
- Hybrid:Steel raceways paired with silicon nitride balls deliver 60 percent weight reduction versus all-steel bearings at 40 percent lower cost than full-ceramic alternatives. Demand concentrates in Michigan and Tennessee powertrain manufacturing, where NHTSA CAFE standards accelerate validation timelines for transmission and auxiliary system applications.
- Full Ceramic:Silicon nitride or zirconia construction eliminates electrical conductivity and magnetic interference for MRI-compatible surgical robots and semiconductor wafer handling equipment. Minnesota and Massachusetts medical device OEMs specify these through single-source partnerships bundling bearing supply with sterilization protocol validation.
- Stainless Steel:Corrosion-resistant steel bearings serve food processing and marine applications where ceramic cost premiums cannot be justified.
- Plastic:Polymer-based bearings address low-load, chemically aggressive environments in laboratory and analytical instrumentation.
By volume, Hybrid leads. By growth pace, Full Ceramic is ahead.
Application:
Cost tier segmentation separates aerospace and medical premium specifications from automotive and industrial commodity procurement patterns.
- Aerospace:FAA airworthiness directives mandate ceramic bearing specifications for next-generation turbine designs and flight-control actuators across Boeing and Gulfstream supply chains. AS9100 certification bottlenecks create 14-18 month vendor qualification backlogs, freezing new supplier entry.
- Automotive:NHTSA Corporate Average Fuel Economy standards compress automaker timelines for component lightweighting, forcing accelerated silicon nitride validation in powertrain and chassis systems. Detroit and Tennessee manufacturing corridors absorb the bulk of hybrid bearing procurement.
- Medical Devices:FDA 510(k) pathway acceleration for minimally invasive instruments opens ceramic bearing specifications in da Vinci-compatible articulating wrists.
- Industrial Machinery:Standard-size bearings maintain mature margin pools through long-term OEM supply agreements for machine tool spindles and robotics.
Aerospace commands the highest unit margins. Medical Devices exhibits the steepest expansion trajectory.
End User:
Customer type determines contract structure and pricing leverage, with manufacturers and OEMs extracting volume discounts unavailable to fragmented aftermarket channels.
- Manufacturers:Precision bearing houses in Ohio and Pennsylvania supply finished ceramic assemblies to downstream equipment builders under multi-year blanket orders.
- OEMs:Boeing, Gulfstream, and Lockheed Martin maintain approved vendor lists with embedded quality engineering requirements.
- Distributors:Industrial distributors stock standard hybrid configurations for maintenance-repair-operations procurement in the Great Lakes automotive belt.
- Aftermarket Suppliers:Independent repair channels serve legacy equipment with cross-referenced steel and ceramic alternatives.
OEMs dominate absolute revenue contribution. Distributors are gaining share fastest through e-procurement platform expansion.
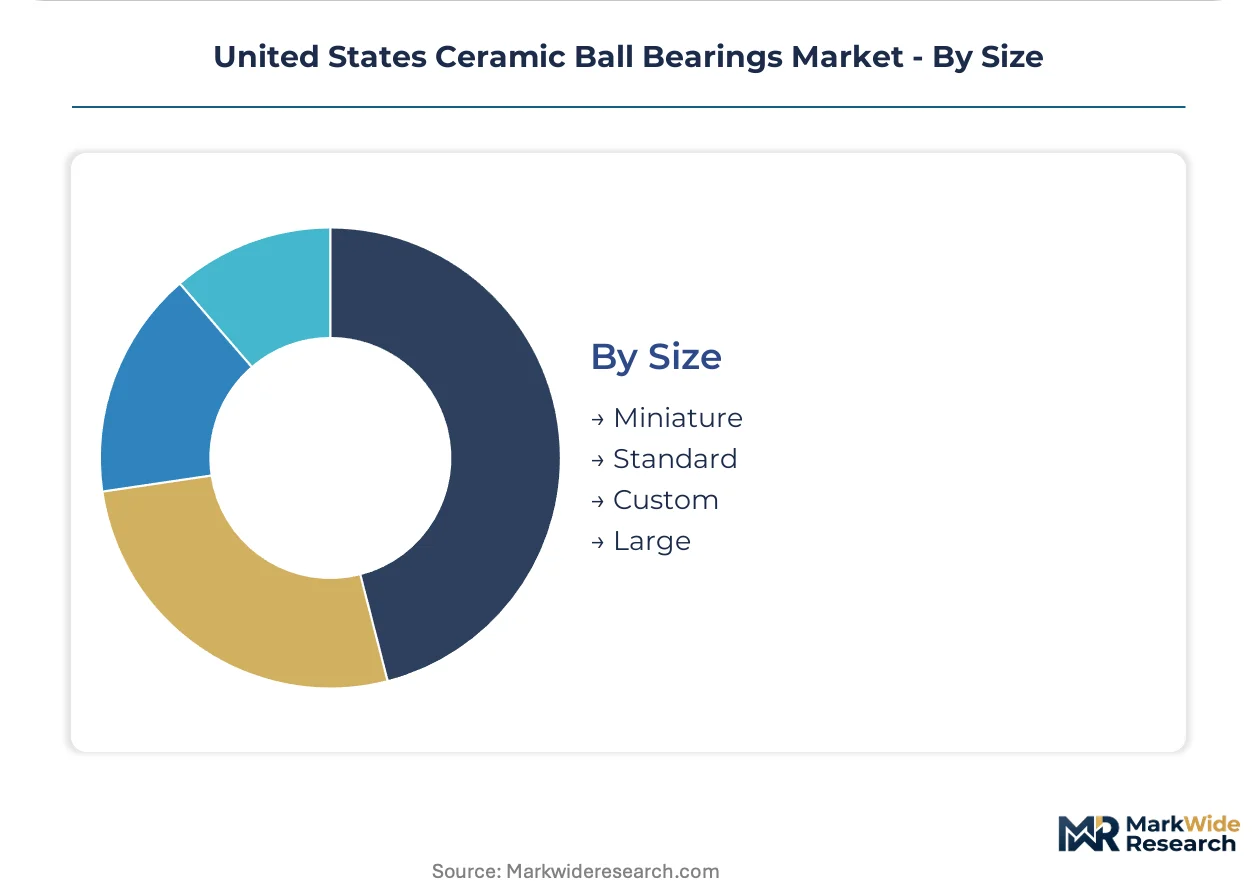
Size:
Volume concentration sits with standard geometries, while margin expansion concentrates in miniature and custom segments serving precision robotics and surgical instrumentation.
- Miniature:Sub-10mm bearings enable drone motor and surgical robot joint applications. Michigan and Illinois grinding operations require $2-4 million per line upgrades to achieve 0.1-micron sphericity tolerances.
- Standard:Mature geometries serve established automotive and industrial machinery installations through high-volume production runs.
- Custom:Application-specific geometries attract premium positioning from precision robotics manufacturers seeking proprietary designs.
- Large:Specialized wind turbine and heavy industrial applications represent niche procurement with extended lead times.
Standard sizes anchor volume shipments. Miniature bearings command the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration clusters around aerospace primes in Washington and Georgia, automotive powertrain engineers in Michigan and Tennessee, and medical device procurement teams in Minnesota and Massachusetts. These three archetypes drive divergent specification requirements across domestic manufacturing corridors.
California
Precision manufacturing demand concentrates in Silicon Valley semiconductor equipment and Southern California aerospace subcontracting. EPA hazardous substance regulations govern ceramic waste disposal from zirconia-bearing production in Mountain Pass rare earth processing facilities. San Diego and Los Angeles house flight-control actuator specialists supplying Gulfstream and Lockheed Martin approved vendor lists.
Michigan
Detroit's powertrain engineering centers validate silicon nitride bearings for electric vehicle transmissions and hybrid drivetrains. NHTSA Corporate Average Fuel Economy standards compress automaker timelines for component lightweighting across the state's manufacturing belt. Grand Rapids grinding operations require multimillion-dollar CNC upgrades to achieve miniature bearing sphericity tolerances for drone motor applications.
Tennessee
Automotive assembly plants in Nashville and Chattanooga absorb hybrid ceramic bearing volumes for climate-control compressors and auxiliary systems. IRA Section 45X clean manufacturing credits offset capital equipment costs for domestic silicon nitride powder synthesis. Oak Ridge National Laboratory partnerships anchor advanced ceramic foundry development for gas-pressure sintering improvements.
Minnesota
Medical device OEMs in Minneapolis-St. Paul consolidate procurement around single-source ceramic bearing partnerships with embedded quality engineering support. FDA 510(k) pathway acceleration for minimally invasive instruments opens specifications in surgical robot joint actuators. The Twin Cities corridor bundles bearing supply with sterilization protocol validation for da Vinci-compatible articulating wrists.
Ohio
Industrial machinery and precision bearing houses in Cleveland and Cincinnati supply finished ceramic assemblies under multi-year blanket orders. Universities in the state graduated fewer than 120 specialized ceramic engineers in 2023, constraining R&D expansion. The region's manufacturing base feeds machine tool spindle and robotics applications through established OEM supply agreements.
United States Ceramic Ball Bearings Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive ceramic powder capabilities alongside specialized technical ceramic houses. Market structure exhibits tiered consolidation, with aerospace-grade suppliers facing AS9100 certification bottlenecks that freeze new entry while automotive hybrid configurations flow through established Tier-1 channels. Three archetypes dominate: vertically integrated powder-to-bearing producers, R&D-intensive formulation specialists, and technical ceramic substrate suppliers feeding precision assemblies. Competitive moves center on dual-sourcing qualification strategies and long-term supply agreements bundling engineering support.
Within the diversified industrial tier, SKF USA Inc. and Timken Company exemplify scale-driven positions, while CoorsTek, Inc. occupies a specialized niche. SKF USA Inc. leverages multi-state production networks. Timken Company anchors its market presence through intensive development programs targeting extreme-temperature environments. CoorsTek, Inc. concentrates on technical ceramic substrates that feed into precision bearing assemblies for medical and semiconductor equipment applications.
| Leading Market Players |
|---|
| SKF USA Inc. |
| Timken Company |
| Schaeffler Technologies AG & Co. KG |
| NTN Corporation |
| NSK Americas |
| JTEKT North America Corporation |
| MinebeaMitsumi Inc. |
| CoorsTek, Inc. |
| Boca Bearing Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with rare earth oxide indexation lock in silicon nitride powder supply for aerospace-grade bearing producers while insulating medical device OEMs from yttria-stabilized zirconia volatility. These arrangements bind Tennessee and Colorado foundries to multi-year capacity commitments, creating price visibility that commodity automotive buyers cannot access.
Pricing Analysis
Cost-plus contracts indexed to rare earth oxide benchmarks dominate aerospace and medical procurement, separating AS9100-certified full-ceramic units from automotive hybrid volumes. Price differentiation rests on certification tier and volume scale, with FAA-recognized qualifications commanding premiums. Cost compression in automotive hybrid tiers intensifies as steel-race configurations capture climate-control compressor share. Tier-1 powertrain engineers exhibit highest price sensitivity; surgical robot OEMs prioritize magnetic transparency over unit cost.
Supply Chain Analysis
China and Mountain Pass, California anchor yttria-stabilized zirconia feedstock production for full-ceramic bearings, while Tennessee and Colorado facilities handle gas-pressure sintering of silicon nitride. The supply chain draws from rare earth oxide processing concentration and specialized ceramic foundry capacity. Single-source vulnerability in Chinese rare earth refining creates exposure for medical device OEMs. Distribution runs through AS9100-certified OEM direct channels for aerospace, Tier-1 networks for automotive.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Great Lakes automotive OEMs and Minnesota medical device houses, fragmenting supplier leverage across specification tiers. Procurement consolidation forces bearing houses into bundled engineering-service contracts.
For Market Incumbents: Shield aerospace margin pools by accelerating AS9100 certification investments before FAA auditor backlogs extend further. Deepen captive silicon nitride powder production in Tennessee to offset IRA credit dependency and rare earth oxide volatility. Hybrid bearing substitution from steel-race competitors threatens volume in automotive auxiliary systems. For New Entrants and Emerging Players: FDA 510(k) fast-track partnerships with Minnesota surgical robot OEMs offer the most penetrable entry path. Target unqualified automotive aftermarket distributors in Michigan with cross-referenced hybrid configurations. Lead with embedded sterilization protocol validation to differentiate from incumbent catalog offerings. For Investors and Strategic Acquirers: Technical ceramic substrate specialists with medical device OEM relationships represent the priority acquisition archetype. Long-term viability hinges on backward integration into powder synthesis and certification asset accumulation. Watch for AS9100 auditor capacity expansion as inflection signal for aerospace supplier entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Acceleration | FAA-recognized qualifications unlock Gulfstream and Lockheed Martin approved vendor list access. |
| Silicon Nitride Powder Reshoring | IRA Section 45X credits offset capital costs for domestic gas-pressure sintering capacity. |
| Surgical Robotics Partnership | da Vinci-compatible articulating wrist specifications open premium full-ceramic bearing demand. |
| Automotive Tier-1 Integration | Dual-sourcing qualification for electric power steering redundant architectures extends validation timelines. |
| CNC Grinding Line Modernization | Michigan and Illinois facility upgrades achieve 0.1-micron sphericity for miniature drone motor bearings. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with aerospace procurement directors, medical device quality engineers, automotive Tier-1 supplier managers, and ceramic foundry operations heads; and secondary validation through FAA airworthiness directive filings, NHTSA CAFE standard dockets, FDA 510(k) submission databases, and SEC manufacturing capex disclosures. Bottom-up volume triangulation across product type, application, and size segments converged with top-down value estimates derived from OEM supply agreement patterns.
Across the analysis window, the forecasting framework modeled growth trajectories by ceramic content tier, end-use criticality, and regional manufacturing corridor concentration. CAGRs emerged from segment-level demand elasticity analysis against NHTSA fuel economy mandates and FAA turbine procurement cycles. Inputs included silicon nitride powder production capacity utilization, AS9100 certification queue lengths, and medical device OEM consolidation trends.
The analysis sits within stated boundaries; outcomes outside sustained IRA credit availability, rare earth oxide supply stability, or FDA pathway acceleration would require recalibration. Forecasts reflect documented assumptions about aerospace procurement expansion and automotive lightweighting compliance timelines. Recalibration cycles align with material shifts in NHTSA rulemaking, FAA airworthiness directive issuance, and rare earth oxide price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Traffic Control Products Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
France Automotive Actuators Market