
 Trailer Brake Controllers Market | 2026-2036
Trailer Brake Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Brake Controllers Market Analytics
United States manufacturing capacity for trailer brake controllers is narrowing as domestic suppliers consolidate production around electrified platforms. Tekonsha leverages its heritage in proportional braking algorithms to sustain premium positioning among recreational towing customers. CURT competes through Lippert's distribution network, which anchors aftermarket availability across North American retail channels. REDARC specializes in dual-axis sensing technology, differentiating its controller modules for off-road and commercial applications where terrain variability demands adaptive response curves.
Trailer brake controllers are electromechanical devices that modulate braking force transmission between a towing vehicle and its trailer, typically operating through 12-volt DC circuits with amperage ratings from 15A to 30A depending on axle count and gross trailer weight. Their primary commercial purpose is to synchronize deceleration profiles, prevent jackknifing, and comply with federal stopping-distance mandates for combined vehicle configurations. Electric technology leads the technology dimension due to lower installation complexity and compatibility with standard trailer wiring harnesses, while hydraulic controllers command margin pools in heavy-truck applications where air-over-hydraulic systems remain entrenched. Aftermarket Providers dominate the end-user channel as owner-operators replace factory-installed units with programmable alternatives, though OEM Installation grows fastest as vehicle assemblers integrate brake controllers into factory tow packages.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 121 for air brake systems, while the Society of Automotive Engineers maintains J2807 testing protocols that define maximum trailer weight ratings and validate controller performance under thermal load. State-level commercial vehicle inspection programs in Texas, California, and Florida further shape demand by flagging non-compliant brake controllers during roadside enforcement. Stakeholders must monitor how pending updates to SAE J2807 incorporate electric vehicle regenerative braking interfaces, as this interface standard will determine controller compatibility with next-generation towing platforms.
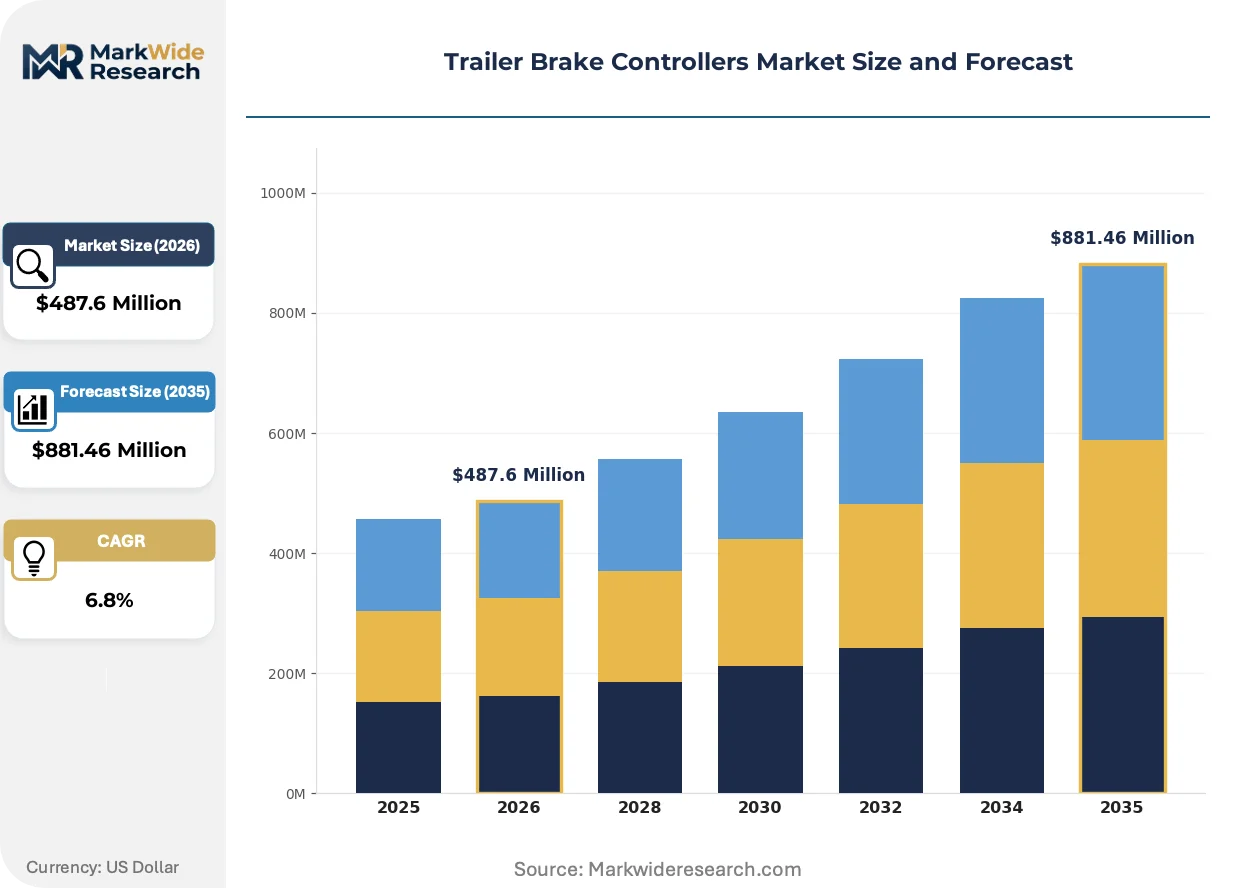
Market Dynamics
The FMCSA's updated stopping-distance mandates for heavy commercial vehicles are compelling fleet-wide brake controller retrofits, while electrified towing platforms force hardware redesigns to interface with regenerative braking systems. This regulatory-technology intersection compresses replacement cycles and rewards suppliers with programmable, multi-protocol architectures.
Growth Catalysts
- Commercial fleet standardization:Logistics operators consolidating tractor-trailer combinations under unified brake controller protocols drive volume procurement across aging equipment bases. Fleet managers prioritize interchangeability to reduce maintenance complexity.
- SAE J2807 thermal validation:The testing protocol's inclusion in OEM tow package certifications ensures controller performance under sustained load, embedding compliance into factory installations and aftermarket replacement demand.
- Fifth-wheel recreational towing:Light-truck owners pulling heavy travel trailers require proportional braking algorithms that adapt to variable terrain, sustaining premium controller demand in the recreational segment.
Market Restraints
- Semiconductor input volatility:Microcontroller unit shortages and automotive-grade chip allocation constraints inflate controller manufacturing costs and extend lead times for programmable units.
- Air-over-hydraulic entrenchment:Heavy-truck applications retain hydraulic brake controllers in air brake systems, limiting electric controller penetration in the highest-axle-count configurations.
- Installation skill scarcity:Proper calibration of proportional braking algorithms requires technician training that aftermarket garages often lack, creating service bottlenecks and warranty claim friction.
Strategic Opportunities
- Electric vehicle towing integration:SAE J2807 updates incorporating regenerative braking interfaces create first-mover advantage for controllers synchronizing with battery-electric truck platforms.
- Texas-California-Florida enforcement corridors:State commercial vehicle inspection programs flagging non-compliant controllers generate replacement pull-through in high-traffic freight lanes.
- Dual-axis sensing convergence:Off-road and construction trailer operators demand adaptive response curves combining accelerometer and gyroscopic inputs for terrain-variable braking.
Industry Challenges
- Legacy wiring harness incompatibility:Retrofitting modern controllers into pre-2010 trailers requires adapter modules and technician time that erode margin on entry-price units.
- Thermal calibration certification delays:NHTSA validation timelines for new controller algorithms extend product launch windows, compressing revenue realization against development investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Brake Controllers Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic, Electric, Air, Vacuum End User: OEMs, Vehicle Assemblers, Aftermarket Providers, Fleet Operators Vehicle Type: Light Trucks, Heavy Trucks, Trailers, SUVs Installation Type: OEM Installation, Aftermarket Installation, Integrated Systems, Modular Kits |
| Companies Covered | Tekonsha, REDARC, CURT (by Lippert), Husky Towing, Lippert Components, Horizon Trailers, Dexter Axle, AL-KO, Atwood Mobile Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Brake Controllers Market Evolving Landscape
Digital integration is transforming trailer brake controllers from analog potentiometers into networked vehicle subsystems, with connectivity protocols enabling real-time diagnostics and over-the-air calibration updates that alter competitive differentiation.
Proportional braking algorithms are digitizing controller response curves through accelerometer-based sensing that replaces time-delay mechanical systems. Recreational towing customers now specify Bluetooth-enabled units allowing smartphone calibration. This capability compression is eroding price premiums for basic time-delay controllers while expanding service revenue streams for connected-device subscriptions.
NHTSA enforcement of Federal Motor Vehicle Safety Standard 121 for air brake systems is tightening controller compliance verification in heavy commercial configurations. The regulation mandates documented stopping-distance performance under loaded thermal conditions. Heavy-truck OEMs are responding by integrating factory-installed controllers with telematics logging to demonstrate roadside compliance.
Aftermarket channel unbundling is fragmenting controller procurement as owner-operators bypass dealer networks for direct-to-consumer programmable alternatives. Amazon and specialized towing retailers capture growing share of replacement demand. This shift concentrates most acutely in the United States, where DIY installation culture and fifth-wheel trailer ownership sustain robust direct-channel volume.
Trailer Brake Controllers Market Segmentation
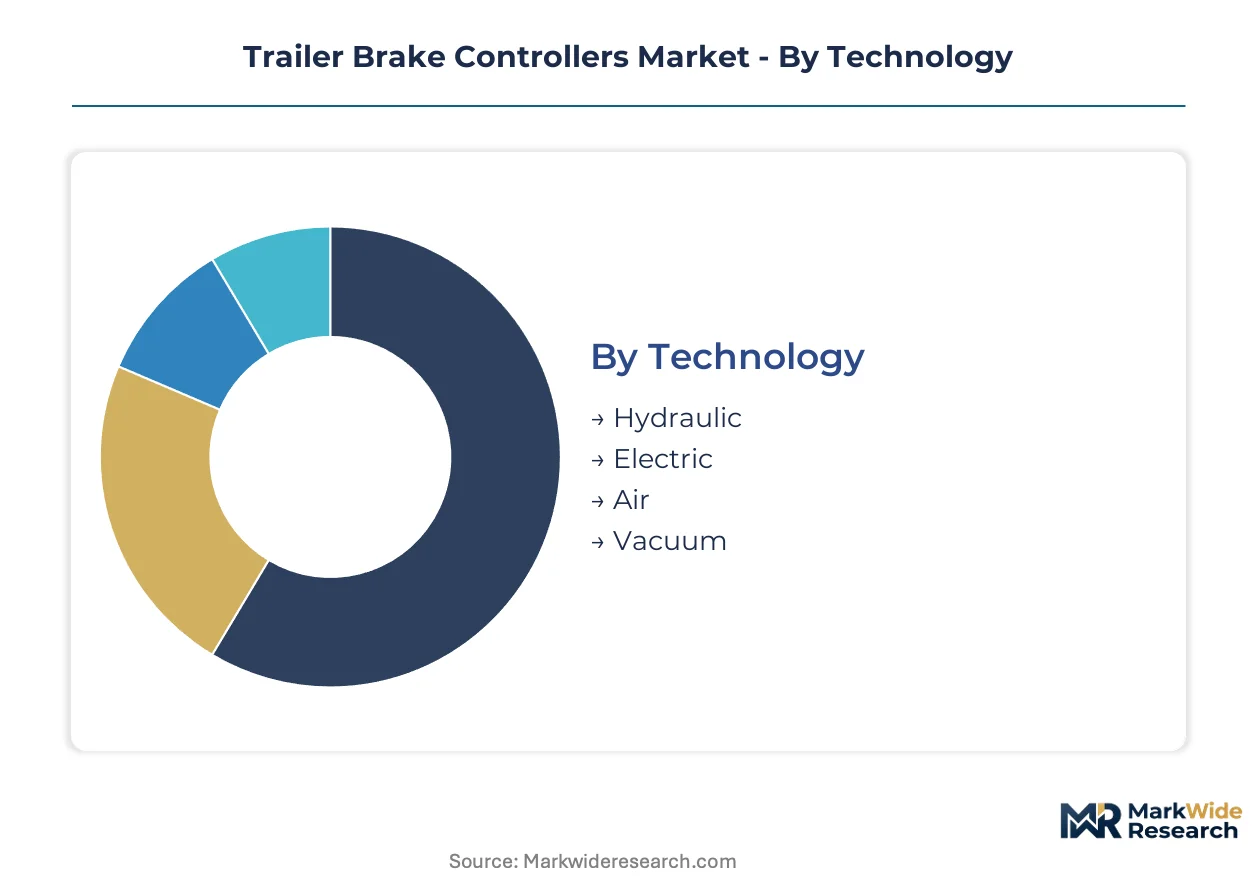
Trailer brake controller segmentation reveals how technology maturity, channel structure, and vehicle integration requirements fragment procurement patterns across commercial and recreational towing applications. Distinct calibration protocols and regulatory compliance frameworks shape purchasing decisions within each category.
Technology:
Mature electric architectures dominate volume, while emerging sensing technologies reshape performance tiers.
- Electric:These controllers operate through 12-volt DC circuits with amperage ratings from 15A to 30A, utilizing solid-state switching to modulate trailer braking force. Demand concentrates in the United States where light-truck towing volumes and fifth-wheel recreational trailer registrations sustain replacement cycles for programmable proportional units.
- Hydraulic:Air-over-hydraulic systems command margin pools in heavy-truck applications, interfacing with existing air brake infrastructure to transmit pressure-based braking signals. Fleet operators in Texas and California prioritize these units for tractor-trailer combinations subject to FMCSA stopping-distance enforcement.
- Air:Direct air brake controllers serve commercial configurations with pneumatic actuation, embedding compliance documentation for NHTSA roadside inspections.
- Vacuum:Legacy vacuum-assisted systems persist in specialized agricultural and vintage trailer applications where hydraulic or electric retrofits prove cost-prohibitive.
Electric handles the majority of throughput; hydraulic is the fastest mover on share as heavy-truck fleets modernize.
End User:
Channel concentration varies sharply between factory-integrated procurement and fragmented aftermarket replacement.
- Aftermarket Providers:Owner-operators bypass dealer networks for direct-to-consumer programmable alternatives, with Amazon and specialized towing retailers capturing replacement demand. This channel concentrates acutely in the United States where DIY installation culture sustains robust direct-channel volume.
- Fleet Operators:Logistics operators consolidating tractor-trailer combinations under unified brake controller protocols drive volume procurement across aging equipment bases, prioritizing interchangeability to reduce maintenance complexity.
- OEMs:Original equipment manufacturers specify controllers for factory tow packages, embedding SAE J2807 thermal validation into vehicle certification.
- Vehicle Assemblers:Light-truck and SUV manufacturers integrate brake controllers into dashboard architectures, requiring compact form factors and vehicle bus compatibility.
Aftermarket Providers handle the majority of throughput; Fleet Operators are expanding most quickly as logistics standardization accelerates.
Vehicle Type:
Weight-class differentiation determines controller specification, calibration range, and regulatory jurisdiction.
- Light Trucks:Half-ton and three-quarter-ton pickups towing recreational trailers require proportional braking algorithms that adapt to variable terrain, sustaining premium controller demand through fifth-wheel and bumper-pull configurations.
- Heavy Trucks:Class 8 tractors face FMCSA stopping-distance mandates that compel controller upgrades, with air-over-hydraulic systems remaining entrenched in the highest-axle-count configurations.
- Trailers:Controller selection depends on gross trailer weight rating and axle count, with multi-axle flatbeds and tankers demanding higher-amperage units.
- SUVs:Unibody crossover platforms with limited towing capacity specify compact, dashboard-integrated controllers for utility trailers and small campers.
Light Trucks handle the majority of throughput; Heavy Trucks are climbing the fastest as commercial fleet retrofits intensify.
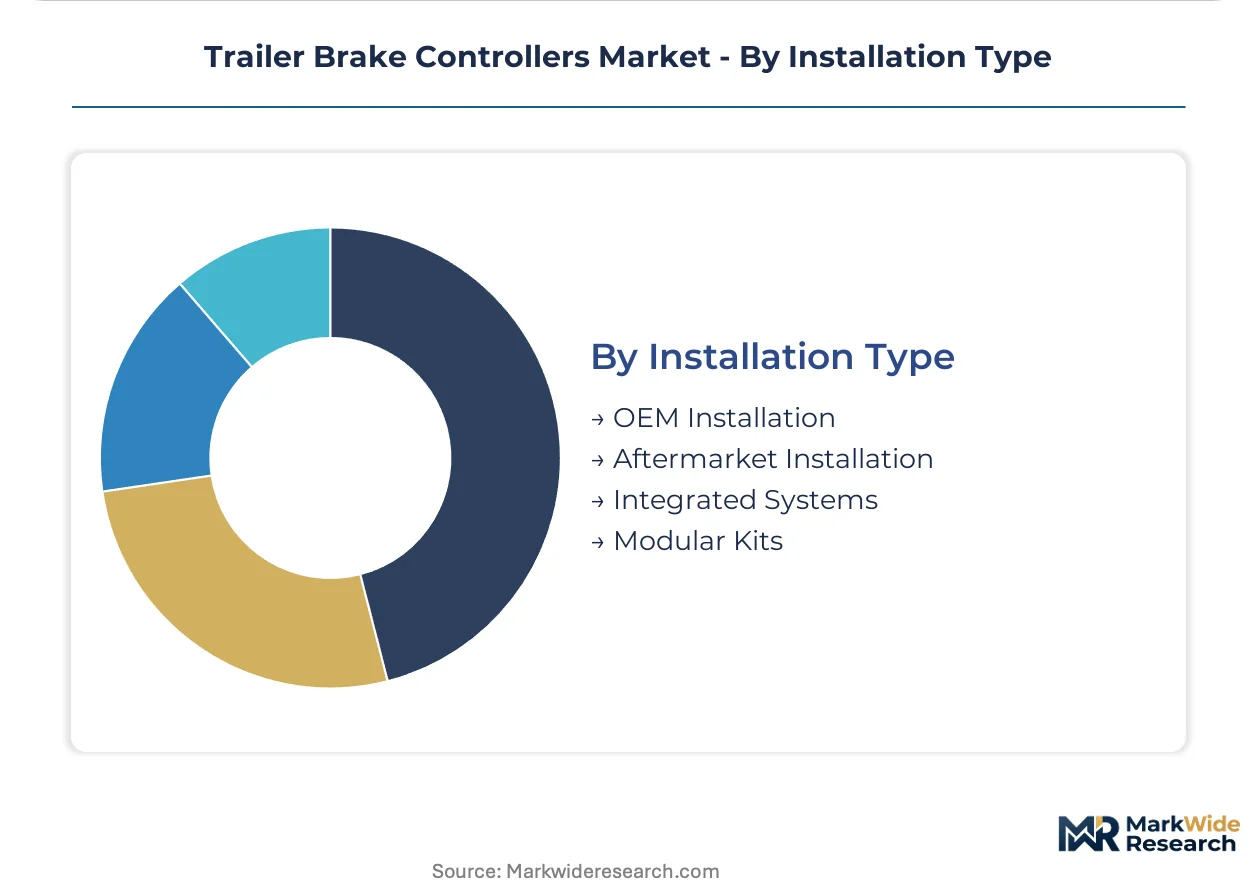
Installation Type:
Integration depth shapes margin structure, with factory installation commanding premium positioning against modular retrofit alternatives.
- OEM Installation:Vehicle assemblers integrate brake controllers into factory tow packages, embedding telematics logging to demonstrate NHTSA roadside compliance and compressing replacement cycles through bundled warranty coverage.
- Modular Kits:Plug-and-play controller systems with vehicle-specific wiring harnesses reduce technician time, addressing installation skill scarcity that aftermarket garages often face.
- Aftermarket Installation:Independent service shops retrofit controllers into existing vehicles, requiring adapter modules for pre-2010 trailers that erode margin on entry-price units.
- Integrated Systems:Dashboard-embedded controllers with vehicle bus connectivity enable real-time diagnostics and over-the-air calibration updates.
OEM Installation handles the majority of throughput; Integrated Systems are gaining share fastest as electric vehicle towing platforms demand regenerative braking synchronization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller manufacturing clusters tightly around Detroit, Stuttgart, and Nagoya, where automotive electronics ecosystems feed tiered supplier networks. Foundry capacity for automotive-grade microcontrollers concentrates in Taiwan and South Korea, creating cross-border dependencies for North American and European assemblers.
United States
Light-truck towing volumes and fifth-wheel recreational trailer registrations sustain replacement cycles across the Midwest and Sun Belt. The NHTSA enforces Federal Motor Vehicle Safety Standard 121 for air brake systems, compelling fleet-wide controller upgrades. Dallas-Fort Worth anchors commercial fleet retrofit demand, where logistics operators standardize brake controller protocols across aging tractor-trailer combinations.
Germany
Heavy-truck OEMs integrate factory-installed controllers with telematics logging to demonstrate roadside compliance under EU braking directives. The KBA enforces type-approval requirements for trailer braking systems under UN ECE Regulation 13. Baden-Württemberg hosts precision sensor manufacturers supplying accelerometer modules for proportional braking algorithms.
China
Domestic electric vehicle manufacturers demand regenerative braking interface standards for next-generation towing platforms. The MIIT coordinates GB standards development for commercial vehicle braking systems. Yangtze River Delta electronics clusters produce solid-state switching components for 12-volt DC controller circuits.
Japan
Automotive suppliers refine dual-axis sensing technology for terrain-variable braking in off-road and construction applications. METI promotes JIS standards alignment with SAE J2807 thermal validation protocols. Nagoya-based manufacturers supply compact form-factor controllers for unibody crossover platforms with limited towing capacity.
Canada
Cross-border supply chains integrate Canadian trailer manufacturers with U.S. controller distributors through harmonized CMVSS regulations. Transport Canada enforces braking performance standards aligned with FMCSA stopping-distance mandates. Ontario's automotive corridor hosts wiring harness suppliers serving modular kit assemblers.
Trailer Brake Controllers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, harnesses, and firmware modules. The supplier base organizes around three archetypes: heritage braking brands with proportional algorithm expertise, diversified automotive electronics houses leveraging vehicle bus integration, and aftermarket-focused distributors capturing direct-to-consumer replacement cycles. Consolidation pressures mount as programmable architectures absorb standalone controller functions into consolidated vehicle electronics modules. Strategic moves center on backward integration into sensor manufacturing and captive supply of vehicle-specific calibration software.
Within the heritage braking tier, Tekonsha and REDARC exemplify specialists that have migrated from mechanical time-delay systems to accelerometer-based proportional platforms. CURT occupies a position bridging aftermarket distribution and OEM supply through its integration within Lippert's manufacturing and logistics network. These three anchors illustrate how controller suppliers defend positioning: algorithmic differentiation for recreational towing, dual-axis sensing for commercial terrain variability, and channel density for replacement pull-through.
| Leading Market Players |
|---|
| Tekonsha |
| REDARC |
| CURT (by Lippert) |
| Husky Towing |
| Lippert Components |
| Horizon Trailers |
| Dexter Axle |
| AL-KO |
| Atwood Mobile Products |
| Others |
Value Network & Pricing Analysis
Undercapacity in Taiwan semiconductor foundries is compressing microcontroller availability and forcing controller manufacturers into allocation-based procurement that elevates unit costs and extends quoted lead times for programmable brake controller variants.
Pricing Analysis
SAE J2807 thermal validation dictates the pricing tier structure across the trailer brake controller market. Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and installation complexity. Price differentiation centers on accelerometer precision and Bluetooth connectivity bundling. Cost compression in economy-tier time-delay units is intensifying because of raw material pass-through from automotive-grade chip shortages. Fleet operators demonstrate highest price sensitivity due to volume procurement leverage, while recreational towing customers absorb premium positioning for terrain-adaptive proportional algorithms.
Supply Chain Analysis
Electronics manufacturing services concentration at Foxconn, Jabil, and Flex anchors controller assembly capacity across Mexico, China, and Vietnam. Semiconductor inputs draw from Taiwan foundries and South Korean memory suppliers. Legacy wiring harness components rest on copper pricing from Chilean mining operations. Single-source vulnerability in automotive-grade microcontroller supply creates exposure to geopolitical trade restrictions. Distribution runs through Lippert's captive network for OEM channels and Amazon-direct for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
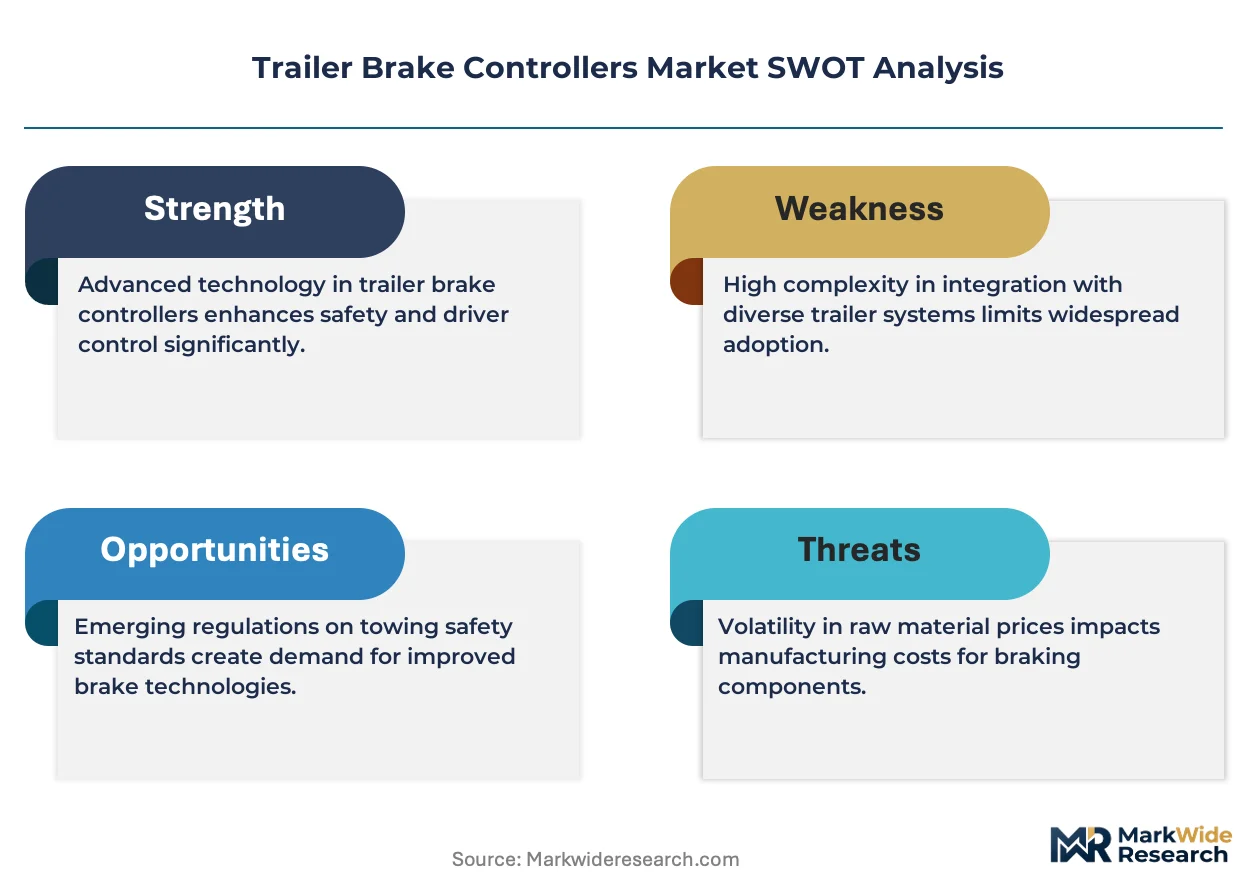
The trailer brake controller market functions as a defensive-moat industry where regulatory entrenchment through FMCSA stopping-distance mandates and SAE J2807 certification requirements erects structural barriers against unvalidated competitors.
For Market Incumbents: Insulate algorithmic differentiation through backward integration into accelerometer sensor manufacturing and captive firmware development centers. Consolidate channel control by absorbing specialized towing retailers facing margin pressure from direct-to-consumer platform migration. Prioritize R&D investment in regenerative braking interface protocols before SAE J2807 updates crystallize compatibility standards. For New Entrants and Emerging Players: Establish a beachhead in electric vehicle towing integration where incumbent controller architectures require redesign for battery-electric truck platforms. Target the Texas-California-Florida enforcement corridor where state inspection programs generate replacement pull-through for compliant units. Pursue a go-to-market angle through telematics bundling that embeds brake controller diagnostics into fleet management software subscriptions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated systems manufacturing as electric vehicle towing platforms demand vehicle bus compatibility and over-the-air calibration infrastructure. Long-term viability favors suppliers with programmable multi-protocol architectures capable of spanning recreational and commercial applications. Acquisition target archetype: mid-tier aftermarket distributors with dense installer relationships in fifth-wheel towing corridors. Monitor SAE J2807 revision timelines as the critical inflection signal for regenerative braking interface standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive accelerometer supply secures margin pools for proportional braking algorithms against semiconductor allocation constraints. |
| Regenerative Braking Interface Development | First-mover alignment with pending SAE J2807 updates captures electric vehicle towing platform certification. |
| Fleet Telematics Integration | Embedded diagnostics demonstrate NHTSA roadside compliance and generate recurring service revenue streams. |
| Channel Consolidation in Sun Belt Markets | Installer network density in Texas and Florida secures replacement pull-through from state enforcement programs. |
| Dual-Axis Sensing Patent Portfolio | Accelerometer-gyroscope fusion technology differentiates positioning for off-road and construction trailer applications. |
Research Methodology
A spread of perspectives from fleet maintenance directors, aftermarket distributor procurement managers, OEM platform engineers, and NHTSA compliance officers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with tiered supplier executives and brake controller calibration technicians. Secondary validation drew from FMCSA enforcement data, SAE technical standards documentation, state commercial vehicle inspection records, and customs trade databases. Bottom-up unit economics triangulated against top-down fleet replacement cycle modeling.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, end-user channel structure, vehicle weight class, and installation integration depth. CAGRs derived from logistic curve penetration assumptions calibrated to historical retrofit cycle patterns. Industry-specific forecast inputs incorporated fifth-wheel trailer registration trajectories and electric vehicle towing platform production schedules.
Sensitivities concentrate around semiconductor allocation volatility, FMCSA enforcement intensity variation across state jurisdictions, and SAE J2807 revision timing. Forecasts reflect documented assumptions subject to revision from regulatory technology mandates or supply chain restructuring. Quarterly review of microcontroller lead time indicators and state inspection program budget allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Idler Arm Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Car Radiator Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Headlight Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Hydraulic Actuators Market