
 Automotive in-Wheel Motors Market | 2026-2036
Automotive in-Wheel Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive in-Wheel Motors Market Analysis
Copper winding substitution by aluminum hairpin configurations is repositioning thermal management economics in in-wheel motor architectures. Protean Electric leverages integrated power electronics to sustain design leadership in high-torque density systems. Elaphe Propulsion Technologies anchors its position through direct-drive expertise optimized for low-floor commercial vehicle platforms. Schaeffler AG competes via bearing-integration capabilities that reduce unsprung mass in wheel-hub assemblies.
Automotive in-wheel motors integrate electric drive components directly into wheel assemblies, eliminating mechanical drivetrain losses through permanent magnet synchronous or switched reluctance topologies with torque densities exceeding 30 Nm/kg. These systems enable independent torque vectoring, regenerative energy capture, and packaging efficiency critical to electric vehicle platform design. Synchronous motors dominate current production volumes due to superior efficiency maps at highway speeds, while asynchronous induction variants gain traction in cost-sensitive commercial applications where magnet-free construction reduces supply chain risk. Electric propulsion applications command the largest share of installed capacity, though regenerative braking integration is emerging as a secondary value driver for fleet operators prioritizing energy recovery in stop-duty cycles.
NHTSA crashworthiness standards and EPA zero-emission vehicle mandates in the United States are accelerating OEM validation timelines for hub-mounted propulsion systems. ECE R100 electrical safety protocols and EU battery passport traceability requirements under the EU Green Deal are reshaping certification pathways for European market entry. Stakeholders must monitor how dual carbon goals in China and emerging GB standard revisions for commercial EV safety will influence magnet sourcing strategies and thermal validation protocols.
Market Dynamics
Permanent magnet reduction strategies are compressing motor economics as rare earth supply constraints force synchronous motor designers toward switched reluctance and ferrite-based alternatives. This material pivot is reshaping competitive positioning across commercial vehicle platforms.
Growth Catalysts
- Zero-emission fleet mandates:Shenzhen and Santiago electric bus operators are accelerating hub motor validation timelines as municipal operators face binding carbon neutrality deadlines.
- GB standard revisions:China's commercial EV safety protocol updates are creating certification pathways that validate thermal management architectures for in-wheel systems.
- Aluminum hairpin windings:Copper substitution is reducing raw material exposure while sustaining torque density in high-duty cycle applications.
Market Restraints
- Neodymium price volatility:Rare earth oxide concentrate costs from Myanmar and Chinese separation facilities are creating input cost instability for permanent magnet motor producers.
- Unsprung mass penalties:Wheel-hub assembly weight increases degrade ride quality and suspension component durability, limiting passenger car adoption.
- ECE R100 compliance friction:European electrical safety validation timelines for high-voltage wheel-mounted systems extend OEM development cycles by 18-24 months.
Strategic Opportunities
- Low-floor commercial platforms:Direct-drive architectures eliminate axle differentials and driveshafts, enabling flat-floor interior configurations for urban transit buses.
- EU battery passport traceability:Green Deal supply chain disclosure requirements favor localized motor production with verifiable material sourcing.
- Independent torque vectoring:Wheel-level traction control is expanding into off-highway mining and agricultural equipment where terrain variability demands precise power modulation.
Industry Challenges
- Power electronics integration:Inverter thermal management within confined wheel-hub volumes requires specialized packaging expertise that crosses automotive and industrial electronics skill domains.
- Crashworthiness validation:NHTSA side-impact protocols for hub-mounted high-voltage systems demand extensive physical testing that compresses development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive in-Wheel Motors Market |
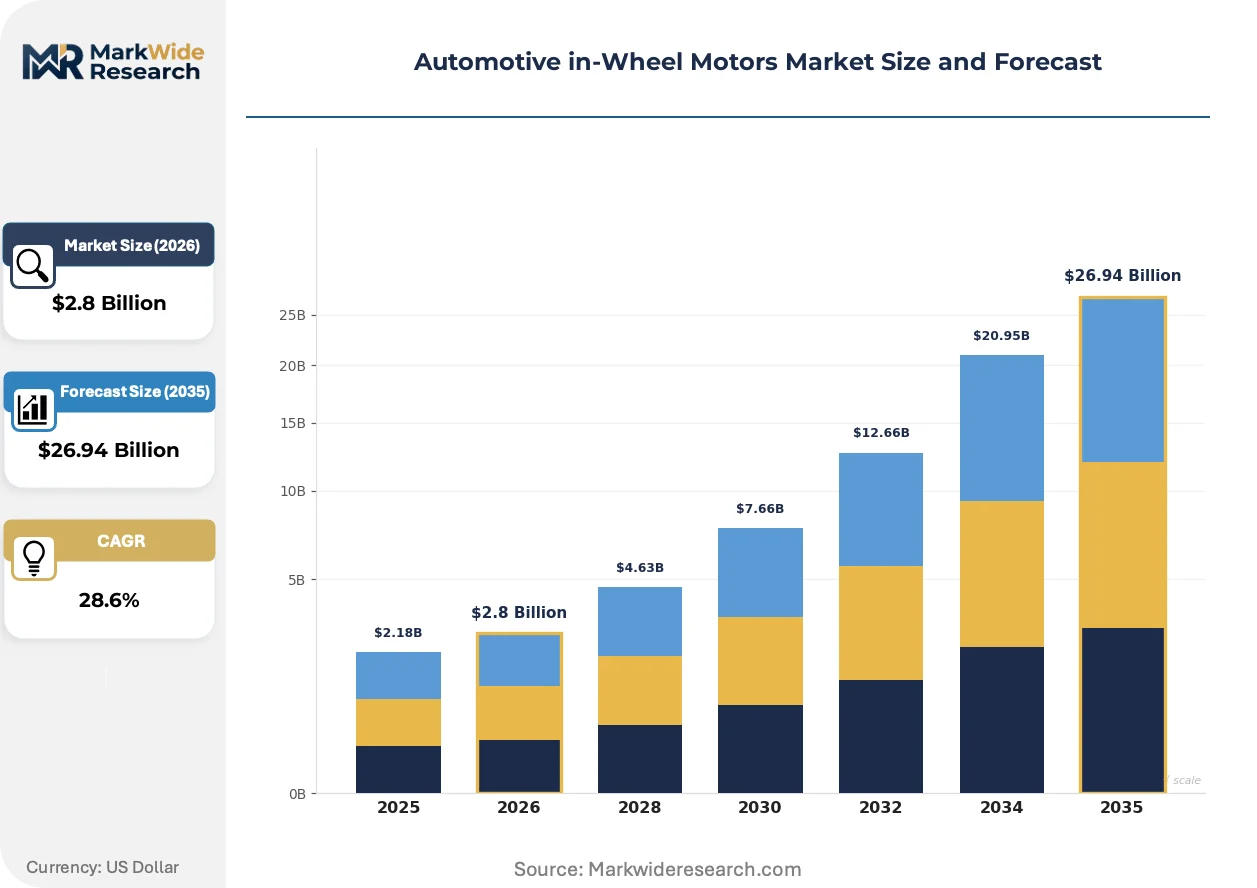
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Synchronous Motors, Asynchronous Motors Technology: Brushless Technology, Direct Drive, Magnetic Levitation, Variable Reluctance End User: Passenger Vehicles, Commercial Vehicles, Electric Buses, Cargo Vans Application: Performance Upgrade, Electric Propulsion, Regenerative Braking, Off-Road Vehicles |
| Companies Covered | Protean Electric, Elaphe Propulsion Technologies, NTN Corporation, NSK Ltd., Schaeffler AG, Ziehl-Abegg, e-Traction, Ecomove GmbH, Printed Motor Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive in-Wheel Motors Market Emerging Trajectories
Material science advances and regulatory disclosure requirements are converging to reshape motor architecture decisions. Thermal management innovation and supply chain traceability are becoming primary design constraints rather than secondary optimization targets.
Switched reluctance motor topologies are expanding into cost-sensitive commercial vehicle segments where magnet-free construction eliminates rare earth supply risk. Regional bus manufacturers in India and Brazil are adopting these systems for municipal fleet tenders where total cost of ownership dominates procurement scoring. This topology shift is expanding into highway-speed applications as silicon carbide inverters improve efficiency maps at rotational velocities above 10,000 RPM.
EU battery passport traceability requirements under the Green Deal are mandating documented supply chains for critical raw materials in electrified drivetrains. Motor manufacturers must now certify magnet provenance and carbon intensity for European market entry. Commercial vehicle OEMs are responding by qualifying dual-source ferrite magnet suppliers in Vietnam and South Korea to satisfy disclosure thresholds.
Fleet operators are consolidating procurement decisions at the metropolitan authority level rather than delegating to individual depots or route operators. Santiago's integrated transit procurement office now specifies hub motor performance benchmarks across its entire electric bus fleet. This buyer concentration is compressing supplier negotiation cycles and favoring motor architectures with standardized mounting interfaces and service documentation.
Automotive in-Wheel Motors Market Segmentation
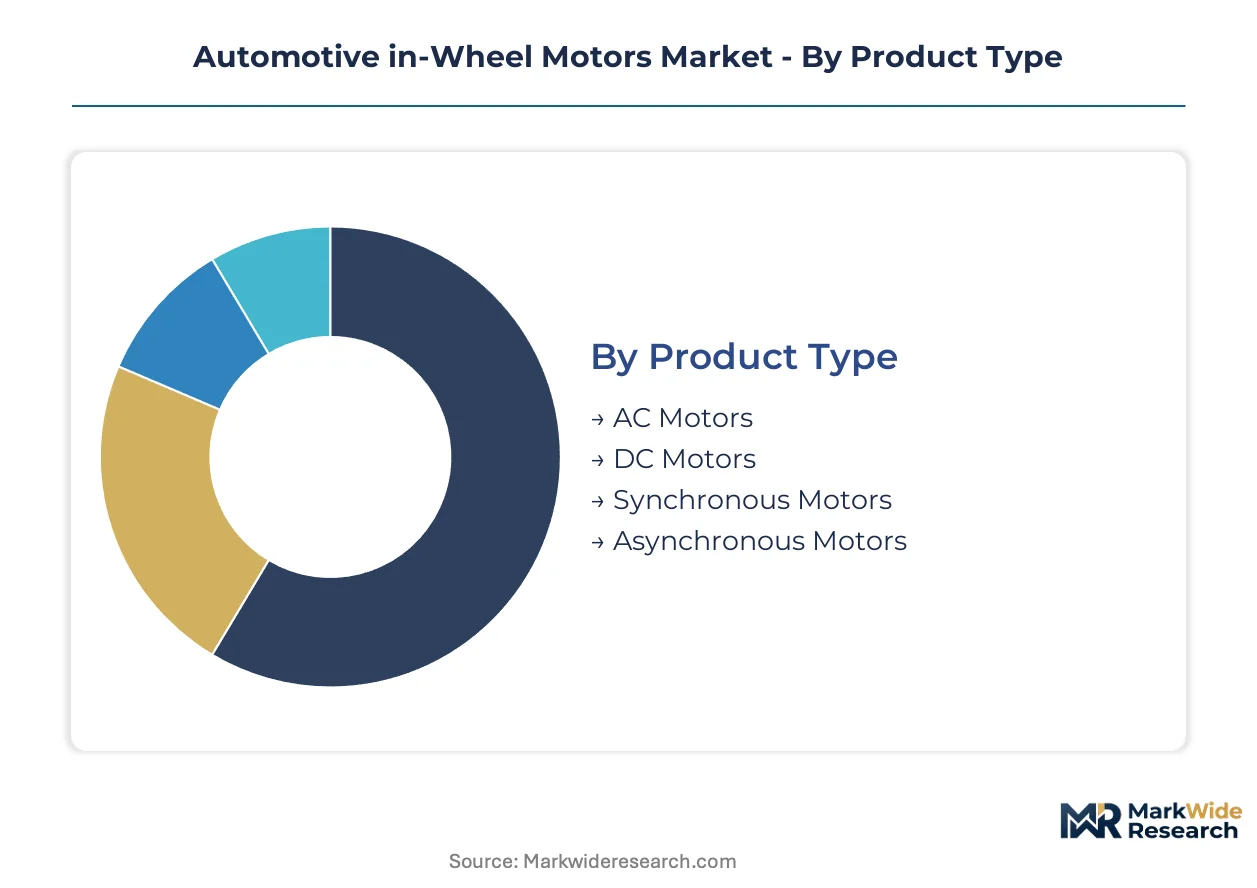
Segmentation in the automotive in-wheel motors market reveals how torque density requirements, thermal constraints, and duty cycle intensity fragment procurement decisions across vehicle platforms. Buyers prioritize motor topologies based on whether their fleets demand sustained highway efficiency or stop-start urban regeneration.
Product Type:
Procurement teams select motor categories based on magnet dependency and efficiency map characteristics that determine total cost of ownership across fleet lifecycles.
- Synchronous Motors:Permanent magnet synchronous architectures deliver efficiency exceeding 95% at highway speeds, making them dominant in electric bus fleets across Shenzhen and Santiago where range optimization drives procurement scoring. Rare earth supply constraints are forcing magnet reduction strategies that compress unit economics for this segment.
- Asynchronous Motors:Induction designs eliminate magnet procurement risk entirely, attracting municipal fleet tenders in India and Brazil where total cost of ownership dominates vendor selection. Copper rotor losses limit peak efficiency but simplify maintenance protocols in high-dust operating environments.
- AC Motors:Polyphase alternating current systems integrate with standard inverter architectures common to commercial vehicle power electronics.
- DC Motors:Brushed direct current configurations persist in low-speed industrial mobility applications requiring minimal control complexity.
Synchronous motors lead on scale across installed capacity; asynchronous motors lead on momentum as rare earth price volatility accelerates magnet-free adoption.
Technology:
Technology selection hinges on whether buyers prioritize unsprung mass reduction, elimination of mechanical drivetrain components, or specialized performance characteristics for niche applications.
- Direct Drive:Elimination of reduction gears enables flat-floor configurations in low-floor urban transit buses, with Santiago's integrated procurement office specifying this architecture across its entire electric fleet. Torque density requirements above 30 Nm/kg sustain design leadership for high-duty commercial platforms.
- Brushless Technology:Electronic commutation removes mechanical wear points, extending service intervals for electric bus operators facing binding carbon neutrality deadlines. Silicon carbide inverters are improving efficiency maps at rotational velocities exceeding 10,000 RPM.
- Magnetic Levitation:Contactless bearing systems reduce friction losses in premium performance applications where maintenance access is constrained.
- Variable Reluctance:Magnet-free construction aligns with supply chain disclosure requirements under EU Green Deal traceability mandates.
Direct drive dominates commercial vehicle procurement volumes; brushless technology climbs fastest as fleet operators consolidate specifications at metropolitan authority levels.
End User:
End user segmentation reflects divergent tolerance for unsprung mass penalties and thermal validation complexity across passenger, commercial, and specialized transport applications.
- Electric Buses:Zero-emission mandates in Chinese and Chilean cities are compressing supplier negotiation cycles for hub motor architectures with standardized mounting interfaces. Flat-floor interior requirements make direct-drive in-wheel systems non-negotiable for urban transit procurement.
- Commercial Vehicles:Cargo van fleets prioritize regenerative braking integration for stop-duty cycles, with energy recovery emerging as a secondary value driver in last-mile delivery applications. Aluminum hairpin windings are reducing raw material exposure in high-volume production.
- Passenger Vehicles:Ride quality degradation from wheel-hub assembly weight increases limits adoption to performance-oriented segments where torque vectoring justifies suspension compromise.
- Cargo Vans:Last-mile logistics operators specify hub motors for packaging efficiency in compact urban delivery platforms.
Electric buses lead on scale through municipal fleet consolidation; commercial vehicles gain share fastest as last-mile electrification accelerates.
Application:
Application segmentation tracks whether buyers seek primary propulsion, energy recovery, performance enhancement, or specialized terrain capability from in-wheel motor integration.
- Electric Propulsion:Primary drive applications command the largest installed capacity, with permanent magnet synchronous topologies dominating highway-speed efficiency requirements. China's Yangtze River Delta manufacturing corridor concentrates production near EV assembly plants.
- Regenerative Braking:Energy recovery integration is emerging as a standalone value driver for fleet operators prioritizing stop-duty cycle efficiency in urban transit and delivery applications. GB standard revisions are validating thermal management architectures for high-frequency regeneration.
- Performance Upgrade:Aftermarket torque vectoring systems target enthusiast segments where independent wheel control enhances dynamic handling.
- Off-Road Vehicles:Mining and agricultural equipment demands precise power modulation for terrain variability, expanding wheel-level traction control into heavy industrial applications.
Electric propulsion leads on scale across production volumes; regenerative braking shows steepest expansion trajectory as energy recovery becomes a standalone procurement criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing corridor anchors production capacity for in-wheel motor systems, with tier-one suppliers clustering near EV assembly plants in Shanghai, Suzhou, and Ningbo. Municipal fleet electrification programs across multiple continents are compressing validation timelines and reshaping regional procurement patterns.
China
Shenzhen's electric bus fleet operators specify hub motor architectures with standardized mounting interfaces across their entire zero-emission mandate compliance programs. GB standard revisions for commercial EV safety under MIIT are validating thermal management protocols for wheel-mounted high-voltage systems. The Yangtze River Delta corridor concentrates manufacturing near assembly plants in Shanghai and Suzhou.
United States
Last-mile delivery fleet operators in California and Texas prioritize regenerative braking integration for stop-duty cycle efficiency in urban logistics applications. NHTSA crashworthiness standards for side-impact protocols on hub-mounted high-voltage systems extend OEM development timelines. Manufacturing activity clusters near Detroit and Austin where EV platform engineering centers validate motor architectures.
Germany
Commercial vehicle OEMs in Bavaria and Baden-Württemberg qualify dual-source ferrite magnet suppliers to satisfy EU battery passport traceability mandates under the Green Deal. ECE R100 electrical safety protocols reshape certification pathways for European market entry. Stuttgart and Munich anchor development activity where bearing-integration capabilities reduce unsprung mass in wheel-hub assemblies.
Chile
Santiago's integrated transit procurement office specifies direct-drive in-wheel motor performance benchmarks across its entire electric bus fleet. Municipal carbon neutrality deadlines compress supplier negotiation cycles for urban transit platforms. The metropolitan authority's consolidated procurement decisions favor architectures with verifiable material sourcing documentation.
India
Municipal fleet tenders in Maharashtra and Karnataka adopt switched reluctance motor topologies where total cost of ownership dominates vendor selection scoring. BIS certification requirements for commercial EV components create compliance pathways for magnet-free construction. Manufacturing activity concentrates in Pune and Bangalore where regional bus manufacturers serve stop-start urban duty cycles.
Automotive in-Wheel Motors Market Vendor Landscape
Strategic partnerships dominate the current landscape as motor specialists align with bearing manufacturers and power electronics integrators to solve thermal management and unsprung mass challenges simultaneously. The vendor base organizes around three archetypes: integrated system houses combining motor and inverter expertise, bearing specialists extending into hub assemblies, and pure-play motor designers licensing architectures to tier-one suppliers. Capacity expansion and technology licensing represent the two dominant competitive moves, with regional production localization accelerating to satisfy EU supply chain disclosure requirements.
Within the integrated system tier, Protean Electric and Elaphe Propulsion Technologies exemplify contrasting approaches to hub motor commercialization. Protean Electric occupies a position emphasizing power electronics integration for high-torque density applications. Elaphe Propulsion Technologies anchors the direct-drive specialization vector optimized for low-floor commercial vehicle platforms. Among European-based diversified suppliers, Schaeffler AG represents the bearing-integration archetype that reduces unsprung mass through wheel-hub assembly expertise.
| Leading Market Players |
|---|
| Protean Electric |
| Elaphe Propulsion Technologies |
| NTN Corporation |
| NSK Ltd. |
| Schaeffler AG |
| Ziehl-Abegg |
| e-Traction |
| Ecomove GmbH |
| Printed Motor Works |
| Others |
Supply Flow & Price Mechanics
Aluminum hairpin winding substitution is compressing motor manufacturing costs while simultaneously redistributing supplier power toward metallurgical processors in China and South Korea. This dual transformation tightens margins for copper-dependent producers and elevates pricing leverage for vertically integrated tier-one suppliers commanding rare earth magnet alternatives.
Pricing Analysis
Neodymium oxide cost pass-through dominates synchronous motor pricing, with ferrite-based alternatives commanding 15-25% unit cost advantages in municipal bus tenders. Price differentiation rests on magnet certification grade and thermal management complexity, with GB-standard validated architectures capturing premium positioning. Pricing pressure intensifies downward as Indian and Brazilian fleet operators prioritize total cost of ownership scoring over efficiency benchmarks. Municipal procurement offices exhibit highest price sensitivity, while performance-oriented passenger vehicle segments tolerate suspension-compromising premiums for torque vectoring capability.
Supply Chain Analysis
Reverse-logistics networks for remanufactured wheel-hub assemblies remain nascent, constraining secondary market development and extending primary equipment replacement cycles. Manufacturing gravity centers on China, Germany, and Japan, with the Yangtze River Delta corridor feeding EV assembly plants in Shanghai and Suzhou. Magnet supply draws from Chinese separation facilities and Vietnamese ferrite processors, while silicon carbide inverters source from Japanese substrate manufacturers. Single-source vulnerability concentrates in rare earth oxide concentrate flows from Myanmar. Distribution runs through tier-one automotive supplier networks with direct OEM qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive in-wheel motors market compounds steadily as municipal zero-emission mandates harden into binding procurement specifications across three continents. Fleet electrification timelines provide predictable demand visibility that sustains manufacturer investment confidence.
For Market Incumbents: Anchor defensive positioning through backward integration into ferrite magnet supply chains and captive aluminum hairpin winding capacity in the Yangtze River Delta corridor. Magnet-free switched reluctance topologies threaten permanent motor economics; incumbents should consolidate bearing-integration expertise through specialized hub assembly acquisitions to maintain unsprung mass advantages against emerging power electronics specialists. For New Entrants and Emerging Players: Capture white-space in Indian municipal bus tenders where BIS certification pathways favor magnet-free construction and total cost of ownership procurement scoring. Last-mile delivery cargo vans present the most penetrable segment, with regenerative braking integration emerging as a standalone value driver. A software-defined torque vectoring go-to-market angle differentiates against hardware-centric incumbents in fleet management platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play motor designers lacking inverter integration capabilities, as power electronics convergence determines competitive survival. Long-term viability favors vertically integrated system houses with thermal management packaging expertise spanning automotive and industrial electronics domains. Monitor GB standard revision implementation timelines and EU battery passport enforcement thresholds as inflection signals for regional production localization mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet-Free Motor Architecture Development | Eliminates rare earth supply risk for Indian and Brazilian municipal tenders under BIS protocols. |
| Power Electronics Integration Investment | Silicon carbide inverter packaging expertise crosses automotive and industrial skill domains. |
| Regional Production Localization | EU battery passport traceability mandates favor verifiable material sourcing documentation. |
| Thermal Management Certification | GB standard revisions validate wheel-mounted high-voltage system architectures for commercial EV entry. |
| Direct-Drive Platform Standardization | Flat-floor bus configurations in Santiago and Shenzhen consolidate procurement specifications. |
Methodological Framework
Coverage spans China, the United States, Germany, Chile, and India, with primary inputs from each regional cluster combining interviews with Tier 1 supplier procurement officers, OEM platform engineers, municipal fleet managers, and power electronics integration specialists. Secondary validation draws from vehicle production databases, IHS Markit registration data, SEC filings from bearing and motor component suppliers, and MIIT GB standard documentation. Bottom-up unit economics triangulate against top-down market sizing across synchronous, asynchronous, and switched reluctance motor categories.
Rate-of-change decomposition separates volume expansion from value capture across vehicle class, propulsion architecture, magnet dependency tier, and regional production cluster dimensions. CAGRs derive from modeled adoption curves for electric bus fleets, commercial van electrification, and passenger vehicle torque vectoring penetration. Forecast inputs incorporate neodymium price volatility scenarios, GB standard revision implementation pacing, and EU Green Deal supply chain disclosure enforcement thresholds.
Underlying measurement precision varies by segment; electric bus procurement volumes carry tighter precision than passenger vehicle adoption given consolidated metropolitan authority buying patterns. Forecasts reflect assumptions on rare earth supply stability, thermal validation protocol harmonization, and fleet operator total cost of ownership scoring weights. Practitioners should monitor Myanmar rare earth export licensing, ferrite magnet qualification timelines in Vietnam and South Korea, and NHTSA side-impact protocol finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Smart E-Drive Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Air Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
Global Motor Soft Starter Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Global Electric Motor Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Traction Motor Core Market
Electric Motor
Global Motor Management Market