
 Rail Wheel Market | 2026-2036
Rail Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Wheel Market Intelligence
Clad wheel manufacturing is narrowing the performance gap between forged and cast production routes for high-axle-load applications. Nippon Steel Corporation leverages its integrated steelmaking complex to control alloy chemistry from melt to final heat treatment. Amsted Rail Company Inc. anchors North American supply through captive foundry capacity and in-service monitoring networks.
Rail wheels are hardened steel discs, typically 860-1,070 mm in diameter, mounted on axles to support and propel rolling stock; they must withstand contact stresses exceeding 1,500 MPa while maintaining dimensional stability across millions of load cycles. Solid wheels still occupy the bulk of replacement demand, though composite wheels are capturing share in urban transit where noise regulation and unsprung mass reduction command premium positioning. Steel dominates material selection for freight and high-speed segments, while aluminum garners interest in light-rail and metro configurations where acceleration performance outweighs wear-life metrics.
China's NMPA-aligned GB standards and India's RDSO specifications enforce fatigue-testing protocols that filter out non-integrated suppliers, while the EU's MDR and CE marking frameworks extend quality-assurance requirements to wheels imported for European rolling stock. The US Federal Railroad Administration mandates ultrasonic inspection intervals that shape wheel-set replacement economics. Stakeholders must weigh alloy-development cycles against the certification timelines of multiple national rail safety bodies.
Market Dynamics
Axle-load standard escalation across Asia-Pacific freight corridors is compressing wheel replacement cycles and forcing alloy upgrades that favor integrated steelmakers over merchant suppliers.
Growth Catalysts
- China's GB Standard Escalation:The NMPA-aligned GB criteria mandate fatigue-testing protocols that disqualify non-integrated foundries, concentrating procurement among captive steel complexes serving Belt-and-Rail corridors.
- Composite Wheel Adoption:Urban transit operators in noise-regulated European and Japanese metros are specifying aluminum-steel hybrid configurations to reduce unsprung mass and track impact forces.
- India's Dedicated Freight Corridor Buildout:RDSO specifications for 32.5-tonne axle loads on the Eastern and Western DFC routes are generating concentrated demand for clad and forged wheel sets from domestic steel producers.
Market Restraints
- Scrap Steel Price Volatility:Electric-arc furnace operators face margin compression when shredded auto scrap fluctuates, forcing wheel foundries to absorb input cost swings or renegotiate long-term supply agreements.
- Supplier Concentration in Premium Forgings:High-axle-load wheel production depends on a narrow base of integrated steelworks with vacuum-degassing and radial forging capacity, creating single-source risk for Tier-1 rail OEMs.
- Cast Wheel Performance Ceiling:Solid cast configurations face structural fatigue limits above 25-tonne axle loads, constraining their deployment in heavy-haul iron ore and coal corridors where forged or clad wheels dominate.
Strategic Opportunities
- Underpenetrated Southeast Asian Freight Networks:Indonesia's Trans-Sumatra and Malaysia's East Coast Rail Link projects lack established wheel supply chains, creating first-mover positioning for producers with ASEAN certification.
- Predictive Maintenance Integration:Wheel-mounted acoustic and temperature sensors enabling real-time crack detection are converging with cloud-based fleet management platforms, opening recurring revenue streams beyond hardware sales.
- EU Green Deal Procurement Mandates:The EU's sustainable procurement directives for public rail operators favor suppliers with verified Scope 3 emissions data, advantaging European mills with integrated hydrogen-reduction pilot programs.
Industry Challenges
- Metallurgical Talent Scarcity:Vacuum degassing and controlled-cooling process engineering expertise concentrates among retiring specialists at legacy steelworks, constraining quality consistency at newer foundry investments.
- Multi-Jurisdiction Certification Timelines:Wheels destined for cross-border rolling stock must satisfy sequential FRA, EU MDR, and RDSO approval processes, extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Wheel Market |
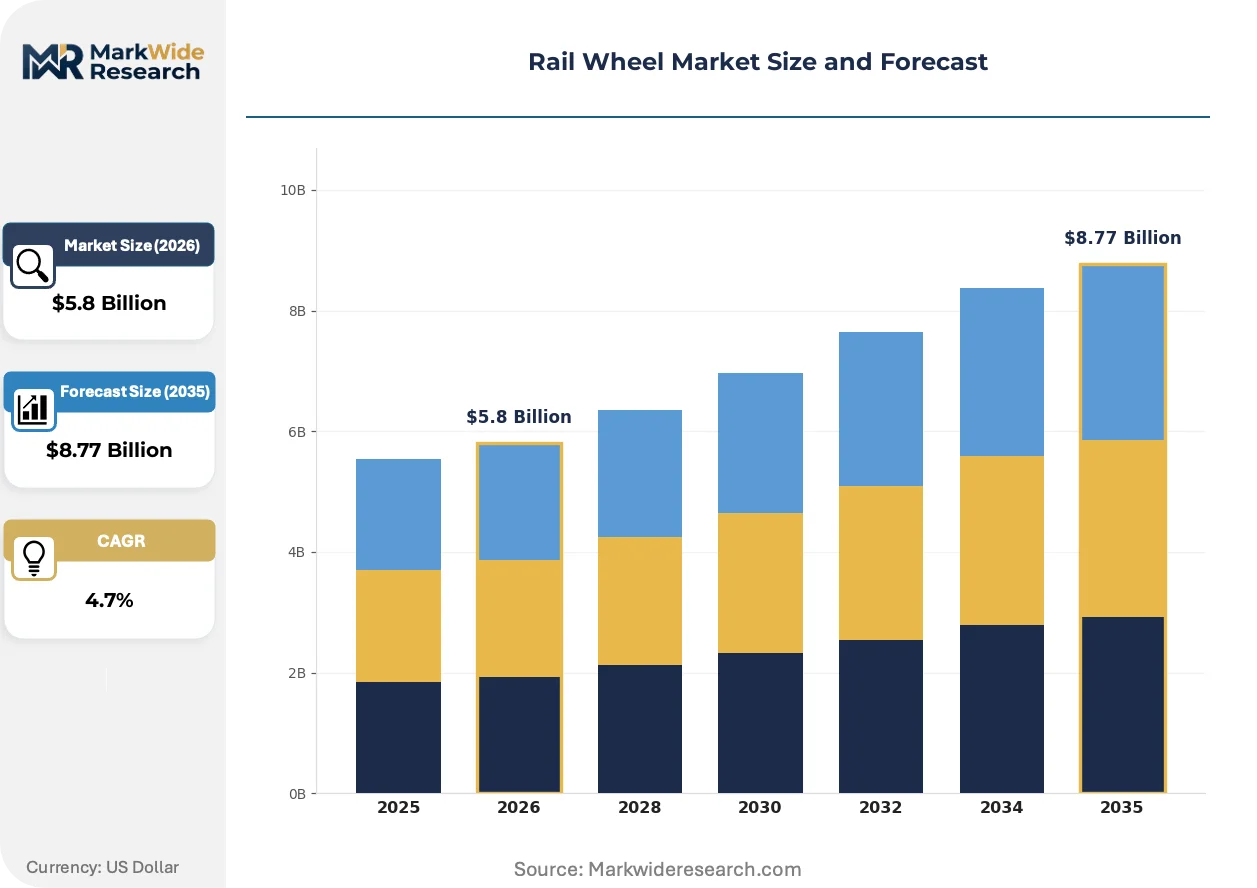
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Wheels, Composite Wheels, Cast Wheels, Forged Wheels Material: Steel, Aluminum, Iron, Other Alloys End User: Freight Operators, Passenger Services, Infrastructure Providers, OEMs Application: High-Speed Rail, Urban Transit, Freight Transport, Specialized Lines |
| Companies Covered | Alstom SA, Nippon Steel Corporation, Amsted Rail Company Inc., EVRAZ Plc, Lucchini RS, ArcelorMittal, Bharat Forge Limited, Wabtec Corporation, CRRC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Wheel Market Strategic Shifts & Innovations
Digital inspection protocols and material science advances are compressing the performance gap between production routes while regulatory carbon accounting reshapes supplier qualification criteria.
Clad wheel manufacturing bonds a high-carbon steel tread to a tougher alloy core, delivering forged-grade fatigue resistance at cast-equivalent production economics. Heavy-haul operators in Australia's Pilbara iron ore network and Brazil's Carajás corridor are qualifying clad configurations for 40-tonne axle loads. This hybrid route is rendering obsolete the historical trade-off between unit cost and load-bearing capacity that segmented the market.
The EU's MDR and CE marking frameworks now extend quality-assurance documentation requirements to wheels imported for European rolling stock, including third-party fatigue-test witnessing and material traceability back to melt source. European rail OEMs are responding by qualifying fewer, larger suppliers capable of sustaining audit-ready documentation systems. High-speed passenger segments face the steepest compliance burden given their zero-failure tolerance regimes.
After-sales service unbundling is separating wheel-set replacement from traditional rolling-stock maintenance contracts. Freight operators in North America are contracting directly with wheel foundries for condition-based replacement scheduling, bypassing railcar lessors and OEM service networks. This pattern is most visible among Class I railroads with centralized fleet analytics capabilities, compressing procurement decision cycles and rewarding suppliers with in-service monitoring infrastructure.
Rail Wheel Market Segmentation
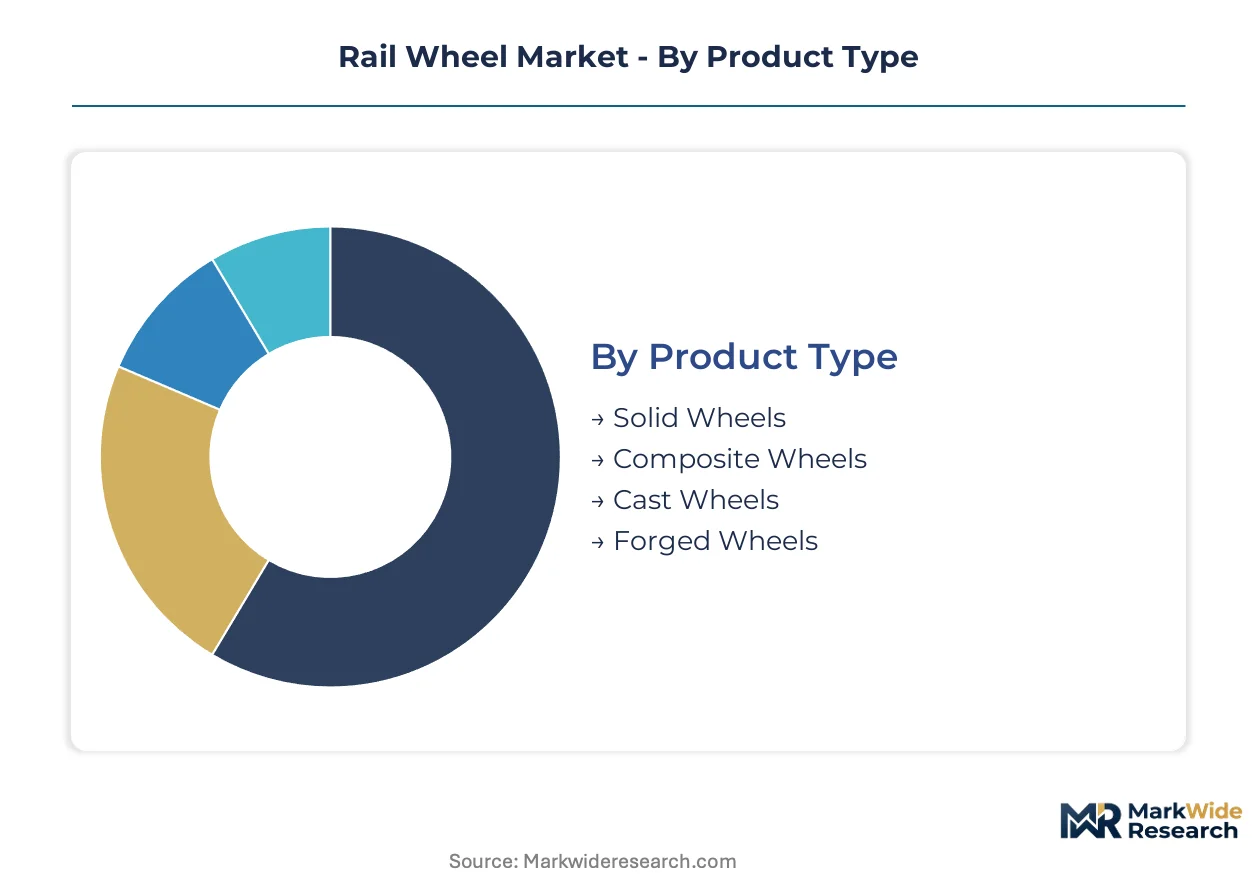
Rail wheel procurement patterns diverge sharply across product configurations, with replacement cycle economics and certification requirements driving distinct service intensity levels. Understanding these segment boundaries clarifies where suppliers can capture recurring revenue versus one-off equipment sales.
Product Type:
After-sales service intensity varies dramatically by manufacturing route, with forged and clad wheels demanding predictive monitoring contracts while cast wheels rely on volume-driven spot replacement programs.
- Solid Wheels:Monolithic steel discs remain the default specification for freight corridors and legacy passenger fleets. India's Dedicated Freight Corridor and China's Belt-and-Rail corridors generate concentrated demand as axle-load standards tighten under RDSO and GB criteria.
- Composite Wheels:Aluminum-steel hybrid configurations reduce unsprung mass for noise-regulated urban transit. Japanese and European metro operators specify these for acceleration-sensitive applications where track impact forces must stay below 80 kN.
- Cast Wheels:Liquid-metal forming delivers cost-efficient production for standard-duty applications. Foundry capacity concentrates among integrated steel complexes with captive melt supply.
- Forged Wheels:Radial forging and controlled cooling yield grain structures withstand contact stresses above 1,500 MPa. Australia's Pilbara iron ore network and Brazil's Carajás corridor qualify these for 40-tonne axle loads.
By volume, solid wheels lead. By growth pace, composite configurations are expanding most quickly.
Material:
Cost tier stratification separates commodity steel from performance-optimized alloys, with premium grades commanding three-to-five-year certification documentation packages.
- Steel:Pearlitic and bainitic grades dominate freight and high-speed segments, with alloy chemistry controlled from melt through heat treatment. Vacuum-degassed production at integrated mills filters out merchant suppliers.
- Aluminum:Lightweight alloys capture urban transit share where acceleration performance outweighs wear-life metrics. Metro operators in noise-regulated jurisdictions specify these for unsprung mass reduction.
- Iron:Gray and ductile iron variants serve niche industrial applications with moderate duty cycles. Foundry economics favor short-run production for specialized rolling stock.
- Other Alloys:Nickel-chromium and manganese-molybdenum blends address extreme temperature or corrosion environments. Arctic freight corridors and coastal humidity zones drive specification.
Steel commands absolute volume leadership. Aluminum alloys are climbing the fastest as metro fleet electrification accelerates.
End User:
Customer type determines contract structure, with freight operators consolidating procurement through direct foundry relationships while passenger services retain OEM-mediated supply chains.
- Freight Operators:Class I railroads and corridor authorities are unbundling wheel-set replacement from rolling-stock maintenance contracts. North American operators with centralized fleet analytics now contract directly for condition-based scheduling.
- Passenger Services:High-speed and intercity operators maintain zero-failure tolerance regimes with intensive documentation requirements. EU MDR and CE marking frameworks extend quality-assurance obligations to imported wheels.
- Infrastructure Providers:Track authorities and leasing companies manage wheel-set pools across multiple operator fleets. Replacement economics hinge on ultrasonic inspection intervals mandated by national safety bodies.
- OEMs:Rolling-stock manufacturers integrate wheel supply into new-build contracts, with specification authority shifting toward operator customers in aftermarket cycles.
Freight operators dominate absolute demand. Infrastructure providers are gaining share fastest as asset-light operating models spread.
Application:
Application context dictates performance thresholds, with high-speed and heavy-haul segments enforcing the steepest metallurgical qualification barriers.
- High-Speed Rail:Passenger segments above 250 km/h require flawless fatigue resistance across millions of load cycles. European and East Asian networks enforce sequential FRA, EU MDR, and domestic approval processes extending launch cycles 18-24 months.
- Urban Transit:Metro and light-rail systems prioritize noise reduction and acceleration responsiveness. Composite wheel adoption concentrates in Japanese and European noise-regulated jurisdictions.
- Freight Transport:Heavy-haul iron ore and coal corridors drive demand for forged and clad configurations at 32.5-tonne and 40-tonne axle loads. India's Eastern and Western DFC routes and China's mineral corridors anchor procurement.
- Specialized Lines:Industrial, mining, and military railways specify custom geometries and alloy grades outside standard catalog offerings. Batch sizes remain small but margins compensate for engineering overhead.
Freight transport leads by installed base. Urban transit shows the steepest expansion trajectory as metro network buildouts accelerate across Southeast Asia and the Middle East.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight operators with centralized fleet analytics now dominate procurement decisions across major rail corridors. China's Belt-and-Rail infrastructure and India's Dedicated Freight Corridor network concentrate heavy-haul axle-load upgrades. European metro authorities drive composite wheel specifications for noise-regulated urban transit.
China
The Eastern and Western corridors of the Belt-and-Rail initiative generate concentrated demand for 32.5-tonne and 40-tonne axle-load wheel sets. NMPA-aligned GB standards enforce fatigue-testing protocols that filter procurement toward integrated steel complexes. Baotou and Wuhan steel clusters supply clad and forged configurations for mineral transport routes.
India
RDSO specifications for the Eastern and Western Dedicated Freight Corridors mandate upgraded wheel metallurgy for 32.5-tonne axle loads. The Ministry of Railways directs procurement toward domestic steel producers with vacuum-degassing capacity. Jamshedpur and Bhilai industrial zones anchor forged wheel production for heavy-haul coal and iron ore trains.
United States
Class I railroads unbundle wheel-set replacement from traditional rolling-stock maintenance contracts through direct foundry relationships. The Federal Railroad Administration mandates ultrasonic inspection intervals that shape replacement economics. Chicago and Omaha logistics clusters concentrate fleet analytics capabilities enabling condition-based scheduling.
Germany
High-speed passenger operators enforce zero-failure tolerance regimes with intensive documentation requirements under EU MDR and CE marking frameworks. The EU Green Deal procurement directives favor suppliers with verified Scope 3 emissions data. Ruhr industrial heritage zones host integrated mills piloting hydrogen-reduction steelmaking for rail applications.
Japan
Metro operators in Tokyo and Osaka specify aluminum-steel composite wheels to reduce unsprung mass below noise-regulated thresholds. METI guidelines accelerate fleet electrification programs demanding acceleration-optimized wheel configurations. Nagoya and Kitakyushu manufacturing clusters supply hybrid wheel technologies for urban transit systems.
Rail Wheel Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply configurations. Integrated steel complexes with captive melt supply dominate high-axle-load segments, while merchant foundries serve standard-duty replacement cycles. Three archetypes define positioning: metallurgy-integrated mills controlling alloy chemistry from ore to finished wheel, precision-forging specialists delivering grain-structured fatigue resistance, and composite-technology developers bonding dissimilar materials for mass-sensitive applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers secure certification across multiple national rail safety bodies.
Among integrated steelmakers, Nippon Steel Corporation and ArcelorMittal occupy positions defined by backward control over raw material inputs and heat-treatment infrastructure. EVRAZ Plc represents the specialized forging tier with radial forming capabilities for extreme axle-load environments. Amsted Rail Company Inc. anchors the North American service-intensive segment through proximity to Class I railroad maintenance networks. These three exemplify how geographic concentration of steelmaking assets and regulatory certification depth determine competitive access to premium procurement channels.
| Leading Market Players |
|---|
| Alstom SA |
| Nippon Steel Corporation |
| Amsted Rail Company Inc. |
| EVRAZ Plc |
| Lucchini RS |
| ArcelorMittal |
| Bharat Forge Limited |
| Wabtec Corporation |
| CRRC Corporation |
| Others |
Cost & Logistics Intelligence
Undercapacity in European vacuum-degassing foundries is compressing lead times for high-axle-load wheel sets and shifting procurement power toward integrated steel complexes with captive melt supply. This utilization squeeze simultaneously inflates alloy-grade premiums and accelerates buyer migration toward long-term offtake contracts that lock in volume allocation.
Pricing Analysis
Cost-plus contracts indexed to shredded auto scrap and ferrochrome benchmarks dominate procurement for forged and clad wheel configurations. Three-tier pricing structure across premium forged, standard cast, and economy solid-wheel levels separates suppliers by certification depth and fatigue-test documentation. Pricing pressure stems from scrap steel volatility forcing foundries to absorb margin compression or renegotiate indexation clauses. Freight operators with centralized fleet analytics exhibit lowest price sensitivity due to condition-based replacement economics, while infrastructure providers managing pooled wheel sets remain most cost-conscious.
Supply Chain Analysis
Contract manufacturing concentrates among integrated steel complexes in China, India, and Russia with captive vacuum-degassing and radial forging capacity. Raw material sourcing draws from electric-arc furnace scrap networks, ferroalloy processors, and specialty steel billet suppliers. Single-source vulnerability pervades the 40-tonne axle-load segment where fewer than six foundries worldwide hold qualified metallurgical process control. Distribution runs through direct foundry relationships with Class I railroads and corridor authorities, bypassing traditional OEM service networks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail wheel incumbents face substitution pressure from composite aluminum-steel configurations in urban transit, requiring defensive metallurgical investment to preserve freight and high-speed dominance.
For Market Incumbents: Entrench forged-wheel leadership through backward integration into vacuum-degassing capacity and radial forging infrastructure. Deepen certification moats by accelerating sequential FRA, EU MDR, and RDSO approval timelines before composite technologies achieve heavy-haul fatigue parity. Prioritize captive scrap supply agreements to insulate margin structures from shredded auto steel volatility. For New Entrants and Emerging Players: Southeast Asian freight corridors lacking established wheel supply chains represent the most penetrable entry point for producers with ASEAN certification pathways. Indonesia's Trans-Sumatra and Malaysia's East Coast Rail Link projects offer first-mover positioning for clad wheel technologies that bridge cast economics and forged performance. Target predictive maintenance integration as a recurring revenue wedge that separates hardware commoditization from service differentiation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogen-reduction steelmaking pilot programs serving EU Green Deal procurement mandates. Five-to-ten-year viability favors integrated mills with verified Scope 3 emissions data and backward control from ore to finished wheel. Monitor EU sustainable procurement directive enforcement as the signal indicating which suppliers secure premium channel access versus margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Degassing | Nippon Steel and ArcelorMittal control alloy chemistry from melt through heat treatment, filtering out merchant competitors. |
| Sequential Multi-Jurisdiction Certification | FRA, EU MDR, and RDSO approvals extend product launch cycles, concentrating procurement among documentation-capable suppliers. |
| Predictive Maintenance Platform Integration | Wheel-mounted acoustic sensors enable real-time crack detection, opening recurring revenue beyond hardware sales. |
| Hydrogen-Reduction Steelmaking Pilot | Ruhr industrial zones pilot green steel production, aligning with EU Green Deal procurement mandates for Scope 3 verification. |
| Clad Wheel Technology Qualification | Australia's Pilbara and Brazil's Carajás corridors validate hybrid configurations for 40-tonne axle loads, displacing pure forged economics. |
Research Approach
Operator-level perspectives from freight procurement directors, rolling-stock maintenance chiefs, foundry metallurgical engineers, and rail safety regulator technical staff anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs trade records, Association of American Railroads equipment statistics, EU MDR certification databases, and SEC filings from listed steel producers. Bottom-up volume modeling triangulated against top-down corridor investment forecasts to converge on segment-level projections.
Scenario-bracketing framed the analytical approach across the projection horizon, with low-case assumptions reflecting scrap price volatility and high-case assumptions incorporating accelerated composite wheel penetration. Segmentation dimensions modeled include manufacturing route, material grade, end-user type, and application context alongside axle-load tier as the industry-specific stratifier. CAGRs derived from fitted growth curves applied to replacement cycle economics and fleet expansion pipelines.
Practitioners should monitor GB standard escalation timelines, RDSO specification revisions, and EU Green Deal enforcement intensity for early signals requiring forecast adjustment. Cross-checking against railway equipment association shipment data and national rail safety body certification disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Piston Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Locomotive Drive Shaft Market