
 Vehicle Exhaust Hose Market | 2026-2036
Vehicle Exhaust Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Exhaust Hose Market Analytics
ISO 9001 quality management certification is bifurcating the competitive landscape between qualified system suppliers and unqualified regional fabricators. Nederman Holding AB leverages its captive extraction system integration to command premium positioning in European workshop chains. Masterflex SE anchors its position through deep specialization in thermoplastic elastomer formulations for temperature-critical segments. Dayco LLC competes via extensive OEM channel control and backward integration into rubber compounding operations.
A vehicle exhaust hose is a flexible or semi-rigid conduit, typically constructed from stainless steel wire reinforcement, silicone rubber layers, or composite textile substrates, engineered to channel hot toxic gases from internal combustion engines to external ventilation or aftertreatment systems while withstanding continuous operating temperatures exceeding 300°C. Its primary industrial purpose centers on protecting technician health in enclosed service bays and ensuring regulatory compliance with occupational exposure thresholds for carbon monoxide and diesel particulate matter. Flexible hoses capture the dominant share of aftermarket demand due to universal fitment adaptability across mixed fleets, while silicone-based constructions represent the fastest-expanding material category as thermal performance requirements escalate under modern low-NOx engine calibrations. OEM procurement concentrates on corrugated stainless assemblies for original fitment durability, leaving margin-rich custom fabrication opportunities to specialized aftermarket providers serving retrofit and off-road conversion applications.
The EPA enforces emission compliance timelines that mandate periodic exhaust system integrity verification, directly sustaining replacement hose demand across regulated vehicle classes. OSHA workplace ventilation standards govern permissible exposure limits in maintenance facilities, compelling fleet operators and repair shops to invest in engineered extraction hose assemblies rather than improvised solutions. California Air Resources Board protocols extend these requirements with supplementary testing burdens for heavy-duty diesel populations. Stakeholders must monitor evolving material restrictions under REACH and state-level chemical disclosure rules while calibrating inventory depth against cyclical commercial vehicle utilization patterns.
Market Dynamics
EPA tailpipe emission standards and OSHA workplace exposure limits are tightening material specifications and fitment requirements simultaneously, forcing fleet operators and service chains to accelerate replacement cycles rather than defer maintenance.
Growth Catalysts
- State-Level Inspection Mandates:California Air Resources Board protocols and comparable state programs in Texas and New York enforce periodic exhaust system integrity verification, sustaining aftermarket pull for compliant hose assemblies.
- Fleet Electrification Lag:Commercial vehicle parc density in the United States continues expanding diesel and gasoline populations, extending addressable replacement demand through the forecast window.
- Silicone Elastomer Advances:Thermoplastic formulations withstand continuous operating temperatures exceeding 300°C, enabling compliance with modern low-NOx engine calibrations without material degradation.
Market Restraints
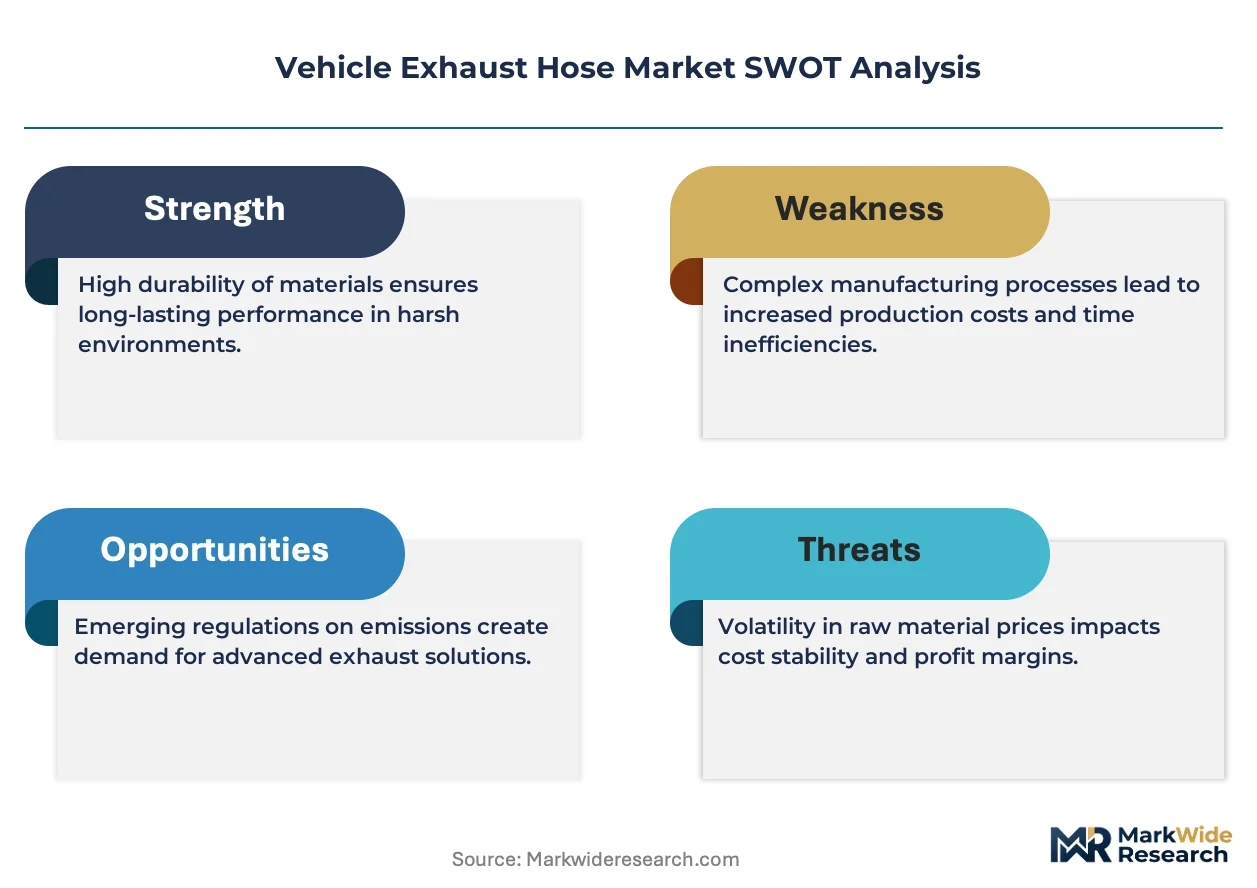
- Specialty Polymer Cost Volatility:Silicone rubber and fluorocarbon compound prices fluctuate with petrochemical feedstock markets, compressing margin stability for fabricators without backward integration.
- European Supply Concentration:REACH-compliant material certification concentrates qualified substrate supply among German and Swedish compounders, creating single-source vulnerability for North American assemblers.
- Electric Vehicle Substitution:Battery-electric commercial vehicle deployments eliminate exhaust infrastructure entirely, eroding long-term addressable market scope in urban delivery segments.
Strategic Opportunities
- Off-Road Conversion Applications:Mining and construction equipment retrofit programs in Australia and Canada require custom-fabricated high-temperature assemblies outside standard OEM specifications.
- Workshop Chain Consolidation:Automotive service chains are centralizing procurement through national distribution agreements, creating volume aggregation points for qualified system suppliers.
- Integration with Captive Extraction Systems:Hose manufacturers can bundle ventilation hardware and ducting into turnkey workshop packages, capturing premium positioning through engineered system sales.
Industry Challenges
- ISO 9001 Certification Timeline:Regional fabricators face 12-18 month quality management system implementation periods to qualify for automotive service chain vendor lists, delaying market access.
- Legacy Fleet Compatibility:Mixed-age commercial vehicle populations require inventory depth across corrugated stainless, textile-reinforced, and silicone constructions, straining working capital for distributors.
- Material Disclosure Compliance:State-level chemical reporting rules in California and emerging jurisdictions demand supply chain documentation burdens that smaller fabricators lack systems to satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Exhaust Hose Market |
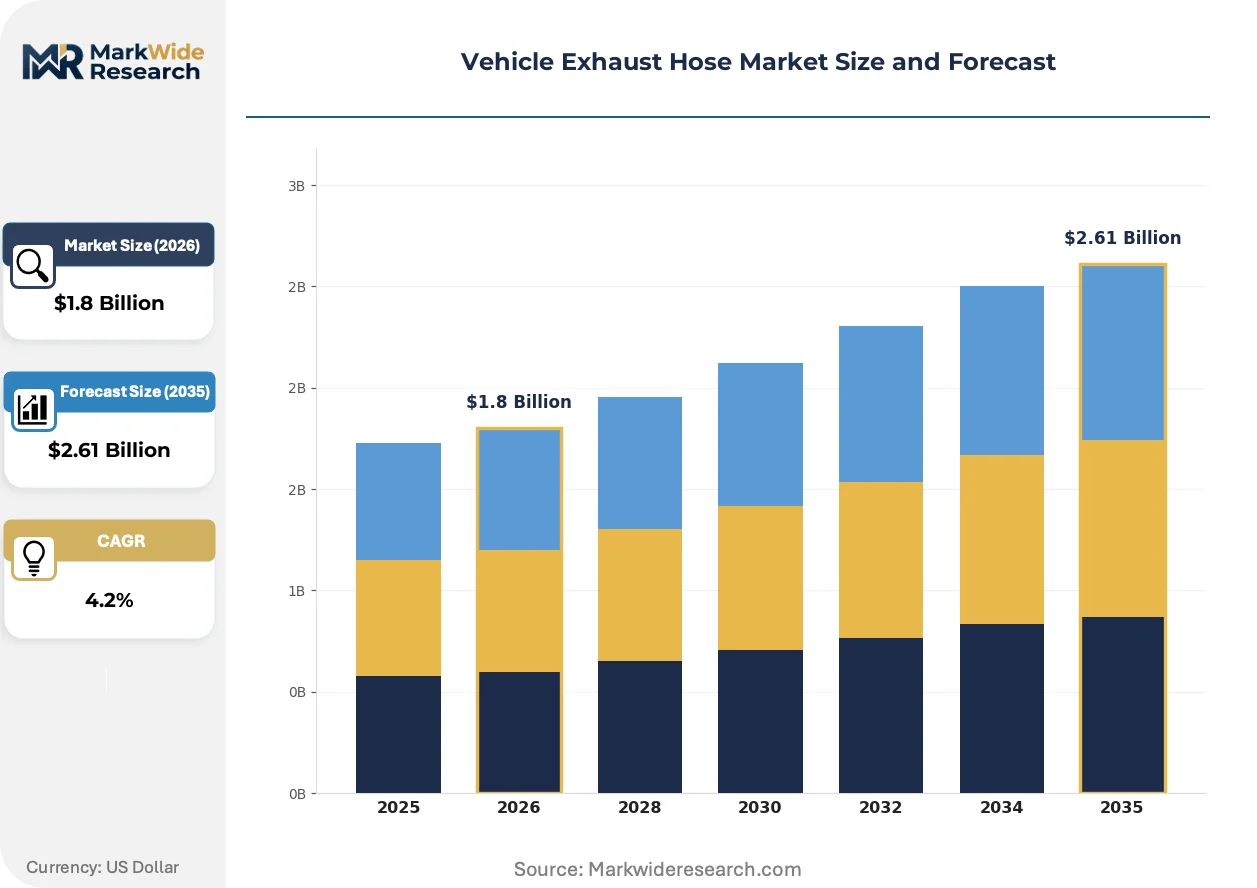
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Hoses, Rigid Hoses, Corrugated Hoses, Custom Hoses Material: Stainless Steel, Rubber, Silicone, Composite End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles |
| Companies Covered | Nederman Holding AB, Masterflex SE, Air Cleaning Specialists, Inc., Novaflex Group, Flexaust Inc., Eurovac, Precision Hose & Expansion Joints, BISCO Enterprise, Inc., Dayco LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Exhaust Hose Market Evolving Landscape
Material science advances and regulatory stringency are restructuring competitive advantage around thermal performance certification and integrated system design rather than commodity hose fabrication.
Silicone-based hose constructions are bifurcating the aftermarket between temperature-rated premium assemblies and commodity textile-reinforced alternatives. Fleet maintenance depots operating modern low-NOx diesel populations specify silicone formulations exclusively, while price-sensitive independent shops continue sourcing multi-layer fabric hoses for older vehicle populations. This material divide is bifurcating distributor inventory strategies and compressing margin recovery for undifferentiated fabricators.
OSHA workplace ventilation standards are tightening permissible exposure limits for carbon monoxide and diesel particulate matter in enclosed service bays. The industrial consequence mandates engineered extraction hose assemblies with verified flow rates and leak-tight connections, displacing improvised shop-fabricated solutions. Heavy-duty diesel populations in United States fleet maintenance facilities face the most acute compliance pressure, driving specification upgrades to stainless-corrugated and silicone-lined constructions.
Automotive service chains are consolidating procurement through national distribution agreements with qualified system suppliers. Independent distributors and jobber networks are losing share to direct vendor-managed inventory programs at workshop chains, compressing traditional aftermarket channel margins. This concentration is most visible in United States commercial vehicle service networks, where national accounts now specify hose assemblies as part of integrated extraction system packages rather than standalone commodity purchases.
Vehicle Exhaust Hose Market Segmentation
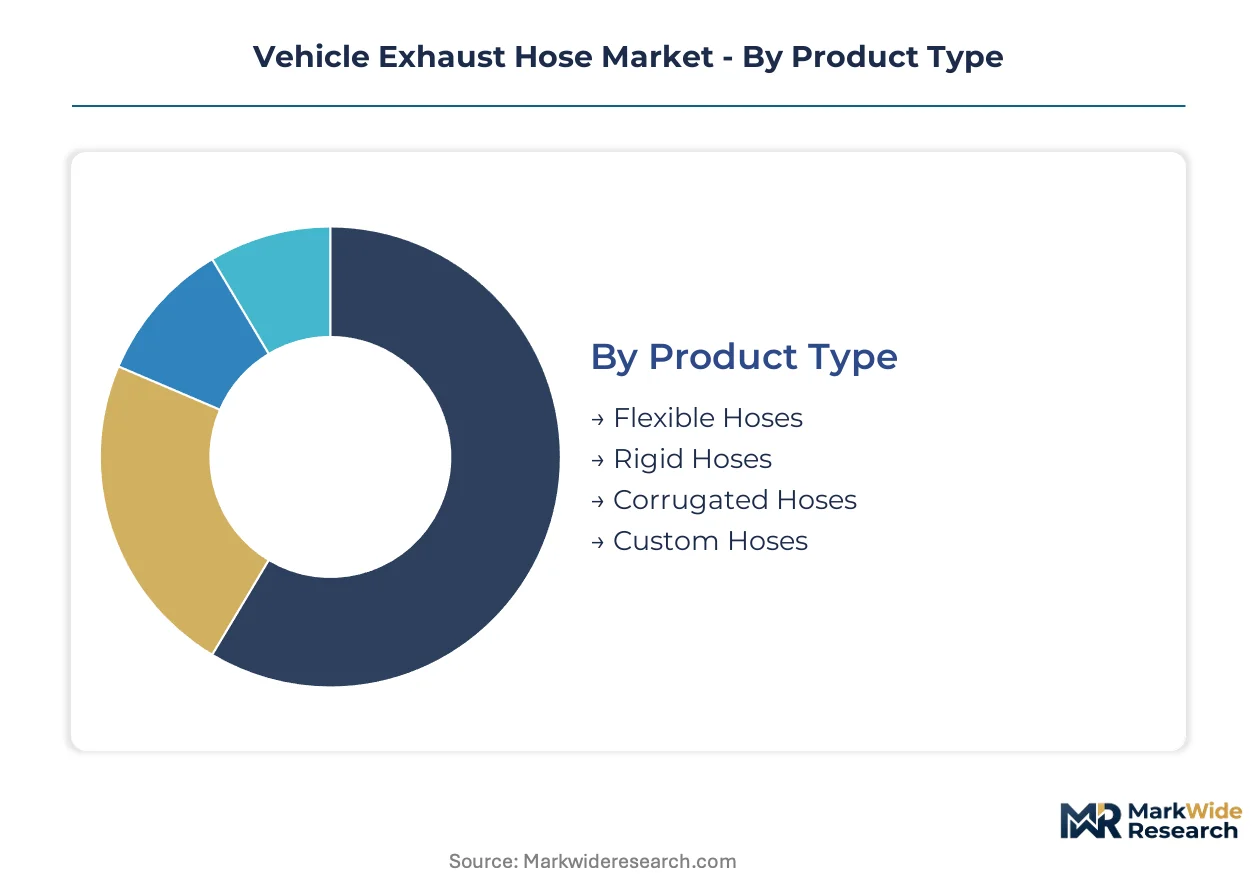
Vehicle exhaust hose procurement splits across incompatible technical specifications, forcing suppliers to maintain parallel production lines. Fleet operators and service chains select segments based on thermal rating mandates and vehicle parc composition rather than interchangeability.
Product Type:
OSHA workplace ventilation standards differentiate permissible hose constructions by verified flow rates and leak-tight connection requirements, elevating certified assemblies over improvised alternatives.
- Flexible Hoses:Multi-layer fabric or elastomeric constructions with wire reinforcement enable universal fitment across mixed fleet populations. Demand concentrates in United States independent repair shops serving aging commercial vehicle parcs where adaptability outweighs thermal performance. Fleet maintenance depots specify these for light-duty applications below 250°C continuous operation.
- Corrugated Hoses:Stainless steel interlock or convolute profiles withstand sustained temperatures exceeding 500°C without material degradation. Heavy-duty diesel populations in California CARB-regulated jurisdictions mandate these for low-NOx engine calibrations. OEM original fitment and retrofit compliance programs sustain premium pricing.
- Rigid Hoses:Fixed-diameter metallic or composite tubes serve permanent installation points in centralized extraction systems.
- Custom Hoses:Fabricated-to-specification assemblies address off-road conversion and non-standard equipment geometries outside OEM catalogs.
Established volume favors flexible configurations; emerging adoption favors corrugated stainless assemblies.
Material:
Cost tier stratification separates commodity substrates from temperature-rated premium compounds, with thermal certification determining qualification for automotive service chain vendor lists.
- Silicone:Thermoset elastomer formulations withstand continuous 300°C operation while maintaining flexibility across thermal cycling. Modern low-NOx diesel calibrations in United States fleet depots specify silicone exclusively for exhaust gas recirculation proximity. REACH-compliant compound certification limits qualified supply to German and Swedish compounders.
- Stainless Steel:Austenitic grades 304 and 316 provide oxidation resistance and structural integrity for corrugated and rigid constructions. Mining equipment retrofit programs in Australia and Canada require custom-fabricated high-temperature assemblies utilizing these substrates.
- Rubber:EPDM and NBR compounds serve cost-sensitive replacement demand in older vehicle populations with moderate thermal exposure.
- Composite:Textile-reinforced elastomeric laminates balance flexibility and cost for general service applications.
Procurement volume concentrates in silicone for temperature-critical segments; margin recovery favors stainless steel in custom fabrication.
End User:
Customer type dictates specification authority and procurement channel, with national accounts displacing traditional distribution for consolidated service chains.
- Aftermarket Providers:Specialized fabricators and distributors serve retrofit, replacement, and off-road conversion demand outside OEM captive supply. United States commercial vehicle service networks specify hose assemblies through vendor-managed inventory programs rather than spot purchases. ISO 9001 certification qualifies suppliers for automotive service chain procurement.
- Fleet Operators:National and regional commercial vehicle fleets centralize maintenance through dedicated facilities with standardized extraction infrastructure. OSHA workplace exposure compliance mandates engineered hose assemblies with verified performance documentation.
- OEMs:Original equipment manufacturers specify corrugated stainless assemblies for factory fitment durability.
- Repair Shops:Independent facilities source flexible hoses through jobber networks for immediate replacement demand.
Procurement consolidation favors fleet operators; specification fragmentation sustains aftermarket provider relevance.
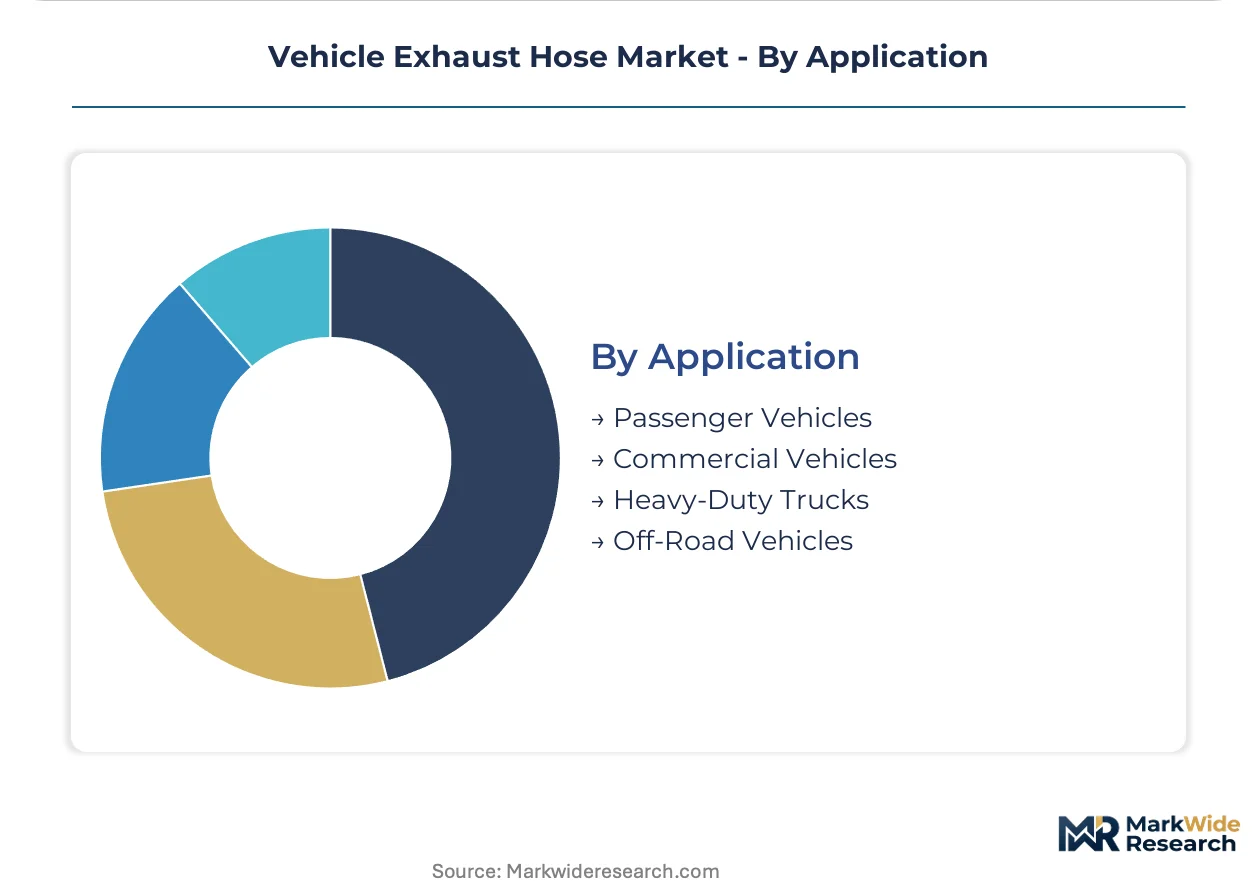
Application:
Vehicle duty cycle and operating environment determine thermal load and regulatory exposure, segmenting demand by compliance intensity.
- Heavy-Duty Trucks:Class 8 diesel populations face the most acute EPA tailpipe emission and OSHA workplace ventilation compliance pressure. California CARB protocols and comparable state programs enforce periodic exhaust system integrity verification. Fleet maintenance depots specify silicone-lined or stainless-corrugated constructions exclusively.
- Commercial Vehicles:Medium-duty diesel and gasoline populations in United States urban delivery segments sustain replacement demand through inspection mandates. Electrification lag extends addressable market scope for exhaust infrastructure.
- Passenger Vehicles:Light-duty applications utilize flexible textile-reinforced hoses for standard service intervals.
- Off-Road Vehicles:Mining and construction equipment retrofit programs require custom-fabricated assemblies outside standard specifications.
Regulatory stringency elevates heavy-duty truck specifications; electrification erosion threatens commercial vehicle segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American commercial vehicle throughput, sustaining dense fleet maintenance infrastructure that drives exhaust hose replacement demand across the continent.
United States
California Air Resources Board protocols enforce periodic exhaust system integrity verification for heavy-duty diesel populations. OSHA workplace ventilation standards mandate engineered extraction hose assemblies with verified flow rates in enclosed service bays. Fleet maintenance depots in Texas and the Midwest concentrate procurement through national distribution agreements.
Germany
REACH-compliant material certification concentrates qualified silicone compound supply among domestic and Swedish suppliers. KBA vehicle inspection mandates sustain aftermarket pull for temperature-rated premium assemblies. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialized fabricators serving European workshop chains.
China
MIIT emission standards for commercial vehicles tighten fitment requirements for domestic fleet operators. GB standards govern workplace ventilation in maintenance facilities across major logistics corridors. Manufacturing concentration in the Yangtze River Delta supplies both domestic aftermarket and export demand for textile-reinforced constructions.
Canada
Health Canada and provincial workplace safety regulators enforce exposure limits for diesel particulate matter in fleet maintenance facilities. Mining equipment retrofit programs in Alberta and British Columbia require custom-fabricated high-temperature assemblies. Cross-border supply chains integrate Canadian distributors with United States national account programs.
Australia
State-level mining safety regulations in Queensland and Western Australia mandate engineered exhaust extraction for underground equipment maintenance. TGA-aligned workplace exposure frameworks govern permissible limits in enclosed service environments. Perth and Brisbane clusters concentrate aftermarket demand for off-road conversion applications.
Vehicle Exhaust Hose Market Competitive Landscape
Listed leaders compete with private specialists across material certification and system integration capabilities. The vendor base separates into ISO 9001-qualified system suppliers and unqualified regional fabricators, with quality management certification now gating access to automotive service chain procurement. Three archetypes dominate: captive extraction system integrators bundling ventilation hardware; thermoplastic elastomer specialists commanding temperature-critical segments; and rubber compounders leveraging backward integration into substrate production. Competitive moves center on vendor-managed inventory programs and geographic expansion into mining retrofit markets.
Among European-listed entities, Nederman Holding AB and Masterflex SE exemplify divergent positioning archetypes. Nederman represents the captive system integration model, while Masterflex occupies the deep specialization tier in high-performance elastomer formulations. Dayco LLC anchors the North American premium tier through rubber compounding integration. These three entities collectively illustrate how quality certification and material control separate qualified suppliers from commodity fabricators.
| Leading Market Players |
|---|
| Nederman Holding AB |
| Masterflex SE |
| Air Cleaning Specialists, Inc. |
| Novaflex Group |
| Flexaust Inc. |
| Eurovac |
| Precision Hose & Expansion Joints |
| BISCO Enterprise, Inc. |
| Dayco LLC |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German silicone compounders and United States fleet maintenance depots lock in both REACH-compliant material access and price visibility across multi-year replacement cycles. These contracts insulate qualified suppliers from petrochemical feedstock volatility while compressing margin recovery for spot-market purchasers.
Pricing Analysis
Volume-discount tiering structures separate automotive service chain national accounts from independent repair shop spot purchases. Three-tier pricing stratifies across ISO 9001-certified premium assemblies, standard silicone constructions, and economy textile-reinforced alternatives. Cost compression in the economy tier intensifies because unqualified regional fabricators compete on material substitution. Fleet operators demonstrate the least price sensitivity due to OSHA compliance mandates, while independent shops exhibit acute sensitivity to per-unit replacement costs.
Supply Chain Analysis
Just-in-time inventory strategies dominate United States distributor networks serving mixed-age commercial vehicle parcs, while strategic stockpiling of REACH-certified silicone prevails among German and Swedish compounders. Raw material procurement draws from German petrochemical feedstocks, Chinese textile substrates, and Swedish specialty elastomer formulations. Single-source vulnerability concentrates in REACH-compliant silicone supply, with distribution running through national account programs at automotive service chains rather than traditional jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor-managed inventory programs and extraction system integration services expand addressable revenue per customer faster than standalone hose hardware, transforming procurement relationships into recurring service attachments.
For Market Incumbents: Compound defensive positioning through backward integration into silicone compounding operations and captive supply of REACH-certified substrates. Electric vehicle substitution threatens long-term addressable scope in urban delivery segments, requiring incumbents to anchor revenue in off-road conversion and mining retrofit applications. ISO 9001 certification investment remains essential for automotive service chain vendor list retention. For New Entrants and Emerging Players: ISO 9001 certification fast-tracks unlock procurement access to automotive service chains within 12-18 month implementation windows. White-space targets concentrate in Australian mining equipment retrofit programs and Canadian provincial fleet maintenance depots requiring custom-fabricated assemblies. Go-to-market execution should prioritize direct technical sales to mine operators rather than distributor channel penetration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive silicone formulation capabilities and existing automotive service chain contracts. Long-term viability hinges on thermal performance certification moats rather than commodity fabrication scale. The signal to watch is battery-electric commercial vehicle deployment rates in urban delivery segments as inflection indicator for exhaust infrastructure demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive supply of REACH-certified substrates insulates margin from petrochemical volatility. |
| Vendor-Managed Inventory Programs | National account penetration at automotive service chains displaces traditional distributor channels. |
| Extraction System Integration | OSHA compliance mandates bundle ventilation hardware with hose assemblies at premium positioning. |
| Off-Road Custom Fabrication Capability | Mining retrofit programs in Australia and Canada require non-standard geometries outside OEM catalogs. |
| ISO 9001 Certification Investment | Quality management certification gates access to automotive service chain procurement lists. |
Research Methodology
A standing panel of fleet maintenance directors, automotive service chain procurement officers, silicone compounder technical leads, and OSHA compliance consultants provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews combined with trade customs data, EPA enforcement disclosure records, REACH registration databases, and automotive aftermarket distributor financial filings. Bottom-up unit demand modeling and top-down value chain triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-user archetype, and vehicle application class. CAGRs derived from fitted growth curves applied to replacement cycle frequencies and fleet parc expansion trajectories. Industry-specific inputs incorporated EPA tailpipe emission compliance timelines and OSHA workplace ventilation standard revision schedules.
The analysis sits within stated boundaries; outcomes outside sustained commercial vehicle diesel population levels or accelerated battery-electric substitution would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and material certification continuity. Revision becomes warranted when electric vehicle commercial deployment crosses critical thresholds in urban delivery segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Wheel Seals Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Air Suspension Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Gas-Powered Chainsaw Market