
 Air Ride Suspension Systems Market | 2026-2036
Air Ride Suspension Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Ride Suspension Systems Market Analytics
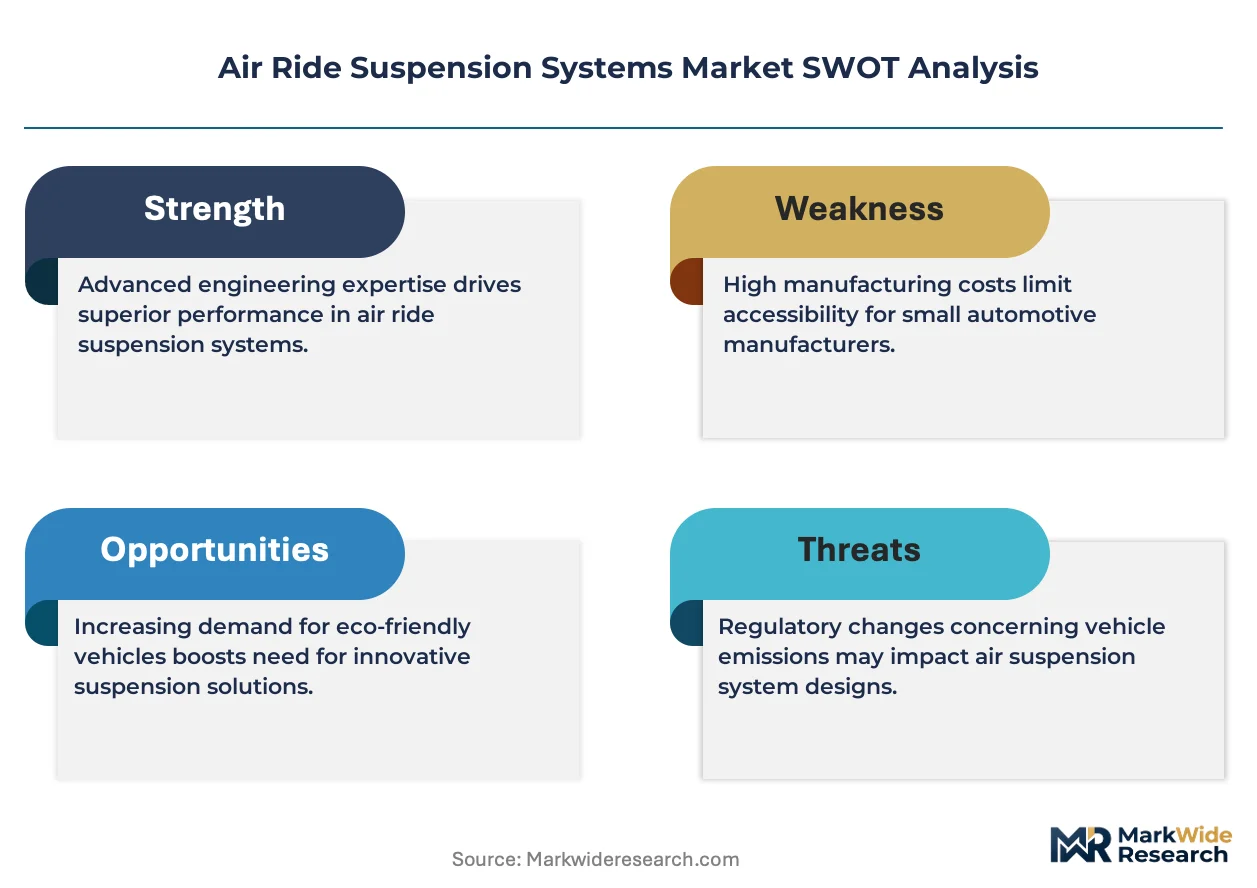
Skilled technician availability for electronic control calibration is collapsing across supplier networks, creating bottlenecks for OEM installation ramp-ups. Continental AG leverages its integrated sensor-actuator platforms to capture premium fleet contracts. ZF Friedrichshafen AG anchors European heavy-duty production through captive air spring manufacturing. Hendrickson International Corporation specializes in trailer suspension configurations for North American long-haul operators.
Air ride suspension systems employ pressurized elastomeric bellows or sleeve-style air springs paired with height control valves to maintain chassis elevation under variable loads, typically operating at pressures between 80 and 150 psi depending on axle rating and vehicle class. Electronic Control technology leads value contribution as fleets prioritize real-time damping adjustment and predictive maintenance integration. Heavy-Duty applications sustain margin concentration due to severe-duty cycle requirements and replacement part predictability. The Aftermarket channel competes aggressively on service network density for aging commercial truck parc renewal.
EPA greenhouse gas standards for medium and heavy-duty vehicles, NHTSA Federal Motor Vehicle Safety Standards for brake and suspension performance, and ISO 9001 quality management certifications collectively shape product validation timelines and material specifications for market entry. ECE R13 braking and stability regulations in Europe enforce dual-circuit air supply redundancy that elevates system complexity for exporters. Stakeholders must monitor electrified chassis architectures and autonomous vehicle readiness levels to anticipate how air suspension control logic will integrate with centralized vehicle dynamics computers.
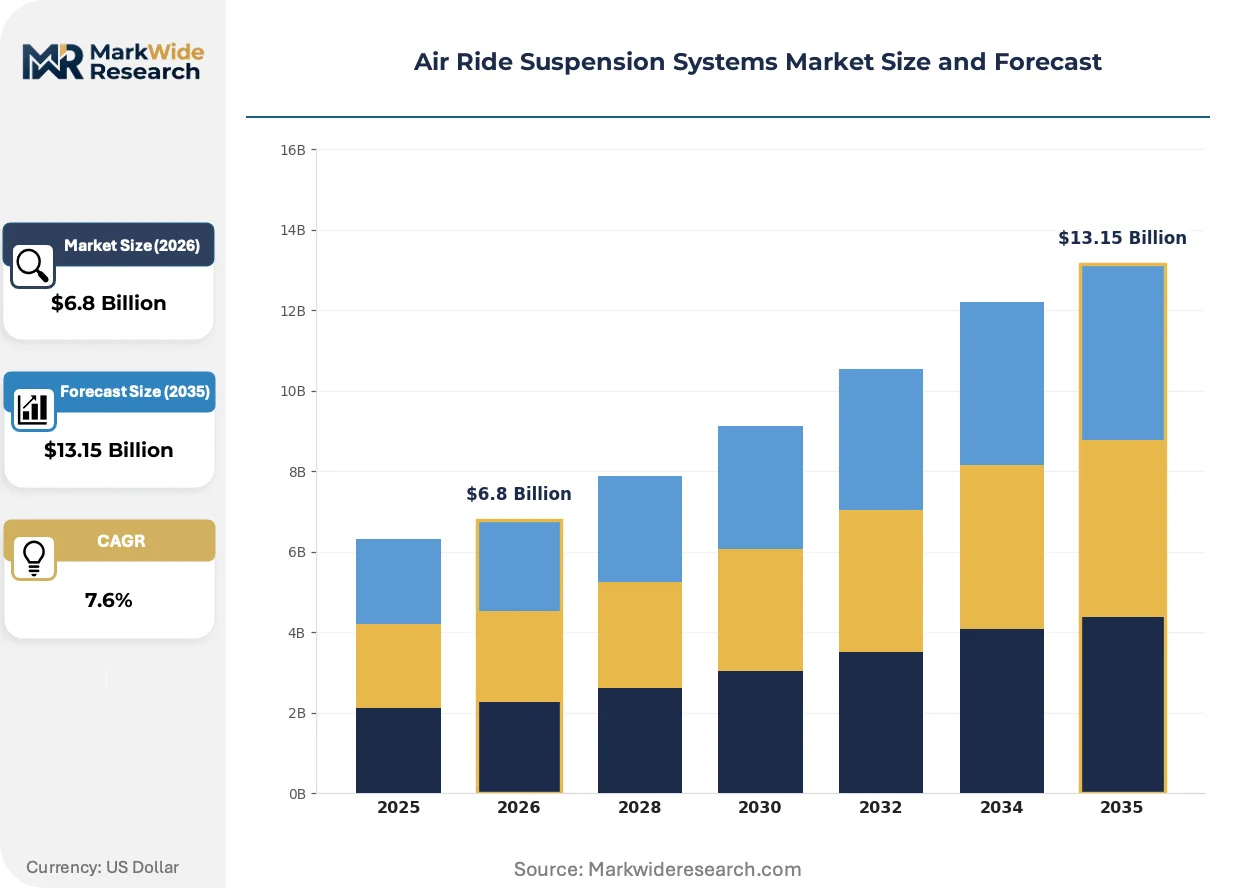
Market Dynamics
Electronically controlled air suspension is compressing replacement cycles for mechanical spring systems across heavy-duty commercial vehicle fleets, driven by predictive maintenance integration and real-time damping adjustment capabilities that reduce unplanned downtime costs.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Fleet operators in the United States are retrofitting existing tractor-trailers with lightweight air spring technologies to comply with stricter emissions benchmarks for medium and heavy-duty vehicles.
- Predictive maintenance integration:Sensor-embedded air suspension modules enable condition-based servicing, reducing total cost of ownership for long-haul operators managing thousand-vehicle parcs.
- China commercial vehicle production clusters:Dense OEM assembly networks in Shandong and Hubei provinces generate concentrated demand for regional air spring component suppliers.
Market Restraints
- Natural rubber and synthetic elastomer price volatility:Air spring bellows production depends on petroleum-derived compounds and natural rubber supply concentrated in Southeast Asian plantation regions.
- Skilled technician scarcity:Electronic control calibration requires specialized training that supplier networks struggle to scale, creating installation bottlenecks for OEM ramp-ups.
- Hydraulic suspension substitution in severe mining:Extreme-duty applications in Australian iron ore and Canadian oil sands operations favor hydraulic systems for load-bearing capacity exceeding air spring ratings.
Strategic Opportunities
- Autonomous truck readiness:Centralized vehicle dynamics computers require air suspension control logic integration, creating specification opportunities for chassis-agnostic module suppliers.
- India commercial vehicle aftermarket:Aging truck parc in Maharashtra and Gujarat states lacks dense authorized service networks, opening independent channel expansion for component distributors.
- ECE R13 dual-circuit mandate:European braking and stability regulations enforce redundant air supply architectures that elevate system complexity and value capture for compliant exporters.
Industry Challenges
- ISO 9001 validation timeline compression:Quality management certification requirements extend product development cycles as OEMs demand simultaneous compliance with NHTSA safety standards.
- Legacy mechanical suspension integration:Mixed fleet operators face interoperability challenges when retrofitting electronic air ride systems onto chassis originally specified for steel springs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Ride Suspension Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Light-Duty, Commercial, Performance Technology: Electronic Control, Pneumatic, Mechanical, Hybrid End User: OEMs, Aftermarket, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Trucks, Buses, Luxury Vehicles |
| Companies Covered | Continental AG, ZF Friedrichshafen AG, ThyssenKrupp AG, SAF-Holland, Hendrickson International Corporation, Firestone Industrial Products, Hitachi Ltd., Mando Corporation, AccuAir Suspension, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Ride Suspension Systems Market Evolving Landscape
Three distinct vectors are restructuring competitive positioning in air ride suspension: predictive sensor integration, regulatory-driven lightweighting mandates, and fleet procurement centralization around total cost of ownership metrics.
Smart air spring modules incorporating accelerometer and pressure transducer arrays are supplanting passive height control valves in premium fleet specifications. North American long-haul operators with thousand-vehicle parcs are adopting these systems fastest. Real-time damping adjustment is compressing maintenance intervals and shifting supplier value capture toward software-enabled service contracts.
REACH substance restrictions in Europe are accelerating fluoropolymer displacement in air spring membrane formulations. Compound suppliers are reformulating elastomer blends to eliminate perfluorinated substances while maintaining pressure ratings above 120 psi. German heavy-duty OEMs are qualifying alternative membrane materials ahead of regulatory deadlines, compressing validation timelines for tier-two component manufacturers.
Fleet procurement departments are consolidating supplier relationships around integrated chassis-axle-suspension packages. Large operators in the United States are bypassing traditional distribution channels to negotiate direct OEM contracts. This concentration is visible most acutely in dedicated contract carriage segments where specification standardization across regional terminals reduces parts inventory complexity.
Air Ride Suspension Systems Market Segmentation
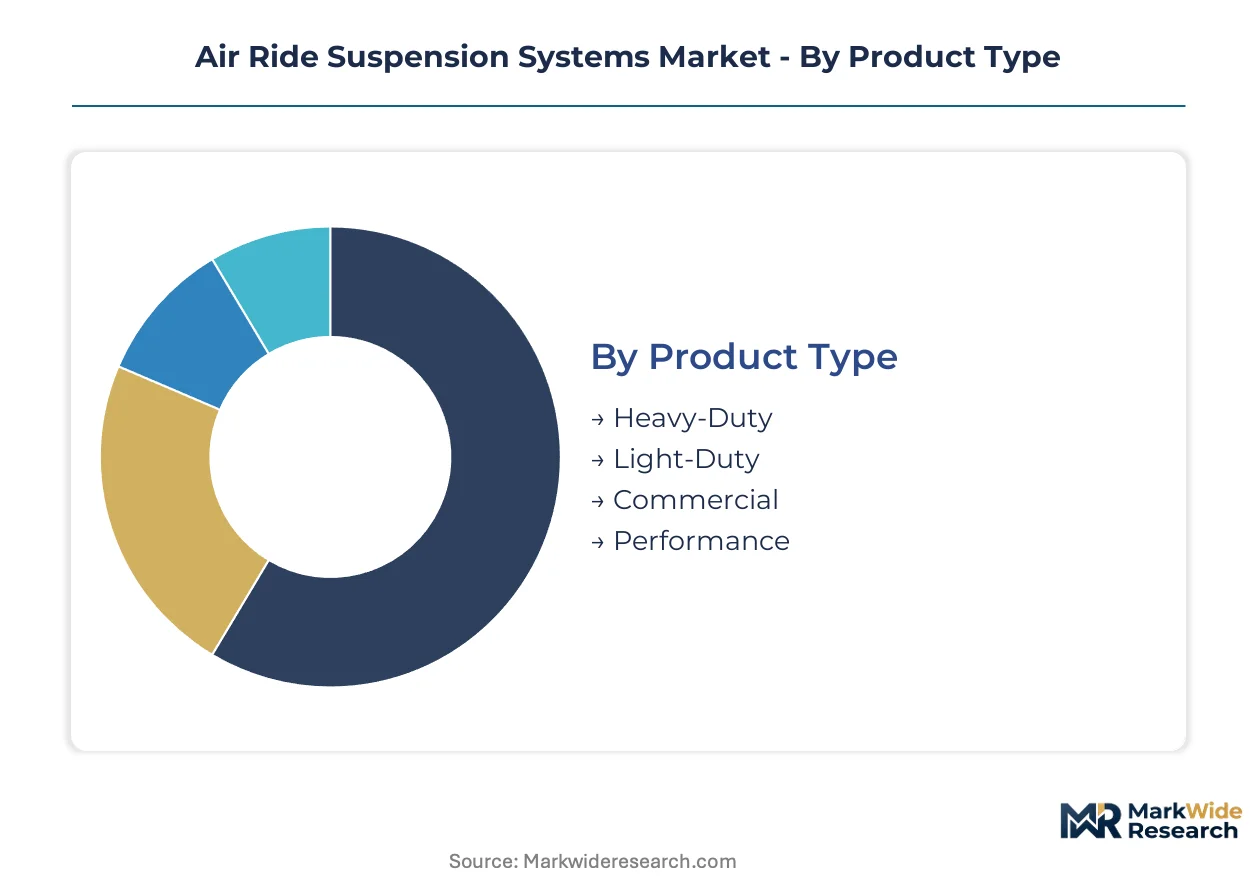
Segmentation in air ride suspension systems reveals how technology tiers, duty cycles, and procurement channels split value capture across supplier networks. Understanding these divides exposes where electronic integration commands premium pricing versus where mechanical systems retain cost-driven replacement demand.
Product Type:
Heavy-Duty and Commercial segments concentrate in domestic fleet procurement within the United States, Germany, and China, while Light-Duty and Performance systems see stronger export-led demand into emerging vehicle assembly markets.
- Heavy-Duty:Severe-duty air springs rated for axle loads exceeding 20,000 lbs employ multi-ply reinforced elastomer bellows with integrated bead rings. Demand clusters around North American long-haul tractor-trailers and European construction truck fleets where replacement predictability sustains aftermarket margins.
- Commercial:Medium-duty configurations for delivery vans and regional haul trucks balance payload capacity with ride quality specifications. Fleet operators in China's Shandong province are expanding adoption fastest as urban logistics electrification demands lighter unsprung mass.
- Light-Duty:Passenger pickup and SUV applications favor sleeve-style air springs for adjustable load leveling.
- Performance:Low-profile air spring modules for sports sedans and tuners prioritize rapid height adjustment response.
Heavy-Duty holds the largest share; momentum sits with Commercial as regional logistics fleets upgrade specifications.
Technology:
Cost tier stratification separates sensor-integrated Electronic Control systems from legacy Pneumatic and Mechanical alternatives, with Hybrid architectures emerging as a mid-tier bridge for mixed fleet retrofits.
- Electronic Control:Real-time damping algorithms process accelerometer and pressure transducer inputs through centralized chassis controllers. OEMs in Germany are mandating these systems for premium heavy-duty platforms ahead of predictive maintenance integration requirements.
- Pneumatic:Conventional height control valves without electronic feedback dominate price-sensitive replacement demand. The segment retains volume concentration in India's aging truck parc where technician scarcity limits electronic system adoption.
- Mechanical:Passive leaf-spring replacement kits serve legacy chassis with minimal integration complexity.
- Hybrid:Electronically assisted pneumatic systems offer partial upgrade paths for fleets transitioning from mechanical suspensions.
Electronic Control dominates value contribution; Hybrid configurations are climbing the fastest as retrofit demand accelerates.
End User:
Customer type fragmentation shows OEMs and Fleet Operators driving specification innovation, while Aftermarket and Vehicle Assemblers compete on service density and regional assembly proximity respectively.
- Fleet Operators:Thousand-vehicle parc managers in the United States negotiate direct OEM contracts for standardized chassis-axle-suspension packages. Procurement centralization around total cost of ownership metrics compresses supplier margins while locking in multi-year service agreements.
- OEMs:Integrated vehicle manufacturers specify air suspension modules during chassis design for new platform launches. German heavy-duty OEMs are qualifying alternative membrane materials ahead of REACH substance restriction deadlines.
- Aftermarket:Independent distributors compete on service network density for aging commercial truck renewal.
- Vehicle Assemblers:Contract manufacturers in China's Hubei province source regional air spring components for knock-down assembly.
Fleet Operators command specification authority; Aftermarket channels are gaining share fastest in underpenetrated regional markets.
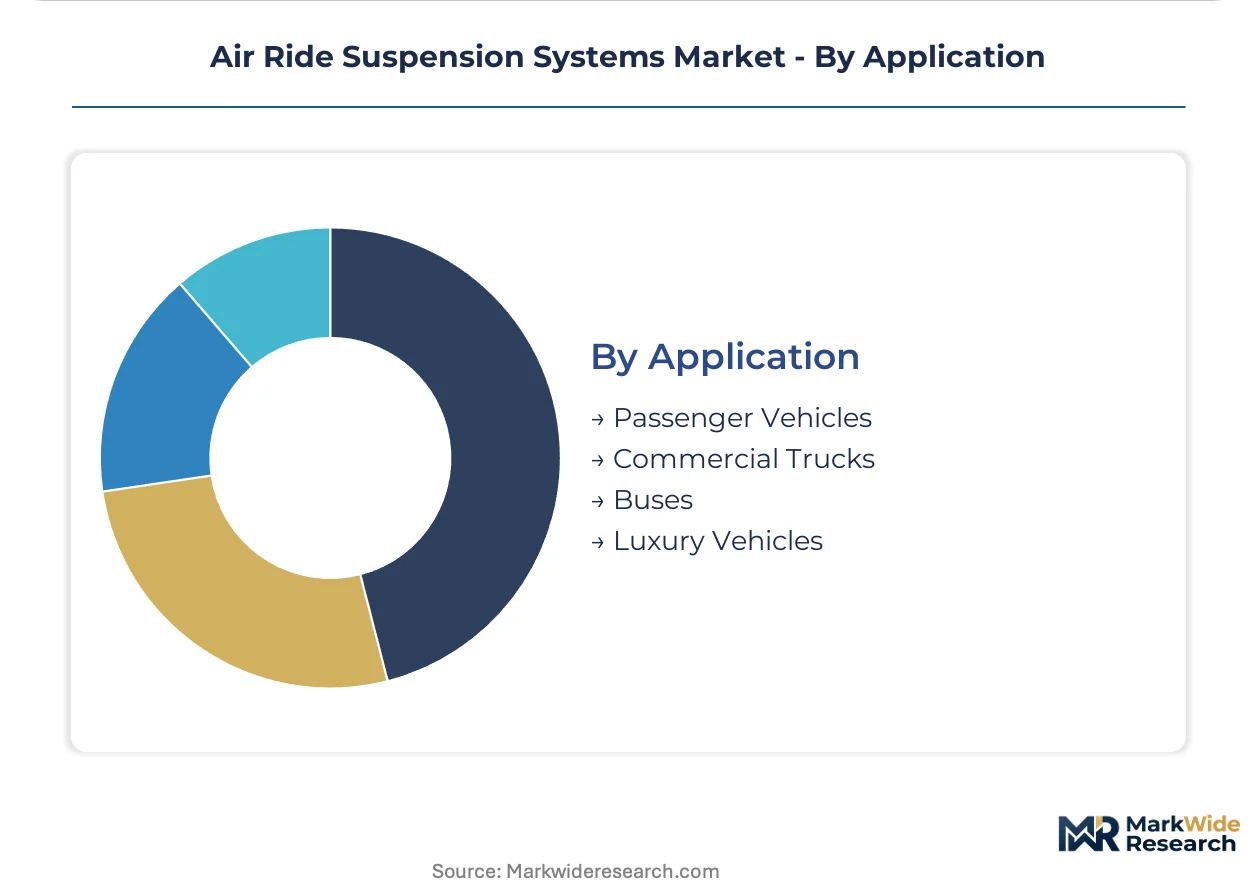
Application:
Application segmentation tracks how duty cycle severity and ride quality mandates split demand between passenger comfort priorities and commercial payload optimization.
- Commercial Trucks:Tractor-trailer and rigid truck applications account for the dominant volume share, with EPA Phase 3 compliance accelerating lightweight air spring retrofits across United States fleets.
- Luxury Vehicles:Adaptive air suspension with predictive road scanning concentrates in German premium sedan platforms where brand positioning justifies system cost.
- Buses:Transit and coach applications prioritize kneeling functionality for accessibility compliance.
- Passenger Vehicles:SUV and crossover load-leveling systems serve towing and cargo versatility requirements.
Commercial Trucks hold the largest share; Luxury Vehicles represent the steepest expansion trajectory as predictive damping technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns split sharply between mature markets where electronic control retrofits dominate fleet spending and emerging markets where mechanical replacement cycles still anchor aftermarket volume.
United States
Long-haul fleet operators with thousand-vehicle parcs are retrofitting tractor-trailers with lightweight air springs to meet EPA Phase 3 greenhouse gas standards. NHTSA Federal Motor Vehicle Safety Standards enforce brake and suspension performance benchmarks that accelerate OEM integration timelines. Detroit and Columbus anchor dense aftermarket service networks where independent distributors compete for aging commercial truck renewal.
Germany
Premium heavy-duty OEMs are qualifying alternative membrane materials ahead of REACH substance restriction deadlines for perfluorinated compounds. ECE R13 braking and stability regulations mandate dual-circuit air supply redundancy that elevates system complexity for domestic producers. Stuttgart and Munich concentrate captive air spring manufacturing operations serving European construction truck fleets.
China
Regional logistics electrification in Shandong and Hubei provinces is driving demand for lighter unsprung mass configurations in medium-duty delivery applications. MIIT vehicle emission standards and GB quality certifications shape product validation requirements for component suppliers. Wuhan and Jinan host dense OEM assembly networks generating concentrated procurement from regional air spring fabricators.
India
Aging truck parc in Maharashtra and Gujarat states lacks dense authorized service networks, opening independent channel expansion for mechanical suspension replacement. BIS quality management certifications and CDSCO automotive component standards extend product development cycles for market entry. Mumbai and Ahmedabad anchor aftermarket distribution hubs where technician scarcity limits electronic system adoption.
Japan
Automotive suppliers are integrating predictive maintenance sensors into chassis-agnostic modules for autonomous vehicle readiness programs. METI industrial standards and JIS quality certifications enforce material specifications for export-oriented production. Nagoya and Tokyo-Yokohama clusters concentrate R&D investment in smart air spring architectures with accelerometer and pressure transducer arrays.
Air Ride Suspension Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding specification authority through captive sensor-actuator platforms and the lower tier competing on regional service density and retrofit installation speed. Market structure favors suppliers with backward integration into elastomer compounding and in-house calibration capabilities. Three archetypes dominate: diversified automotive conglomerates with chassis systems divisions, dedicated suspension specialists with heavy-duty focus, and regional component fabricators serving knock-down assembly markets. Competitive moves concentrate on strategic partnerships for predictive maintenance software integration and capacity expansion in China's Shandong province production clusters.
Within the integrated tier, Continental AG and ZF Friedrichshafen AG exemplify diversified conglomerates leveraging sensor-platform breadth to capture premium fleet contracts. Hendrickson International Corporation occupies a position among North American specialists focused on trailer suspension configurations for long-haul operators. SAF-Holland represents the European specialist archetype with heavy-duty production anchored in captive manufacturing arrangements. These three sit within distinct competitive vectors—sensor integration, regional service density, and OEM captive supply—rather than direct product confrontation.
| Leading Market Players |
|---|
| Continental AG |
| ZF Friedrichshafen AG |
| ThyssenKrupp AG |
| SAF-Holland |
| Hendrickson International Corporation |
| Firestone Industrial Products |
| Hitachi Ltd. |
| Mando Corporation |
| AccuAir Suspension |
| Others |
Value Network & Pricing Analysis
Fluoropolymer displacement in air spring membrane formulations is simultaneously shifting compound supplier geography toward European elastomer blenders and compressing validation timelines that traditionally anchored premium pricing tiers. REACH substance restrictions are forcing reformulation investments that tier-two manufacturers struggle to amortize, concentrating pricing power with German heavy-duty OEMs who qualified alternative materials ahead of regulatory deadlines.
Pricing Analysis
Long-term offtake contracts dominate procurement between thousand-vehicle fleet operators and integrated chassis suppliers, compressing spot-market opportunities for independent distributors. Three-tier pricing structure across premium sensor-integrated, standard pneumatic, and economy mechanical levels separates Electronic Control modules from legacy height control valve replacements. Pricing pressure stems from fleet procurement centralization around total cost of ownership metrics that squeeze supplier margins. Aftermarket channels serving India's aging truck parc exhibit highest price sensitivity due to technician scarcity limiting electronic system adoption.
Supply Chain Analysis
Thailand and Malaysia anchor natural rubber supply for air spring bellows production, while Germany and China concentrate captive manufacturing of sensor-actuator platforms and regional component fabrication respectively. Raw material inputs draw from petroleum-derived synthetic elastomers, multi-ply reinforcement fabrics, and precision-machined bead rings. Single-source vulnerability concentrates in Southeast Asian plantation regions exposed to climate disruption and export policy shifts. Distribution runs through OEM direct contracts for fleet operators and independent service networks for commercial truck aftermarket renewal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air ride suspension systems sit in early-cycle expansion as EPA Phase 3 greenhouse gas standards and predictive maintenance integration create simultaneous retrofit and new-platform specification tailwinds. Fleet procurement centralization around integrated chassis-axle-suspension packages is compressing supplier margins while locking in multi-year service relationships.
For Market Incumbents: Consolidate sensor-actuator platform capabilities through backward integration into elastomer compounding to defend against chassis-agnostic module suppliers entering through autonomous truck readiness programs. Lock in captive supply arrangements with Chinese OEM assembly clusters in Shandong and Hubei provinces before regional fabricators achieve electronic control calibration scale. Prioritize ISO 9001 and ECE R13 dual-circuit certification investments that extend validation timelines beyond emerging competitor reach. For New Entrants and Emerging Players: Lead with aftermarket service network density in underpenetrated Indian states where Maharashtra and Gujarat aging truck parcs lack authorized electronic system support. Target mechanical-to-hybrid retrofit configurations as the most penetrable technology tier where technician scarcity limits full Electronic Control adoption. Deploy mobile calibration units and remote diagnostic partnerships as the go-to-market angle to bypass fixed infrastructure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional suspension specialists in North America lacking predictive maintenance software integration. Long-term viability over the five-to-ten year window hinges on autonomous vehicle readiness positioning and fleet data monetization capabilities. Monitor specification authority shifts in thousand-vehicle fleet direct OEM contracts as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Integration | Sensor-embedded modules from Continental AG enable condition-based servicing contracts that shift value capture toward recurring revenue streams. |
| Capacity Expansion in Shandong Province | Regional OEM assembly networks in China generate concentrated procurement demand requiring localized air spring fabrication capabilities. |
| Alternative Mematerial Qualification | German heavy-duty OEMs ahead of REACH deadlines compress validation timelines that tier-two suppliers cannot match. |
| Long-term Fleet Service Agreements | Thousand-vehicle parc managers in the United States lock in multi-year chassis-axle-suspension packages that reduce parts inventory complexity. |
| Joint Venture for Dual-Circuit Systems | ECE R13 compliant exporters capture elevated system complexity value through redundant air supply architectures mandated in Europe. |
Research Methodology
Cross-validation between primary interviews with fleet operations directors, OEM platform engineers, aftermarket service technicians, and Tier 1 procurement managers anchors the qualitative findings against secondary validation from EPA regulatory filings, NHTSA safety standard databases, vehicle production registries, and customs trade data for elastomer imports. Bottom-up triangulation across component supplier shipment records and top-down reconciliation against OEM platform launch schedules ensures segmentation integrity. The analysis combines field perspectives from maintenance directors at long-haul operators with technical documentation from ISO certification audits.
Sensitivity analysis around natural rubber price volatility scenarios and technician training pipeline constraints shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, end-user procurement channel, and application duty cycle severity. CAGRs derive from installed base renewal patterns and new vehicle content-per-unit trajectories. Forecast inputs incorporate EPA Phase 3 compliance retrofit schedules and REACH substance restriction implementation timelines.
Forecasts assume regulatory continuity in EPA greenhouse gas standards and ECE R13 braking mandates; material policy shifts would require re-modeling adoption curves for lightweight air spring technologies. Commodity price spikes in petroleum-derived elastomers or export restrictions from Southeast Asian rubber producers represent specific revision triggers. Recalibration cycles align with material shifts in fleet procurement centralization and autonomous vehicle readiness program milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Tow Tractor Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Engine Air Filter Market