
 Automotive Exhaust Gas Sensor Market | 2026-2036
Automotive Exhaust Gas Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Gas Sensor Market Analysis
A shift from single-source to multi-source procurement is pivoting how Tier-1 suppliers secure ceramic sensing elements. NGK Insulators, Ltd. leverages captive zirconia production to anchor its position in oxygen sensing substrates. Robert Bosch GmbH sustains broad integration from chip design to module assembly. DENSO Corporation competes through thermal management expertise that extends into exhaust stream applications.
Automotive exhaust gas sensors are electrochemical or solid-state devices that measure oxygen, nitrogen oxide, or temperature levels in engine exhaust streams, typically operating at 300°C to 900°C to enable real-time air-fuel ratio correction and aftertreatment system control. Their primary purpose is ensuring combustion efficiency while enabling catalytic converter and selective catalytic reduction system performance. Lambda and NOx sensor categories command the deepest OEM integration due to direct emissions compliance linkage. MEMS-based architectures are gaining share where miniaturization and multi-gas detection convergence matter most. Electrochemical variants retain cost advantages in aftermarket replacement cycles across aging vehicle parcs.
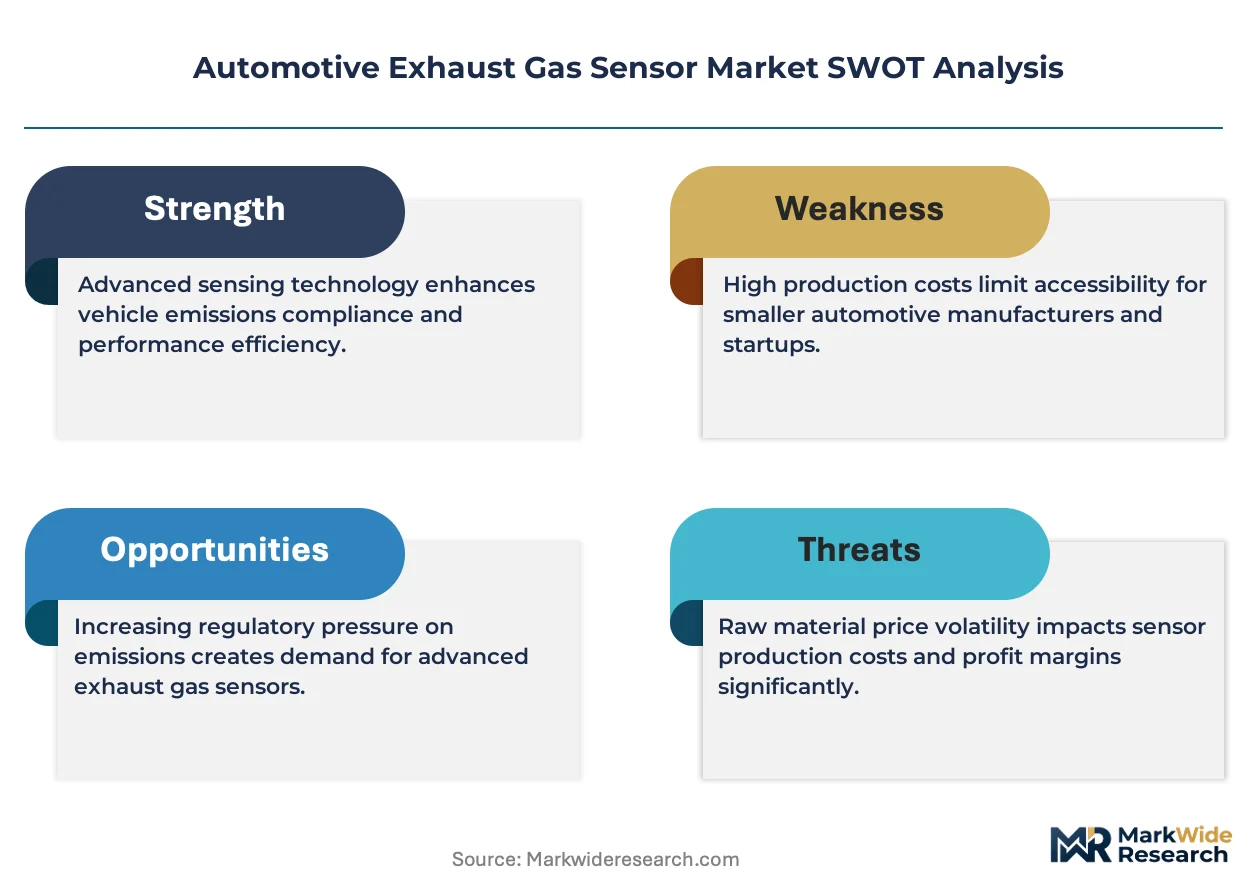
The EPA, Euro 7 framework, and China's MEE set the tripartite regulatory boundary for sensor accuracy thresholds, calibration protocols, and onboard diagnostic requirements. These bodies mandate failure detection within seconds, which forces suppliers to embed self-diagnostic circuitry and redundant measurement paths. Stakeholders must weigh ceramic versus silicon carbide substrate bets as electrified powertrains alter exhaust thermal profiles and sensor duty cycles.
Market Dynamics
Powertrain electrification is fragmenting exhaust thermal profiles, forcing sensor architectures to accommodate intermittent combustion cycles and wider temperature swings than traditional internal combustion engines required.
Growth Catalysts
- Euro 7 emission limits:The framework mandates real-time NOx monitoring with sub-second failure detection, expanding sensor count per vehicle across European OEM platforms.
- Hybrid powertrain proliferation:Light-duty OEMs deploy additional sensing points to manage transient combustion events during engine-on intervals in plug-in architectures.
- China's dual carbon goals:MEE enforcement tightens tailpipe verification protocols, accelerating replacement cycles for aging sensor populations in the country's vehicle parc.
Market Restraints
- Ceramic substrate concentration:Zirconia supply chains cluster in East Asian refractory producers, exposing Tier-1 module assemblers to input volatility and single-source vulnerability.
- Silicon carbide technical immaturity:Wide-bandgap substrates promise higher thermal tolerance but lack standardized fabrication protocols for electrochemical cell integration.
- Electrification substitution:Battery-electric powertrains eliminate exhaust streams entirely, compressing addressable sensor demand in premium vehicle segments.
Strategic Opportunities
- Aftermarket channel expansion:Aging vehicle populations in Germany and Japan sustain replacement demand for lambda and NOx sensors outside OEM warranty periods.
- MEMS multi-gas convergence:Solid-state architectures enable simultaneous oxygen, hydrocarbon, and particulate detection within single housing units.
- India BIS emission roadmap:Staged implementation of Bharat Stage VI phase-II creates regulatory tailwind for sensor suppliers entering domestic OEM supply chains.
Industry Challenges
- Embedded software certification:EPA and Euro 7 diagnostic mandates require ASIL-rated firmware validation, extending development timelines for new sensor platforms.
- Cross-platform thermal calibration:Hybrid duty cycles demand sensor algorithms that adapt to rapid temperature swings without recalibration service visits.
- Skill scarcity in solid-state electrochemistry:MEMS fabrication expertise concentrates in semiconductor foundries, creating hiring friction for traditional ceramic sensor houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Gas Sensor Market |
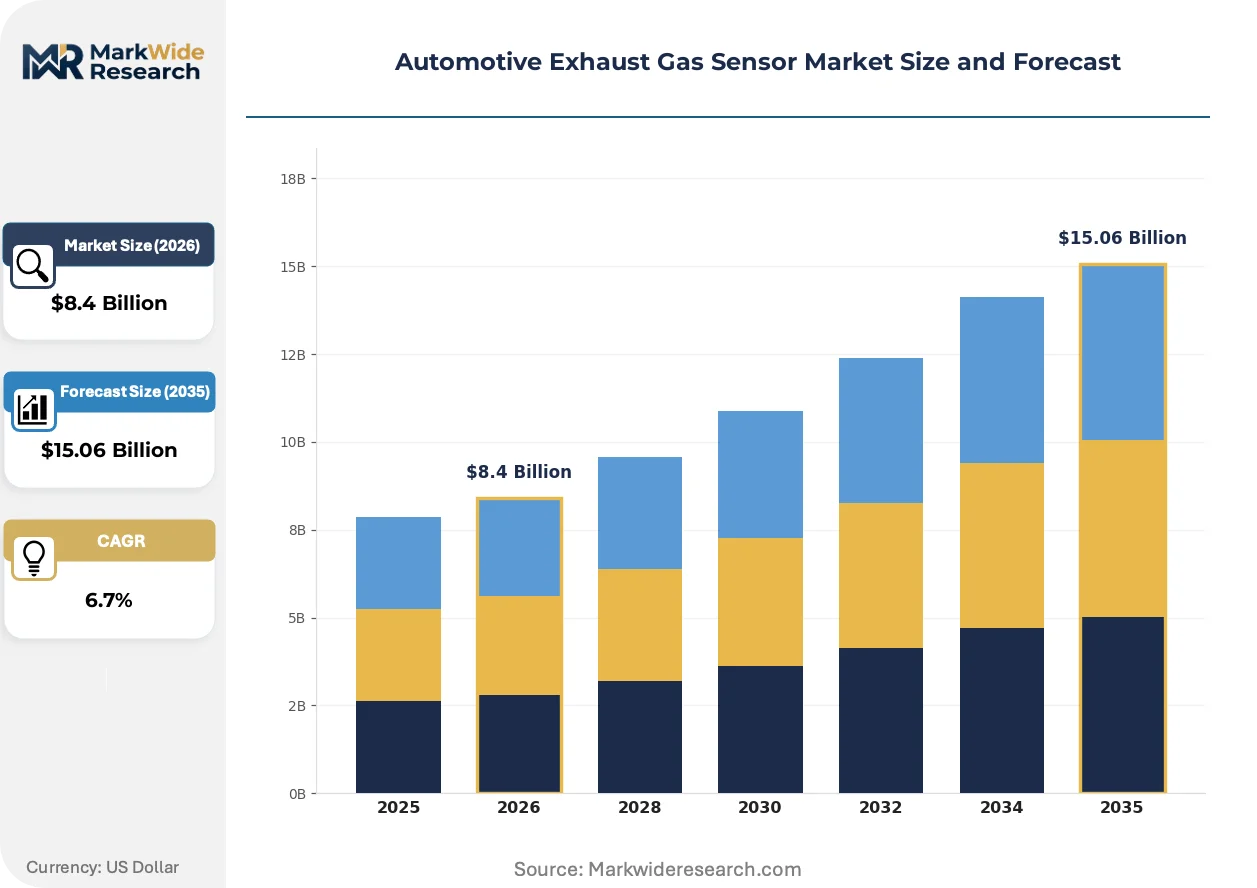
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
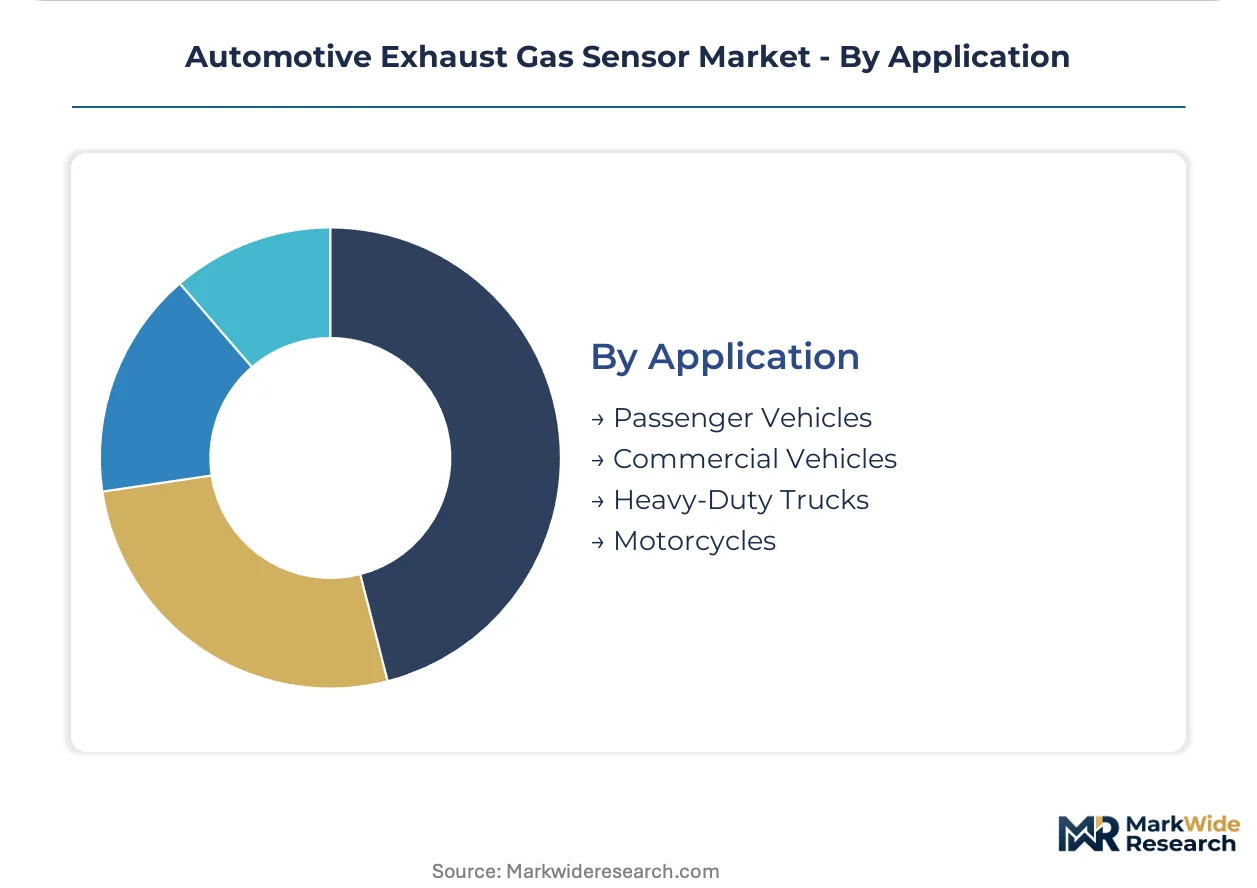
| Segmentation | Product Type: Lambda Sensors, O2 Sensors, NOx Sensors, Temperature Sensors End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: MEMS, Electrochemical, Infrared, Solid-State Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles |
| Companies Covered | NGK Insulators, Ltd., Sensata Technologies, Inc., Robert Bosch GmbH, HELLA KGaA Hueck & Co., HORIBA, Ltd., DENSO Corporation, BorgWarner Inc., Valeo S.E., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Gas Sensor Market Emerging Trajectories
Sensor architectures are converging toward multi-physics detection platforms, compressing the traditional separation between gas measurement and thermal management functions into unified modules.
Wide-bandgap silicon carbide substrates are overtaking conventional yttria-stabilized zirconia in next-generation high-temperature applications. OEMs developing 48V mild-hybrid systems specify SiC-based cells for exhaust streams exceeding 800°C. The shift is compressing the cost premium that ceramic substrates historically maintained through mature high-volume production.
EPA's updated heavy-duty onboard diagnostic regulations expand real-time monitoring mandates to vocational vehicle categories previously exempt from passenger-car protocols. Engine manufacturers must now embed redundant sensing paths for particulate filter regeneration verification. The rule change most affects medium-duty truck platforms assembled in Michigan and Ohio, where suppliers are reconfiguring module firmware to accommodate dual-sensor validation loops.
Fleet operators are unbundling sensor replacement from full exhaust system service contracts, creating direct procurement relationships with component manufacturers. Independent repair chains in Texas and California now stock lambda and NOx sensors as separate SKUs rather than bundled catalyst assemblies. The pattern is most pronounced in commercial vehicle segments where uptime metrics drive preference for rapid component-level replacement over complete subsystem swaps.
Automotive Exhaust Gas Sensor Market Segmentation
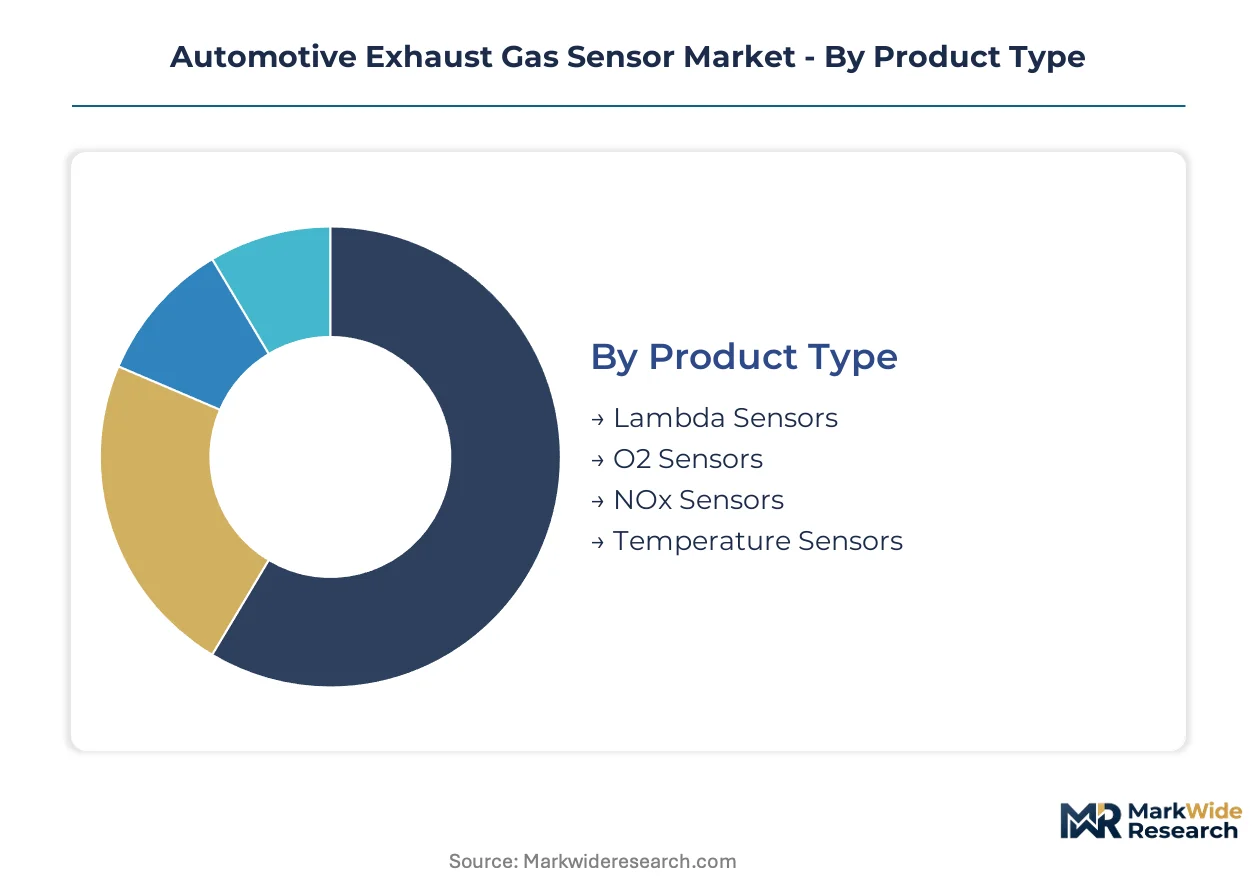
Exhaust gas sensor procurement diverges sharply between regulatory-driven OEM specifications and cost-sensitive aftermarket replacement cycles. Each segment category reflects distinct technical requirements, thermal tolerances, and compliance linkages that reshape supplier priorities across the value chain.
Product Type:
OEMs prioritize sensing precision thresholds that map directly to emission certification tiers rather than unit economics alone.
- Lambda Sensors:Zirconia-based electrochemical cells measure air-fuel ratios with ±1% accuracy at 600°C operating temperatures. German and Japanese OEMs specify wide-band variants for Euro 7 pre-compliance testing on hybrid powertrains.
- NOx Sensors:Solid-state architectures with titanium dioxide sensing elements detect nitrogen oxide concentrations below 10 ppm. China's MEE enforcement accelerates deployment across heavy-duty diesel platforms in Shandong and Jiangsu provinces.
- O2 Sensors:Narrow-band designs dominate aftermarket channels where calibration simplicity outweighs measurement range requirements.
- Temperature Sensors:Thermocouple and resistance-temperature-detector hybrids monitor exhaust stream thermal profiles for diesel particulate filter regeneration timing.
Volume sits with Lambda Sensors; growth tilts toward NOx Sensors.
End User:
Procurement authority concentrates differently across warranty periods and vehicle lifecycle stages.
- OEMs:Direct sourcing relationships with ceramic substrate producers lock in multi-year supply commitments. Ford and Toyota specify ASIL-D diagnostic firmware for lambda sensor modules integrated into engine control units.
- Aftermarket Providers:Independent distributors in Texas and California stock universal-fit sensors compatible with 15+ vehicle platforms. Price competition intensifies as Chinese module assemblers bypass traditional Tier-1 channels.
- Tier-1 Suppliers:Bosch and DENSO integrate sensing elements with harness assemblies and connector systems for just-in-sequence delivery to vehicle assembly plants.
- Vehicle Assemblers:Contract manufacturers in Mexico and Eastern Europe specify sensor kits bundled with exhaust manifold subassemblies to reduce line-side complexity.
Revenue concentrates with OEMs; margin expansion favors Aftermarket Providers.
Technology:
Substrate material selection determines thermal ceiling and electrochemical stability tradeoffs.
- MEMS:Silicon-based microelectromechanical systems enable multi-gas detection within 5mm³ housing volumes. MEMS fabrication expertise at semiconductor foundries in South Korea and Taiwan supports sensor miniaturization for 48V mild-hybrid architectures.
- Electrochemical:Yttria-stabilized zirconia cells maintain cost advantages in high-temperature applications exceeding 800°C where MEMS silicon substrates degrade.
- Infrared:Non-dispersive infrared absorption measures CO₂ and hydrocarbon concentrations without direct exhaust stream contact, reducing thermal stress on optical components.
- Solid-State:Wide-bandgap silicon carbide substrates enable NOx detection at 900°C with faster response times than ceramic alternatives.
Deployment volume favors Electrochemical; technology transition accelerates toward Solid-State.
Application:
Exhaust thermal profiles and duty cycle intensity reshape sensor specification requirements.
- Passenger Vehicles:Hybrid powertrains demand sensors tolerant of intermittent combustion cycles with rapid temperature swings between 200°C and 700°C during engine-on intervals.
- Commercial Vehicles:Medium-duty truck platforms in Michigan and Ohio require redundant sensing paths under EPA heavy-duty onboard diagnostic regulations for particulate filter regeneration verification.
- Heavy-Duty Trucks:Long-haul diesel applications specify hardened sensor housings resistant to vibration and thermal shock across million-mile operational lifespans.
- Motorcycles:Compact single-cylinder engines with high-revving exhaust pulses drive demand for lightweight sensors with sub-50mm probe lengths.
Unit volume concentrates in Passenger Vehicles; specification complexity escalates fastest in Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zirconia refractory production clusters in East Asia supply ceramic sensing elements worldwide. Germany, Japan, and the United States concentrate OEM sensor demand where hybrid powertrains prolong internal combustion engine production. Regulatory divergence across EPA, Euro 7, and China's MEE frameworks fragments compliance requirements by geography.
United States
Heavy-duty truck manufacturers in Michigan and Ohio deploy redundant sensing paths under EPA's updated onboard diagnostic regulations. The EPA mandates real-time particulate filter regeneration verification for vocational vehicles previously exempt from passenger-car protocols. Sensor module suppliers reconfigure firmware in Detroit-area facilities to accommodate dual-sensor validation loops for medium-duty platforms.
Germany
Automotive OEMs specify wide-band lambda sensors for Euro 7 pre-compliance testing on hybrid architectures. The KBA enforces sub-second failure detection thresholds that expand sensor count per vehicle across European platforms. Bosch and Continental anchor development activity in Stuttgart and Hanover, integrating ASIL-D diagnostic firmware directly into engine control units.
China
Shandong and Jiangsu provinces accelerate NOx sensor deployment across heavy-duty diesel fleets. The MEE tightens tailpipe verification protocols under dual carbon goals, compressing replacement cycles for aging sensor populations. Domestic module assemblers bypass traditional Tier-1 channels to serve independent distributors in aftermarket channels.
Japan
Captive zirconia production at NGK Insulators anchors oxygen sensing substrate supply for hybrid powertrain programs. METI standards coordinate with Euro 7 alignment timelines, sustaining sensor demand despite domestic vehicle parc contraction. DENSO Corporation leverages thermal management expertise from air conditioning systems into exhaust stream applications at Nagoya-area facilities.
India
Bharat Stage VI phase-II implementation creates regulatory tailwind for sensor suppliers entering domestic OEM supply chains. The BIS emission roadmap stages compliance requirements that mirror Euro progression timelines. Tamil Nadu and Maharashtra vehicle assembly plants specify sensor kits bundled with exhaust manifold subassemblies to reduce line-side complexity.
Automotive Exhaust Gas Sensor Market Vendor Landscape
Strategic partnerships dominate the current landscape as suppliers secure ceramic substrate access and firmware certification capabilities. The market structures around three tiers: integrated system suppliers with captive material production, module assemblers sourcing from external refractory producers, and aftermarket distributors competing on price. Two archetypes predominate: refractory-anchored specialists controlling zirconia supply chains, and thermal-management diversifiers extending expertise from adjacent automotive systems. Competitive moves concentrate on backward integration into ceramic substrates and technology licensing for MEMS fabrication protocols.
Among Japanese specialists, NGK Insulators, Ltd. exemplifies the refractory-anchored archetype through captive zirconia production. Robert Bosch GmbH represents the integrated system supplier model with broad capabilities spanning chip design through module assembly. DENSO Corporation occupies a position within the thermal-management diversifier category, applying expertise developed in climate control systems to exhaust stream applications.
| Leading Market Players |
|---|
| NGK Insulators, Ltd. |
| Sensata Technologies, Inc. |
| Robert Bosch GmbH |
| HELLA KGaA Hueck & Co. |
| HORIBA, Ltd. |
| DENSO Corporation |
| BorgWarner Inc. |
| Valeo S.E. |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
MEMS fabrication specialists concentrated in South Korea and Taiwan create labor-cost differentials that widen pricing spreads between premium solid-state sensors and economy-grade electrochemical replacements. Warranty bundling decisions at German and Japanese OEMs compress aftermarket price elasticity, while unbundled sensor procurement by Texas fleet operators exposes Chinese module assemblers to direct price competition.
Pricing Analysis
Warranty bundling with exhaust system service contracts separates OEM procurement premiums from aftermarket component-level pricing. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade and thermal tolerance specifications. Cost compression in economy tiers intensifies because Chinese module assemblers bypass traditional Tier-1 channels. Fleet operators in commercial vehicle segments exhibit highest price sensitivity; OEMs with captive zirconia supply exhibit lowest.
Supply Chain Analysis
Reverse-logistics flows for sensor refurbishment remain underdeveloped, limiting circularity in ceramic substrate recovery. Zirconia refractory production clusters in Japan, China, and South Korea; MEMS silicon wafers draw from Taiwan and South Korea foundries. Raw material dependencies center on yttria-stabilized zirconia, titanium dioxide sensing elements, and wide-bandgap silicon carbide substrates. Single-source vulnerability in East Asian refractory producers exposes Tier-1 assemblers to input volatility. Distribution runs through just-in-sequence delivery to vehicle assembly plants and independent aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive exhaust gas sensor market sits in a technology-transition phase where silicon carbide substrates displace legacy zirconia electrochemical cells in high-temperature hybrid applications.
For Market Incumbents: Hedge ceramic substrate exposure by diversifying into silicon carbide partnerships before wide-bandgap fabrication protocols standardize. Lock in multi-year zirconia supply commitments with East Asian refractory producers to defend against input volatility. Accelerate ASIL-D firmware certification investments to meet Euro 7 diagnostic mandates.
For New Entrants and Emerging Players: MEMS multi-gas convergence platforms offer a technology-first wedge into 48V mild-hybrid architectures where miniaturization commands premium positioning. Target India's Bharat Stage VI phase-II implementation as the most penetrable regulatory tailwind. Pursue direct procurement relationships with Texas and California fleet operators unbundling sensor replacement from full exhaust system contracts.
For Investors and Strategic Acquirers: The window for entry favors thermal-management diversifiers with adjacent automotive system expertise transferable to exhaust stream applications. Long-term viability hinges on substrate material bets resolving across the next decade. Monitor EPA heavy-duty onboard diagnostic rule expansions to vocational vehicle categories as the inflection indicator for redundant sensing path demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive zirconia supply insulates Tier-1 assemblers from East Asian refractory volatility. |
| MEMS Fabrication Licensing | Semiconductor foundry partnerships in Taiwan accelerate solid-state sensor miniaturization roadmaps. |
| ASIL-D Firmware Certification | Euro 7 and EPA mandates require validated diagnostic circuitry for sub-second failure detection. |
| Aftermarket Channel Expansion | Direct procurement relationships with Texas fleet operators bypass traditional bundled service contracts. |
| Silicon Carbide Substrate Development | Wide-bandgap materials enable 900°C NOx detection for next-generation hybrid powertrains. |
Methodological Framework
Trade databases, vehicle production registries, and regulatory filing repositories formed the secondary backbone of this analysis. Primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and exhaust system service technicians validated demand assumptions. Bottom-up and top-down triangulation cross-referenced sensor unit volumes against vehicle parc data and emission compliance timelines.
Bottom-up modeling aggregated segment-level sensor counts per vehicle across propulsion architectures, while top-down validation checked aggregate market value against OEM procurement disclosure patterns. Segmentation dimensions included product type, technology substrate, vehicle class, and regional regulatory framework. CAGRs derived from regression analysis of historical replacement cycles and projected electrification penetration rates. Forecast inputs incorporated Euro 7 implementation timelines and EPA heavy-duty onboard diagnostic expansion schedules.
Several conditions sit outside the modeled scope, including potential battery-electric vehicle adoption acceleration that eliminates exhaust streams entirely, and breakthroughs in optical sensing technologies that displace electrochemical architectures. Forecasts reflect documented assumptions about hybrid powertrain production persistence and ceramic substrate supply continuity. Practitioners should monitor silicon carbide fabrication cost curves and China MEE enforcement intensity for early signals of technology-transition velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Throttle Cable Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
EGR Coolers Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Heavy Vehicles Suspension Anti-Vibration Components Market