
 Locomotive Lighting Batteries Market | 2026-2036
Locomotive Lighting Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Lighting Batteries Market Foresight
Multi-source procurement from dedicated battery suppliers is shifting away from captive rail OEM workshops. EnerSys leverages its industrial motive power infrastructure to serve Class I railroads across North America. Saft anchors European demand through its specialization in nickel-based chemistries for rolling stock applications. Exide Technologies competes on manufacturing scale in the lead acid replacement segment for aging freight fleets.
Locomotive lighting batteries are rechargeable electrochemical cells engineered to deliver stable DC output for headlamps, marker lights, and cabin illumination, typically operating at 24V or 74V nominal with vibration-resistant construction to withstand rail-grade shock loads. Their primary purpose is ensuring continuous lighting independent of catenary or diesel-generator availability during startup, tunnel transit, or power interruption. Lithium-ion products command the fastest expansion as rail operators seek weight reduction and extended cycle life in passenger train applications. Lead acid retains volume dominance in the freight replacement channel where capital constraints and existing charging infrastructure limit chemistry switching. Smart lighting technology integration creates margin pools for suppliers capable of embedding battery management systems with real-time state-of-charge telemetry.
The Federal Railroad Administration governs emergency lighting duration and battery performance standards for U.S. rolling stock, while the EU F-Gas Regulation and REACH compliance shape material selection and recycling obligations for European suppliers. India's BIS certification mandates and the Railways Board's electrification targets are accelerating domestic procurement of advanced lead acid and lithium-ion systems. Stakeholders must monitor how battery passport requirements and carbon border adjustments restructure supplier qualification criteria across major rail networks.
Market Dynamics
The locomotive lighting batteries market is being fundamentally restructured by chemistry migration from lead acid to lithium-ion systems, driven by rail operators pursuing weight reduction and extended cycle life in electrified fleets. This transition compresses replacement cycles and forces suppliers to requalify products under evolving safety mandates.
Growth Catalysts
- FRA Safety Protocols:U.S. Federal Railroad Administration mandates for emergency lighting duration are accelerating battery replacement schedules across Class I railroads, particularly for aging freight locomotives operating in non-electrified corridors.
- Rail Electrification Programs:India's Railways Board electrification targets are generating procurement volume for advanced lead acid and lithium-ion lighting systems in new-build passenger coaches and retrofitted diesel fleets.
- Lithium-Ion Chemistry Advances:Energy density improvements and thermal management innovations are enabling 24V and 74V systems to meet vibration-resistant specifications previously exclusive to nickel-based alternatives.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material cost swings in cathode supply chains are compressing margins for lithium-ion product lines and delaying conversion decisions by capital-constrained freight operators.
- Charging Infrastructure Lock-In:Existing lead acid charging stations across North American railyards create switching costs that anchor replacement demand in legacy chemistry despite superior lithium-ion performance metrics.
- REACH Compliance Burden:European material registration and recycling obligations are extending product development timelines and raising qualification barriers for non-EU suppliers seeking EU market access.
Strategic Opportunities
- Battery Management System Integration:Embedded telemetry for real-time state-of-charge monitoring is converging with smart lighting architectures, creating premium pricing tiers for suppliers with software-hardware integration capabilities.
- German Rail Electrification:Deutsche Bahn's fleet modernization program is concentrating demand for nickel-based and lithium-ion lighting batteries in European passenger applications with stringent vibration specifications.
- Aftermarket Service Unbundling:Battery-as-a-service models are emerging as rail operators seek to transfer cycle life risk and maintenance liability to specialized suppliers.
Industry Challenges
- BMS Firmware Certification:Functional safety validation for battery management systems under rail-specific electromagnetic compatibility standards is extending product launch timelines and requiring specialized engineering talent pools.
- Legacy System Integration:Retrofit installations must maintain electrical interface compatibility with 30-year-old locomotive wiring harnesses while delivering modern lithium-ion performance, complicating system architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Lighting Batteries Market |
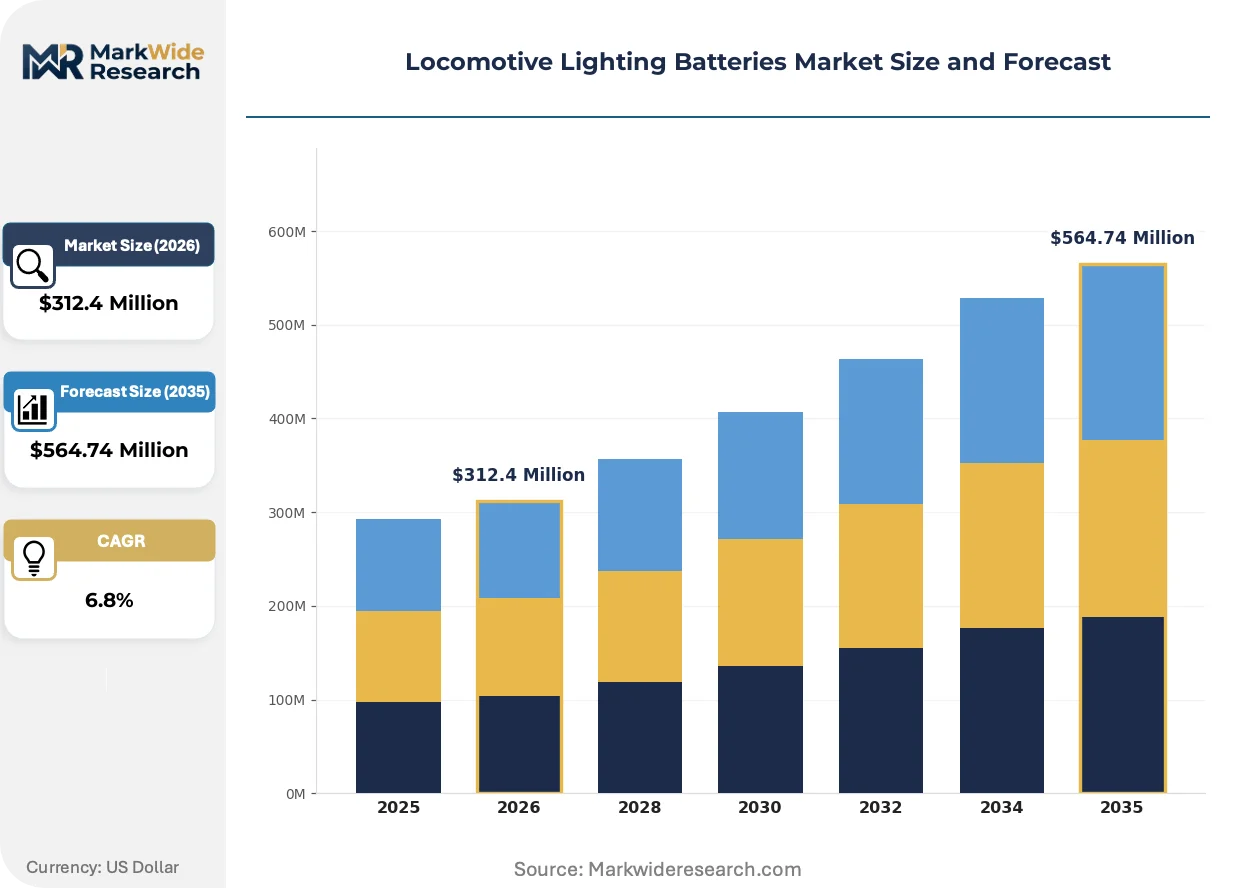
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-ion, Nickel Cadmium, Advanced Lead Acid Application: Passenger Trains, Freight Trains, Maintenance-of-Way Equipment, Switch Locomotives Technology: Conventional, Smart Lighting, Energy-Efficient, High-Intensity Discharge End User: Rail Operators, Manufacturers, Maintenance Services, Transportation Authorities |
| Companies Covered | Saft, EnerSys, Exide Technologies, GS Yuasa Corporation, Panasonic Corporation, BYD Company Ltd., Hoppecke Batterien Gmbh & Co. Kg, A123 Systems, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Lighting Batteries Market Shifts & Advancements
Technology integration and regulatory compression are reshaping how locomotive lighting batteries are specified, procured, and maintained across rail networks. Suppliers must now deliver electrochemical performance alongside digital connectivity and compliance documentation.
Smart battery management systems are converging with locomotive lighting architectures to enable predictive maintenance and remote diagnostics. European passenger operators are deploying these systems fastest, driven by EU F-Gas Regulation requirements for leak detection and asset traceability. This convergence is compressing supplier margins on standalone cell sales while opening recurring revenue streams from software-enabled service contracts.
REACH and the EU Battery Passport framework are mandating material provenance disclosure and carbon footprint accounting across European rail supply chains. Battery suppliers must now document cobalt sourcing, recycling pathways, and manufacturing emissions to maintain qualification status. German and French rolling stock manufacturers are responding by consolidating supplier panels to reduce compliance audit burden.
Rail operators are unbundling lighting battery procurement from locomotive OEM contracts and sourcing directly from specialized electrochemical suppliers. North American Class I railroads are leading this shift, establishing technical qualification programs independent of original equipment manufacturer recommendations. This disintermediation is visible most acutely in the United States, where Union Pacific and BNSF have published standalone battery specifications for tender response.
Locomotive Lighting Batteries Market Segmentation
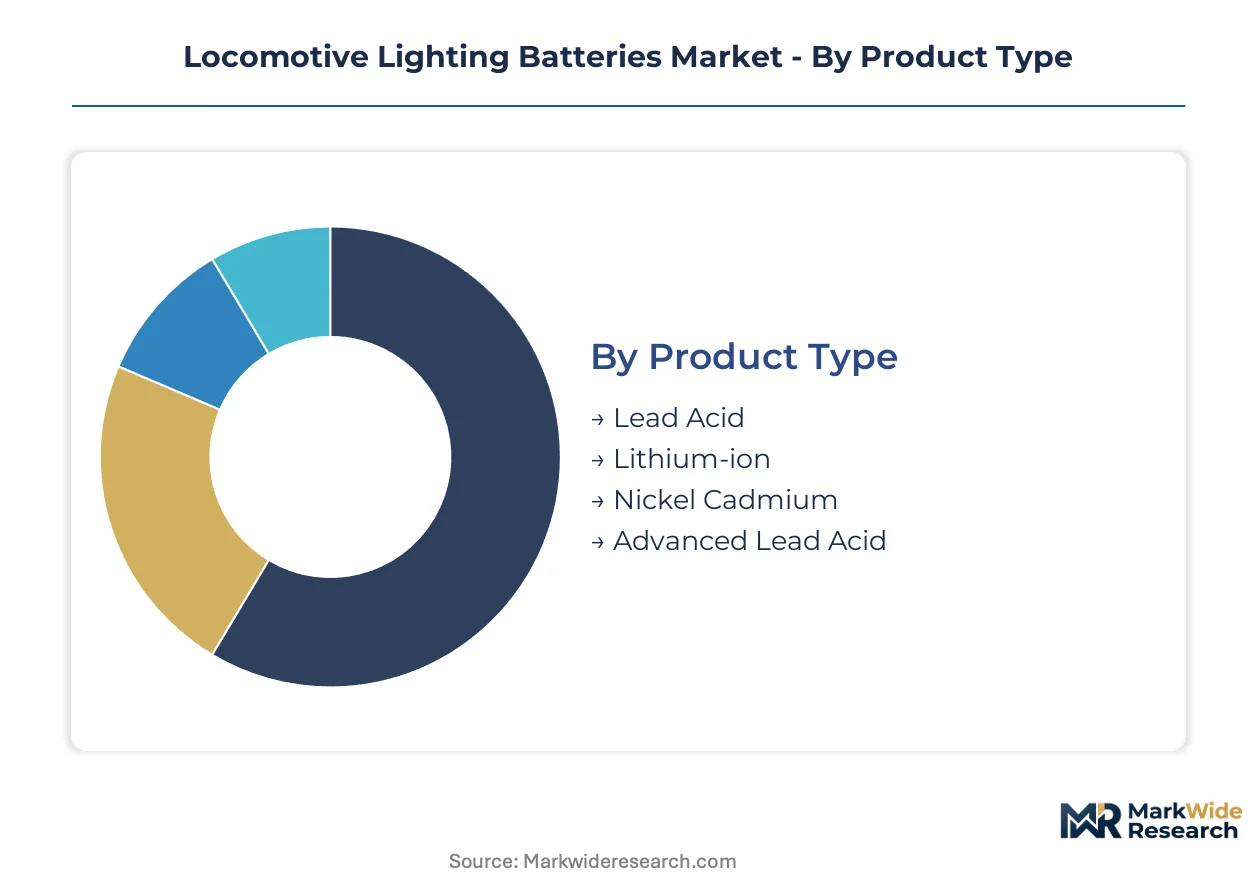
Segmentation in locomotive lighting batteries reveals how capital allocation, regulatory pressure, and operational requirements fragment demand across chemistry types, vehicle classes, and procurement channels. Understanding these divisions exposes where suppliers must build distinct capabilities versus where scale economies apply.
Product Type:
Capital intensity varies sharply across chemistries, with lithium-ion demanding the highest upfront manufacturing investment for cell formation and thermal management systems.
- Lead Acid:Flooded and valve-regulated designs dominate freight retrofit channels where existing charging infrastructure limits switching costs. Demand concentrates in North American Class I railyards constrained by capital budgets and legacy equipment compatibility requirements.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants deliver energy density above 150 Wh/kg with cycle life exceeding 2,000 deep discharges. Procurement is accelerating in German and Indian passenger fleets where weight reduction directly reduces energy consumption per passenger-kilometer.
- Nickel Cadmium:Sintered plate construction withstands extreme temperature swings in Nordic and alpine rail corridors. Railway operators in Norway and Switzerland specify these for tunnel emergency lighting where thermal runaway risks must approach zero.
- Advanced Lead Acid:Carbon-enhanced negative electrodes and gel electrolyte formulations extend cycle life 40% beyond conventional lead acid. Indian Railways and Deutsche Bahn are piloting these for diesel-electric hybrid locomotives seeking chemistry transitions without full infrastructure replacement.
Lead acid absorbs the bulk of installed capacity; lithium-ion is expanding most quickly.
Application:
Operating duty cycles and regulatory exposure create four distinct demand pools with diverging performance specifications and replacement frequencies.
- Passenger Trains:High-speed and intercity rolling stock require continuous lighting availability through catenary gaps. European operators under EU F-Gas Regulation mandates are specifying smart battery management systems with predictive failure analytics for these fleets.
- Freight Trains:Long-haul diesel locomotives operate in electrification gaps across the United States, Canada, and Russia. FRA emergency lighting duration rules are compressing replacement cycles for aging battery banks in these applications.
- Maintenance-of-Way Equipment:Ballast regulators and track tampers need portable lighting independent of locomotive power. BNSF and Union Pacific procurement specifications now require vibration resistance to 5 Grms for these mobile work platforms.
- Switch Locomotives:Low-speed yard operations demand frequent start-stop cycling that degrades conventional lead acid. Indian port railways and German marshalling yards are testing lithium-ion conversions for these high-cycling duty profiles.
Freight trains represent the largest addressable base; passenger trains command the steepest expansion trajectory.
Technology:
Integration complexity and margin structure separate legacy electrochemical systems from digitally enabled architectures.
- Conventional:Passive cell balancing and fixed charge profiles serve cost-sensitive operators with minimal telemetry requirements. These systems retain volume in North American freight replacement cycles where procurement prioritizes unit cost over lifecycle optimization.
- Smart Lighting:CAN-bus integrated battery management systems communicate state-of-charge, temperature, and health metrics to locomotive control networks. Deutsche Bahn and SNCF are mandating these for new-build passenger stock under predictive maintenance directives.
- Energy-Efficient:LED driver optimization and adaptive dimming algorithms reduce battery discharge depth by 15-25%. Indian Railways' electrification program is specifying these for diesel fleet retrofits seeking auxiliary load reduction.
- High-Intensity Discharge:Xenon and metal-halide arc lamps demand high instantaneous current delivery that stresses battery internal resistance. These are declining in new specifications as LED luminous efficacy surpasses 150 lumens per watt.
Conventional technology holds the majority of active installations; smart lighting is gaining share fastest.
End User:
Procurement authority and technical sophistication fragment the buyer landscape across four organizational types with distinct vendor qualification processes.
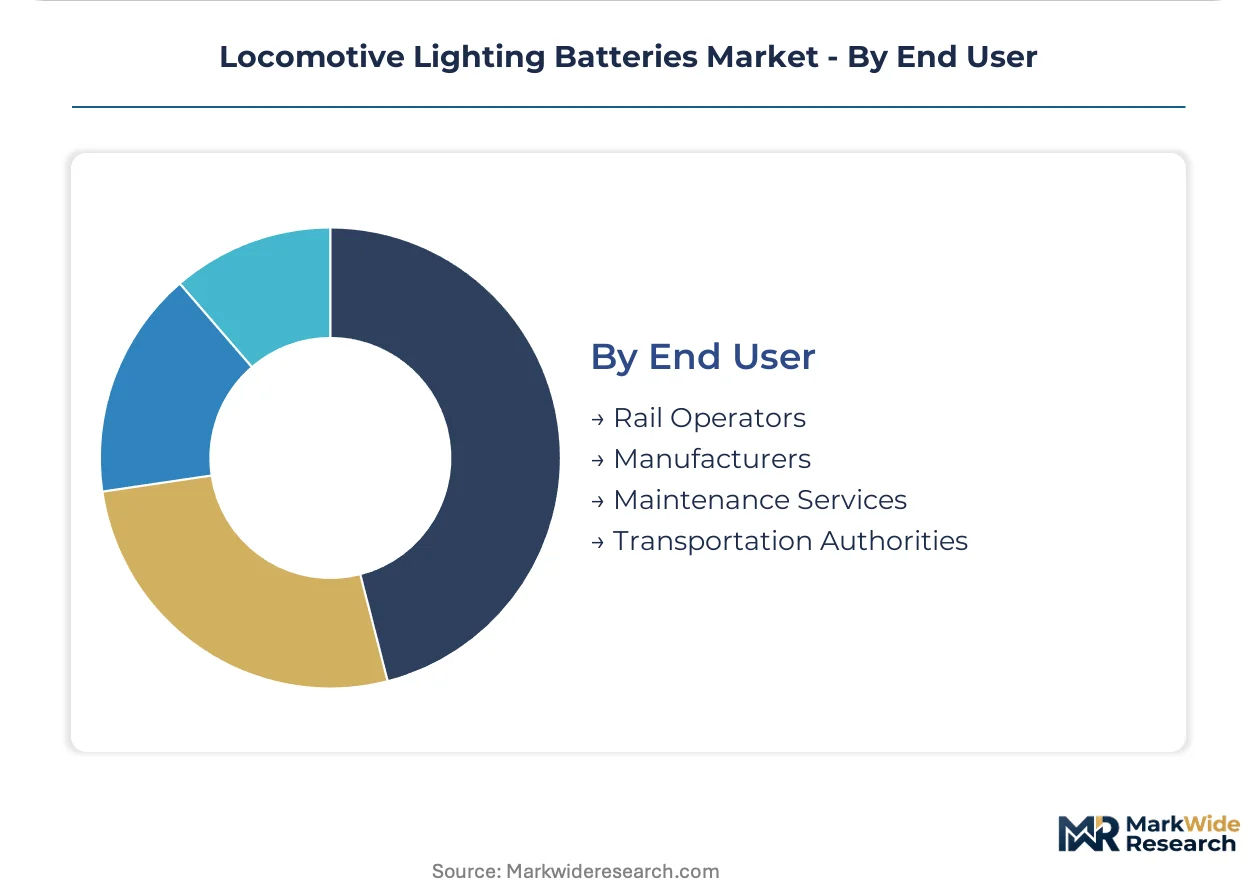
- Rail Operators:Class I railroads and national carriers like Indian Railways and Deutsche Bahn specify batteries directly in tender documents. These buyers are unbundling lighting procurement from locomotive OEM contracts to access specialized electrochemical suppliers.
- Manufacturers:Siemens Mobility, Alstom, and Stadler integrate batteries into complete lighting system architectures. Their supplier qualification programs emphasize electromagnetic compatibility certification and REACH documentation for European deliveries.
- Maintenance Services:Third-party overhaul contractors perform battery replacement during scheduled locomotive shop visits. These intermediaries prioritize inventory availability and standardized form factors across multiple locomotive classes.
- Transportation Authorities:Regional transit agencies in Germany, France, and Japan specify lighting systems for commuter rail fleets. Their procurement emphasizes whole-life cost models incorporating recycling obligations under EU Battery Passport frameworks.
Rail operators control the largest procurement volume; transportation authorities are specifying advanced systems most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate processing clusters in Chile's Atacama Desert and cobalt refining capacity in the Democratic Republic of Congo anchor upstream material flows for battery manufacturers serving rail electrification programs worldwide.
United States
Class I railroads Union Pacific and BNSF operate over 140,000 route miles of non-electrified freight corridors. FRA emergency lighting duration mandates compress replacement cycles for aging lead acid battery banks. Chicago's rail hub concentrates aftermarket battery distribution for Midwest freight terminals.
Germany
Deutsche Bahn's fleet modernization program drives nickel-based and lithium-ion procurement for passenger rolling stock. EU F-Gas Regulation and REACH compliance shape material selection and recycling obligations for domestic suppliers. Siemens Mobility anchors battery integration demand from its Munich and Berlin manufacturing centers.
India
Indian Railways' electrification targets generate procurement volume for advanced lead acid and lithium-ion systems in new-build passenger coaches. BIS certification mandates accelerate domestic manufacturing qualification. Integral Coach Factory in Chennai and Rail Coach Factory in Kapurthala concentrate rolling stock production requiring localized battery supply.
Japan
East Japan Railway and West Japan Railway specify high-reliability lighting systems for Shinkansen and commuter fleets. METI energy efficiency standards drive lithium-ion adoption in new-build applications. Kawasaki and Nagoya house rolling stock manufacturing clusters with integrated battery specification authority.
China
China State Railway Group operates the world's largest electrified network with expanding high-speed passenger corridors. GB standards and MIIT battery safety regulations govern domestic procurement specifications. CRRC's manufacturing footprint in Changchun, Qingdao, and Zhuzhou concentrates demand for qualified lighting battery suppliers.
Locomotive Lighting Batteries Market Competitive Landscape
Global majors compete with regional champions across chemistry specialization and rail network relationships. The vendor base separates into three tiers: integrated electrochemical conglomerates with rail-specific divisions, dedicated industrial battery specialists, and emerging lithium-ion technology providers. Consolidation pressure intensifies as battery management system integration requirements raise R&D barriers. Dominant competitive moves include backward integration into cell manufacturing and strategic partnerships with rolling stock OEMs for co-development of smart lighting architectures.
Within the integrated electrochemical tier, EnerSys and Saft exemplify divergent geographic anchoring strategies. EnerSys leverages its North American industrial motive power infrastructure to serve Class I railroad procurement programs. Saft occupies a position as the European specialist in nickel-based chemistries for rolling stock applications with stringent vibration specifications. Exide Technologies represents the scale-driven archetype competing on manufacturing footprint in lead acid replacement segments where capital-constrained freight operators delay chemistry conversion.
| Leading Market Players |
|---|
| Saft |
| EnerSys |
| Exide Technologies |
| GS Yuasa Corporation |
| Panasonic Corporation |
| BYD Company Ltd. |
| Hoppecke Batterien Gmbh & Co. Kg |
| A123 Systems |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Cobalt cathode precursors and lithium carbonate feed from Chilean and Australian mining operations through Chinese cell formation facilities before reaching tiered pricing structures in North American and European rail procurement channels. This upstream concentration in critical mineral processing creates asymmetric pricing power that propagates through battery management system integration premiums downstream.
Pricing Analysis
Warranty bundling separates premium-tier suppliers offering full lifecycle service contracts from economy-tier vendors selling cells without predictive maintenance telemetry. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and BMS firmware sophistication, with Deutsche Bahn and Indian Railways specifications commanding premiums for REACH-compliant material documentation. Cost compression in the lead acid replacement segment is intensifying because freight operators delay lithium-ion conversion amid charging infrastructure lock-in. Class I railroads in North America exhibit highest price sensitivity due to capital budget cycles, while European passenger operators prioritize whole-life cost models over unit procurement.
Supply Chain Analysis
Rail-specific electromagnetic compatibility certification and FRA safety validation gate supplier qualification, extending product development timelines for non-incumbent entrants. Cell manufacturing concentrates in China, South Korea, and Japan, with Germany and the United States hosting final pack assembly and system integration. The supply chain draws from cobalt refining capacity in the Democratic Republic of Congo and lithium carbonate processing in Chile's Atacama Desert. Single-source vulnerability in cathode active material supply creates exposure to export restriction risk. Distribution runs through regional rail OEM workshops and direct procurement programs established by Union Pacific, BNSF, and Deutsche Bahn.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cell manufacturing capacity for rail-grade vibration specifications remains concentrated among incumbent suppliers, propping pricing power for nickel-based and lithium-ion systems through the analysis window.
For Market Incumbents: To counter disintermediation as rail operators unbundle lighting procurement from locomotive OEM contracts, deepen direct technical qualification relationships with Class I railroads and Indian Railways. Prioritize backward integration into cell formation capacity in Germany or the United States to reduce exposure to Chinese supply chain disruption. Invest in BMS firmware certification under FRA electromagnetic compatibility standards to extend qualification moats. For New Entrants and Emerging Players: Enter via aftermarket service unbundling for North American freight retrofit channels where existing lead acid charging infrastructure delays chemistry conversion. Target maintenance-of-way equipment specifications requiring vibration resistance to 5 Grms, a segment with lower incumbent saturation than passenger rolling stock. Pursue battery-as-a-service revenue models transferring cycle life risk from capital-constrained rail operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor advanced lead acid specialists with carbon-enhanced electrode patents in India, where Railways Board electrification targets accelerate procurement volume. Long-term viability hinges on lithium-ion chemistry migration completion in European passenger fleets. Watch Deutsche Bahn supplier panel consolidation as the inflection signal for qualification barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Management System Integration | Embedded telemetry for Union Pacific and BNSF predictive maintenance programs commands premium pricing tiers. |
| Backward Integration into Cell Formation | In-house cathode production reduces exposure to DRC cobalt and Chilean lithium carbonate volatility. |
| Rail-Specific Certification Investment | FRA electromagnetic compatibility validation extends product launch timelines but locks out unqualified competitors. |
| Aftermarket Service Unbundling | Battery-as-a-service models transfer cycle life risk from Indian Railways and Deutsche Bahn to suppliers. |
| Geographic Manufacturing Footprint | Localized pack assembly in Chennai and Kapurthala satisfies Indian BIS certification mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with rail procurement officers, battery system engineers, rolling stock OEM qualification managers, and aftermarket service contractors. FRA safety protocol documentation, EU REACH registration databases, Indian BIS certification records, and Deutsche Bahn tender specifications provided secondary validation. Bottom-up volume modeling across chemistry types, vehicle classes, and procurement channels triangulated against top-down rail electrification program targets.
Granularity-level modeling specified lithium-ion, lead acid, nickel cadmium, and advanced lead acid chemistries at the cell level, with battery management system integration depth as a cross-cutting dimension. Passenger train, freight train, maintenance-of-way equipment, and switch locomotive applications were modeled separately. CAGRs derived from replacement cycle compression under FRA mandates and chemistry migration curves in European and Indian fleets. Raw material cost indices for cobalt and lithium carbonate informed pricing trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt export restriction scenarios or accelerated REACH compliance timeline revisions. Forecasts reflect documented assumptions regarding rail electrification program execution and lithium-ion thermal management qualification rates. A model refresh is warranted upon material change in FRA emergency lighting duration mandates or EU Battery Passport implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steering Column Module Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Trailer Landing Gear Market