
 Tailgate Chip Spreader Market | 2026-2036
Tailgate Chip Spreader Market Size, Share, and Industry Trends Forecast 2026-2036
Tailgate Chip Spreader Market Insights
Market Context
The capital-intensity divergence between integrated manufacturers and assembly-focused competitors is rotating competitive dynamics across the tailgate chip spreader landscape. Wirtgen Group leverages its vertical manufacturing footprint to control component costs and delivery timelines. Caterpillar anchors its position through extensive dealer networks that dominate North American municipal procurement channels. LeeBoy specializes in compact, maneuverable units tailored to county-level road crews with constrained budgets.
Technical Definition and Segment Structure
A tailgate chip spreader is a truck-mounted or trailer-towed aggregate distribution device engineered to meter stone chips, gravel, or seal coat materials across variable widths, typically employing conveyor belts, spinner discs, or auger-fed delivery systems calibrated to 0.1-pound-per-square-yard precision for road surface treatments. The equipment serves primarily in chip seal applications, pavement preservation, and surface dressing operations where uniform aggregate placement determines roadway longevity. Hydraulic systems dominate contractor fleets due to proven reliability under continuous duty cycles, while electric drive configurations are gaining traction among municipal authorities facing tightening emissions protocols. Equipment rental channels capture disproportionate volume from seasonal landscaping and agricultural users who resist capital ownership.
Regulatory Environment and Outlook
EPA Tier 4 Final emissions standards and OSHA workplace noise regulations constrain diesel-powered unit deployment across United States job sites, compelling manufacturers to certify alternative powertrains. The Federal Highway Administration's surface treatment specifications and state-level DOT material placement standards dictate spread width accuracy and calibration protocols that equipment must satisfy for contract eligibility. Stakeholders must monitor evolving electrification mandates and infrastructure spending authorization timelines to align production capacity with procurement cycles.
Market Dynamics
Fleet electrification mandates from state Departments of Transportation are forcing manufacturers to reconfigure powertrain architectures while maintaining the calibration precision that chip seal applications demand.
Growth Catalysts
- IIJA Infrastructure Funding:The Infrastructure Investment and Jobs Act channels federal dollars toward pavement preservation programs, expanding municipal equipment procurement budgets across state DOTs.
- Telematics Integration:Real-time spread-width monitoring and GPS-tracked material usage are becoming standard specifications in municipal RFPs, driving replacement cycles.
- Surface Treatment Volume:County-level road agencies are extending chip seal programs to defer full-depth reconstruction, sustaining equipment utilization rates.
Market Restraints
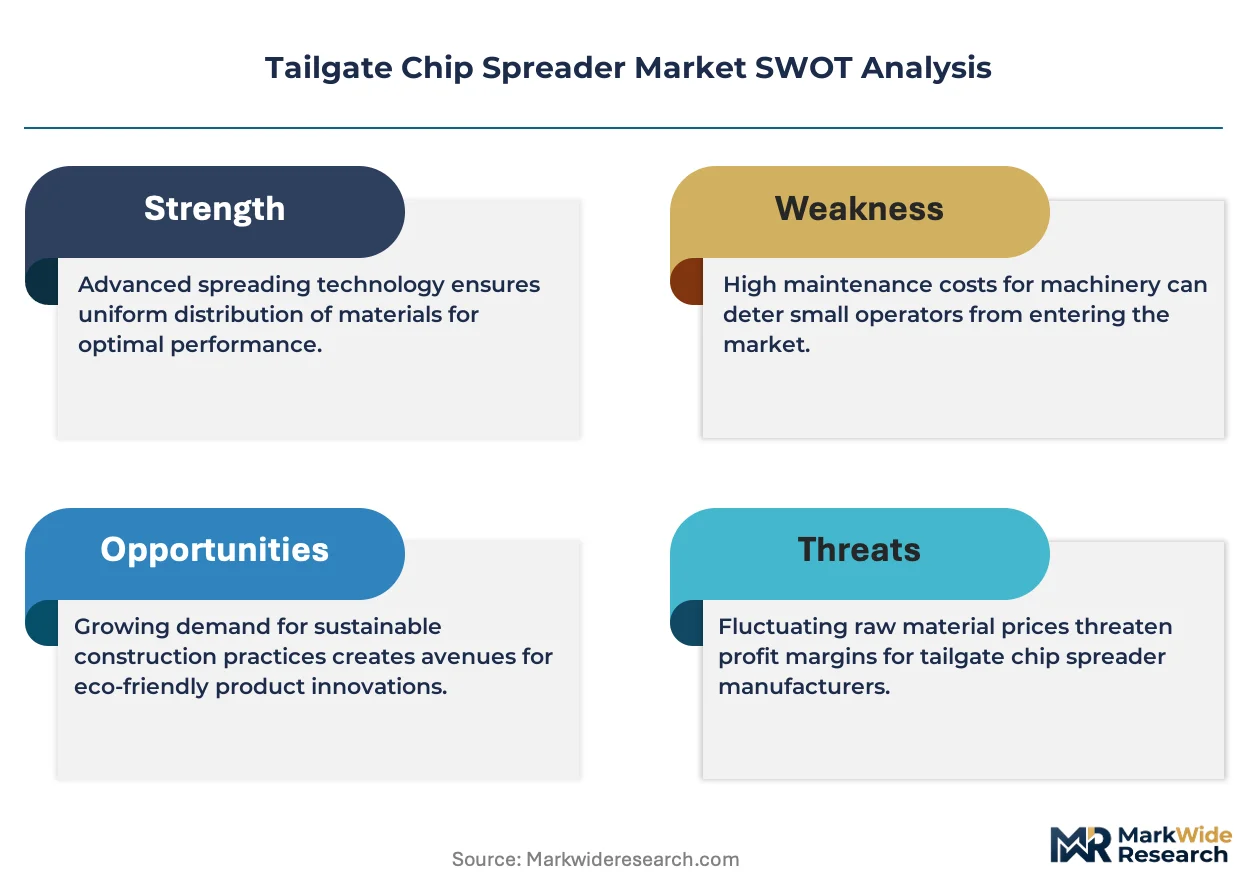
- Steel Input Volatility:Conveyor belt frames and hopper assemblies face cost pressure from fluctuating hot-rolled steel prices, compressing margins for fabricators without long-term supply agreements.
- Hydraulic Component Concentration:Precision metering pumps and valve assemblies rely on a concentrated supplier base in the Midwest industrial corridor, creating single-source vulnerability.
- EPA Tier 4 Compliance Costs:Diesel engine aftertreatment systems add substantial cost to conventional powertrains, narrowing the price gap with emerging electric alternatives.
Strategic Opportunities
- Battery-Electric Powertrains:Zero-emission mandates in California and New York create first-mover advantage for manufacturers certifying electric drive systems for municipal fleets.
- Rental Channel Expansion:Equipment rental networks are adding chip spreaders to surface treatment fleets, capturing seasonal demand from landscaping contractors without capital purchase.
- Precision Agriculture Crossover:Variable-rate spreader technology developed for road applications is finding adoption in vineyard and orchard fertilization operations.
Industry Challenges
- Calibration Technician Shortage:Municipal garages lack personnel trained to maintain 0.1-pound-per-square-yard accuracy specifications, forcing reliance on manufacturer service networks.
- Legacy Fleet Integration:Electric spreader units require voltage compatibility assessments with existing truck chassis, complicating retrofit procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tailgate Chip Spreader Market |
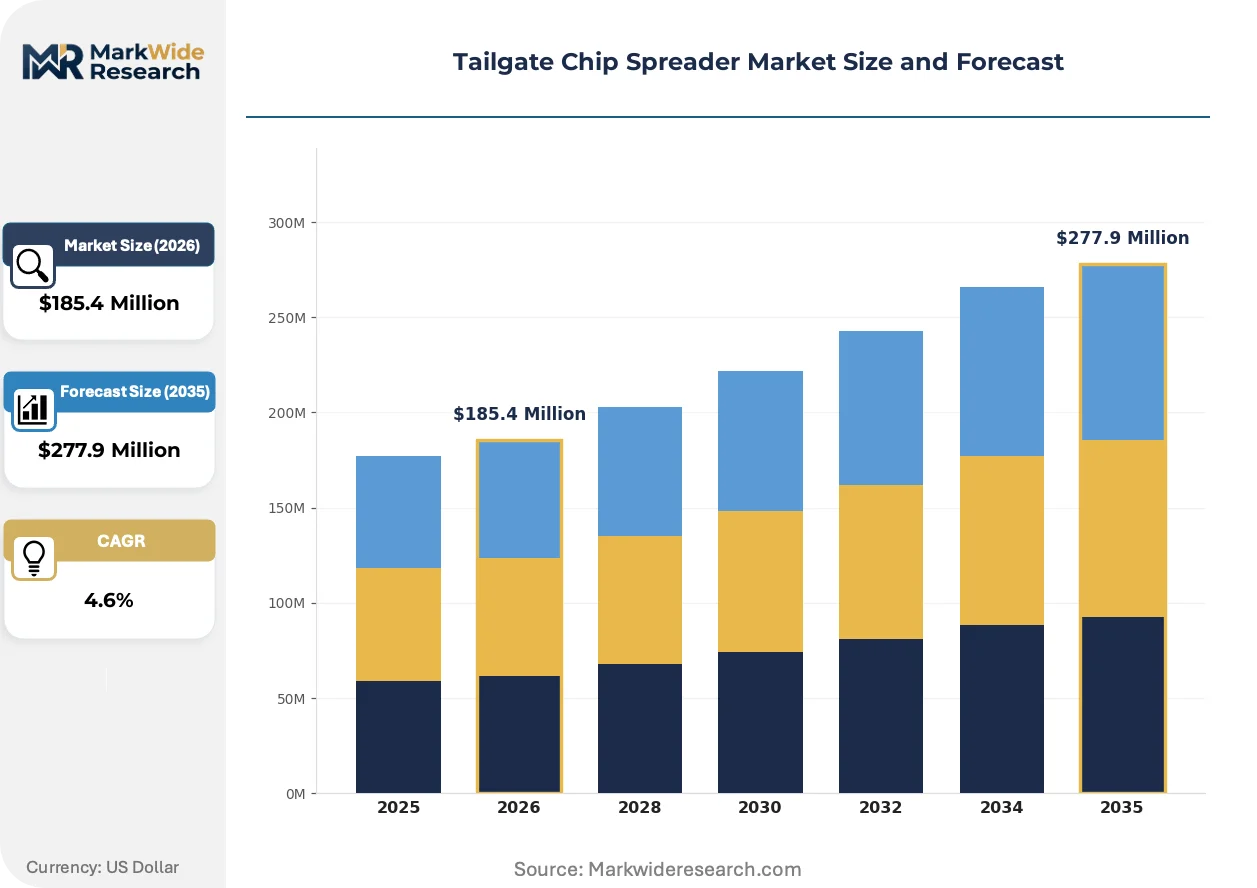
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $277.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electric, Manual Application: Road Repair, Construction Sites, Landscaping, Agricultural Fields End User: Contractors, Municipal Authorities, Farm Operators, Landscaping Firms Distribution Channel: Dealerships, Online Retailers, Equipment Rental, Direct Sales |
| Companies Covered | Wirtgen Group, Caterpillar, Volvo Construction Equipment, FAYAT, Iveco, SANY Group, Astec, K-Tec Earthmovers, LeeBoy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tailgate Chip Spreader Market Trends and Innovations
Electrification is rewriting equipment specifications while telematics and automated calibration reshape how agencies verify performance. Manufacturers must now engineer for emissions compliance without sacrificing the mechanical reliability that road crews depend on.
Electric drive configurations are displacing hydraulic systems in municipal procurement specifications. State DOTs in California and New York now require zero-emission equipment for new fleet additions. Battery-powered spreaders eliminate hydraulic fluid contamination risks while simplifying maintenance protocols for understaffed municipal garages.
EPA Tier 4 Final standards are accelerating aftertreatment system adoption across diesel-powered contractor fleets. Off-road equipment faces the same emissions scrutiny as on-highway trucks. Rental companies are responding by diversifying into electric units to avoid compliance complexity and maintenance downtime.
Performance-based contracting is altering how agencies specify equipment capabilities. Municipalities are unbundling spreader calibration verification from equipment purchase, contracting third-party testing services instead. This shift is most pronounced in Texas and Florida, where county road departments lack in-house metrology capabilities.
Tailgate Chip Spreader Market Segmentation
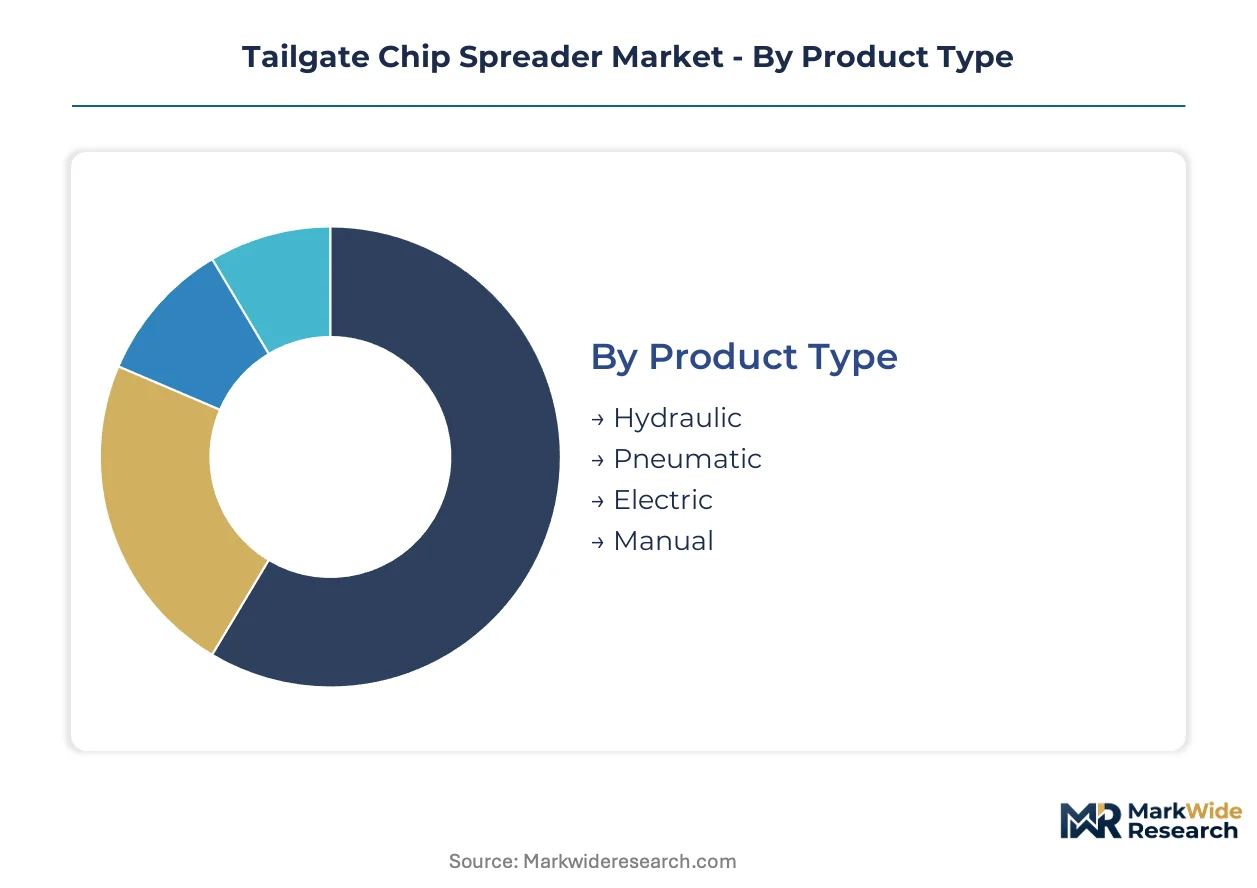
Tailgate chip spreader procurement patterns diverge sharply across powertrain technologies and buyer types. Municipal fleet managers prioritize emissions compliance and telematics integration, while agricultural users favor rental access and manual simplicity.
Product Type:
Hydraulic systems dominate domestic municipal procurement, whereas electric configurations are export-led to jurisdictions with zero-emission mandates.
- Hydraulic:Conveyor belt and spinner disc mechanisms powered by truck PTO or auxiliary diesel engines deliver calibrated aggregate flow under continuous duty cycles. State DOT garages across the Midwest and Southeast specify hydraulic reliability for chip seal programs spanning thousands of lane-miles annually. Hydraulic units face margin compression from Tier 4 aftertreatment costs and fluid contamination liability.
- Electric:Battery-powered drive systems eliminate hydraulic fluid leaks and simplify maintenance protocols for understaffed municipal fleets. California and New York procurement specifications now require zero-emission equipment for new fleet additions, creating concentrated demand on the coasts. Voltage compatibility assessments with existing truck chassis complicate retrofit decisions.
- Pneumatic:Compressed-air aggregate delivery suits specialized surface dressing operations requiring rapid material shutoff.
- Manual:Hand-cranked spreaders serve landscaping contractors and small agricultural users with intermittent, low-volume requirements.
Hydraulic holds the largest share; momentum sits with Electric.
Application:
Cost tier stratification separates high-specification pavement preservation from budget-constrained seasonal use.
- Road Repair:Chip seal and surface dressing operations demand 0.1-pound-per-square-yard calibration precision verified through third-party testing contracts. County road agencies in Texas and Florida extend pavement preservation programs to defer full-depth reconstruction, sustaining equipment utilization. Performance-based contracting is unbundling calibration verification from equipment purchase.
- Construction Sites:Temporary access roads and haul road maintenance require durable spreaders capable of abrasive aggregate handling. Infrastructure Investment and Jobs Act funding is expanding contractor fleet procurement budgets across state DOT programs.
- Landscaping:Seasonal decorative gravel and mulch distribution favors rental channel access over capital ownership.
- Agricultural Fields:Vineyard and orchard fertilization operations are adopting variable-rate spreader technology developed for road applications.
Road Repair commands premium pricing; Landscaping is expanding most quickly through rental penetration.
End User:
Customer type determines specification complexity, with municipal authorities driving telematics requirements and farm operators prioritizing mechanical simplicity.
- Contractors:Commercial paving firms specify hydraulic reliability for continuous duty cycles and dealer service network proximity. EPA Tier 4 Final compliance costs are narrowing the price gap with electric alternatives, prompting powertrain reassessment.
- Municipal Authorities:State and county DOTs mandate GPS-tracked material usage and real-time spread-width monitoring in RFP specifications. California and New York zero-emission fleet mandates are accelerating electric adoption despite voltage compatibility challenges with legacy chassis.
- Farm Operators:Vineyard and orchard managers favor manual or compact hydraulic units for variable-rate fertilization with minimal capital outlay.
- Landscaping Firms:Seasonal demand patterns drive rental channel preference, with equipment utilization concentrated in spring and fall months.
Municipal Authorities represent the highest-value segment; Contractors are gaining share fastest through IIJA-funded procurement.
Distribution Channel:
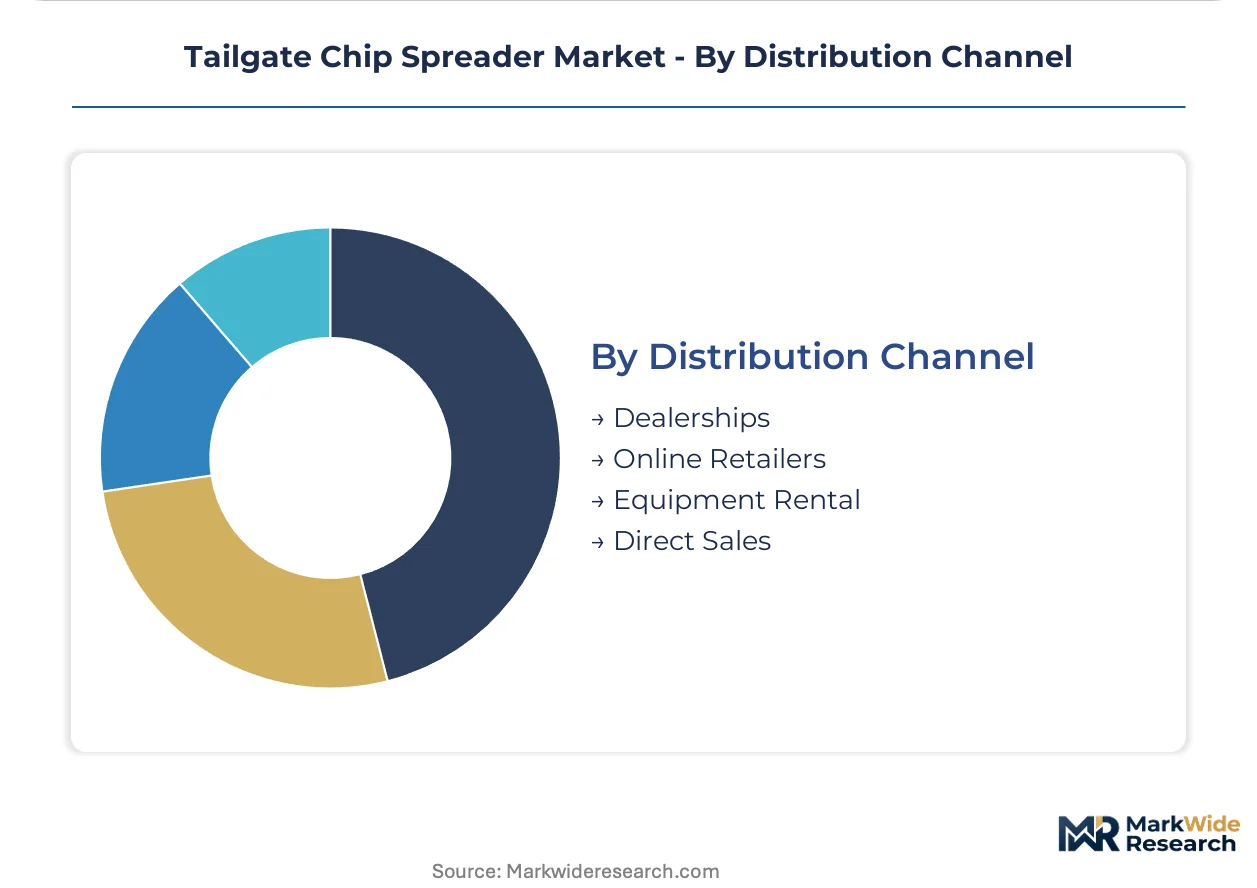
Supply concentration varies by channel, with dealer networks anchoring municipal procurement and rental platforms capturing seasonal volatility.
- Dealerships:Caterpillar and Wirtgen dealer networks dominate North American municipal procurement channels through established service relationships and parts availability. State DOT procurement programs route volume through authorized dealers with certified calibration technician support.
- Equipment Rental:United Rentals and regional platforms are adding chip spreaders to surface treatment fleets, capturing seasonal demand from landscaping contractors without capital purchase. Rental companies diversify into electric units to avoid Tier 4 compliance complexity.
- Online Retailers:E-commerce platforms serve small agricultural users and landscaping firms with manual and compact pneumatic units.
- Direct Sales:Large contractor fleets and multi-county municipal consortiums negotiate manufacturer-direct pricing for volume procurement.
Dealerships hold the largest share; Equipment Rental is climbing the fastest as seasonal users resist capital ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes tailgate chip spreaders through state-level Department of Transportation procurement programs, while Germany and China deploy the equipment through contractor-led infrastructure maintenance models.
United States
State DOTs in Texas and Florida drive volume through county-level pavement preservation programs that defer full-depth reconstruction. The Federal Highway Administration's surface treatment specifications mandate spread-width accuracy for contract eligibility. Equipment clusters concentrate in the Midwest industrial corridor where hydraulic component suppliers maintain proximity to fabricators.
Germany
Deutsche Bahn and federal highway maintenance contracts sustain demand for precision-calibrated aggregate distribution equipment. The EU Green Deal and national emissions standards push municipal fleets toward electric alternatives. Industrial fabrication centers in North Rhine-Westphalia host precision metering pump suppliers serving road machinery manufacturers.
China
Provincial highway bureaus in Sichuan and Shandong expand chip seal programs across national road networks. MIIT emissions standards for off-road equipment accelerate hydraulic-to-electric transitions in state-owned fleet procurement. Manufacturing gravity centers on the Yangtze River Delta where conveyor belt and hopper assembly suppliers cluster.
Canada
Provincial transportation ministries in Ontario and Alberta renew municipal fleet contracts through infrastructure stimulus allocations. Environment and Climate Change Canada regulations constrain diesel-powered deployment in urban maintenance zones. Equipment distribution channels anchor in the Toronto-Waterloo corridor serving eastern provincial markets.
Australia
State road authorities in New South Wales and Victoria sustain equipment utilization through rural road network preservation programs. The country's national environmental regulator imposes emissions protocols on off-road diesel machinery in metropolitan jurisdictions. Perth-based contractors serve mining haul road maintenance with durable abrasive-handling spreader configurations.
Tailgate Chip Spreader Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence rotating competitive dynamics across the landscape. Wirtgen Group leverages vertical manufacturing footprints to control component costs and delivery timelines. Caterpillar anchors position through extensive dealer networks that dominate municipal procurement channels. LeeBoy occupies the compact equipment tier tailored to county-level road crews with constrained budgets. Competitive moves concentrate on telematics integration and electric powertrain certification to satisfy zero-emission mandates.
Among integrated heavy machinery manufacturers, Wirtgen Group and Caterpillar exemplify the capital-intensive archetype with captive supply chains and established service infrastructures. Volvo Construction Equipment and SANY Group represent the geographic diversification strategy, with Swedish and Chinese origins respectively, positioning to capture regional procurement preferences. LeeBoy occupies the specialist tier focused on maneuverable units for constrained municipal budgets. FAYAT and Astec exemplify portfolio-diversified industrial groups that cross-leverage surface treatment technologies across road machinery segments.
| Leading Market Players |
|---|
| Wirtgen Group |
| Caterpillar |
| Volvo Construction Equipment |
| FAYAT |
| Iveco |
| SANY Group |
| Astec |
| K-Tec Earthmovers |
| LeeBoy |
| Others |
Pricing and Supply Chain Analysis
Electric drive systems displacing hydraulic powertrains are redrawing supplier maps from the Midwest industrial corridor toward battery manufacturing clusters, simultaneously compressing margins on legacy Tier 4 diesel configurations while opening premium pricing tiers for zero-emission certified units.
Pricing Analysis
Long-term municipal offtake agreements dominate procurement, with state DOTs negotiating multi-year fleet contracts that lock in calibration service bundles and parts availability. Price differentiation hinges on telematics integration density and EPA Tier 4 Final compliance certification, with electric configurations commanding premiums in California and New York procurement channels. Cost compression in hydraulic tiers intensifies because steel input volatility and aftertreatment system expenses erode fabricator margins. County road agencies exhibit the highest price sensitivity, deferring replacement cycles when federal infrastructure allocations tighten.
Supply Chain Analysis
Inventory cycles for precision metering pumps and conveyor belt assemblies stretch lead times when hydraulic component suppliers in the Midwest industrial corridor face capacity constraints. Manufacturing concentrates in the United States, Germany, and China, with conveyor belt and hopper fabrication anchored in the Yangtze River Delta and North Rhine-Westphalia. The supply chain rests on hot-rolled steel, lithium-ion battery cells, and precision hydraulic valve assemblies. Single-source vulnerability in precision metering pump suppliers creates concentration risk. Distribution runs through authorized dealer networks for municipal procurement and rental platforms for seasonal contractor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies an early-cycle expansion phase, with IIJA infrastructure funding accelerating fleet renewal velocity across state DOT procurement programs.
For Market Incumbents: Secure captive supply agreements for battery cells and precision hydraulic components to insulate margins from commodity volatility and single-source vulnerability. Deepen backward integration into conveyor belt fabrication to control delivery timelines against steel price swings. Defensive consolidation through acquisition of regional calibration service providers addresses the technician shortage threatening aftermarket revenue streams.
For New Entrants and Emerging Players: Anchor in the equipment rental channel, where seasonal landscaping demand and Tier 4 compliance avoidance create white-space opportunity without direct competition from integrated manufacturers. Target county-level road agencies in Texas and Florida with compact electric units that bypass legacy chassis voltage compatibility constraints. Pursue precision agriculture crossover applications as a go-to-market angle, leveraging variable-rate spreader technology for vineyard and orchard fertilization operations.
For Investors and Strategic Acquirers: The market sits at an infrastructure stimulus phase that favors specialist fabricators with electric powertrain certification and established dealer service relationships. Long-term viability hinges on alignment with zero-emission fleet mandates and telematics integration capabilities. Acquisition targets should demonstrate calibration technician training infrastructure and state DOT contract eligibility. The signal to watch is California Air Resources Board electrification timeline acceleration as an inflection indicator for national procurement specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Certification | California and New York zero-emission mandates create first-mover procurement advantage for certified municipal fleet suppliers. |
| Telematics Platform Integration | GPS-tracked material usage and real-time spread-width monitoring satisfy performance-based contracting specifications in Texas and Florida. |
| Calibration Service Network Expansion | Third-party testing contracts address municipal garage technician shortages while securing recurring revenue streams. |
| Rental Channel Partnership | United Rentals and regional platforms capture seasonal landscaping demand without capital purchase barriers. |
| Precision Agriculture Technology Transfer | Variable-rate spreader systems developed for road applications unlock vineyard and orchard fertilization market entry. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, state DOT procurement databases, and trade association equipment shipment records, combining interviews with municipal fleet managers, OEM procurement teams, and aftermarket service heads with bottom-up and top-down triangulation. Primary engagement spanned maintenance directors at county road agencies, plant engineers at conveyor belt fabricators, and rental platform category managers. Secondary validation drew from Federal Highway Administration surface treatment specifications, EPA Tier 4 Final compliance filings, and infrastructure spending authorization timelines.
Segmentation dimensions modeled include powertrain technology, end-user archetype, application intensity, and distribution channel structure across the projection horizon. CAGRs derive from equipment replacement cycle analysis, fleet electrification mandate adoption curves, and federal infrastructure allocation trajectories. Forecast inputs incorporate state-level DOT budget authorization patterns, steel price volatility indices, and battery cost decline trajectories for off-road equipment applications.
Material uncertainties — steel input cost spikes, electrification mandate acceleration or delay, and hydraulic component supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure spending continuity and emissions regulatory stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
EGR Valve Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Car Modification Market
Vehicle Components
Global Bearings Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market