
 UK Automotive Carbon Fiber Composites Market | 2026-2036
UK Automotive Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Carbon Fiber Composites Market Analytics
The UK government's zero-emission vehicle mandate is decoupling automotive material selection from traditional steel-intensive paradigms. Hexcel Corporation leverages its prepreg expertise to supply Tier-1 structural programs across British EV platforms. SGL Carbon anchors carbon fiber supply for battery enclosure architectures through its European manufacturing network. Toray Industries competes on tow-size specialization, positioning high-modulus grades for premium chassis applications where stiffness-to-weight ratios dominate engineering specifications.
UK automotive carbon fiber composites combine thermoset or thermoplastic resin matrices with carbon fiber reinforcements, typically achieving tensile strengths exceeding 1,500 MPa and density below 1.6 g/cm³, primarily to reduce vehicle mass while maintaining crash structural integrity. Prepreg formulations dominate current OEM qualification pathways due to controlled resin content and repeatable autoclave processing, though sheet molding compounds are gaining traction in high-volume body panel programs where compression molding cycle times compress manufacturing economics. Automated fiber placement technology leads capital investment patterns among Midlands-based vehicle assemblers seeking to integrate complex geometries without manual layup labor intensity, while vacuum infusion retains share in aftermarket providers serving low-volume motorsport and restoration segments.
The UK's Vehicle Certification Agency enforces UN ECE regulations governing material flammability and occupant protection, while HSE mandates govern resin handling and volatile organic compound emissions in manufacturing facilities. BSI standards for composite material characterization shape supplier qualification protocols, creating compliance barriers for non-UK-certified feedstock entrants. Stakeholders must monitor evolving post-Brexit alignment between UKCA marking requirements and retained EU REACH substance restrictions, as divergence in chemical authorization pathways would fragment supply chain qualification costs across dual regulatory frameworks.
Market Dynamics
Electric vehicle platform architectures are forcing a recalibration of material performance specifications across British OEM supply chains, decoupling structural design from steel-intensive legacy paradigms.
Growth Catalysts
- Zero-emission vehicle mandate:UK government regulations compel OEMs to lightweight powertrain structures, accelerating carbon fiber qualification for battery enclosures and chassis components.
- Midlands manufacturing corridor concentration:Specialist motorsport engineering clusters provide adjacent capabilities that transfer to road car programs, compressing development timelines for structural composite applications.
- Thermoplastic resin systems:Out-of-autoclave processing technologies enable cycle time reductions that align carbon fiber economics with high-volume EV production targets.
Market Restraints
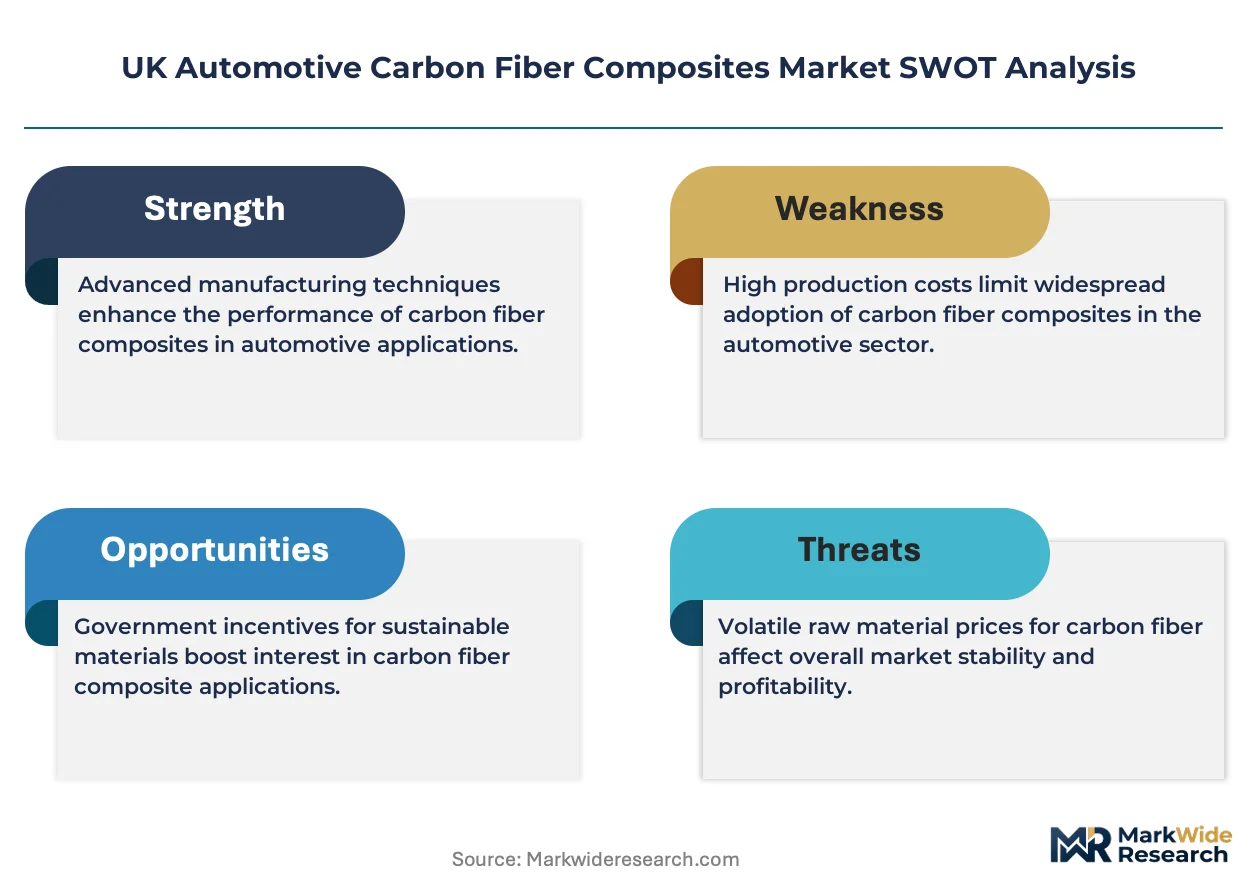
- Acrylonitrile feedstock volatility:Precursor carbon fiber costs fluctuate with petrochemical input prices, constraining margin predictability for Tier-1 suppliers serving price-sensitive body panel programs.
- Single-source prepreg concentration:Qualified material supply for crash-critical structural applications concentrates among limited UKAS-certified processors, amplifying disruption risk from facility outages.
- Aluminum-intensive platform competition:Established joining technologies and recycling infrastructure for aluminum sheet structures present substitution pressure in non-premium vehicle segments.
Strategic Opportunities
- Northern England supplier development:Underutilized composites manufacturing capacity in South Yorkshire and Tyneside offers expansion vectors for battery enclosure production serving Scottish EV assembly operations.
- Automated fiber placement convergence:Robotics integration with in-situ consolidation processes enables geometric complexity previously requiring manual layup, opening architectural applications in A-pillar and roof bow structures.
- UKCA marking alignment arbitrage:Regulatory consultancy services addressing post-Brexit divergence between retained EU REACH substance restrictions and emerging British chemical authorization pathways create service revenue pools.
Industry Challenges
- Autoclave technician scarcity:Specialized curing process expertise concentrates among aging workforce cohorts in Motorsport Valley, constraining capacity scaling for qualified structural component output.
- OEM qualification timeline compression:Crashworthiness validation protocols under UN ECE regulations demand extended testing cycles that misalign with accelerated EV platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Carbon Fiber Composites Market |
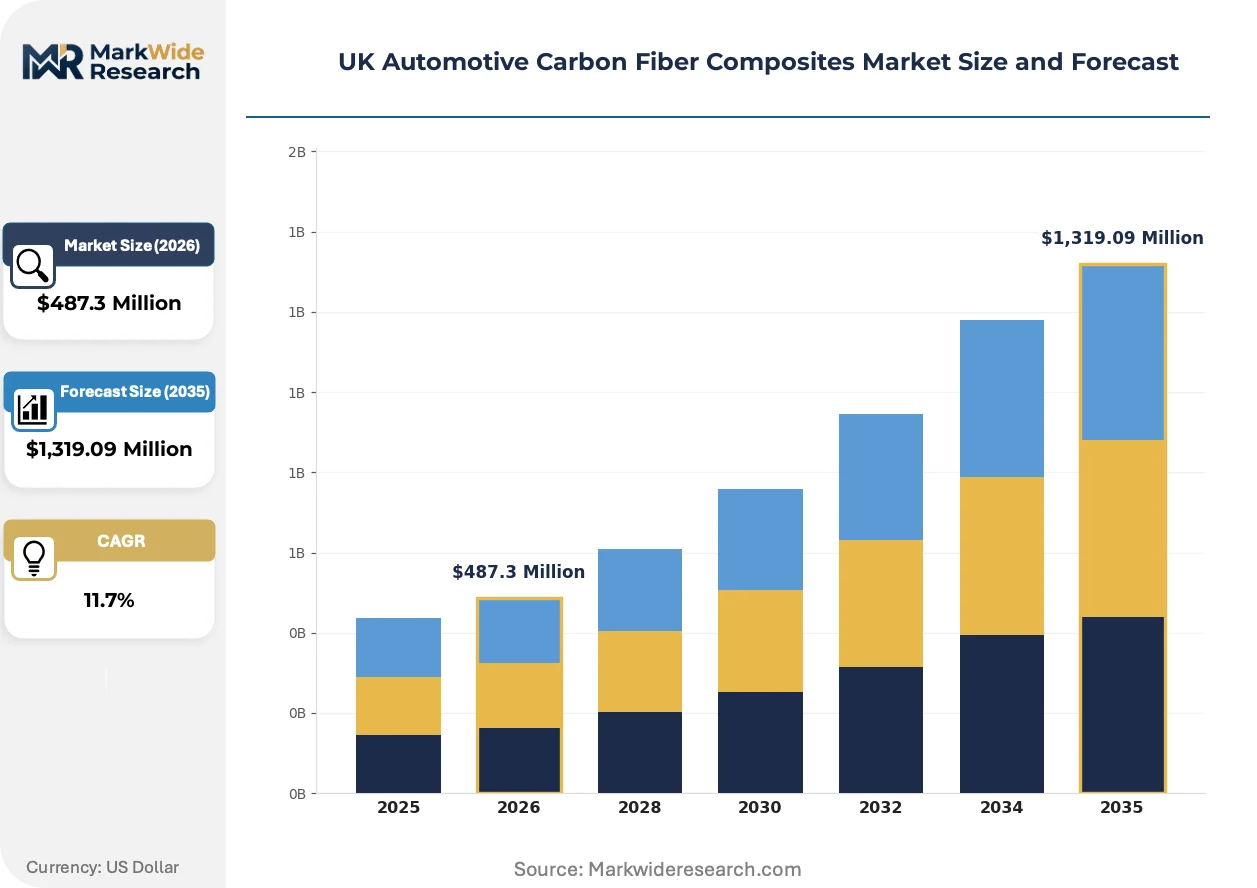
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Plastics, Prepregs, Sheet Molding Compounds, Continuous Fiber Application: Body Panels, Chassis, Interior Components, Structural Parts End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Automated Fiber Placement, Resin Transfer Molding, Vacuum Infusion, Hand Layup |
| Companies Covered | Hexcel Corporation, SGL Carbon, Toray Industries, Mitsubishi Chemical Carbon Fiber and Composites, Teijin Limited, Solvay, Sigmatex, BASF, Toho Tenex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Carbon Fiber Composites Market Evolving Landscape
Process automation and regulatory stringency are jointly compressing the viable technology set for structural automotive composites, privileging solutions that reconcile cycle economics with crash performance certification.
Thermoplastic composite tapes are converging with automated fiber placement systems to enable welded joint configurations that eliminate mechanical fastening weight penalties. Midlands-based EV assemblers are piloting these hybrid material-process combinations for floor pan structures. The convergence is compressing the cost gap between carbon fiber and aluminum intensive body architectures.
UKCA marking requirements for retained EU REACH substance restrictions are tightening chemical authorization documentation burdens on resin formulation suppliers. Industrial consequence includes extended qualification timelines for new matrix systems seeking OEM approval. Battery enclosure manufacturers are responding by consolidating supplier relationships with established UKAS-certified feedstock providers.
Direct OEM procurement of raw fiber and resin is displacing traditional Tier-1 compounder intermediation in high-volume structural programs. British EV platform engineering teams are establishing captive specifications for tow sizing and modulus grades. This pattern concentrates most visibly in premium chassis applications where stiffness-to-weight ratios dominate supplier selection criteria.
UK Automotive Carbon Fiber Composites Market Segmentation
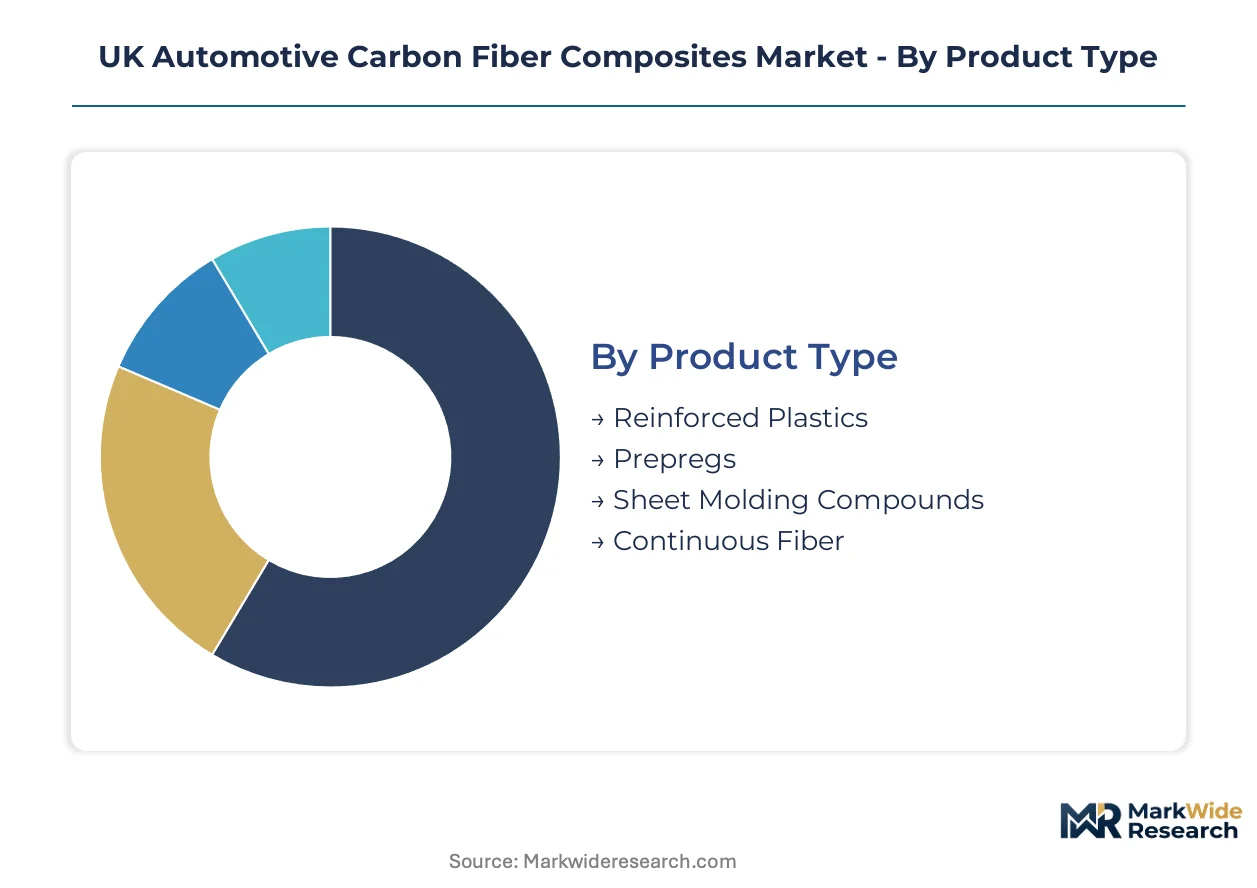
Carbon fiber qualification pathways diverge sharply across product forms and processing technologies, with UKAS certification requirements fragmenting supplier access by segment. OEMs structure procurement strategies around these certification moats, concentrating volume in pre-qualified material categories while screening experimental formats through motorsport-adjacent development programs.
Product Type:
UKCA marking obligations and retained EU REACH substance restrictions impose differentiated documentation burdens across material formats, with thermoset systems facing tighter chemical authorization scrutiny than emerging thermoplastic alternatives.
- Prepregs:Resin-impregnated fiber sheets with controlled volatile content and repeatable cure profiles dominate crash-critical structural qualifications. Midlands-based EV assemblers concentrate procurement here for battery enclosure programs requiring UN ECE R100 flammability certification. Autoclave processing requirements lock in qualified supplier relationships with UKAS-certified compounders.
- Sheet Molding Compounds:Chopped fiber-resin matrices enable compression molding cycle times below three minutes, aligning economics with high-volume body panel targets. Demand concentrates in South Yorkshire manufacturing corridors serving price-sensitive vehicle segments where aluminum substitution pressure is strongest.
- Reinforced Plastics:Short-fiber thermoplastic compounds integrate with injection molding infrastructure for non-structural interior brackets and housings.
- Continuous Fiber:Unidirectional tow and fabric formats supply automated fiber placement systems for geometrically complex chassis components.
Leading the category by volume: Prepregs. Growing fastest: Sheet Molding Compounds.
Application:
Structural performance requirements and crashworthiness validation intensity segment procurement priorities, with chassis applications commanding premium qualification investments and body panels competing on manufacturing throughput.
- Chassis:Battery enclosures, subframes, and crash structures demand the highest stiffness-to-weight ratios and absorb the most extensive UN ECE testing cycles. British EV platforms anchor specification development here, with direct OEM procurement of tow sizing and modulus grades displacing traditional Tier-1 intermediation. HSE resin handling mandates compound facility qualification costs.
- Structural Parts:A-pillars, roof bows, and floor pans integrate automated fiber placement with in-situ consolidation to eliminate mechanical fastening weight penalties. Midlands manufacturing clusters pilot these hybrid material-process combinations, compressing cost gaps with aluminum-intensive architectures.
- Body Panels:Hoods, roofs, and fenders prioritize surface finish and dent resistance over structural load-bearing, opening qualification pathways for faster-curing resin systems.
- Interior Components:Dashboard carriers, seat shells, and trim panels face less stringent crash performance requirements, enabling broader supplier participation.
Chassis commands the highest per-kilogram qualification investment. Body panels are expanding most quickly as compression molding economics improve.
End User:
Procurement authority concentration and technical specification control determine segment boundaries, with direct OEM engagement rising in premium platforms and Tier-1 suppliers retaining intermediation in volume programs.
- OEMs:British EV engineering teams increasingly specify raw fiber tow sizing, modulus grades, and resin formulations captive, bypassing traditional compounder margins in high-value chassis applications. This pattern concentrates where stiffness-to-weight ratios dominate supplier selection and platform architectures are greenfield.
- Tier-1 Suppliers:Structural integrators manage UKAS-certified prepreg qualification and autoclave processing for crash-critical components, absorbing OEM qualification timeline compression risks. Workforce scarcity in Motorsport Valley constrains their capacity scaling.
- Vehicle Assemblers:Midlands-based operations focus on automated fiber placement integration and geometric complexity resolution without manual layup labor intensity.
- Aftermarket Providers:Low-volume motorsport and restoration segments retain vacuum infusion processing with less stringent BSI certification requirements.
OEMs are capturing specification authority fastest. Tier-1 Suppliers retain the deepest qualified processing infrastructure.
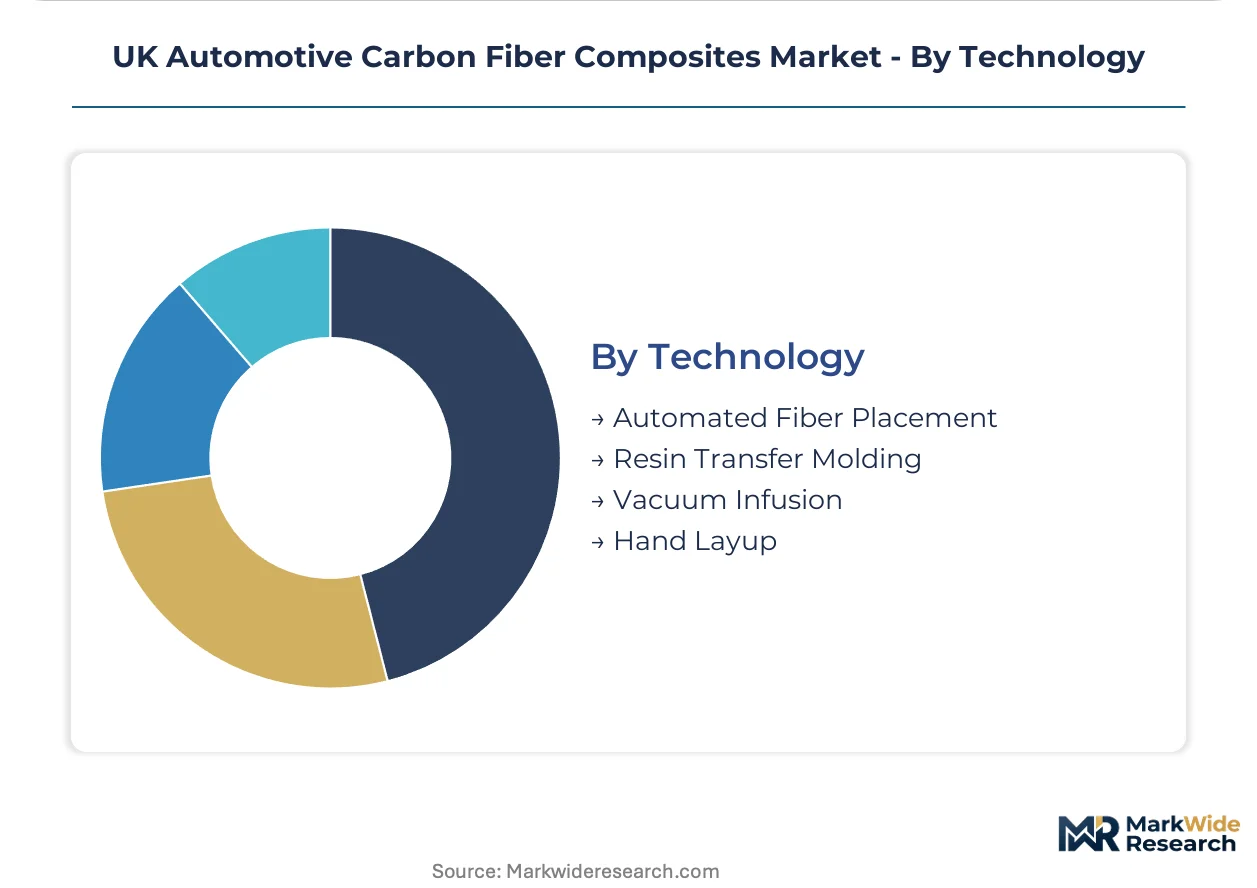
Technology:
Capital intensity and cycle time economics sort manufacturing methods by production volume targets, with automation investments concentrated where labor scarcity and geometric complexity intersect.
- Automated Fiber Placement:Robotic tow laying with in-situ consolidation enables complex curvature without manual labor, commanding capital investment from Midlands vehicle assemblers seeking to integrate A-pillar and roof bow architectures. The convergence with thermoplastic tapes is opening welded joint configurations.
- Resin Transfer Molding:Closed-mold injection processes suit medium-volume structural parts requiring consistent resin distribution and controlled void content.
- Vacuum Infusion:Open-mold resin draw-through retains share in aftermarket and motorsport applications where low tooling costs offset slower cycle times.
- Hand Layup:Manual fiber placement persists in prototype development and restoration segments with minimal automation requirements.
Automated Fiber Placement leads capital deployment. Resin Transfer Molding holds the steepest expansion trajectory as thermoplastic system adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midlands manufacturing corridor anchors UK automotive carbon fiber demand, with Birmingham-to-Northampton engineering clusters supplying both OEM assembly lines and adjacent motorsport fabricators.
Midlands
Battery enclosure programs and chassis subframes drive procurement from Birmingham-based EV assemblers. The Vehicle Certification Agency enforces UN ECE R100 flammability standards for crash-critical components. Coventry-to-Derby manufacturing belts concentrate automated fiber placement capacity serving Jaguar Land Rover and Aston Martin platforms.
South Yorkshire
Compression molding operations target high-volume body panel contracts from price-sensitive vehicle segments. HSE mandates govern resin handling and volatile organic compound emissions in Sheffield-Rotherham facilities. Underutilized composites capacity here offers expansion vectors for battery enclosure production.
Scotland
Scottish EV assembly operations generate pull-through demand for structural composite supply chains. UKCA marking requirements shape supplier qualification protocols for northbound component flows. Glasgow-Edinburgh corridors host emerging lightweight materials research programs aligned with zero-emission vehicle targets.
Wales
Specialist motorsport engineering in South Wales transfers capabilities to road car structural applications. Retained EU REACH substance restrictions govern resin formulation documentation for Welsh compounders. Deeside industrial zones host vacuum infusion providers serving low-volume restoration segments.
North East England
Tyneside manufacturing bases seek qualification for battery enclosure supply to Scottish and Midlands OEMs. BSI standards for composite material characterization create compliance barriers for non-UK-certified feedstock entrants. Newcastle-Sunderland corridors leverage offshore wind composites expertise for automotive crossover applications.
UK Automotive Carbon Fiber Composites Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification certification tiers, with UKAS-certified compounders commanding structural program pricing power over uncertified challengers. The vendor base stratifies between fiber precursor manufacturers, prepreg compounders, and finished component integrators. Two archetypes dominate: vertically integrated chemical conglomerates with captive carbon fiber supply, and specialist composites engineers with deep motorsport heritage. Competitive moves concentrate on thermoplastic resin system partnerships and automated fiber placement technology licensing.
Among US-based material science conglomerates, Hexcel Corporation occupies a position exemplifying prepreg qualification dominance for crash-critical structural programs. Japanese industrial groups Toray Industries and Mitsubishi Chemical Carbon Fiber and Composites represent the scale-driven archetype, anchoring high-modulus fiber supply for premium chassis applications where stiffness-to-weight ratios dictate procurement decisions.
| Leading Market Players |
|---|
| Hexcel Corporation |
| SGL Carbon |
| Toray Industries |
| Mitsubishi Chemical Carbon Fiber and Composites |
| Teijin Limited |
| Solvay |
| Sigmatex |
| BASF |
| Toho Tenex |
| Others |
Value Network & Pricing Analysis
Autoclave technician scarcity in Motorsport Valley amplifies labor-cost premiums that separate UKAS-certified structural prepreg suppliers from uncertified commodity compounders. This workforce concentration compresses margins at the premium tier while HSE resin-handling mandates inflate facility qualification costs that propagate through battery enclosure pricing.
Pricing Analysis
Crashworthiness validation outcomes anchor pricing tiers across the UK automotive carbon fiber market. Three-tier pricing structure across premium, standard, and economy levels sorts suppliers by UKAS certification depth and UN ECE R100 flammancy test documentation. Price differentiation stems from modulus grade specification and autoclave processing guarantees. Cost compression in body panel segments intensifies because aluminum substitution pressure forces faster-curing thermoplastic adoption. Fleet procurement teams at Midlands-based EV assemblers exhibit highest price sensitivity, while premium chassis engineers prioritize stiffness-to-weight ratios over unit economics.
Supply Chain Analysis
UKAS certification gating fragments qualified feedstock supply across UK, German, and Japanese precursor networks. The supply chain draws from acrylonitrile petrochemical streams, high-modulus tow production, and thermoplastic resin formulation. Single-source vulnerability concentrates in Midlands-based autoclave facilities serving crash-critical structural programs. Distribution runs through Tier-1 compounders with captive OEM qualification relationships, though direct fiber procurement is displacing intermediation in premium chassis applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK automotive carbon fiber composites constitute a vertical-integration race where upstream control over precursor supply and downstream captive processing capacity determine margin capture. Players are pursuing backward integration into acrylonitrile feedstock to insulate against petrochemical volatility.
For Market Incumbents: Anchor qualification moats through UKAS-certified prepreg expansion in South Yorkshire underutilized capacity. Deepen automated fiber placement technology licensing to Midlands vehicle assemblers confronting geometric complexity requirements. Aluminum-intensive platform competition threatens volume body panel margins; defend through thermoplastic tape welding partnerships that compress cycle economics.
For New Entrants and Emerging Players: The price-point gap between premium chassis specifications and economy body panel tiers opens entry vectors in Northern England battery enclosure supply. Target Scottish EV assembly pull-through demand with BSI-compliant material characterization services. Pursue regulatory consultancy revenue addressing UKCA-REACH divergence as a service-layer wedge before manufacturing investment.
For Investors and Strategic Acquirers: The window for entry favors UKAS-certified compounders with Motorsport Valley workforce access and established OEM qualification timelines. Long-term viability hinges on thermoplastic resin system partnerships that align with high-volume EV production targets. Watch automated fiber placement adoption rates at Jaguar Land Rover and Aston Martin platforms as inflection indicators for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive acrylonitrile sourcing insulates Hexcel and SGL Carbon from petrochemical margin volatility. |
| Thermoplastic Resin System Partnerships | Toray Industries alliances with Midlands assemblers enable welded joint configurations eliminating mechanical fastening weight. |
| Automated Fiber Placement Licensing | Robotics integration with in-situ consolidation opens A-pillar and roof bow applications previously requiring manual layup. |
| UKCA Marking Alignment Services | Regulatory consultancy revenue pools emerge from post-Brexit divergence between retained EU REACH and British chemical authorization pathways. |
| South Yorkshire Capacity Expansion | Underutilized composites manufacturing bases offer battery enclosure production vectors serving Scottish EV assembly operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this UK automotive carbon fiber composites assessment. Primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, HSE compliance officers, and Motorsport Valley autoclave technicians combined with bottom-up and top-down triangulation. Secondary sources encompassed Vehicle Certification Agency UN ECE documentation, BSI composite material standards, UKCA marking guidance, and SEC filings from listed fiber precursor manufacturers.
Data-stream reconciliation across vehicle production databases, IHS Markit registration data, and EV platform engineering disclosures shaped the analytical framework. Segmentation dimensions modeled encompassed product form, application category, end-user procurement authority, and manufacturing technology across the projection horizon. CAGRs derived from production volume trajectories, content-per-vehicle assumptions, and price elasticity responses to aluminum substitution pressure. Forecast inputs incorporated zero-emission vehicle mandate compliance timelines and thermoplastic processing adoption curves.
Inputs from HSE enforcement records and UKAS certification registries were available through the study window; gaps in proprietary OEM qualification timeline data introduce uncertainty bands around crash-critical structural adoption forecasts. A model refresh is warranted upon material change in UN ECE flammability standard revisions or UKCA-REACH regulatory divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
RV Battery Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Global Bearings Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Vehicle Trailer Hitch Market