
 Latin America Two-Wheeler Components Market | 2026-2036
Latin America Two-Wheeler Components Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Two-Wheeler Components Market Intelligence
Independent parts distribution networks across Latin America are reshaping how replacement components reach rural mechanics and urban service stations. Honda Motor Co. Ltd. leverages its Brazilian manufacturing base to sustain captive supply chains for brake and engine assemblies across the Southern Cone. Yamaha Motor Co. Ltd. competes through specialized suspension and gearbox distribution partnerships with regional aftermarket aggregators. TVS Motor Company Ltd. anchors its Latin American position through cost-optimized aluminum and steel component sourcing tied to Colombian and Peruvian assembly operations.
Latin America two-wheeler components comprise the mechanical, electrical, and structural subsystems manufactured to OEM specifications or aftermarket interchange standards for motorcycles, scooters, and mopeds, typically requiring ISO 9001-aligned dimensional tolerances and region-specific corrosion resistance for tropical humidity exposure. These components serve the dual purpose of enabling vehicle assembly and sustaining fleet operability across high-utilization commercial and personal transport applications. Brake and engine categories command the largest current value pools given their replacement frequency and safety-critical certification requirements, while suspension systems represent the fastest-growing segment as ride-quality expectations rise among urban delivery fleets. Aluminum material grades are gaining share against traditional steel castings as manufacturers reduce unsprung weight to meet evolving fuel efficiency benchmarks.
Brazil's ANFAVEA emission protocols and Mexico's NOM environmental standards collectively dictate engine architecture choices and exhaust component specifications across the regional supply base. Argentina's INTI quality certification requirements and Colombia's Ministry of Transport safety mandates further fragment compliance obligations for cross-border component suppliers. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks when configuring manufacturing footprints and product qualification strategies for sustained market access.
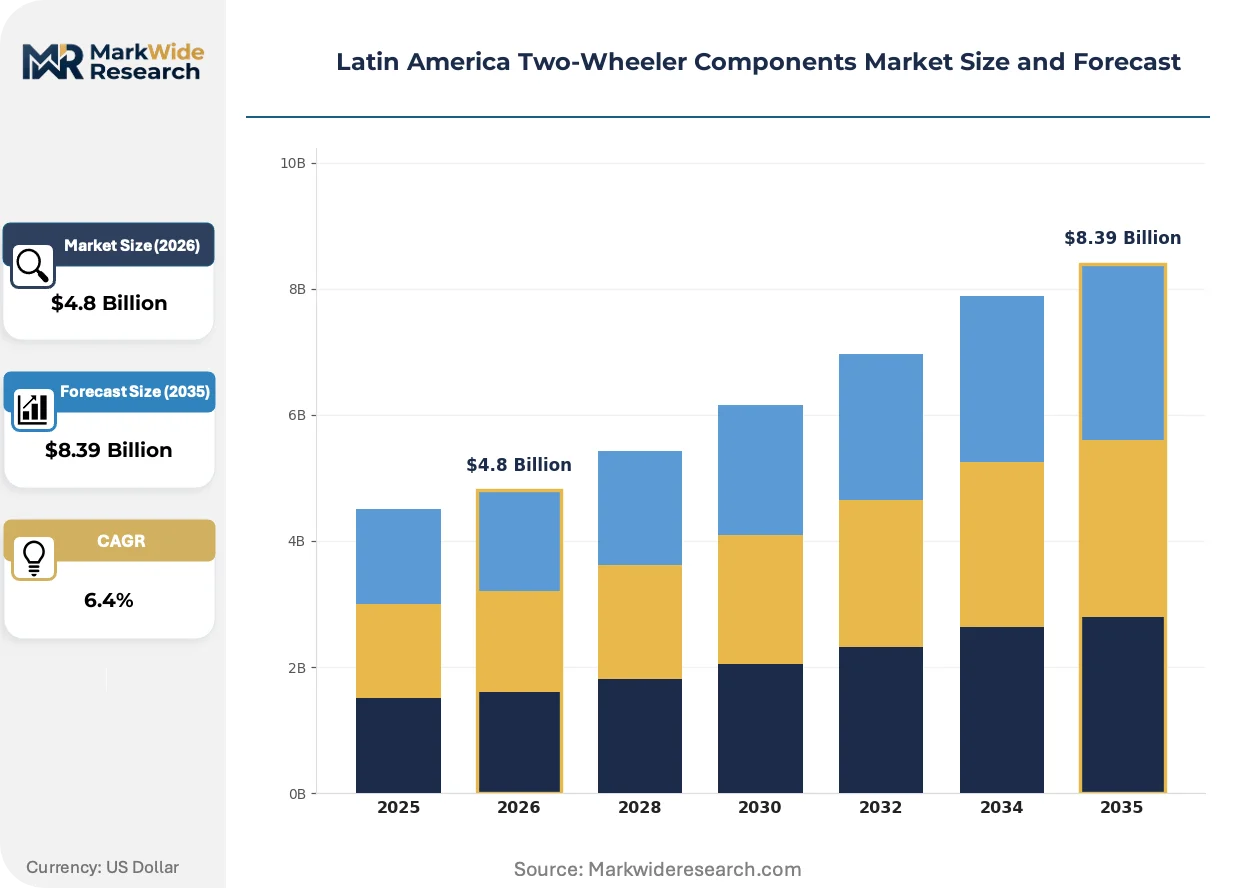
Market Dynamics
Proconve emission protocols in Brazil and NOM standards in Mexico are forcing component suppliers to redirect engineering resources toward cleaner engine architectures and exhaust systems, compressing development cycles for traditional carburetor-based supply chains.
Growth Catalysts
- Urban delivery fleet expansion:E-commerce logistics operators across São Paulo and Mexico City are accelerating motorcycle procurement for last-mile distribution, driving brake pad and clutch replacement volumes.
- ANFAVEA emission tier advancement:Brazil's progressive tightening of hydrocarbon limits is compelling OEMs to source fuel-injection components and catalytic converters from domestic qualified suppliers.
- Aluminum forging adoption:Suspension and wheel manufacturers are substituting steel castings with A356-T6 aluminum grades to reduce unsprung weight and meet fuel efficiency benchmarks.
Market Restraints
- Scrap steel price volatility:Brazilian steel input costs fluctuate with international commodity indices, squeezing margin stability for forged crankshaft and gear producers in Minas Gerais.
- Import dependency for electronic controllers:Engine management units and ABS modules concentrate sourcing from Asian semiconductor foundries, exposing assemblers to extended lead times.
- Technical limitation in lithium-ion integration:Tropical humidity and temperature cycling degrade battery pack longevity, constraining electric two-wheeler component substitution rates.
Strategic Opportunities
- Peruvian Andean corridor penetration:Underdeveloped service networks in Cusco and Arequipa create whitespace for brake and tire distributors to establish captive retail partnerships.
- Colombia Ministry of Transport safety mandate:Mandatory ABS requirements for motorcycles above 150cc will expand addressable market for hydraulic brake system suppliers through 2028.
- Remanufactured component channels:Independent rebuilders in Guadalajara and Medellín are developing certified pre-owned engine and transmission programs for price-sensitive fleet operators.
Industry Challenges
- Precision machining skill scarcity:CNC programming and dimensional metrology expertise remains concentrated in São Paulo and Monterrey industrial zones, limiting supplier scaling in secondary cities.
- Homologation timeline compression:INTI certification requirements in Argentina and Colombia's updated crash-testing protocols extend product qualification cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Two-Wheeler Components Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Brakes, Engines, Gearboxes, Suspension Material: Aluminum, Steel, Plastic, Rubber End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Manufacturing Stage: Raw Material, Assembly, Quality Control, Distribution |
| Companies Covered | Bajaj Auto Ltd., Dafra Motos, Honda Motor Co. Ltd., Motomel S.A., Italika, Yamaha Motor Co. Ltd., TVS Motor Company Ltd., Shineray Do Brasil SA, Suzuki Motor Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Two-Wheeler Components Market Strategic Shifts & Innovations
Component architectures across Latin America are pivoting from mechanical durability toward electronic integration and lightweight material science, reshaping supplier capability requirements and procurement evaluation criteria.
Direct fuel-injection systems with piezoelectric injector control are replacing carburetor assemblies in commuter motorcycles above 125cc displacement. Assemblers in Brazil and Mexico are qualifying these systems for tropical fuel quality variance. Carburetor casting and jetting expertise is rendering obsolete across the regional supply base.
Brazil's Proconve L7 and L8 emission tiers are mandating closed-loop catalytic converter monitoring with oxygen sensor feedback. Exhaust system suppliers must integrate ceramic substrate technologies and stainless steel shell fabrication into previously muffler-focused operations. Catalytic converter-equipped motorcycles now dominate São Paulo and Rio de Janeiro registration data.
Independent mechanics in Colombia and Peru are consolidating purchasing through mobile-enabled parts aggregators that bypass traditional wholesale distributors. These platforms offer same-day delivery of brake pads, chains, and filters to urban service stations. Digital procurement penetration concentrates most visibly in Bogotá and Lima metropolitan zones.
Latin America Two-Wheeler Components Market Segmentation
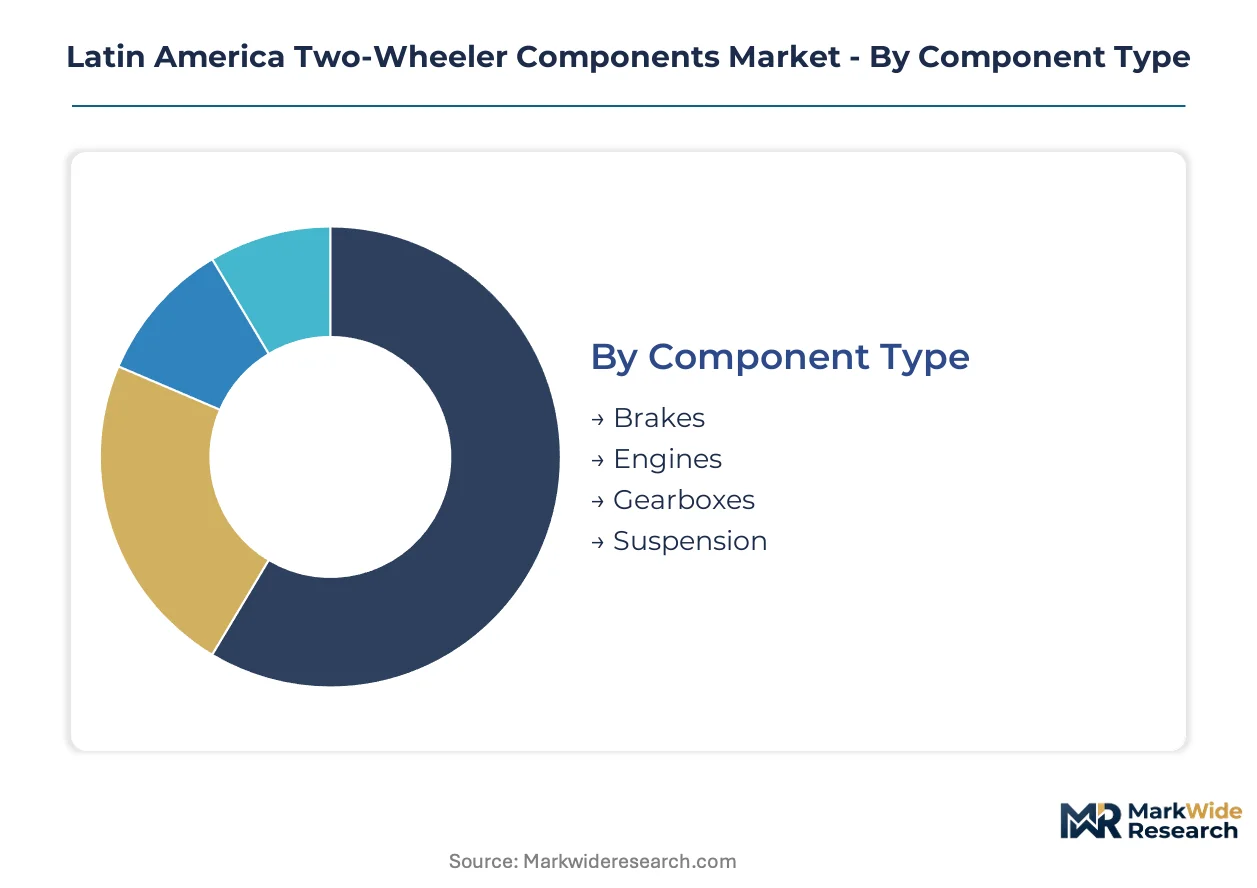
Latin America two-wheeler components span mechanical, electrical, and structural subsystems with divergent replacement cycles and margin profiles. Understanding how demand fragments across component types, materials, and supply chain positions enables suppliers to allocate engineering and distribution resources effectively.
Component Type:
Use-case spectrum stretches from daily commuter durability requirements to commercial fleet uptime optimization across Brazil's urban corridors and Andean delivery routes.
- Brakes:Hydraulic disc and drum assemblies incorporating sintered metallic or organic friction materials. São Paulo's e-commerce logistics operators drive pad replacement volumes through intensive stop-and-go routing, with ANFAVEA safety mandates accelerating ABS module adoption for motorcycles above 150cc displacement.
- Engines:Single-cylinder air-cooled and liquid-cooled powertrains with displacement ranging from 100cc to 300cc. Brazil's Proconve emission tiers are forcing fuel-injection system integration and displacing carburetor architectures across Minas Gerais assembly plants.
- Gearboxes:Constant-mesh manual transmissions with 4-6 speed configurations optimized for tropical fuel quality variance.
- Suspension:Telescopic forks and twin-shock rear systems with progressive damping rates.
Established volume favors brakes; emerging adoption favors suspension as ride-quality expectations rise among urban delivery fleets.
Material:
Cost tier differentiation separates premium forged grades from commodity castings across Brazilian and Mexican supplier bases.
- Aluminum:A356-T6 and A380 die-cast grades for wheel hubs, engine casings, and suspension components. Colombian assemblers specify aluminum forgings to reduce unsprung weight and meet fuel efficiency benchmarks mandated by the Ministry of Transport.
- Steel:Carbon and alloy grades for crankshafts, gears, and structural frames. Scrap price volatility in Brazilian spot markets squeezes margin stability for forged component producers concentrated in Minas Gerais industrial zones.
- Plastic:Polypropylene and ABS blends for body panels, fuel tanks, and electrical housings.
- Rubber:Natural and synthetic compounds for seals, gaskets, and vibration isolation mounts.
Steel retains dominant volume share; aluminum gains fastest across premium motorcycle segments.
End User:
Customer type determines certification requirements, payment terms, and technical support intensity across the regional supply base.
- OEMs:Vehicle assemblers with captive supply agreements and ISO 9001-aligned quality protocols. Honda's Brazilian manufacturing base sustains dedicated brake and engine supply chains across the Southern Cone.
- Aftermarket Providers:Independent distributors serving rural mechanics and urban service stations through expanding logistics networks. Mobile-enabled parts aggregators in Bogotá and Lima now bypass traditional wholesale channels for same-day brake pad and filter delivery.
- Tier-1 Suppliers:Subsystem integrators managing qualification and assembly for OEM accounts.
- Dealerships:Authorized service networks with proprietary parts procurement and warranty administration.
OEM relationships anchor revenue stability; aftermarket channels offer fastest expansion trajectory through digital procurement penetration.
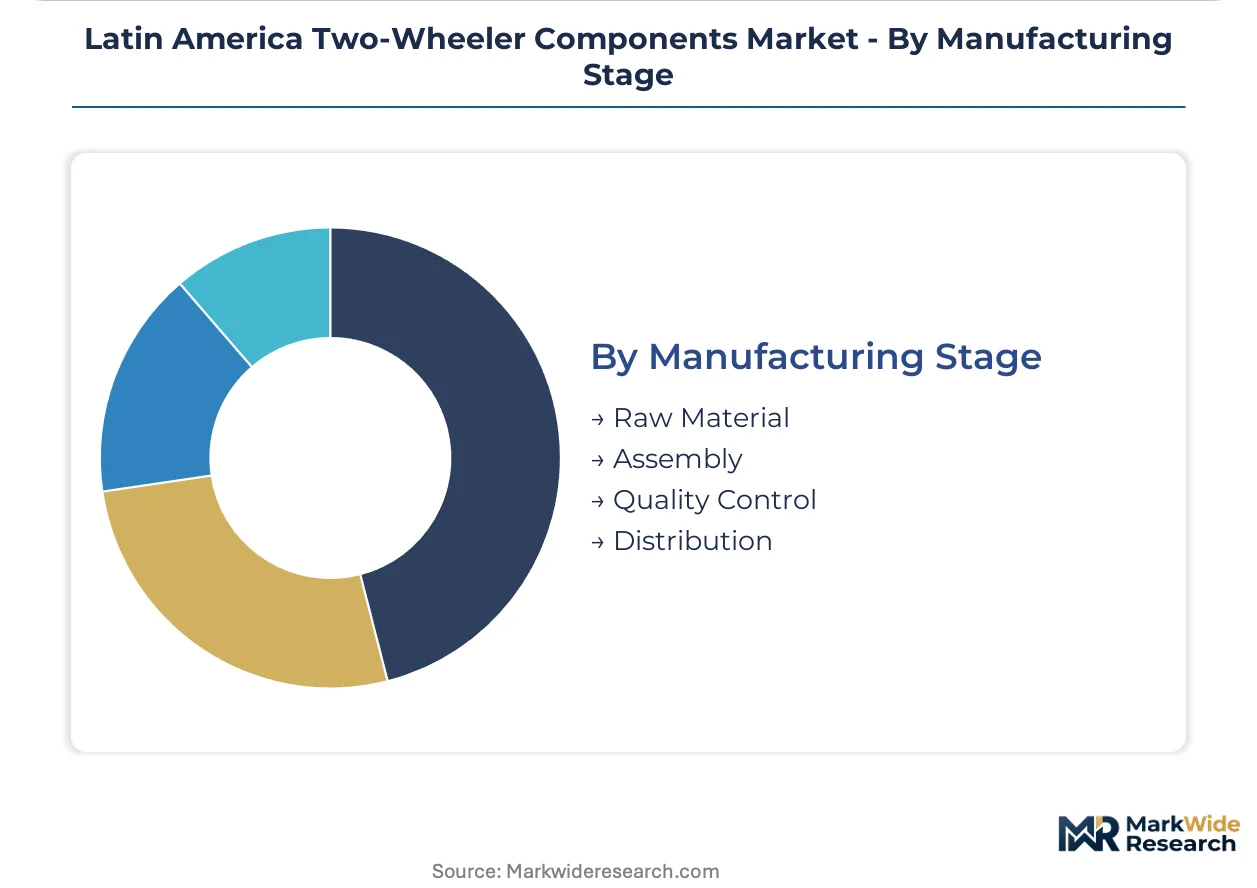
Manufacturing Stage:
Supply concentration varies by value-add position, with precision machining and quality certification concentrated in São Paulo and Monterrey industrial corridors.
- Raw Material:Aluminum ingot, steel billet, and polymer resin sourcing subject to import dependency and commodity index volatility.
- Assembly:Component integration and subsystem testing operations. Brazilian domestic content requirements redirect supplier investment toward local manufacturing partnerships for sustained Proconve compliance.
- Quality Control:Dimensional metrology, material testing, and homologation documentation. INTI certification in Argentina and Colombia's updated crash-testing protocols extend qualification cycles by four to six months.
- Distribution:Finished goods logistics through regional warehouses and cross-border freight networks.
Assembly commands capital intensity; quality control creates differentiation through certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors Brazil's two-wheeler component trade, handling aluminum ingot imports and finished brake assembly exports that sustain the Southern Cone supply chain.
Brazil
São Paulo's e-commerce logistics operators drive intensive brake pad replacement cycles through stop-and-go urban routing. ANFAVEA emission tier advancement forces fuel-injection component sourcing from domestic qualified suppliers. The São Paulo industrial corridor concentrates precision machining and quality certification operations that serve both OEM assembly and regional distribution networks.
Mexico
Mexico City delivery fleet expansion accelerates motorcycle procurement for last-mile distribution corridors. NOM environmental standards dictate exhaust system specifications and engine architecture choices across the supply base. The Bajío Region hosts expanding assembly partnerships that redirect supplier investment toward local manufacturing for sustained market access.
Colombia
Bogotá's mobile-enabled parts aggregators bypass traditional wholesale channels for same-day brake pad delivery to urban service stations. Ministry of Transport safety mandates mandate ABS requirements for motorcycles above 150cc displacement through 2028. The Andean corridor around Medellín develops certified pre-owned engine programs for price-sensitive fleet operators.
Argentina
Buenos Aires metropolitan aftermarket channels sustain replacement component demand for aging motorcycle fleets. INTI quality certification requirements extend product qualification cycles by four to six months for cross-border suppliers. Córdoba's industrial zone retains CNC programming expertise that limits supplier scaling in secondary cities.
Peru
Lima's digital procurement penetration concentrates visible demand for brake and filter components through mobile-enabled platforms. The national transport regulator enforces progressive safety equipment standards for commercial motorcycle operators. Cusco and Arequipa present underdeveloped service network whitespace for brake and tire distributors establishing captive retail partnerships.
Latin America Two-Wheeler Components Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in a structure that fragments across captive OEM supply chains and independent aftermarket channels. Japanese and Indian motorcycle assemblers sustain vertically integrated component sourcing from Brazilian manufacturing bases. Three archetypes dominate: OEM-captive suppliers with dedicated assembly partnerships, independent aftermarket distributors with expanding logistics networks, and regional assemblers with cost-optimized material sourcing. Competitive moves concentrate on strategic partnerships with digital procurement platforms and backward integration into aluminum forging capacity.
Among Japanese-origin platform integrators, Honda Motor Co. Ltd. and Yamaha Motor Co. Ltd. occupy positions that exemplify OEM-captive supply chain architecture. TVS Motor Company Ltd. represents the cost-optimized sourcing archetype through Colombian and Peruvian assembly operations. These three companies anchor the competitive structure without exhausting its variation.
| Leading Market Players |
|---|
| Bajaj Auto Ltd. |
| Dafra Motos |
| Honda Motor Co. Ltd. |
| Motomel S.A. |
| Italika |
| Yamaha Motor Co. Ltd. |
| TVS Motor Company Ltd. |
| Shineray Do Brasil SA |
| Suzuki Motor Corporation |
| Others |
Cost & Logistics Intelligence
Idle forging capacity across Minas Gerais steel corridors is compressing supplier pricing power while accelerating consolidation among brake and engine component producers seeking scale economies against Brazilian scrap volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts for brake assemblies and engine subsystems. Price differentiation hinges on ANFAVEA certification tier and volume commitment scale, with fleet operators commanding steepest discounts. Cost compression in commodity steel castings is intensifying because Brazilian scrap index volatility squeezes margin stability. Urban delivery fleets exhibit highest price sensitivity, while OEM captive suppliers maintain pricing resilience through long-term offtake agreements.
Supply Chain Analysis
Tariff exposure between Asian semiconductor foundries and Brazilian assembly plants dominates supply chain risk profiles for engine management units and ABS modules. Geographic supply concentration centers on China for electronic controllers, Brazil for forged steel components, and Mexico for aluminum die-cast operations. Raw material dependencies rest on scrap steel billets, A356-T6 aluminum ingot, and ceramic catalytic substrates. Single-source vulnerability for piezoelectric injectors threatens fuel-injection system qualification timelines. Distribution runs through São Paulo regional warehouses serving Southern Cone aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America two-wheeler components market rewards suppliers who control precision machining talent pools, as CNC programming expertise concentrates in São Paulo and Monterrey while secondary cities face capability gaps.
For Market Incumbents: Insulate margin stability through backward integration into aluminum forging capacity in Minas Gerais, reducing exposure to scrap steel volatility. Deepen certification investment for Proconve L8 emission compliance ahead of regulatory deadlines, locking in OEM qualification windows that emerging competitors cannot replicate. For New Entrants and Emerging Players: The Peruvian Andean corridor around Cusco and Arequipa offers underdeveloped service network whitespace for brake and tire distributors establishing captive retail partnerships. Target mobile-enabled parts aggregation platforms in Bogotá and Lima, where digital procurement penetration concentrates visible demand and traditional wholesale bypass creates entry velocity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket distributors with established logistics networks serving urban delivery fleets. Long-term viability favors acquisition targets with INTI or ANFAVEA pre-qualification status and aluminum forging capabilities. Monitor ABS mandate implementation timelines in Colombia as inflection indicators for hydraulic brake system supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Forging | Reduces scrap steel exposure while meeting Ministry of Transport weight-reduction mandates. |
| Proconve L8 Certification Investment | Secures OEM qualification windows for fuel-injection and catalytic converter supply contracts. |
| Mobile-Enabled Parts Platform Partnership | Captures same-day delivery demand from Bogotá and Lima urban service stations. |
| Peruvian Andean Corridor Expansion | Establishes captive retail partnerships in underdeveloped Cusco and Arequipa markets. |
| ABS Module Qualification Program | Addresses Colombia Ministry of Transport safety mandates for motorcycles above 150cc displacement. |
Research Approach
A spread of perspectives from OEM procurement directors, aftermarket distributor operations heads, Tier-1 subsystem integrators, and ANFAVEA regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, vehicle production databases, and INTI certification registries. Bottom-up component demand modeling triangulated against top-down motorcycle fleet penetration estimates.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning component type, material grade, end-user archetype, and manufacturing stage. CAGRs derived from fitted growth curves applied to replacement cycle frequencies and fleet expansion trajectories. Industry-specific forecast inputs incorporated Proconve emission tier implementation schedules and ABS mandate rollout timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian electronic controller suppliers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Truck Suspension System Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Child Seats Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Navigation Light Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
EGR Coolers Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Mobility Aids and Transportation Equipment Market