
 Steering Tie Rod Market | 2026-2036
Steering Tie Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Tie Rod Market Analysis
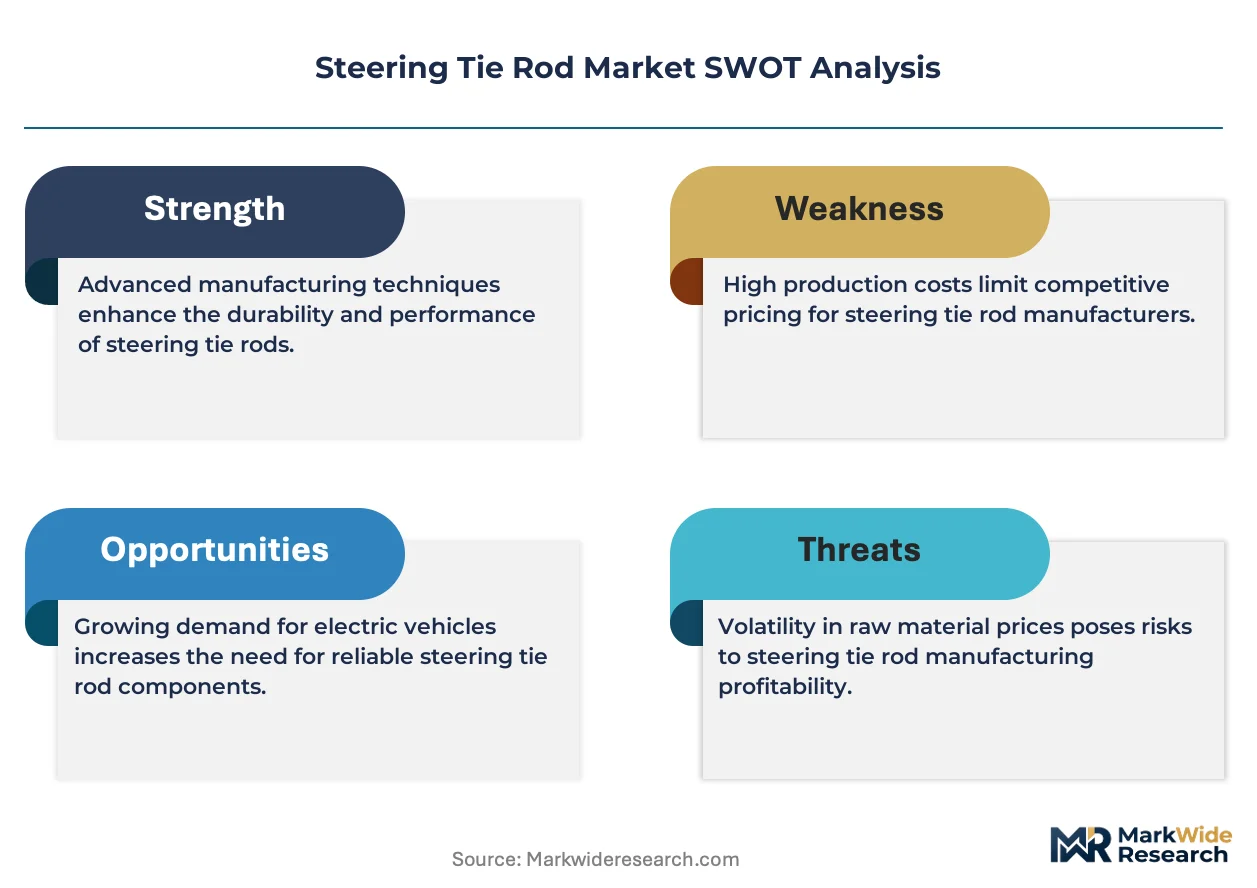
A shift from single-source to multi-source procurement for forged steering components is pivoting supplier relationships across the tier chain. BorgWarner leverages its powertrain integration expertise to bundle steering with driveline packages. ZF Friedrichshafen AG anchors European OEM contracts through its systems-level chassis portfolio. Nexteer Automotive Group Limited specializes in electric power steering adjacencies that tighten tie rod specification windows.
A steering tie rod is a slender structural linkage, typically forged from medium-carbon alloy steel with yield strengths exceeding 600 MPa, that transmits steering rack or gearbox force to the steering knuckle and maintains precise toe alignment under dynamic load. Its primary commercial purpose is to ensure directional control response while isolating road shock from the steering column in passenger and commercial vehicles. Inner tie rods and outer tie rods represent the dominant product pair, with inner rods capturing higher per-unit value due to integrated ball joint complexity and rack-end sealing requirements. Steel material grades still occupy the volume majority, though aluminum variants are gaining share in front-wheel electric platforms where unsprung mass reduction directly extends range.
NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity and tie rod separation resistance in the United States, while ECE R79 in Europe mandates steering effort and returnability criteria that cascade into tie rod stiffness specifications. China's GB standards for automotive steering, enforced by MIIT homologation, require localized testing for imported assemblies and favor domestic forge houses. Stakeholders must monitor how software-defined steering architectures redefine mechanical linkage duty cycles and whether aftermarket channels can match OEM-grade corrosion warranties.
Market Dynamics
Electric power steering architectures are compressing mechanical linkage duty cycles while tightening geometric tolerances, forcing suppliers to recalibrate forging processes and ball joint sealing specifications for reduced-load operating envelopes.
Growth Catalysts
- EPA fuel-efficiency mandates:Unsprung mass reduction targets in North America are accelerating aluminum tie rod adoption in front-wheel electric platforms, extending vehicle range through chassis lightweighting.
- Commercial vehicle fleet expansion:Precision steering component procurement is intensifying among logistics operators managing larger trailer configurations and tighter turning radius requirements.
- MIIT homologation pathways:China's GB standards for automotive steering are channeling aftermarket demand toward domestic forge houses capable of localized testing and certification.
Market Restraints
- Medium-carbon alloy steel price volatility:Yield strength requirements exceeding 600 MPa expose suppliers to scrap metal and energy input fluctuations that compress margin buffers on forged components.
- Ball joint complexity concentration:Inner tie rod manufacturing with integrated rack-end sealing remains concentrated among specialized forging operations, creating single-source vulnerability for OEM specification windows.
- Software-defined steering substitution:Steer-by-wire development programs in premium electric platforms threaten mechanical linkage volumes in long-cycle vehicle architectures.
Strategic Opportunities
- Aftermarket corrosion warranty gaps:Independent distributors can capture value by matching OEM-grade surface treatment specifications currently absent in secondary channels.
- Dual carbon goals in China:MEE enforcement of carbon intensity benchmarks favors domestic suppliers with electric forging capabilities and renewable energy sourcing.
- Chassis-driveline bundling convergence:Powertrain integration expertise is unifying steering and driveline procurement decisions, creating entry points for multi-system suppliers.
Industry Challenges
- Geometric tolerance calibration:Precision forging operations require capital-intensive press retrofits to achieve sub-millimeter consistency for electric power steering adjacencies.
- Cross-regulatory certification timelines:Simultaneous NHTSA, ECE R79, and GB standard compliance extends homologation cycles and strains testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Tie Rod Market |
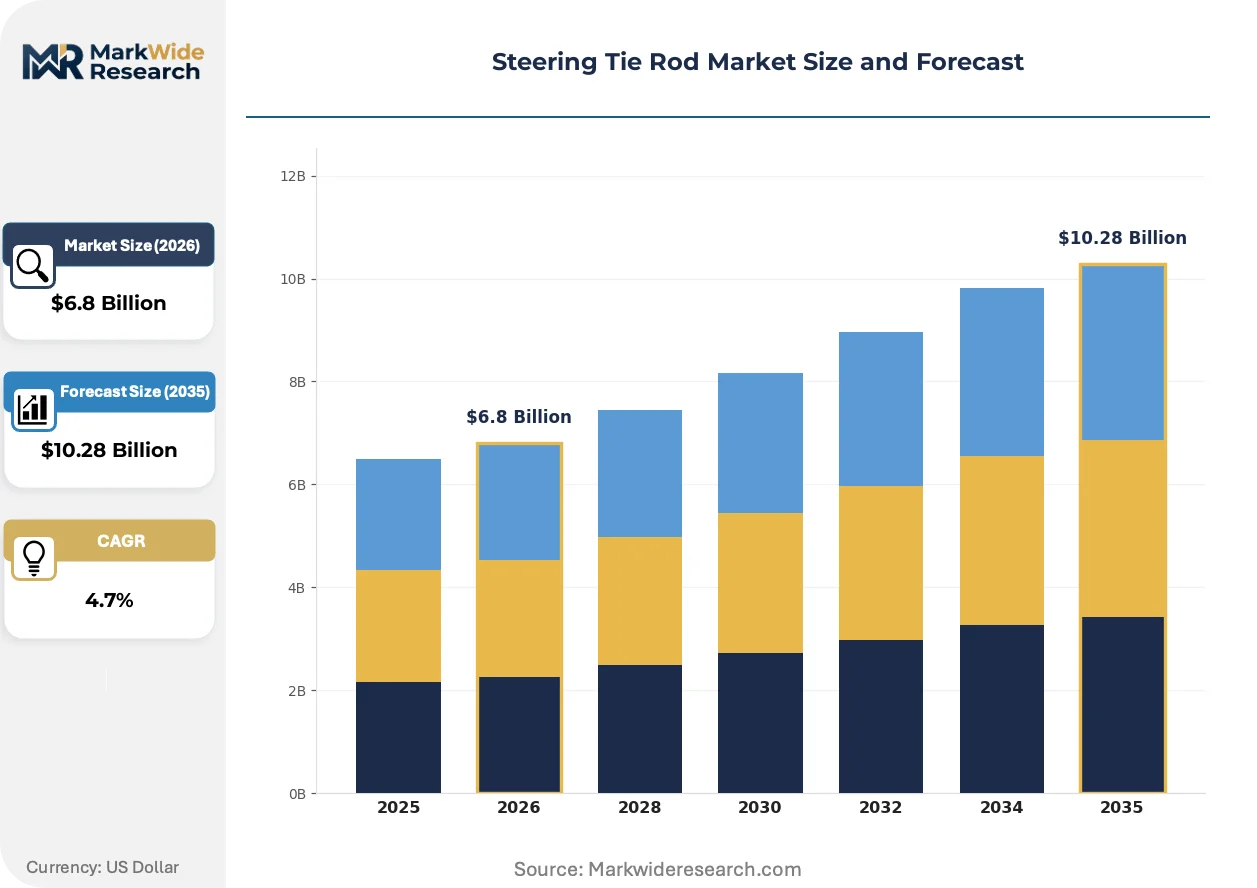
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inner Tie Rods, Outer Tie Rods, Adjustable Tie Rods, Fixed Tie Rods Material: Steel, Aluminum, Composite, Carbon Fiber End User: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Motorsports Installation Type: OEM, Aftermarket, Custom Installation, Standard Installation |
| Companies Covered | CTR Corporation, BorgWarner, ZF Friedrichshafen AG, Moog, Delphi Technologies, Nexteer Automotive Group Limited, Mando Corporation, Bosch Group, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Tie Rod Market Emerging Trajectories
Active materials substitution and regulatory convergence are compressing traditional component boundaries while rewiring procurement relationships across the tier chain.
Aluminum forging alloys for steering linkages are unifying lightweighting and corrosion resistance in single-component designs. Front-wheel electric platform engineers are specifying these grades at accelerating pace to offset battery mass. This substitution is compressing steel forging volumes in passenger vehicle segments while expanding specification windows for heat-treatment and surface finishing capabilities.
ECE R79 mandates on steering effort and returnability are cascading into tie rod stiffness specifications across European OEM contracts. The regulation forces recalibration of ball joint torsional resistance and rack-end compliance characteristics. German and French passenger vehicle programs are responding with integrated chassis simulation workflows that embed tie rod dynamics earlier in platform development cycles.
Fleet procurement consolidation is compressing supplier negotiation cycles and unbundling after-sales service from component supply contracts. Commercial vehicle operators in the United States are centralizing steering component purchasing through national maintenance networks. This channel shift is most visible among long-haul logistics providers managing standardized trailer fleets across multiple state jurisdictions.
Steering Tie Rod Market Segmentation
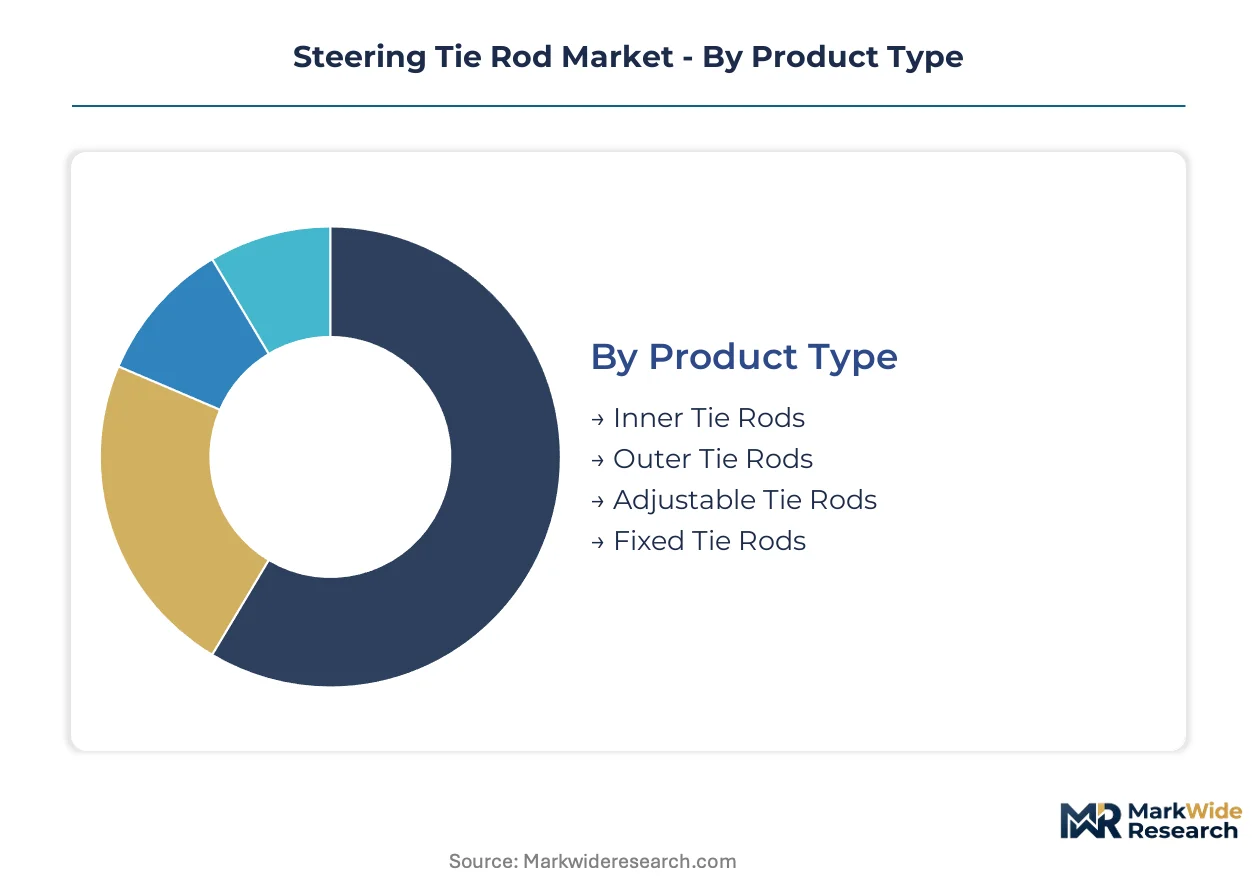
Segmentation in steering tie rods reveals how specification windows diverge across powertrain architectures and duty cycles. Procurement patterns split between integrated chassis programs and standalone replacement channels, with material choices increasingly tied to unsprung mass targets rather than legacy forging economics.
Product Type:
Standalone tie rod assemblies serve rack-end replacement cycles, while embedded ball-joint configurations integrate deeper into steering system architectures.
- Inner Tie Rods:These incorporate precision-forged rack-end housings with integrated ball joints and sealing systems. Demand concentrates in front-wheel electric platforms across Germany and China, where reduced steering loads still require sub-millimeter toe stability under regenerative braking torque reversals.
- Outer Tie Rods:Threaded shank designs with replaceable ball studs dominate commercial vehicle aftermarket channels. United States fleet operators specify these for standardized trailer configurations, prioritizing field-serviceability over integrated sealing complexity.
- Adjustable Tie Rods:Threaded sleeve constructions permit toe alignment correction without component replacement.
- Fixed Tie Rods:Non-adjustable forged linkages serve sealed-for-life applications in compact passenger architectures.
Inner tie rods lead volumes today; adjustable tie rods are gaining share fastest.
Material:
Cost tiers separate commodity forging grades from precision alloys and active lightweighting substitutes.
- Steel:Medium-carbon alloy grades exceeding 600 MPa yield strength retain volume dominance in commercial and heavy-duty segments. United States NHTSA safety standards and European ECE R79 stiffness mandates perpetuate steel specifications where fatigue resistance trumps mass reduction.
- Aluminum:Heat-treatable forging alloys are displacing steel in front-wheel electric platforms across China and Germany. MIIT carbon intensity benchmarks and EPA range-extension targets accelerate adoption where unsprung mass reduction directly offsets battery pack weight.
- Composite:Glass-reinforced polymer linkages serve corrosion-critical motorsports applications.
- Carbon Fiber:Prepreg layup constructions remain confined to ultra-premium racing programs.
Steel retains the highest volume position; aluminum is expanding most quickly.
End User:
Application severity determines specification windows, from corrosion warranties to impact resistance.
- Passenger Vehicles:Electric power steering architectures dominate specification development. OEM contracts in Germany and China prioritize integrated ball-joint designs with extended corrosion warranties matching vehicle electrification lifecycles.
- Commercial Vehicles:Fleet procurement centralization in the United States drives standardized tie rod specifications across multi-state logistics networks. Heavy-duty forged grades endure trailer articulation cycles and salt-spray exposure on interstate corridors.
- Heavy Machinery:Articulated loaders and excavators require oversized shank diameters and sealed boot systems.
- Motorsports:Rapid-replacement designs prioritize adjustability and crash-damage tolerance over durability.
Passenger vehicles anchor current volumes; commercial vehicles are climbing the fastest.
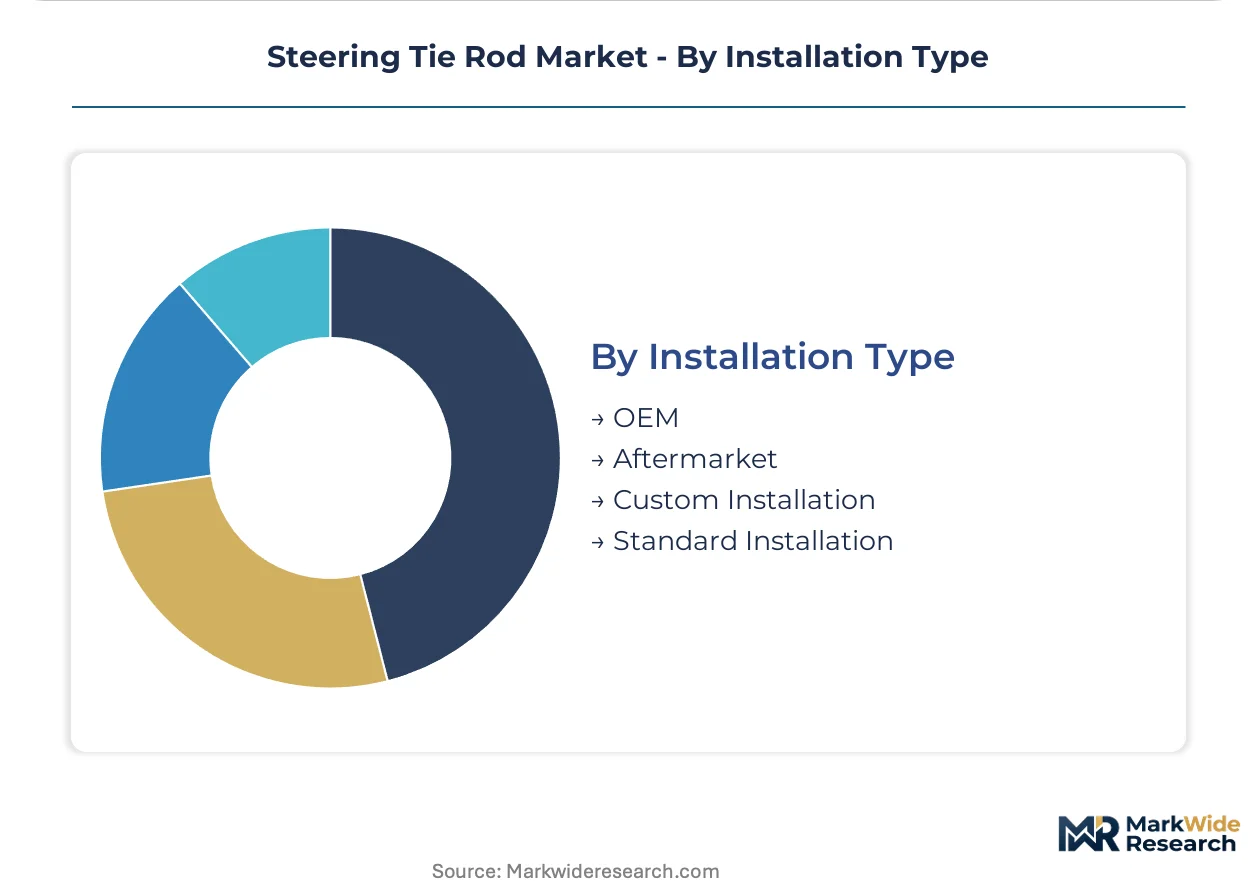
Installation Type:
Channel structure separates captive supply relationships from independent distribution economics.
- OEM:Tier-1 forging houses supply just-in-time sequences aligned with chassis assembly rhythms. NHTSA, ECE R79, and GB standard compliance requirements concentrate procurement among multi-certification suppliers capable of simultaneous homologation.
- Aftermarket:Independent distributors in the United States and China capture replacement cycles through national maintenance networks. Surface treatment specification gaps versus OEM grades create margin opportunities for certified secondary channels.
- Custom Installation:Motorsports and restoration specialists specify non-standard geometries and materials.
- Standard Installation:Direct-fit catalog items serve routine maintenance without modification.
OEM channels dominate value capture; aftermarket is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting forging capacity toward jurisdictions with streamlined homologation pathways and lower energy-input costs. Suppliers now site production where compliance burden and carbon-intensity benchmarks create measurable cost-of-compliance gaps.
United States
NHTSA Federal Motor Vehicle Safety Standards and EPA fuel-efficiency mandates are tightening tolerance requirements for steering assemblies. Fleet procurement centralization among long-haul logistics operators drives standardized tie rod specifications across multi-state networks. Detroit-Warren corridor forging houses supply just-in-time sequences aligned with domestic OEM chassis assembly rhythms.
Germany
ECE R79 mandates on steering effort and returnability cascade into tie rod stiffness specifications across European OEM contracts. German passenger vehicle programs embed tie rod dynamics earlier in platform development through integrated chassis simulation workflows. Baden-Württemberg and Bavaria host specialized forging operations concentrated among multi-certification suppliers.
China
MIIT homologation pathways and GB standards for automotive steering channel aftermarket demand toward domestic forge houses with localized testing capabilities. Dual carbon goals and MEE carbon intensity benchmarks favor suppliers with electric forging and renewable energy sourcing. Yangtze River Delta clusters concentrate precision forging capacity for front-wheel electric platform specifications.
Japan
METI industrial policy and JIS standards govern steering component quality certification for domestic and export markets. Japanese OEMs specify extended corrosion warranties matching vehicle electrification lifecycles. Kanto and Chubu industrial corridors maintain forging expertise for integrated ball-joint designs with rack-end sealing complexity.
South Korea
MFDS-aligned automotive quality frameworks and export-oriented OEM supply chains drive precision component demand. Seoul Capital Area suppliers serve integrated chassis-driveline bundling requirements from domestic vehicle manufacturers. Busan-Ulsan industrial zones concentrate heat-treatment and surface finishing capabilities for aluminum forging alloys.
Steering Tie Rod Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electric power steering adjacencies and aluminum lightweighting specialties. The supplier base organizes around three strategic archetypes: systems-level chassis integrators, precision forging specialists, and powertrain-driveline bundlers. Consolidation pressure concentrates procurement among multi-certification suppliers capable of simultaneous NHTSA, ECE R79, and GB compliance. Dominant competitive moves include strategic partnerships for forged component sourcing and geographic expansion into MIIT-favored domestic forge networks.
Among systems-level chassis integrators, ZF Friedrichshafen AG and BorgWarner exemplify the bundling convergence unifying steering and driveline procurement decisions. Nexteer Automotive Group Limited occupies a position within the precision-tier specialist archetype, representing electric power steering adjacency expertise that tightens specification windows. These three anchors illustrate how supplier relationships are pivoting from single-source to multi-source procurement patterns across the tier chain.
| Leading Market Players |
|---|
| CTR Corporation |
| BorgWarner |
| ZF Friedrichshafen AG |
| Moog |
| Delphi Technologies |
| Nexteer Automotive Group Limited |
| Mando Corporation |
| Bosch Group |
| NSK Ltd. |
| Others |
Supply Flow & Price Mechanics
Fleet procurement centralization among United States long-haul logistics operators anchors contract-based long-term offtake as the dominant pricing model, compressing negotiation cycles and unbundling after-sales service from component supply.
Pricing Analysis
Distributor margins in aftermarket channels absorb the widest spread between OEM list and end-user paid prices, while direct-to-OEM contracts trade volume scale for locked-in specification windows. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-certified assemblies from ECE R79-grade components and uncertified secondary imports. Cost compression in aluminum forging grades is intensifying because MIIT carbon intensity benchmarks favor electric forge houses with renewable energy sourcing. Commercial vehicle fleet operators exhibit highest price sensitivity due to standardized trailer configurations and multi-state maintenance network economics, while German passenger vehicle OEMs prioritize specification adherence over unit cost.
Supply Chain Analysis
MIIT homologation pathways and China's GB standards for automotive steering are reshaping sourcing toward domestic forge houses with localized testing capabilities, displacing import-dependent procurement patterns. Forging capacity concentrates in China, Germany, and the United States, with Yangtze River Delta clusters and Baden-Württemberg operations anchoring precision output. Medium-carbon alloy steel billets, heat-treatable aluminum forging stock, and specialized ball joint sealing compounds constitute critical input dependencies. Single-source vulnerability in integrated rack-end sealing manufacturing creates supply chain risk for OEM specification windows. Distribution runs through just-in-time Tier-1 sequences for OEM channels and national maintenance networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA Federal Motor Vehicle Safety Standards and EPA fuel-efficiency mandates tighten tolerance requirements and extend replacement cycles simultaneously.
For Market Incumbents: Anchor multi-certification capabilities across NHTSA, ECE R79, and GB standards to defend OEM specification windows against emerging domestic forge houses in China. Deepen backward integration into heat-treatment and surface finishing capabilities to capture aluminum lightweighting premiums in front-wheel electric platforms. Software-defined steering substitution threatens mechanical linkage volumes; counter by bundling steering with driveline packages through chassis-driveline procurement convergence. For New Entrants and Emerging Players: Enter via aftermarket corrosion warranty gaps in United States independent distribution channels, where surface treatment specification shortfalls versus OEM grades create margin capture opportunities. Target domestic forge networks in China favored by MIIT homologation pathways and dual carbon enforcement. Pursue electric forging capabilities with renewable energy sourcing to qualify for MEE carbon intensity benchmarks and secure Tier-2 supply relationships with Yangtze River Delta OEM programs. For Investors and Strategic Acquirers: Powertrain integration specialists are the most active acquirer in this space, seeking steering component capabilities to complete chassis-driveline bundling portfolios. Long-term viability hinges on positioning for software-defined vehicle architectures while harvesting mechanical linkage replacement cycles through the projection horizon. Acquisition target archetype: precision forging specialists with electric power steering adjacency expertise and sub-millimeter geometric tolerance capabilities. Monitor steer-by-wire development program announcements from premium electric platform manufacturers as inflection indicator for mechanical linkage demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Simultaneous NHTSA, ECE R79, and GB compliance concentrates procurement among qualified suppliers. |
| Electric Forging Capacity Buildout | MEE carbon intensity benchmarks favor suppliers with renewable energy sourcing in China. |
| Aluminum Alloy Heat-Treatment Expansion | EPA range-extension targets accelerate demand for unsprung mass reduction in front-wheel electric platforms. |
| Aftermarket Surface Treatment Upgrade | OEM-grade corrosion warranties in independent channels capture value from specification gaps. |
| Chassis-Driveline Bundling Convergence | Powertrain integration expertise unifies procurement decisions and creates multi-system entry points. |
Methodological Framework
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and domestic forge house technical directors grounded qualitative insights in operational reality. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard filings, ECE R79 regulatory submissions, MIIT homologation databases, vehicle production registries, and customs trade records for forging alloy movements. Bottom-up segment sizing triangulated against top-down macroeconomic anchors to constrain estimation variance.
Segment-level projections across product type, material grade, end-use application, and installation channel fed into an integrated analytical framework spanning the projection horizon. Modeled dimensions included vehicle propulsion architecture, steering system load envelope, and regional regulatory compliance cluster. CAGRs emerged from curve-fitting historical shipment patterns against OEM platform launch timelines and fleet replacement cycle data. Key inputs encompassed EPA fuel-efficiency mandate phase-ins, MIIT carbon intensity enforcement schedules, and commercial vehicle fleet expansion trajectories.
Inputs from regulatory filings and OEM procurement disclosures were available through the study window; gaps in real-time aftermarket channel inventory data introduce uncertainty bands around replacement cycle velocity estimates. Forecasts reflect assumptions about NHTSA tolerance enforcement continuity, aluminum alloy price stability, and steer-by-wire adoption curves in premium electric platforms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Global Bearings Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Suction Road Sweeper Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Electric Vehicle High Voltage Connector System Market