
 Global Automotive Carbon Fiber Composites Market | 2026-2036
Global Automotive Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Carbon Fiber Composites Market Intelligence
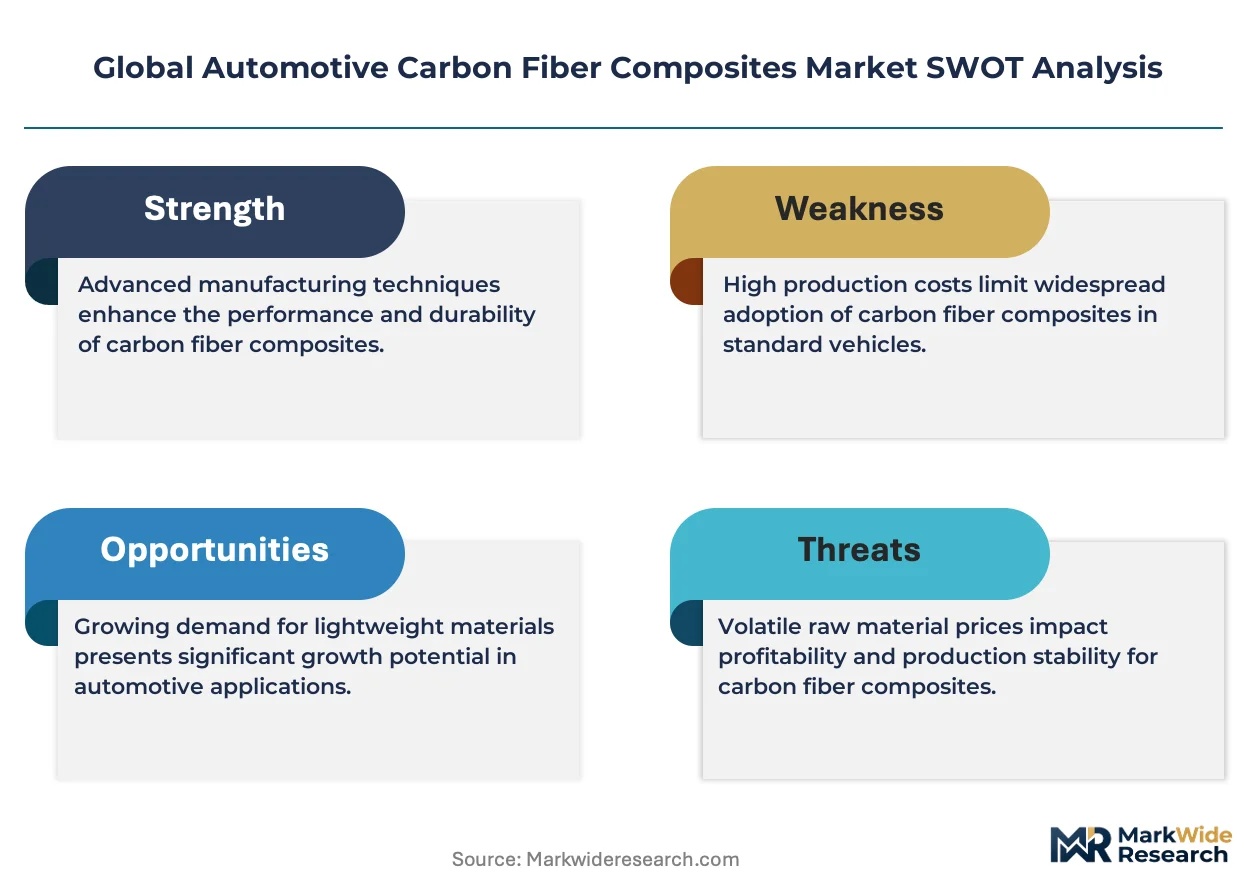
Profitability from the sale of raw carbon fibers is narrowing as value shifts toward the production of finished components and integrated assembly modules. Toray Industries Inc. leverages its scale in precursor and fiber production to supply major OEMs. Hexcel Corporation specializes in advanced composite materials, including prepregs for aerospace and high-performance automotive applications. SGL Carbon SE competes by offering a portfolio that spans from fibers and materials to complete composite parts for vehicle structures.
Automotive carbon fiber composites are materials made from carbon fibers, typically polyacrylonitrile (PAN)-based, embedded in a polymer matrix like epoxy or polyamide. Their primary purpose in vehicle manufacturing is to replace heavier metals, significantly reducing vehicle weight while maintaining or enhancing structural integrity. Prepregs represent a dominant product form due to their consistent quality and processing efficiency for Tier-1 Suppliers. Demand from OEMs for structural supports and body panels drives market volume, as these applications offer the greatest potential for mass reduction.
Vehicle lightweighting mandates are enforced by regulations such as the US EPA's fuel economy standards and the EU Green Deal's CO2 emission targets. In China, the Ministry of Industry and Information Technology (MIIT) promotes new energy vehicles, indirectly boosting demand for lightweight materials to extend battery range. Supplier success will depend on developing high-volume, cost-effective manufacturing processes to meet OEM price-performance requirements.
Market Dynamics
The market's central dynamic is the convergence of stringent emissions regulations and the technical demands of electric vehicle battery performance. Automakers are compelled by rules like the EU's CO2 targets to reduce vehicle mass, a need amplified in EVs where lightweighting directly extends driving range.
Growth Catalysts
- Emissions Reduction Mandates:Regulations such as the US EPA's fuel economy standards and China's dual carbon goals directly incentivize vehicle lightweighting, making carbon fiber composites a preferred material for achieving compliance without compromising safety.
- EV Battery Enclosures:The electric vehicle segment drives significant demand for composites in battery enclosures, where the material offers lightweight protection, thermal management, and structural support for heavy battery packs.
- Processing Advancements:The adoption of prepregs and automated manufacturing techniques like high-pressure resin transfer molding allows Tier-1 suppliers to meet the quality and volume requirements of major automotive production lines in Germany and Japan.
Market Restraints
- High Material Cost:The price of PAN-based carbon fiber precursor remains a significant barrier to widespread adoption in mass-market vehicles, limiting its use primarily to premium and high-performance models.
- Manufacturing Cycle Times:Traditional thermoset composite manufacturing processes have slower cycle times compared to conventional metal stamping, creating production bottlenecks for high-volume vehicle platforms.
- Substitution from Metals:Advanced high-strength steel and aluminum alloys present a strong substitution threat, offering a more cost-effective pathway to vehicle lightweighting for many non-critical structural applications.
Strategic Opportunities
- Thermoplastic Composites:The development of thermoplastic matrix composites offers significant opportunity, promising faster production cycles, improved recyclability, and easier integration through welding-like processes.
- Component System Integration:Suppliers can move up the value chain by offering complete, multi-material modules, such as integrated front-end structures or entire floor assemblies, rather than just individual parts.
- Expansion into Commercial Vehicles:Underpenetrated segments like electric buses and long-haul trucks present a new frontier for lightweighting, where fuel efficiency and payload capacity gains justify the material's cost.
Industry Challenges
- High-Volume Manufacturing Scalability:The primary operational hurdle is developing and financing automated production lines capable of producing composite parts at the speed and cost-per-part required by mass-market automotive OEMs.
- Lack of Material Standardization:A deficit in universally accepted standards for composite material testing and data reporting complicates the vehicle design and validation process, slowing OEM adoption.
- Workforce Skill Gaps:A shortage of technicians and engineers with expertise in composite design, manufacturing, and repair creates a bottleneck for both production scaling and establishing a viable aftermarket service network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Carbon Fiber Composites Market |
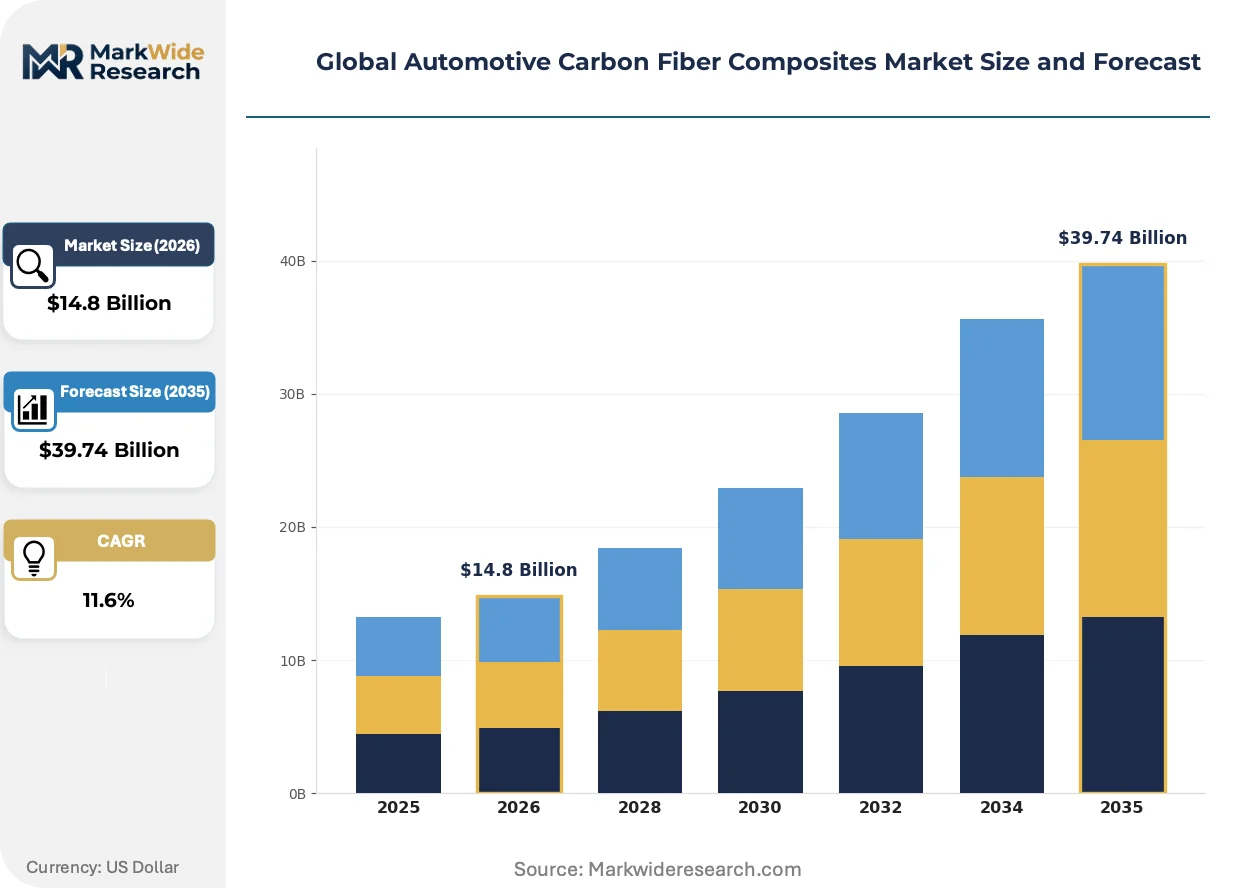
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepregs, Towpregs, Chopped Fibers, Woven Fabrics, Nonwovens Application: Chassis Components, Body Panels, Interior Parts, Electrical Housings, Structural Supports Manufacturing Stage: Raw Carbon Fibers, Intermediate Composites, Finished Components, Assembly Modules Customer Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Teijin Limited, Solvay, Toray Industries Inc., Owens Corning, BASF SE, Hexcel Corporation, Mitsubishi Chemical Corporation, Zoltek, SGL Carbon SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Carbon Fiber Composites Market Strategic Shifts & Innovations
Industrialization of composite manufacturing is the dominant theme, as processes once confined to aerospace and racing are adapted for automotive scale. This evolution focuses on reducing cycle times, lowering costs, and integrating composites seamlessly into existing vehicle assembly workflows.
Digital twin technology is a key enabler for composite part design and manufacturing simulation. Tier-1 suppliers and OEMs are increasingly adopting these software tools during the initial vehicle development phase. This advanced modeling capability is virtualizing much of the expensive and slow physical prototyping process, thereby compressing development timelines and reducing material waste before production tooling is finalized.
The EU Green Deal and its associated Circular Economy Action Plan are influencing material choices within the automotive industry. This regulatory push creates demand for recyclable composite solutions, particularly those using thermoplastic matrices that can be remolded. The body panels and interior components segment is most affected, as suppliers now engineer parts with end-of-life vehicle directives in mind.
Automotive OEMs are modifying their sourcing strategies away from procuring simple components toward acquiring complex, pre-assembled systems. This trend involves Tier-1 suppliers delivering complete functional modules, such as an entire battery enclosure with integrated cooling and electronics. This shift toward system-level procurement is most visible in the European EV market, where it helps accelerate vehicle assembly.
Global Automotive Carbon Fiber Composites Market Segmentation
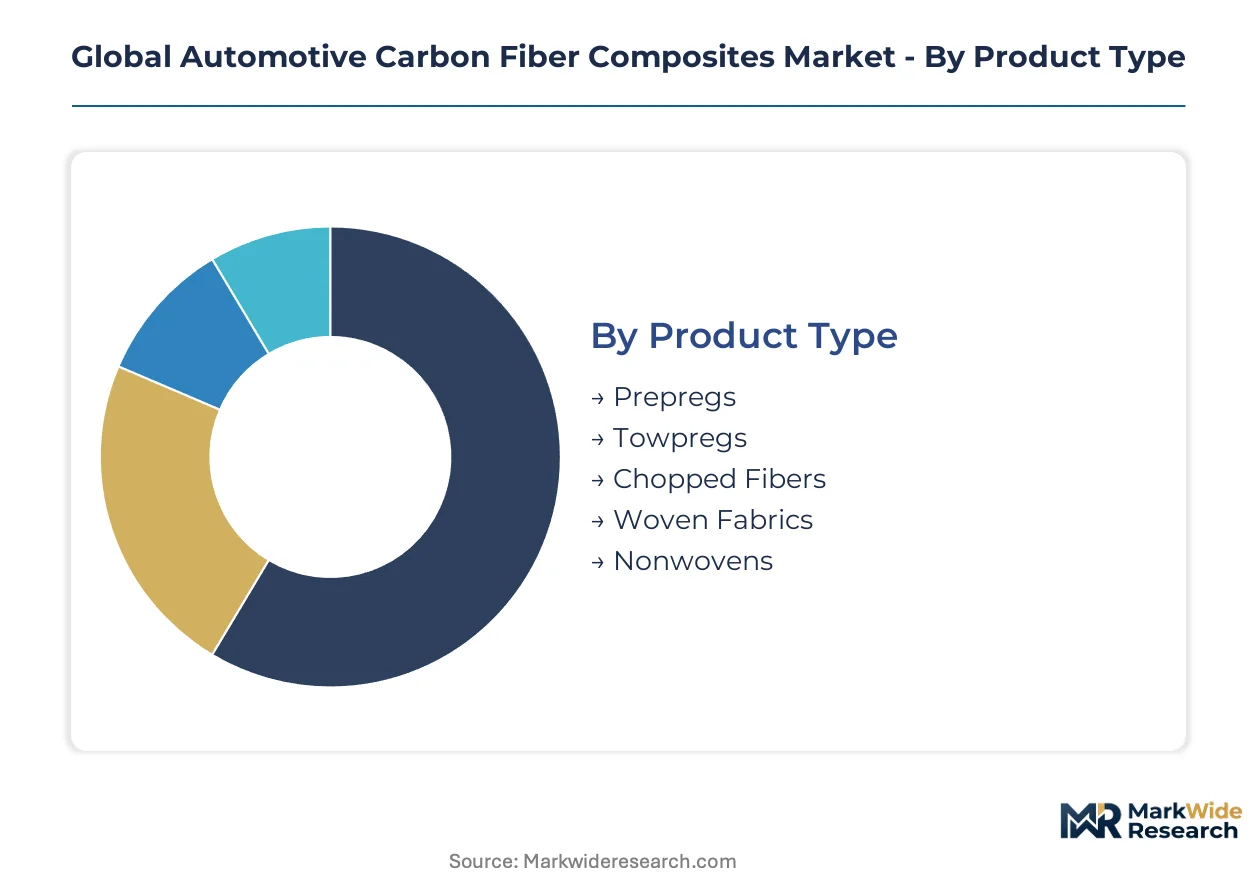
The global automotive carbon fiber composites market is analyzed across key dimensions, revealing how material forms, vehicle applications, manufacturing processes, and customer relationships shape its structure. This segmentation highlights areas of established demand and emerging growth within vehicle lightweighting initiatives.
Product Type:
Product type segmentation highlights the various forms in which carbon fiber composites are supplied to the automotive industry, each optimized for specific manufacturing processes and performance requirements.
- Prepregs:These are pre-impregnated composite materials, where carbon fibers are pre-coated with a resin matrix and stored for later curing. Their consistent quality and ease of handling make them a dominant product form, especially for Tier-1 suppliers producing high-performance structural components for German and Japanese automakers.
- Woven Fabrics:Carbon fibers are woven into textile-like sheets, providing specific directional strength and aesthetic appeal. These fabrics are critical for fabricating complex body panels and structural parts where multi-directional load paths are present, supporting mass reduction efforts in premium vehicle segments.
- Towpregs:These consist of continuous carbon fiber tows pre-impregnated with resin, primarily used in filament winding or pultrusion processes for components requiring high axial strength.
- Chopped Fibers:Short carbon fiber strands are dispersed in a polymer matrix for injection molding or compression molding, offering isotropic properties for non-critical parts like interior components.
- Nonwovens:Randomly oriented carbon fibers are bonded together, providing good stiffness-to-weight ratios for semi-structural applications and acoustic dampening in vehicle interiors.
Prepregs command the established base. The steepest expansion runs through Woven Fabrics.
Application:
The application landscape for carbon fiber composites demonstrates their versatility in addressing critical vehicle lightweighting and performance challenges across various vehicle systems.
- Structural Supports:These applications involve primary load-bearing elements within the vehicle chassis and frame, replacing heavier metals to reduce overall vehicle mass. Demand from OEMs for these parts is substantial, offering the greatest potential for fuel efficiency gains and extended EV ranges.
- Electrical Housings:Composites are increasingly used for electric vehicle battery enclosures, providing lightweight protection, thermal management, and structural integrity for heavy battery packs. This application is crucial for extending EV driving range and meeting stringent safety standards.
- Chassis Components:Carbon fiber composites are integrated into suspension arms, subframes, and other chassis elements to reduce unsprung mass, which enhances vehicle handling and ride dynamics.
- Body Panels:Exterior body parts such as hoods, roofs, and fenders utilize composites to reduce weight and improve aerodynamic performance, particularly in high-performance and premium vehicles.
- Interior Parts:Lightweight composite materials are employed in seat frames, dashboards, and door panels to contribute to overall vehicle mass reduction without compromising occupant safety or comfort.
Demand for Chassis Components remains foundational, while Electrical Housings present significant growth prospects.
Manufacturing Stage:
Value chain participation defines the manufacturing stage segments, reflecting the progression from raw materials to fully integrated vehicle systems supplied to automakers.
- Finished Components:This segment includes ready-to-assemble composite parts such as body panels, structural beams, or battery casing shells, delivered directly to OEMs or vehicle assemblers. Value shifts toward these components as suppliers offer more integrated solutions.
- Assembly Modules:These are complex, multi-material sub-assemblies, like integrated front-end structures or entire floor assemblies, provided by Tier-1 suppliers. OEMs are increasingly sourcing these complete modules to accelerate vehicle assembly, particularly in the European EV market.
- Raw Carbon Fibers:These are the fundamental fibrous materials, typically polyacrylonitrile (PAN)-based, produced by companies like Toray Industries Inc. that serve as the precursor for all composite products.
- Intermediate Composites:This stage encompasses materials like prepregs, towpregs, and woven fabrics, which are processed forms of carbon fiber ready for component fabrication.
The market is evolving towards greater integration, with Raw Carbon Fibers representing a foundational input and Assembly Modules signifying higher value creation.
Customer Type:
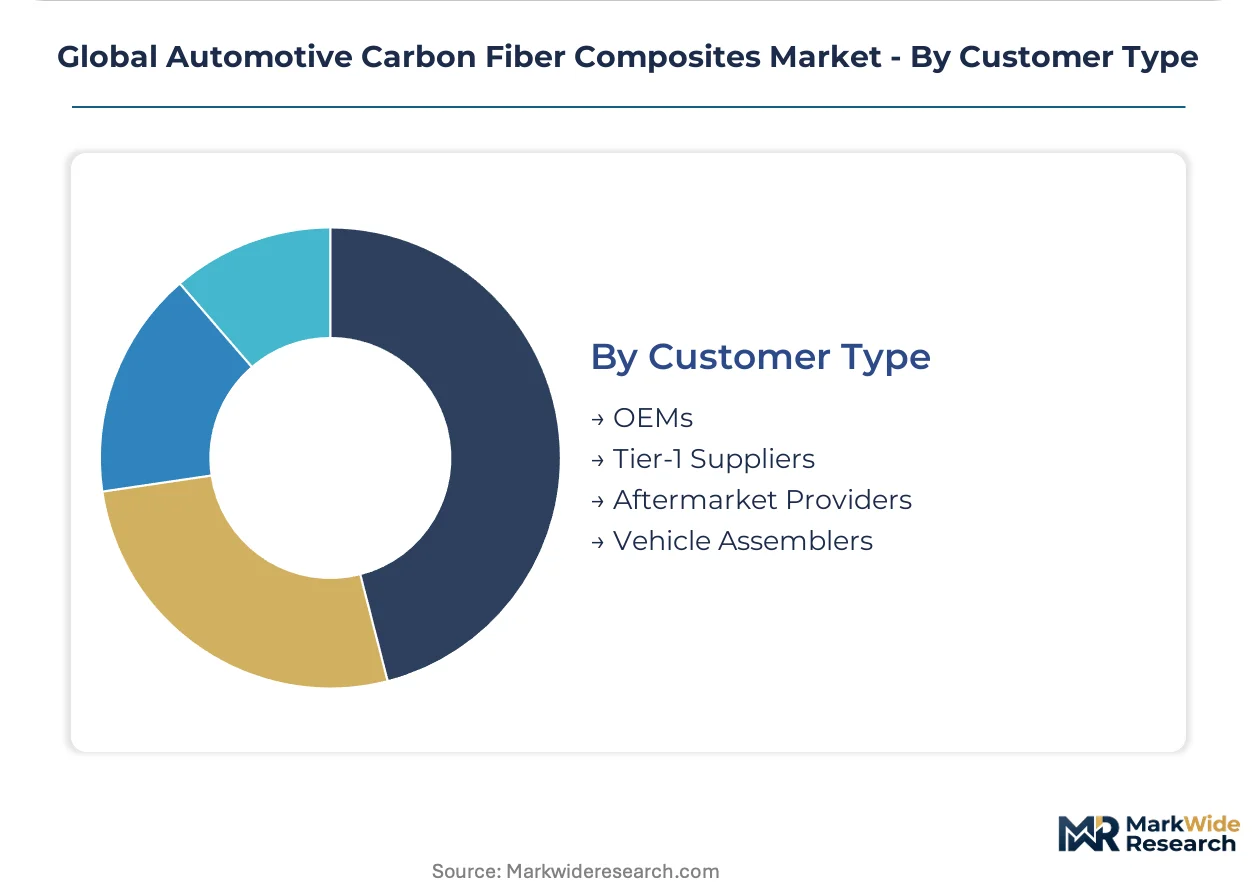
The customer type classification reflects the diverse entities procuring carbon fiber composite materials and components within the automotive supply chain.
- OEMs:Original Equipment Manufacturers directly purchase finished composite components and assembly modules for integration into their vehicle production lines. Automakers like those in Germany, Japan, and the United States drive significant market volume.
- Tier-1 Suppliers:These companies specialize in manufacturing complex sub-assemblies and systems for OEMs, often utilizing intermediate composites like prepregs to produce finished parts. Hexcel Corporation and SGL Carbon SE serve this segment.
- Vehicle Assemblers:Entities focused on the final assembly of vehicles, which may procure some composite parts directly, especially for specialized or low-volume models.
- Aftermarket Providers:Suppliers catering to the post-sale market, offering replacement or performance-enhancing composite parts for vehicle repair and customization.
OEMs drive initial material specification, with Tier-1 Suppliers critical for high-volume production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global consumption mix for automotive carbon fiber composites varies significantly by region. While traditional automotive powerhouses prioritize high-performance applications, rapidly expanding electric vehicle markets emphasize lightweighting for battery range extension. This differentiation shapes regional material demand and manufacturing strategies.
Germany
German automakers drive demand for carbon fiber composites in premium vehicle performance and structural supports. The EU Green Deal's CO2 emission targets compel manufacturers to adopt lightweight materials. The Stuttgart region, home to major automakers, focuses on advanced composite component development and integration.
Japan
Japanese vehicle manufacturers seek carbon fiber composites for lightweighting to improve fuel efficiency and enhance chassis components. METI initiatives actively support the development and adoption of advanced materials in the automotive sector. Nagoya's automotive cluster drives innovation in composite manufacturing processes and material science.
United States
American automotive demand for carbon fiber composites stems from electric vehicle battery enclosures and high-performance vehicle segments. The US EPA's fuel economy standards incentivize mass reduction across vehicle platforms. Michigan's automotive corridor sees significant investment in composite production facilities and advanced material research.
China
China's robust new energy vehicle (NEV) market drives substantial demand for carbon fiber composites, primarily for extended battery range lightweighting. The Ministry of Industry and Information Technology (MIIT) promotes NEVs and dual carbon goals, boosting material adoption. The Yangtze River Delta region is a hub for EV manufacturing and composite integration into vehicle designs.
South Korea
South Korea's automotive industry increasingly utilizes carbon fiber composites for electric vehicle lightweighting and advanced structural applications. Government policies actively support the development of future mobility technologies and sustainable materials. Ulsan, a major automotive production base, integrates composites into next-generation vehicle designs and production lines.
Global Automotive Carbon Fiber Composites Market Key Industry Players
Capability concentration sits with specialized material science firms, often driving innovation in composite formulations. Conversely, scale advantage sits with large chemical and industrial conglomerates capable of high-volume precursor and fiber production. The market features a tiered structure, with raw fiber producers forming the foundational base and integrated module suppliers occupying the value-added apex. Strategic archetypes include precursor specialists, advanced composite formulators, and finished component manufacturers. Competitive moves primarily involve strategic partnerships to secure supply chains and expand product portfolios, alongside significant capacity expansion in automated manufacturing processes.
On the raw material and intermediate composite tier, Toray Industries Inc. exemplifies a vertically integrated leader, specializing in polyacrylonitrile (PAN)-based carbon fiber production. Hexcel Corporation occupies a position as a specialist in advanced composite materials, including prepregs, catering to high-performance automotive applications. Meanwhile, SGL Carbon SE represents a diversified player, offering a comprehensive portfolio that spans from fundamental fibers and materials to complete composite parts for vehicle structures. These firms anchor critical segments of the automotive carbon fiber composites supply chain, demonstrating varied approaches to market engagement.
| Leading Market Players |
|---|
| Teijin Limited |
| Solvay |
| Toray Industries Inc. |
| Owens Corning |
| BASF SE |
| Hexcel Corporation |
| Mitsubishi Chemical Corporation |
| Zoltek |
| SGL Carbon SE |
| Others |
Cost & Logistics Intelligence
Commodity volatility in polyacrylonitrile (PAN) precursor materials determines both pricing tier spreads for carbon fiber composites and the resilience of the upstream supply chain. This raw material cost directly influences the economic viability of new automotive applications.
Pricing Analysis
Long-term offtake agreements characterize the dominant pricing model for high-volume carbon fiber composite components supplied to major automotive OEMs. Price differentiation stems from material quality grade and the volume scale of procurement. Pricing pressure stems from OEM demands for cost-effective lightweighting solutions. Mass-market vehicle manufacturers exhibit high price sensitivity, contrasting with premium segment OEMs who prioritize performance.
Supply Chain Analysis
Tier-1 suppliers like Hexcel Corporation and SGL Carbon SE concentrate manufacturing capacity for advanced composite parts, often operating production facilities in Germany and Japan. The supply chain draws heavily from polyacrylonitrile (PAN)-based carbon fiber precursor material. Single-source vulnerability for specific high-performance precursor grades presents a structural risk. Distribution runs through these Tier-1 suppliers delivering finished components and assembly modules to global automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant fragmentation opportunity, driven by the specialized demand for lightweight battery enclosures in the rapidly expanding electric vehicle segment. Niche applications for advanced structural composites are also emerging.
For Market Incumbents: Build a process efficiency moat by investing heavily in automated manufacturing technologies such as high-pressure resin transfer molding. Secure long-term precursor material supply agreements to mitigate commodity volatility and ensure consistent production. This strategy helps counter the threat of substitution from advanced high-strength steel and aluminum alloys. Expanding capacity in key automotive manufacturing centers like Germany will reinforce market position.
For New Entrants and Emerging Players: The commercial vehicle segment, particularly electric buses and long-haul trucks, represents a significant underpenetration opportunity for lightweight carbon fiber composites. Focus on developing thermoplastic composite solutions offering faster production cycles and improved recyclability. Target integrated component systems like floor assemblies for these applications. This approach provides a clear go-to-market angle by addressing specific payload and fuel efficiency demands.
For Investors and Strategic Acquirers: The market sits at a sustained growth phase that favors integrated module suppliers with proprietary manufacturing processes. Long-term viability remains strong over the next five to ten years, driven by electric vehicle lightweighting mandates. Identify mid-sized Tier-1 suppliers specializing in high-volume composite manufacturing or advanced thermoplastic composite technology. The adoption rate of thermoplastic composites in mainstream electric vehicle platforms is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Automated Manufacturing | Scales production to meet OEM volume requirements for structural components. |
| Thermoplastic Composite R&D Investment | Develops materials for faster cycle times and enhanced end-of-life recyclability. |
| Supply Chain Partnership for Precursors | Secures critical raw material inputs, reducing vulnerability to commodity price fluctuations. |
| Integrated Module Development | Offers OEMs complete functional sub-assemblies, accelerating vehicle production workflows. |
| Commercial Vehicle Segment Entry | Captures new demand from electric bus and truck manufacturers for payload optimization. |
Research Approach
Desk research of industry reports, regulatory filings, and company disclosures preceded structured interviews with Tier-1 supplier procurement leads, OEM platform engineers, and composite material scientists. This primary engagement was validated against secondary sources including US EPA fuel economy standards, EU Green Deal documents, and MIIT reports. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Assumptions regarding regulatory mandates for lightweighting and electric vehicle adoption rates were held fixed; material cost trajectories were varied. The analytical framework modeled segmentation dimensions including product type, application, manufacturing stage, and regional production cluster. Compound annual growth rates were derived from historical growth patterns. Vehicle production volumes and carbon fiber content per vehicle served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated material producers would shift outcomes. Rapid shifts in raw material pricing or unforeseen regulatory changes are key risk factors. Quarterly review of carbon fiber precursor prices is advised.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailer Spindles Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Navigation Light Market
Vehicle Components
HCV Axles Market
Vehicle Components
Chassis Sensors Market