
 Wheat Starch Market | 2026-2036
Wheat Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Starch Market Intelligence
REACH compliance is repositioning the cost-of-entry calculus for European wheat starch processors, forcing capital upgrades in wastewater treatment and allergen control systems. AGRANA Beteiligungs-AG leverages its vertical integration across Austrian grain origination and Central European milling assets. Manildra Group USA anchors North American supply through its Kansas-based wheat processing network. Roquette Frères differentiates via specialty modified starch capabilities for pharmaceutical-grade applications.
Wheat starch is the carbohydrate fraction extracted from wheat endosperm through wet milling, typically comprising 25-30% amylose and 70-75% amylopectin with protein residues below 0.4% for food-grade material. Its primary commercial purpose centers on providing viscosity, gel strength, and moisture retention across processed foods, pharmaceutical binders, and paper coatings. Modified starch commands the deepest margin pools where functional customization justifies premium positioning over native starch commoditization. The food and beverage end-use channel remains the volume anchor, while bioplastics represents the fastest-expanding demand frontier as brand owners seek drop-in replacements for petrochemical feedstocks.
EMA pharmaceutical excipient guidelines, EFSA food additive specifications, and EU Green Deal carbon border adjustments collectively shape product standards and market access trajectories for wheat starch suppliers. EFSA purity benchmarks determine which processors qualify for infant nutrition and clinical nutrition contracts, while the EU Green Deal's embodied carbon tracking favors domestic European milling over imported alternatives. Stakeholders must monitor how evolving bioplastics certification schemes under EU packaging regulations redirect investment between modified starch R&D and native starch capacity expansion.
Market Dynamics
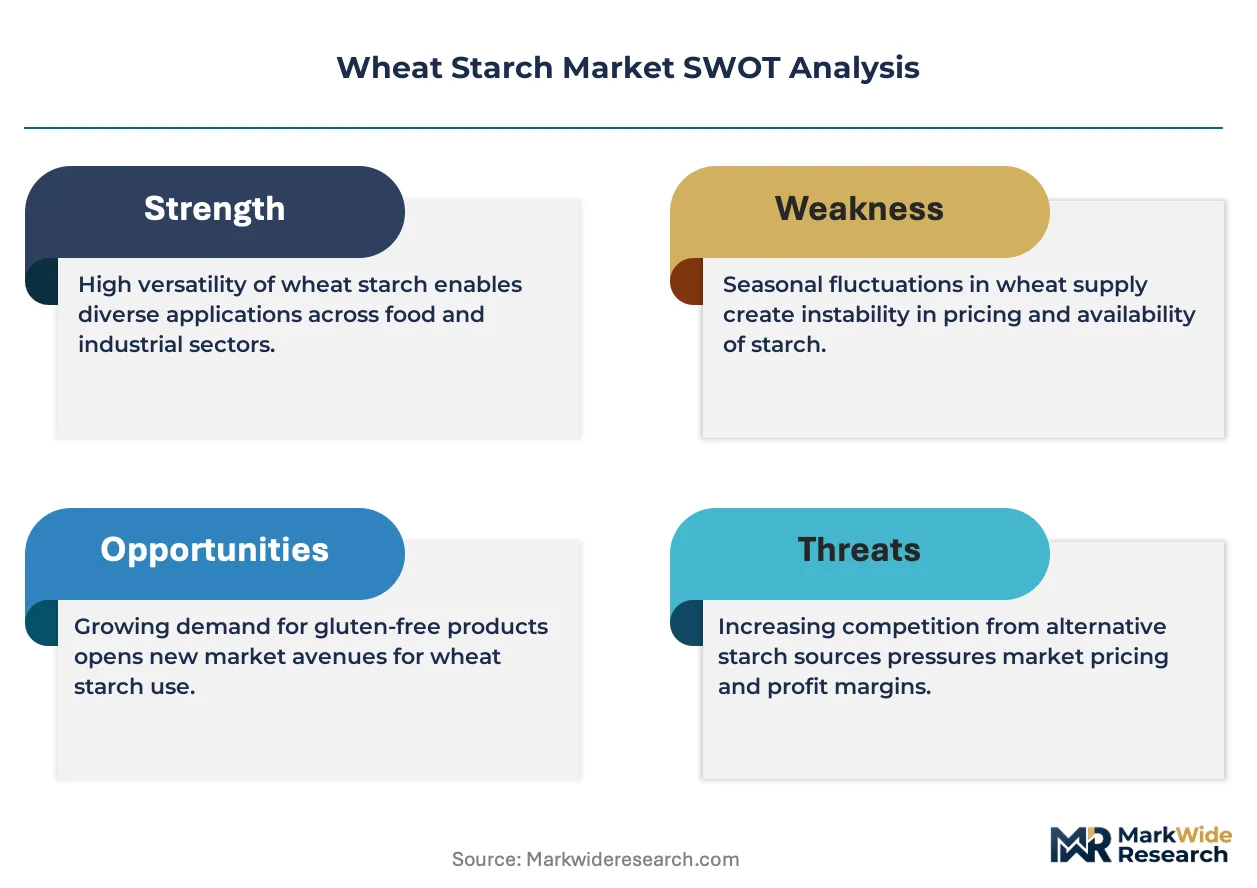
REACH compliance is forcing capital-intensive wastewater and allergen-control upgrades across European wheat starch processing, compressing margin structures for smaller mills while favoring scaled operators with integrated grain origination networks.
Growth Catalysts
- EU Green Deal carbon accounting:Embodied carbon tracking requirements favor domestic European milling over imported alternatives, redirecting procurement contracts toward EU-based processors.
- Clean-label formulation mandates:Food and beverage manufacturers are expanding wheat starch procurement as a recognizable, plant-based ingredient replacement for synthetic thickeners and modified food starches.
- Bioplastics feedstock demand:Brand owners seeking drop-in petrochemical replacements are pulling modified wheat starch into packaging applications, creating new volume anchors beyond traditional food channels.
Market Restraints
- Wheat price volatility:Input cost swings tied to Black Sea grain flows and weather patterns compress processor margins during contract renewal cycles.
- Supply concentration in Central Europe:Milling capacity clusters in Germany, France, and Italy create geographic vulnerability to regional logistics disruptions and energy price spikes.
- Technical substitution by corn and tapioca starches:Alternative carbohydrate sources offer comparable functionality at lower price points in non-premium applications, capping wheat starch pricing power.
Strategic Opportunities
- Pharmaceutical-grade excipient certification:EMA guidelines for tablet binders and disintegrants create a high-margin niche for processors achieving GMP compliance and dedicated allergen-free production lines.
- EU packaging regulation bioplastics mandates:Evolving certification schemes under the Packaging and Packaging Waste Regulation redirect investment toward modified starch R&D for compostable films.
- Clinical nutrition contract manufacturing:EFSA purity benchmarks for infant formula and medical foods open specialized procurement channels for processors with HACCP and FSSC 22000 credentials.
Industry Challenges
- Skilled technician scarcity in wet milling operations:Specialized knowledge in starch-protein separation and gluten recovery is concentrating among aging workforces in traditional milling regions.
- Legacy equipment retrofit costs:Decades-old processing infrastructure requires multimillion-euro upgrades to meet REACH effluent standards and EFSA traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Starch Market |
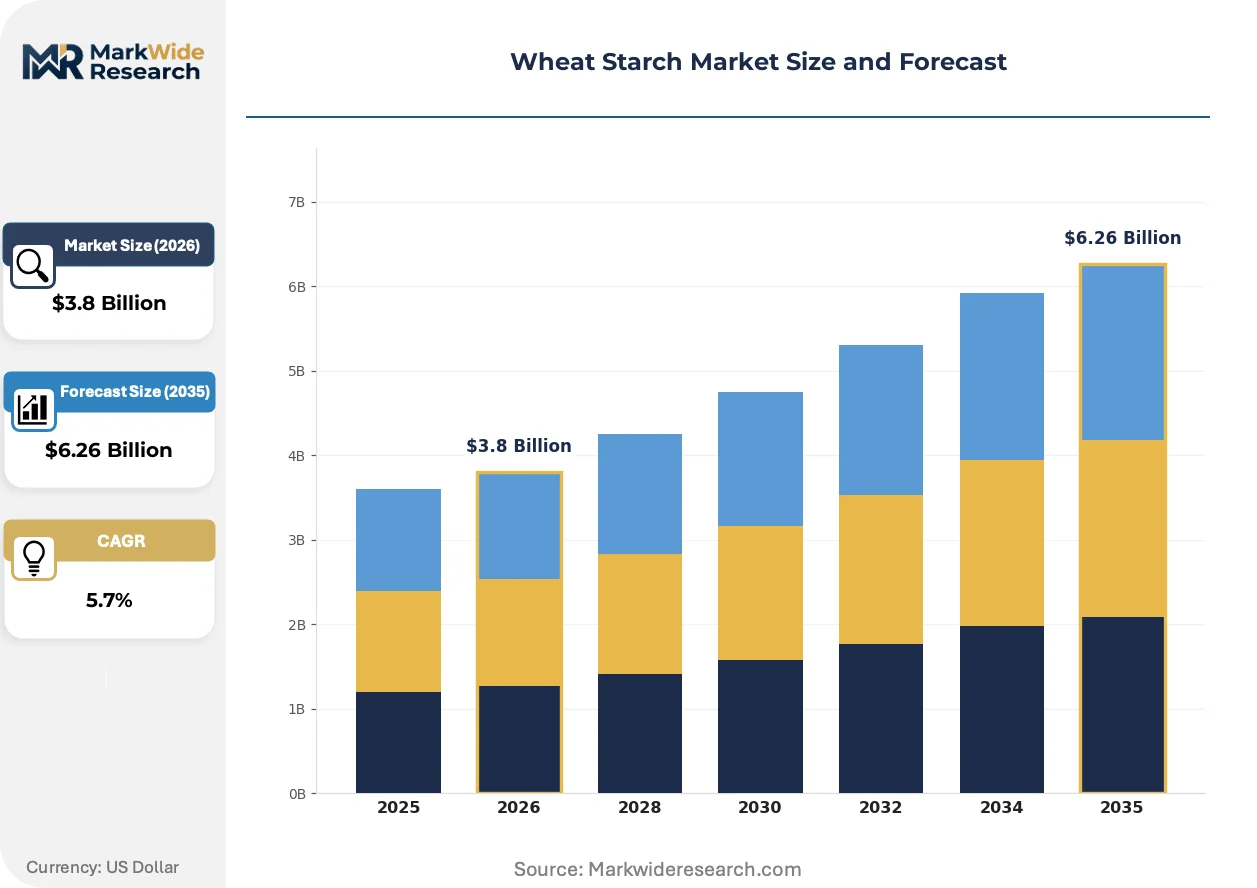
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Liquid Starch, Pregelatinized Starch End Use Industry: Food & Beverage, Pharmaceuticals, Paper & Packaging, Bioplastics Application: Thickening Agent, Stabilizer, Filler, Adhesive Form: Powder, Granules, Paste, Gel |
| Companies Covered | AGRANA Beteiligungs-AG, Manildra Group USA, Archer Daniels Midland Company, MGP Ingredients, Inc., Roquette Frères, Ingredion Incorporated, Cargill, Incorporated, Grain Processing Corporation, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Starch Market Strategic Shifts & Innovations
Novel enzyme-assisted extraction methods are reshaping processing economics by reducing water consumption and improving protein separation yields. These innovations compress energy intensity while expanding output quality tiers.
Modified wheat starch with tailored amylose-amylopectin ratios is expanding into pharmaceutical tablet coatings and controlled-release formulations. Contract manufacturers serving generic drug producers are adopting these specialty grades at accelerating rates. The technology is expanding into high-margin excipient markets previously dominated by corn-derived alternatives.
EFSA's evolving food additive specifications are tightening purity thresholds for heavy metals and pesticide residues in wheat starch destined for infant nutrition. Processors with integrated grain sourcing and in-house testing laboratories are capturing contract volume from traders lacking vertical traceability. German and French milling clusters are responding fastest due to proximity to accredited analytical service providers.
Direct procurement relationships between food manufacturers and starch processors are displacing traditional merchant trading structures. Large bakery and convenience food groups in Italy and Spain are negotiating multi-year supply agreements with named mill specifications. This pattern is most visible in Southern Europe, where processor consolidation has reduced the number of qualified suppliers below critical mass for competitive tendering.
Wheat Starch Market Segmentation
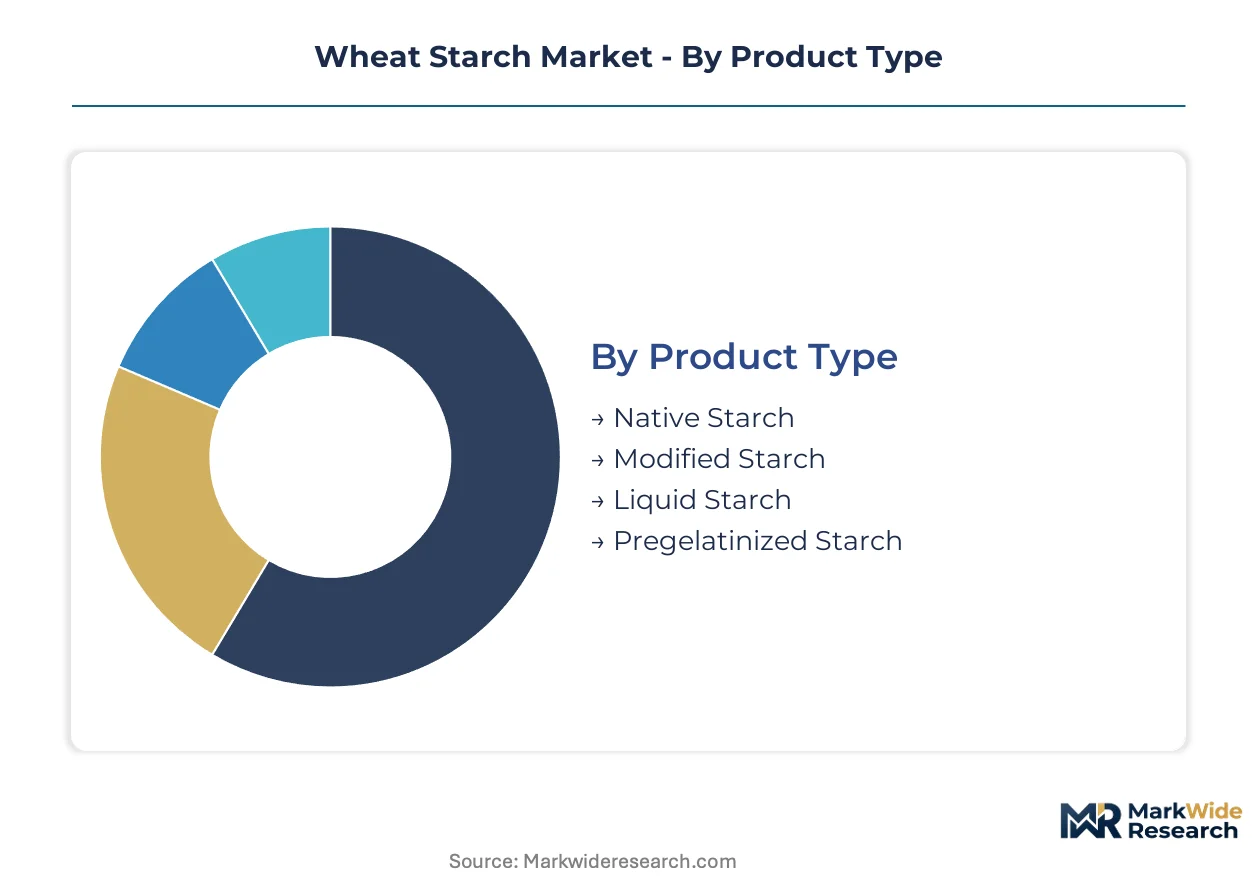
Wheat starch processors face divergent upgrade paths across product grades and end-use channels. Functional specifications from EFSA, EMA, and EU packaging regulations create tiered compliance thresholds that reshape capital allocation priorities.
Product Type:
Equipment replacement cycles concentrate investment where margin premiums justify dedicated processing lines and allergen-control infrastructure.
- Modified Starch:Chemically or physically altered amylose-amylopectin structures deliver tailored viscosity, freeze-thaw stability, and film-forming properties. Pharmaceutical tablet coatings and EU-mandated compostable packaging films in Germany and France pull capacity expansion toward specialty modification capabilities. EMA excipient guidelines and evolving bioplastics certification schemes compress qualification timelines for processors lacking dedicated GMP lines.
- Native Starch:Unmodified carbohydrate fraction extracted through conventional wet milling, retaining natural 25-30% amylose content. Clean-label bakery and convenience food manufacturers in Italy and Spain source native grades for recognizable ingredient declarations. REACH wastewater standards and carbon border adjustments under the EU Green Deal favor domestic European milling with integrated grain origination over imported alternatives.
- Liquid Starch:Aqueous suspension format eliminates drying energy costs and enables direct pipeline delivery to large-scale food processors.
- Pregelatinized Starch:Cold-water soluble variant produced via thermal treatment, serving instant food applications and ready-to-eat bakery mixes.
Native Starch sits at the top of the volume ranking, with Modified Starch climbing the fastest.
End Use Industry:
Customer procurement scale and certification burden determine facility configuration and margin capture potential.
- Food & Beverage:Volume anchor spanning bakery, confectionery, dairy, and processed meat applications where wheat starch provides moisture retention, texture modulation, and shelf-life extension. Direct procurement agreements between Italian and Spanish food manufacturers and named mill specifications are displacing traditional merchant trading structures. EFSA purity benchmarks for heavy metals and pesticide residues concentrate contract volume with processors maintaining in-house testing laboratories.
- Pharmaceuticals:High-margin excipient channel for tablet binders, disintegrants, and controlled-release coatings. EMA guidelines and dedicated allergen-free production lines create qualification barriers that reward scaled operators with GMP compliance and vertical grain sourcing. Modified wheat starch with tailored amylose-amylopectin ratios is gaining share in generic drug manufacturing previously served by corn-derived alternatives.
- Paper & Packaging:Surface sizing and coating applications where starch provides printability and structural integrity.
- Bioplastics:Fastest-expanding demand frontier as brand owners seek drop-in replacements for petrochemical feedstocks in compostable films and molded packaging.
Food & Beverage commands the deepest volume base, while Bioplastics shows the steepest expansion trajectory.
Application:
Functional performance requirements dictate raw material grade selection and processing intensity.
- Thickening Agent:Viscosity-building function in soups, sauces, and gravies where gelatinization temperature and shear stability determine suitability. Food manufacturers in Germany and France specify native or lightly modified grades for clean-label positioning. Enzyme-assisted extraction methods are improving protein separation yields and expanding output quality tiers for this high-volume application.
- Stabilizer:Freeze-thaw resistance and emulsion maintenance in dairy and frozen desserts. Modified starch with cross-linked or substituted molecular structures commands premium positioning over native alternatives in temperature-stressed applications.
- Filler:Bulking and moisture management in processed meats and baked goods.
- Adhesive:Bonding function in corrugated board and paper laminating operations.
Thickening Agent holds the largest application share, with Stabilizer gaining share fastest in premium formulation channels.
Form:
Physical state determines logistics economics, shelf stability, and end-use handling requirements.
- Powder:Dried, free-flowing format dominating long-distance distribution and extended storage applications. Central European milling clusters in Germany, France, and Italy anchor powder production capacity. Legacy equipment retrofit costs for REACH effluent compliance are compressing margin structures for smaller mills while favoring scaled operators.
- Paste:Pre-hydrated format eliminating cooking steps for industrial food processors and adhesive compounders. Direct pipeline delivery contracts with large bakery groups in Southern Europe concentrate demand around processor locations with integrated liquid starch capabilities.
- Granules:Intermediate moisture format for controlled hydration applications.
- Gel:Fully hydrated, high-viscosity state for specialized pharmaceutical and food texturizing uses.
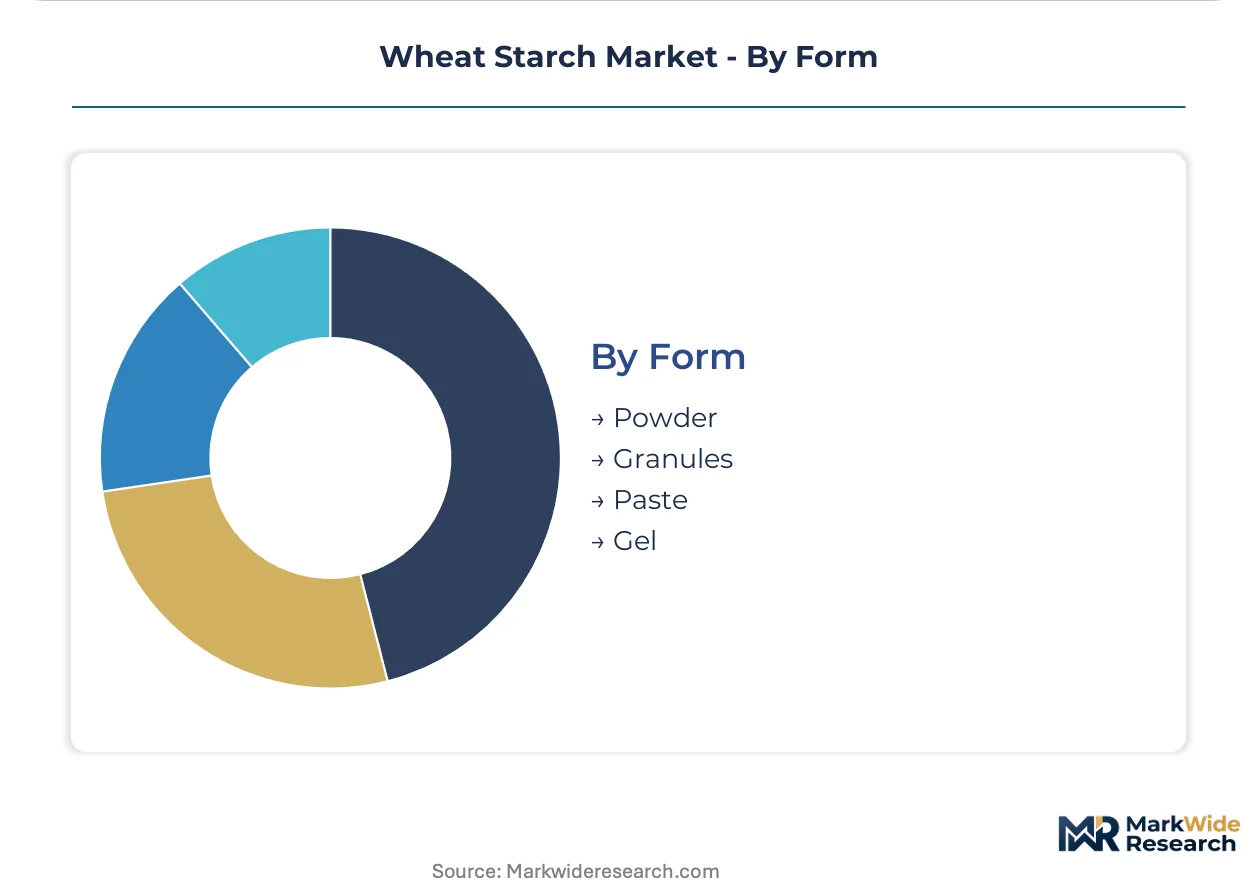
Powder dominates shipment volumes, with Paste expanding most quickly in just-in-time manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technicians in wet milling operations concentrate in Central European milling corridors, creating geographic dependency for starch-protein separation expertise. Their specialized knowledge in gluten recovery and effluent management anchors processing quality standards. This talent distribution shapes where capacity investments flow.
Germany
Clean-label bakery manufacturers in Bavaria and North Rhine-Westphalia drive native starch procurement for recognizable ingredient declarations. REACH compliance mandates wastewater treatment upgrades that compress margins for smaller mills while rewarding scaled operators. The milling cluster around Hamburg anchors powder production capacity with integrated grain origination networks.
France
Pharmaceutical excipient demand from generic drug manufacturers pulls modified wheat starch into tablet coating applications. EMA guidelines for GMP compliance create qualification barriers that concentrate contract volume with dedicated allergen-free producers. The Hauts-de-France region hosts processing facilities serving Northern European pharmaceutical corridors.
Italy
Convenience food groups negotiate direct procurement agreements with named mill specifications, displacing traditional merchant trading structures. EFSA purity benchmarks for heavy metals concentrate contract volume with processors maintaining in-house testing laboratories. Emilia-Romagna and Lombardy anchor Southern European milling capacity with legacy infrastructure requiring multimillion-euro retrofit investments.
United States
Bioplastics feedstock demand from brand owners seeking petrochemical replacements creates new volume anchors beyond traditional food channels. EPA effluent standards and state-level carbon disclosure requirements shape facility upgrade priorities. Kansas-based processing networks anchor North American supply with captive grain origination extending into the Corn Belt.
China
Modified starch capacity expansion serves domestic pharmaceutical and packaging industries with tailored amylose-amylopectin ratios. SAMR food additive specifications and dual carbon goals redirect investment toward energy-efficient extraction technologies. Shandong Province milling clusters leverage proximity to wheat production belts and coastal export infrastructure.
Wheat Starch Market Key Industry Players
The competitive structure tilts toward vertically integrated grain processors with captive origination networks and dedicated pharmaceutical-grade production lines. Scale advantages concentrate among operators with backward integration into wheat milling and forward integration into specialty modification capabilities. Two strategic archetypes dominate: diversified agricultural conglomerates with multi-starch portfolios, and regional specialists with deep single-ingredient expertise. Competitive moves center on capacity expansion for bioplastics feedstock grades and strategic partnerships with food manufacturers for direct procurement relationships.
Within the European specialist tier, AGRANA Beteiligungs-AG and Roquette Frères exemplify contrasting approaches to value capture. AGRANA represents backward integration archetypes with Austrian grain origination feeding Central European milling assets. Roquette occupies a position emphasizing pharmaceutical-grade modification capabilities over commodity volume. Manildra Group USA anchors the North American landscape as a geography-focused operator with Kansas-based processing networks. These three illustrate how competitive positioning diverges across integration depth, geographic focus, and end-use specialization rather than converging on a single optimal model.
| Leading Market Players |
|---|
| AGRANA Beteiligungs-AG |
| Manildra Group USA |
| Archer Daniels Midland Company |
| MGP Ingredients, Inc. |
| Roquette Frères |
| Ingredion Incorporated |
| Cargill, Incorporated |
| Grain Processing Corporation |
| Tate & Lyle PLC |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between pharmaceutical excipient and food-grade native starch manifests in divergent pricing power and supply chain configurations. EMA GMP compliance commands 40-60% premiums over standard food-grade material, while REACH wastewater investments concentrate procurement relationships with scaled German and French processors capable of absorbing fixed compliance costs.
Pricing Analysis
Contract-based long-term offtake dominates pharmaceutical channels, while spot-market flexibility persists in food-grade native starch. Price differentiation rests on EMA certification tier and dedicated allergen-free production line availability, with carbon border adjustments under the EU Green Deal adding geographic delivery cost spreads. Cost compression in standard food-grade material is intensifying because tapioca and corn starch substitution caps wheat starch pricing power. Large Italian bakery groups exhibit highest price sensitivity through direct procurement negotiations, while generic drug manufacturers show lowest sensitivity due to excipient qualification switching costs.
Supply Chain Analysis
Direct-to-food-manufacturer channels handle volume anchor demand from Italian and Spanish convenience food groups, displacing traditional merchant trading structures. Geographic supply concentrates in Germany, France, and Italy within the European processing corridor, with Kansas-based networks anchoring North American supply. Raw material dependencies draw from Black Sea wheat flows, energy-intensive wet milling operations, and specialized enzyme inputs for extraction optimization. Single-source vulnerability runs through Central European milling clusters exposed to regional energy price spikes and logistics disruptions. Distribution runs through named mill specifications with integrated grain origination and in-house testing laboratories capturing EFSA-compliant contract volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheat starch has entered a late-cycle quality phase where premium specification demand from pharmaceutical excipient and bioplastics feedstock channels reshapes value capture. EMA GMP compliance and EU packaging regulation bioplastics mandates concentrate procurement with processors achieving dedicated allergen-free production lines and modified starch R&D capabilities.
For Market Incumbents: Lock in pharmaceutical-grade contract manufacturing relationships before EMA qualification timelines compress further. Expand backward integration into Austrian or Central European grain origination networks to secure carbon-adjusted supply advantages under EU Green Deal embodied carbon tracking. Counter corn and tapioca starch substitution threats in food-grade channels through clean-label native starch positioning with Italian and Spanish bakery groups. For New Entrants and Emerging Players: Launch via clinical nutrition contract manufacturing serving infant formula and medical food processors seeking EFSA purity benchmark compliance. Target bioplastics feedstock grades for EU-mandated compostable packaging films as the fastest-penetrable application frontier. Pursue strategic partnerships with generic drug manufacturers for excipient qualification programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance capital requirements exceed smaller mill balance sheet capacity, creating acquisition opportunities for scaled operators with integrated grain sourcing. Long-term viability favors processors with dual food-pharma certification and bioplastics modification capabilities over commodity native starch pure-plays. Signal to watch: EFSA heavy metal and pesticide residue threshold tightening redirecting contract volume toward vertically integrated processors with captive grain testing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Excipient Certification | EMA GMP compliance opens high-margin tablet binder contracts with generic drug manufacturers. |
| Backward Integration into Grain Origination | Austrian and Central European captive wheat sourcing secures carbon-adjusted supply advantages. |
| Bioplastics Feedstock R&D Expansion | EU Packaging and Packaging Waste Regulation mandates pull modified starch into compostable films. |
| Direct Procurement Relationship Development | Named mill specifications with Italian and Spanish food groups displace merchant trading structures. |
| REACH Wastewater Infrastructure Upgrade | Effluent compliance investments concentrate market share with scaled operators over smaller mills. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wet milling plant managers, procurement leads at Italian and Spanish food manufacturers, pharmaceutical excipient sourcing directors, and bioplastics compounders with secondary validation. Secondary sources included EFSA food additive specifications, EMA excipient guidelines, EU Green Deal carbon border adjustment documentation, customs and trade flow data, and SEC filings from listed agricultural processors. Bottom-up capacity and demand modeling triangulated against top-down market sizing across native and modified starch product tiers.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product type, end-use industry, application function, and physical form. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated wheat price volatility patterns, REACH compliance capital expenditure cycles, and bioplastics certification scheme evolution under EU packaging regulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Black Sea supply disruption scenarios and accelerated corn starch substitution in non-premium applications. Periodic stress-testing of base assumptions is recommended, particularly regarding EFSA purity benchmark tightening timelines and EU Green Deal carbon accounting implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Ice Cream Ingredients Market
Ingredients
Homecare Ingredients Market
Ingredients
Baobab Ingredient Market
Ingredients
North America Dairy Ingredients Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
South America Spirulina Extract Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Biotech Ingredients Market
Ingredients
Global Tomato Powder Market
Ingredients
Bovine Gelatin Market
Ingredients
Glucomannan Market
Ingredients
Baking Ingredients Market
Ingredients
Safflower Oil Market
Ingredients
Edible Oils and Fats Market