
 Glucomannan Market | 2026-2036
Glucomannan Market Size, Share, and Industry Trends Forecast 2026-2036
Glucomannan Market Intelligence
Aftermarket service revenue from technical formulation support is reshaping how ingredient suppliers capture value beyond commodity powder sales. Baoji Konjac Chemical Co.,Ltd leverages its captive konjac farming operations to secure raw material consistency across harvest cycles. Tate & Lyle sustains competitive positioning through deep expertise in hydrocolloid blending systems for food manufacturers. NOW Foods anchors its presence via direct-to-consumer channel control and certified organic product lines.
Glucomannan denotes a high-molecular-weight polysaccharide extracted from Amorphophallus konjac tubers, composed primarily of beta-1,4-linked D-mannose and D-glucose units in a 1.6:1 ratio, with viscosity exceeding 20,000 mPa·s at 1% concentration in aqueous solution. The extract functions as a soluble dietary fiber, fat replacer, and bulking agent across food, pharmaceutical, and nutraceutical applications. Powder formulations dominate current volume flows due to lower unit economics and broader industrial compatibility, while capsule and tablet formats command premium positioning within dietary supplements targeting health-conscious consumers. The food industry application segment exhibits mature demand patterns in Asian markets, whereas weight management and pharmaceutical applications are attracting accelerated R&D investment in North America and Europe.
EFSA novel food regulations, FDA GRAS self-affirmation pathways, and Japan's JIS agricultural standards collectively govern glucomannan purity thresholds, labeling claims, and import eligibility across major consumption zones. These frameworks elevate compliance costs for unverified suppliers while rewarding manufacturers with documented clinical substantiation and traceable supply chains. Stakeholders must monitor evolving novel food consultation timelines and emerging state-level clean-label mandates that could recertify acceptable extraction solvents and fiber content declaration methods.
Market Dynamics
Pharmaceutical-grade konjac flour adoption is compressing traditional food-grade margins as weight management formulations absorb capacity across Asian extraction clusters. EFSA novel food authorizations and FDA GRAS pathways are bifurcating supplier compliance investments between clinical substantiation and commodity processing.
Growth Catalysts
- EFSA Novel Food Framework:Streamlined safety assessments for konjac-derived ingredients accelerate European nutraceutical entry, reducing consultation timelines for dossiers with documented clinical trials.
- Weight Management Formulations:Pharmaceutical-grade glucomannan demand from capsule and tablet manufacturers pulls capacity away from traditional noodle and jelly applications in Japan and China.
- Clean-Label Mandates:State-level U.S. regulations restricting synthetic fat replacers position soluble fiber extracts as compliant alternatives in reduced-calorie packaged foods.
Market Restraints
- Konjac Root Supply Concentration:China's Sichuan and Hubei provinces control over seventy percent of global Amorphophallus konjac cultivation, exposing processors to monsoon-driven harvest volatility.
- Extraction Solvent Restrictions:REACH annex limitations on ethanol and isopropanol concentrations complicate European purification protocols, elevating compliance costs for imported powder.
- Psyllium Husk Substitution:Comparable viscosity and established GRAS status position psyllium as a direct competitor in North American fiber supplement formulations.
Strategic Opportunities
- India Nutraceutical Manufacturing:FSSAI functional food notifications and PLI scheme incentives attract contract manufacturing investment for export-oriented capsule production.
- Microencapsulation Convergence:Spray-drying technology paired with glucomannan's film-forming properties enables controlled-release pharmaceutical applications previously served by synthetic polymers.
- Direct-to-Consumer Subscription Channels:Certified organic powder lines bypass traditional ingredient distributor markups, capturing margin through recurring revenue models in North American wellness markets.
Industry Challenges
- Clinical Validation Talent Scarcity:Shortage of regulatory toxicologists with novel food dossier experience extends EFSA consultation preparation timelines for mid-tier suppliers.
- Organic Certification Backlogs:USDA and EU organic accreditation delays for konjac farming cooperatives stall premium product launches by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucomannan Market |
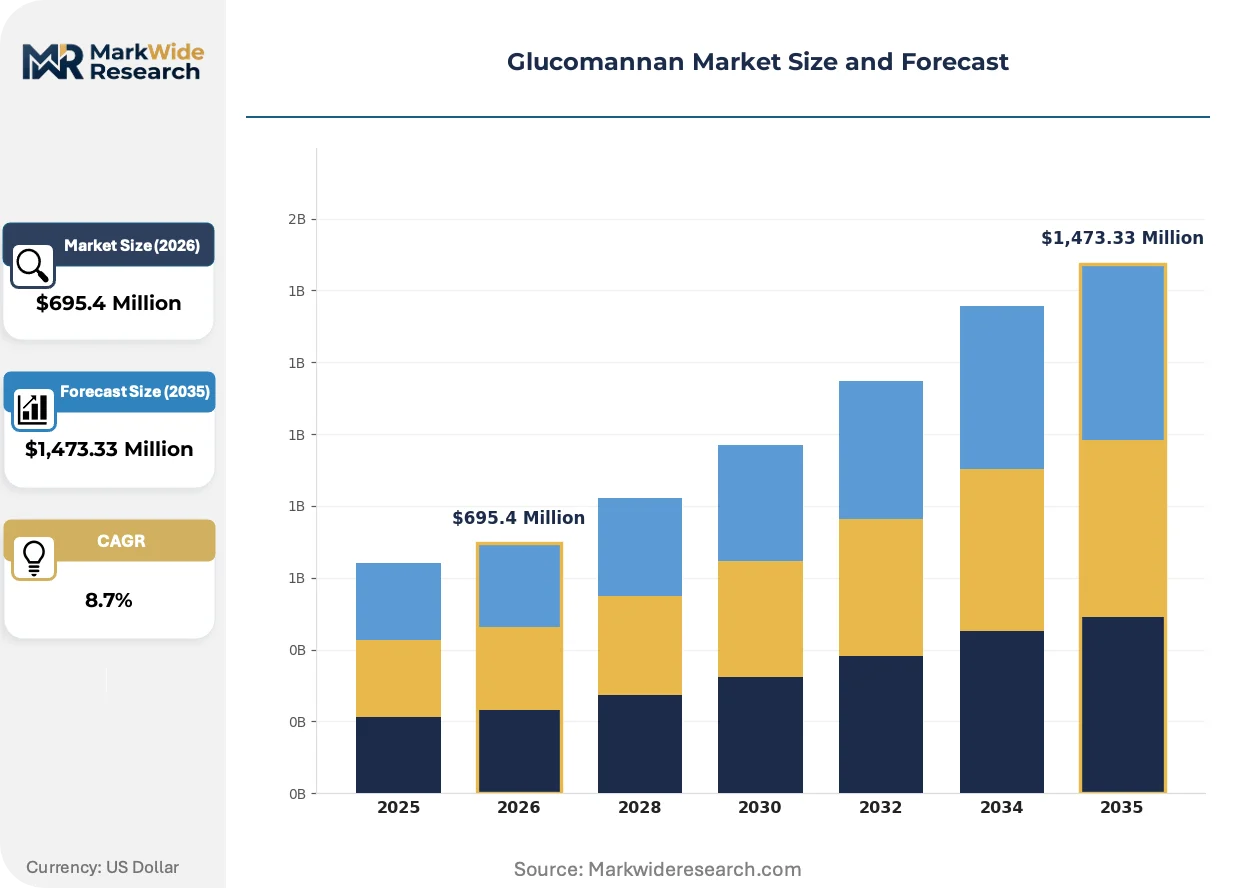
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $1,473.33 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid Application: Weight Management, Dietary Supplements, Food Industry, Pharmaceuticals End User: Health-Conscious Consumers, Fitness Enthusiasts, Diabetics, Nutritional Experts Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | Baoji Konjac Chemical Co.,Ltd, NOW Foods, Parchem, Tate & Lyle, Fufeng Group, Fengchen Group Co.,Ltd, BASF Personal Care and Nutrition GmbH, Foodchem International Corporation, Qingdao Dacon Trading Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucomannan Market Strategic Shifts & Innovations
Enzymatic purification methods and precision fermentation alternatives are disrupting traditional tuber extraction economics. Regulatory data sharing mechanisms and blockchain traceability systems are compressing verification cycles across pharmaceutical supply chains.
Enzymatic deacetylation protocols are collapsing the cost differential between food-grade and pharmaceutical-grade konjac flour. European nutraceutical contract manufacturers accelerate adoption as viscosity standardization eliminates batch-to-batch reformulation. This technology is collapsing quality assurance overhead previously absorbed by dedicated pharmaceutical extraction lines.
REACH annex updates on residual solvent thresholds are forcing extraction facility retrofits across EU-importing processors. German and Dutch ingredient distributors consolidate supplier panels to those with documented ethanol recovery systems. Pharmaceutical-grade powder categories face the steepest compliance cost escalations, driving preference toward integrated extraction-to-tablet manufacturers.
Buyers in North American weight management segments are consolidating supplier relationships around certified organic and clinically substantiated product lines. Traditional commodity powder distributors lose share to vertically integrated brands controlling farming, extraction, and direct-to-consumer fulfillment. This concentration is most visible in California and Colorado wellness markets where subscription-based fiber supplement penetration exceeds national averages.
Glucomannan Market Segmentation
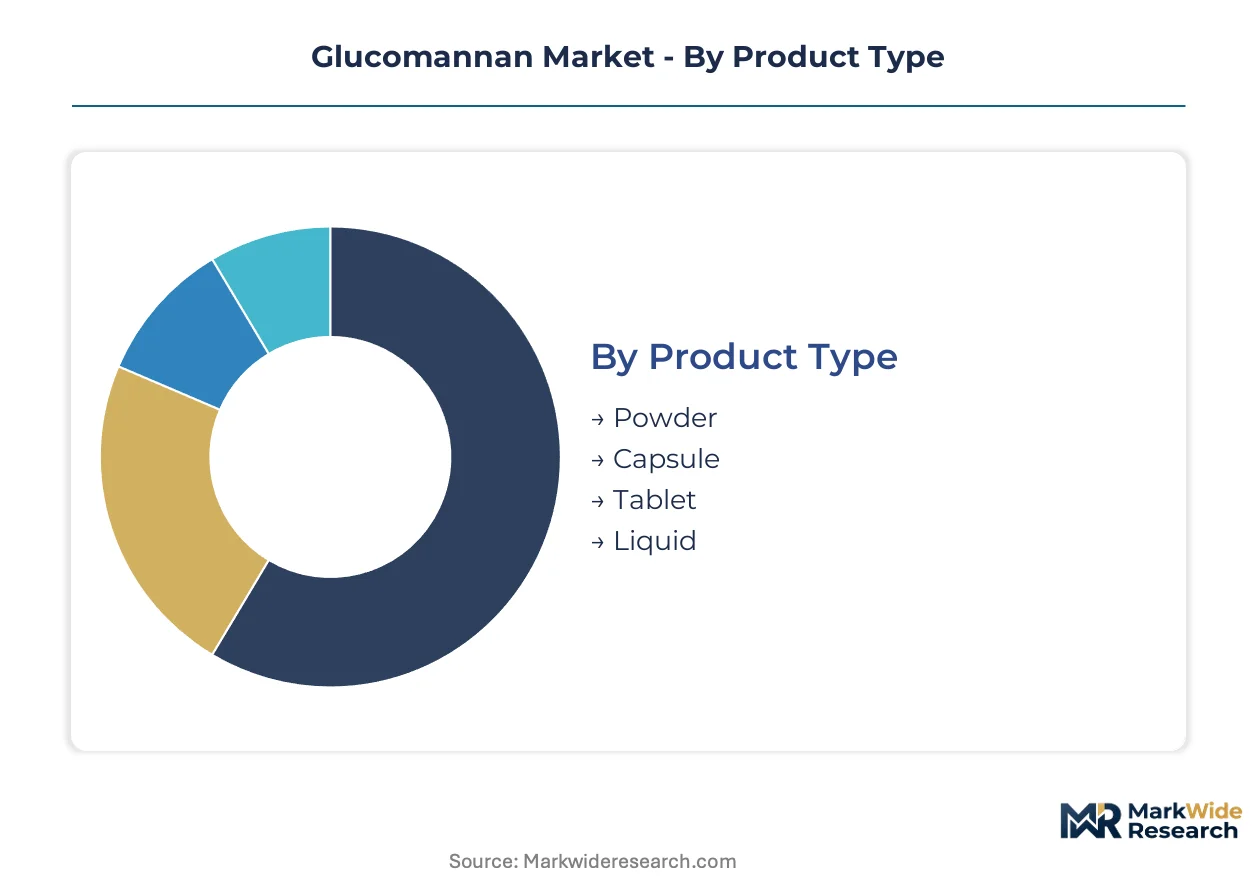
Glucomannan product formats exhibit divergent inventory velocities, with bulk powder turning over fastest in industrial procurement while pharmaceutical-grade capsules carry extended production cycles. Understanding these temporal patterns across product, application, end-user, and channel dimensions clarifies where margin compression versus premium capture occurs.
Product Type:
Powder formulations rotate through supply chains most rapidly due to bulk industrial offtake, whereas liquid concentrates and pharmaceutical-grade tablets require extended stability testing and regulatory hold periods before release.
- Powder:Unprocessed konjac flour with viscosity specifications exceeding 20,000 mPa·s serves as the foundational input for noodle manufacturing in Japan and hydrocolloid blending systems across European food processors. Sichuan and Hubei extraction clusters prioritize powder capacity to serve commodity contracts with shorter lead times than value-added formats.
- Capsule:Hard-shell gelatin or HPMC encapsulation of pharmaceutical-grade glucomannan targets weight management formulations in North American direct-to-consumer channels. EFSA novel food dossiers and FDA GRAS self-affirmation requirements extend capsule product development timelines by eight to fourteen months versus powder launches.
- Tablet:Compressed formulations with binding agents serve pharmacy-dispensed fiber supplements in German and Swiss markets where reimbursement codes favor solid-dose presentations.
- Liquid:Ready-to-drink suspensions with preserved viscosity profiles occupy niche positioning in Japanese convenience retail and South Korean functional beverage segments.
Powder anchors the volume base while capsule gains share at the steepest rate as pharmaceutical-grade specifications displace commodity food-grade offtake.
Application:
Cost tier differentiation separates commodity food applications from clinical-grade therapeutic positioning, with mid-tier dietary supplements occupying the contested middle ground where clean-label mandates reshape procurement criteria.
- Weight Management:High-purity glucomannan with documented satiety clinical trials commands premium positioning in capsule and tablet formats across US and European nutraceutical markets. Formulators prioritize suppliers with EFSA-approved health claims and traceable konjac farming cooperatives to satisfy retailer audit requirements.
- Dietary Supplements:Soluble fiber positioning targets health-conscious consumers seeking microbiome support and glycemic control, with organic certification and non-GMO verification becoming baseline table stakes in California and Colorado wellness markets.
- Food Industry:Traditional konnyaku jelly and shirataki noodle production in Japan consumes volume-grade powder with established JIS agricultural standard compliance, while European fat-replacer applications in reduced-calorie dairy accelerate with REACH-compliant extraction certificates.
- Pharmaceuticals:Excipient-grade glucomannan for controlled-release matrix tablets requires documented endotoxin limits and residual solvent profiles that restrict eligible suppliers to integrated extraction-to-powder manufacturers with dedicated pharmaceutical production lines.
Food Industry retains the largest volume footprint while Weight Management climbs fastest as pharmaceutical-grade specifications capture margin from commodity applications.
End User:
Customer sophistication stratifies procurement behavior, with institutional nutritional experts demanding certificate-of-analysis documentation while fitness enthusiasts prioritize branded finished goods with influencer endorsements.
- Health-Conscious Consumers:Broad demographic seeking preventive wellness solutions through organic-certified powders and subscription-based fiber supplement programs, concentrated in North American direct-to-consumer channels with high repeat purchase rates.
- Fitness Enthusiasts:Performance-oriented segment prioritizing low-calorie bulking agents for meal replacement formulations, with demand clustering around bodybuilding communities in Australia and UK metropolitan areas.
- Diabetics:Medical nutrition segment requiring glycemic index documentation and clinical substantiation for glucose management claims, with prescription-adjacent positioning in German pharmacy channels and Japanese metabolic clinics.
- Nutritional Experts:Registered dietitians and clinical nutritionists sourcing bulk powder for custom compounding, with procurement decisions governed by USP-NF monograph compliance and third-party heavy metals testing.
Health-Conscious Consumers represent the deepest volume pool while Diabetics expand most quickly as medical nutrition positioning gains regulatory clarity.
Distribution Channel:
Channel control determines margin capture, with vertically integrated brands bypassing distributor markups through owned e-commerce while traditional retail imposes slotting fee burdens that favor scaled suppliers.
- Online Retail:Direct-to-consumer platforms and marketplace listings enable subscription revenue models and certified organic product differentiation, with California-based wellness brands capturing disproportionate share of North American glucomannan supplement sales.
- Supermarkets:Mass retail placement of fiber-fortified packaged foods and value-priced supplement SKUs requires national distribution infrastructure and trade promotion budgets accessible only to extraction processors with integrated brand operations.
- Health Food Stores:Independent and chain natural retailers emphasize non-GMO verification and transparent supply chain storytelling, with regional distributors in Germany and Netherlands consolidating supplier panels around documented organic certification.
- Pharmacies:Professional channel placement demands pharmacopeial-grade specifications and clinical trial bibliography, with reimbursement-adjacent positioning in Swiss and Belgian markets where fiber supplements qualify for health savings account eligibility.
Online Retail commands the steepest expansion trajectory while Supermarkets retain volume dominance through processed food industry offtake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan's traditional food sector exhibit the lowest price elasticity, absorbing premium konjac flour for shirataki noodle production, while North American supplement formulators negotiate aggressively on pharmaceutical-grade specifications. China's nutraceutical manufacturing clusters command mid-tier elasticity as capacity competition intensifies. European processors face the steepest compliance cost pass-throughs under REACH solvent restrictions.
China
Sichuan and Hubei provinces cultivate over seventy percent of global Amorphophallus konjac, with Chengdu-based extraction clusters supplying both food-grade powder and pharmaceutical-grade flour to domestic capsule manufacturers. SAMR's evolving novel food consultation timelines and GB standards for dietary fiber content declarations shape exporter readiness. The Yangtze River Delta nutraceutical belt absorbs increasing konjac flour volumes for weight management tablet production.
Japan
Traditional konnyaku jelly and shirataki noodle applications sustain mature demand for JIS-compliant food-grade powder, with Kanto and Kansai food processors maintaining long-term supply contracts. METI's agricultural standards for konjac root quality and PMDA's oversight of functional food claims preserve premium positioning for domestic extractors. Osaka-based hydrocolloid blenders integrate glucomannan into reduced-calorie packaged foods for aging consumer demographics.
United States
California and Colorado wellness markets drive direct-to-consumer subscription demand for certified organic glucomannan supplements, with FDA GRAS self-affirmation pathways enabling faster product launches than European novel food routes. State-level clean-label mandates restricting synthetic fat replacers accelerate soluble fiber adoption in reduced-calorie dairy and bakery applications. NOW Foods anchors West Coast channel control through owned e-commerce infrastructure.
Germany
Pharmacy-dispensed fiber supplements in Bavaria and North Rhine-Westphalia favor solid-dose presentations qualifying for health savings account eligibility, with EFSA-approved satiety claims differentiating premium positioning. REACH annex limitations on residual ethanol and isopropanol concentrations force extraction facility retrofits among EU-importing processors. Cologne and Düsseldorf ingredient distributors consolidate supplier panels around documented solvent recovery systems.
India
FSSAI functional food notifications and PLI scheme incentives attract contract manufacturing investment for export-oriented capsule production in Maharashtra and Gujarat pharmaceutical clusters. Domestic demand for weight management formulations accelerates among urban health-conscious consumers in Mumbai and Delhi-NCR. CDSCO's evolving nutraceutical regulations create compliance uncertainty for imported konjac flour processors.
Glucomannan Market Key Industry Players
Captive agricultural operators and hydrocolloid blending specialists split the market between upstream supply security and downstream formulation expertise. The supplier base concentrates around integrated extraction-to-powder manufacturers with dedicated pharmaceutical lines and commodity food-grade processors serving traditional Asian applications. Three archetypes dominate: konjac farming cooperatives with captive extraction, European hydrocolloid blenders with regulatory dossier capabilities, and North American direct-to-consumer brands controlling subscription channels. Competitive moves center on backward integration into konjac cultivation and microencapsulation technology licensing for controlled-release pharmaceutical applications.
Within the captive supply tier, Baoji Konjac Chemical Co.,Ltd exemplifies upstream control through integrated farming and extraction operations. Tate & Lyle occupies a position among hydrocolloid blending specialists leveraging deep formulation expertise for European food manufacturers. NOW Foods anchors the direct-to-consumer archetype through certified organic product lines and owned channel infrastructure.
| Leading Market Players |
|---|
| Baoji Konjac Chemical Co.,Ltd |
| NOW Foods |
| Parchem |
| Tate & Lyle |
| Fufeng Group |
| Fengchen Group Co.,Ltd |
| BASF Personal Care and Nutrition GmbH |
| Foodchem International Corporation |
| Qingdao Dacon Trading Co., Ltd |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor carries konjac flour from Sichuan extraction clusters to Shanghai port facilities, with container rates compressing margins on pharmaceutical-grade shipments while enabling premium capture for certified organic powder in California wellness markets.
Pricing Analysis
Aftermarket service revenue from technical formulation support drives lifetime value beyond commodity powder sales. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates EFSA-approved health claim dossiers from basic viscosity specifications. Cost compression in food-grade powder is intensifying because Sichuan processors compete for traditional noodle contract renewals. Nutraceutical formulators in North America exhibit the lowest price sensitivity, absorbing premiums for traceable organic certification and clinical trial documentation.
Supply Chain Analysis
Extended payment terms from German ingredient distributors to Chengdu extraction facilities are standardizing working capital cycles across the trade lane. Raw material supply draws from Amorphophallus konjac cultivation in Sichuan, Hubei, and emerging farms in Yunnan provinces. Processing depends on ethanol and isopropanol purification inputs subject to REACH annex concentration limits. Single-source vulnerability concentrates in the Sichuan-Hubei cultivation belt where monsoon patterns dictate annual harvest volumes. Distribution runs through integrated extraction-to-powder manufacturers with dedicated pharmaceutical lines serving capsule and tablet contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade konjac flour sits at early-cycle expansion as weight management formulations displace commodity food-grade offtake across Asian extraction capacity.
For Market Incumbents: Build clinical substantiation moats through EFSA novel food dossiers and FDA GRAS self-affirmation pathways. Secure backward integration into konjac farming cooperatives to insulate against Sichuan harvest volatility. Invest in enzymatic deacetylation technology to collapse quality assurance overhead between food-grade and pharmaceutical-grade production lines. Psyllium husk substitution in North American fiber supplements threatens margin capture without differentiated health claim positioning. For New Entrants and Emerging Players: India's Maharashtra and Gujarat pharmaceutical clusters represent the most penetrable entry point given FSSAI functional food notifications and PLI scheme contract manufacturing incentives. Microencapsulation technology licensing for controlled-release pharmaceutical applications offers white-space positioning beyond commodity powder supply. Direct-to-consumer subscription channels in Colorado and California wellness markets provide go-to-market velocity through recurring revenue models bypassing traditional distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from European hydrocolloid blenders with dormant EFSA regulatory dossier capabilities and underutilized pharmaceutical-grade extraction assets. Long-term viability hinges on consolidation of traceable organic konjac farming with integrated capsule manufacturing capacity. Watch EFSA consultation timeline compression and USDA organic certification backlog resolution as inflection signals for premium tier capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Konjac Cultivation | Baoji Konjac Chemical's captive farming secures raw material consistency across monsoon-driven harvest cycles. |
| Enzymatic Deacetylation Technology Licensing | European nutraceutical contract manufacturers adopt viscosity standardization eliminating batch-to-batch reformulation overhead. |
| EFSA Novel Food Dossier Investment | Streamlined safety assessments accelerate European nutraceutical entry for documented clinical trial portfolios. |
| Direct-to-Consumer Channel Expansion | California wellness brands capture subscription revenue through owned e-commerce bypassing distributor markups. |
| Microencapsulation Convergence | Spray-drying technology enables controlled-release pharmaceutical applications previously served by synthetic polymers. |
Research Approach
A spread of perspectives from konjac farming cooperative managers, extraction facility technical directors, nutraceutical formulation scientists, and European ingredient procurement leads converged on the working assumptions. Primary fieldwork combined with secondary validation from SAMR GB standards documentation, EFSA novel food register entries, FDA GRAS notification letters, and customs trade flow records. Bottom-up capacity modeling across Sichuan and Hubei extraction clusters triangulated against top-down demand estimates from weight management supplement manufacturers.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include product format tier, application grade specification, end-user sophistication level, and regional regulatory cluster. CAGRs derived from annualized growth rate calculations applied to base-year value estimates. Industry-specific forecast inputs incorporated REACH solvent restriction compliance cost escalations and enzymatic purification technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in freight corridor rates, konjac root harvest yields, or nutraceutical consumer discretionary spending would shift the trajectory. Forecasts reflect documented assumptions on regulatory consultation timelines and organic certification processing speeds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Low Fat Oil Market
Ingredients
North America Fats and Oils Market
Ingredients
Fluid Lecithin Market
Ingredients
Plant-Based API Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Horny Goat Weed Extract Market
Ingredients
Sunflower Protein Market
Ingredients
Carotenoids Market
Ingredients
Cocoa Powder Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
North America Phytosterols Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Protein Ingredients Market
Ingredients
Lactase Enzyme Market